
 South America Starch Derivatives Market | 2026-2036
South America Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Starch Derivatives Market Analytics
Buyer concentration among large food manufacturers across Brazil and Argentina is hardening as multinational processors consolidate procurement volumes toward fewer approved suppliers. Cargill Incorporated leverages its integrated corn processing footprint in the Mercosur region to secure consistent feedstock access for dextrose and maltodextrin output. Ingredion Incorporated anchors its position through specialty modified starch formulations tailored to regional beverage and dairy applications. Tate & Lyle PLC competes via technical service partnerships with mid-sized Brazilian confectionery producers seeking texture optimization.
Starch derivatives encompass chemically, physically, or enzymatically altered starch products including maltodextrins, cyclodextrins, and glucose syrups with dextrose equivalence values spanning 5 to 100, serving as thickeners, stabilizers, and bulking agents across industrial formulations. Modified starch commands the dominant value share due to its superior freeze-thaw stability and shear resistance in processed foods, though pregelatinized starch registers the fastest expansion as instant noodle and ready-meal manufacturers in Chile and Peru seek cold-water solubility without additional heat processing. Pharmaceutical-grade starches concentrate margin pools because excipient certification requirements under ANVISA and local pharmacopeia standards create qualification barriers that limit supplier competition.
ANVISA governs food additive approvals and maximum usage levels for starch derivatives in Brazilian processed foods, while Argentina's national food code administered by the country's food safety authority mandates labeling disclosures for modified starch content that shape formulation choices by export-oriented manufacturers. Brazil's Plano Nacional de Bioquímicos and related industrial biotechnology incentives indirectly support enzymatic processing investments that expand specialty derivative capacity. Stakeholders must monitor pending Mercosur harmonization proposals for food additive standards that could unify or fragment cross-border product registration requirements.
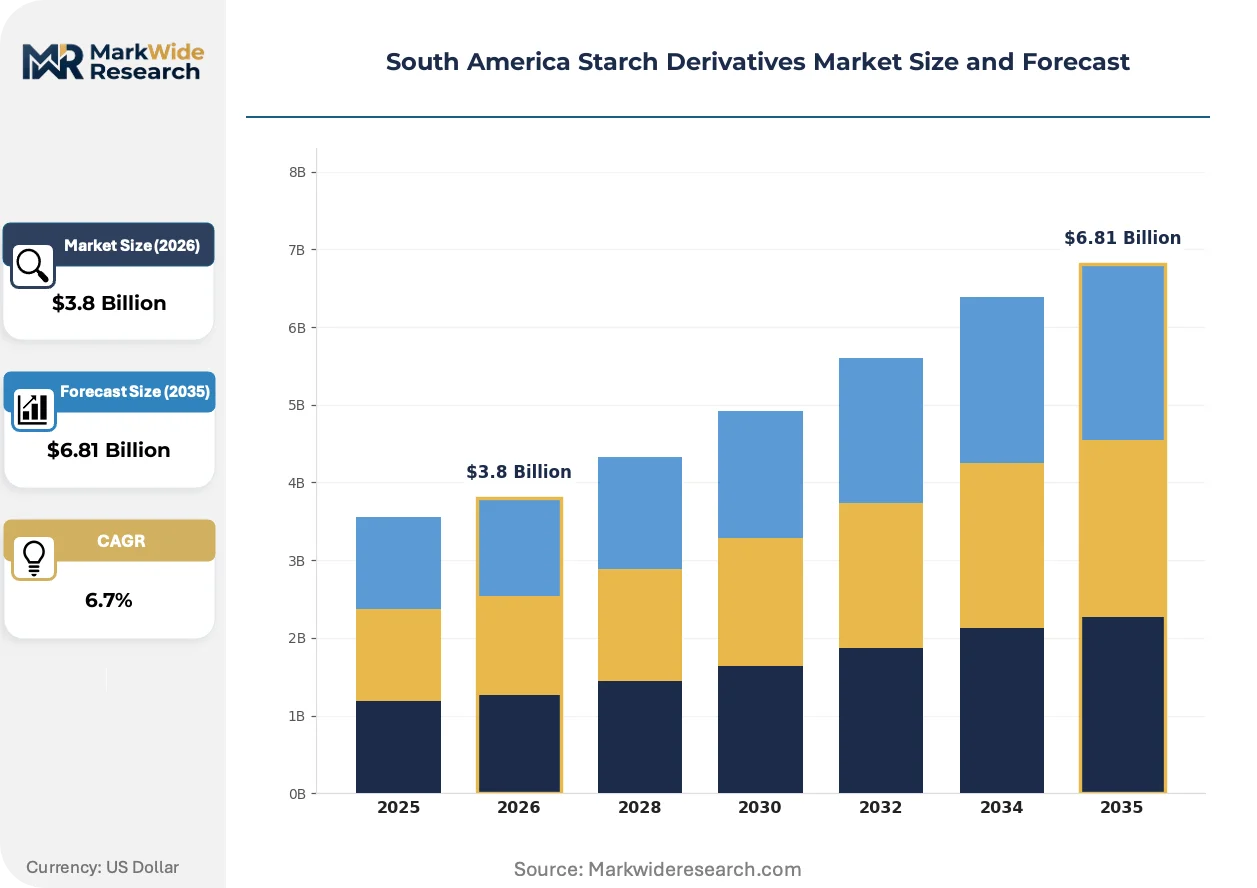
Market Dynamics
ANVISA's accelerated approval pathways for clean-label starch substitutes are compressing formulation cycles across Brazil's processed food sector, forcing ingredient suppliers to requalify product lines under tighter additive disclosure rules.
Growth Catalysts
- Clean-label substitution mandates:Brazil's updated ANVISA food additive regulations are accelerating displacement of synthetic thickeners with native and modified starches in beverage and dairy formulations.
- Pharmaceutical excipient certification:ANVISA's qualification barriers for pharmaceutical-grade starches are creating margin pools that attract specialty derivative investments from domestic processors.
- Industrial biotechnology incentives:Brazil's Plano Nacional de Bioquímicos supports enzymatic processing capacity expansion for maltodextrin and cyclodextrin output.
Market Restraints
- Corn feedstock price volatility:Mercosur region corn supply fluctuations directly compress margins for dextrose and glucose syrup manufacturers dependent on regional grain markets.
- Supplier concentration risk:Procurement consolidation among multinational food processors in São Paulo and Minas Gerais states narrows approved vendor lists for mid-sized starch derivative suppliers.
- Freeze-thaw stability limitations:Native starch performance gaps in frozen ready-meal applications sustain reliance on costlier modified alternatives despite price pressure.
Strategic Opportunities
- Peru and Chile instant food sectors:Pregelatinized starch demand from cold-water soluble noodle and ready-meal manufacturers in Lima and Santiago corridors offers expansion vectors beyond Brazil-Argentina concentration.
- Mercosur harmonization tailwinds:Pending unified food additive registration standards could streamline cross-border product approvals and reduce compliance fragmentation.
- Enzymatic processing convergence:Integration of precision fermentation with conventional wet milling is opening specialty cyclodextrin and resistant starch production pathways.
Industry Challenges
- Excipient qualification timelines:ANVISA and local pharmacopeia certification processes for pharmaceutical-grade starches extend commercialization cycles by 18-24 months.
- Specialized enzymology talent scarcity:Regional universities produce insufficient biocatalysis specialists to staff expanding biotech processing facilities in Brazil's Southeast industrial corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Starch Derivatives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Liquid Starch, Pregelatinized Starch Application: Food & Beverage, Textile, Paper, Pharmaceutical End User: Food Manufacturers, Textile Industries, Pharmaceutical Companies, Chemical Industries Form: Granular, Powder, Liquid, Flake |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Tereos S.A, Tate & Lyle PLC, Südzucker Group, AGRANA Beteiligungs-AG, Molinos Juan Semino SA, Roquette Freres, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Starch Derivatives Market Evolving Landscape
Processing technology convergence and regulatory disclosure requirements are compressing traditional formulation approaches while opening specialty derivative pathways across South American food and pharmaceutical manufacturing.
Enzymatic modification systems are consolidating control over specialty starch derivative output. Food and pharmaceutical manufacturers in Brazil's Southeast corridor are adopting precision biocatalysis platforms at accelerating rates. This technology is consolidating market share among processors capable of delivering consistent dextrose equivalence values across maltodextrin and cyclodextrin product lines.
ANVISA's mandatory modified starch labeling rules under Brazil's national food code are reshaping exporter formulation strategies. Argentina's food safety authority has enacted parallel disclosure requirements that create compliance complexity for cross-border suppliers. Brazilian confectionery and dairy processors are responding by accelerating native starch substitution programs to simplify ingredient declarations.
Buyer concentration among multinational food manufacturers is compressing supplier negotiation leverage. Mid-sized Brazilian processors are consolidating procurement volumes through cooperative purchasing arrangements that bypass traditional distributor markups. This pattern is most visible in São Paulo state's beverage sector, where direct supplier contracts now dominate modified starch sourcing.
South America Starch Derivatives Market Segmentation
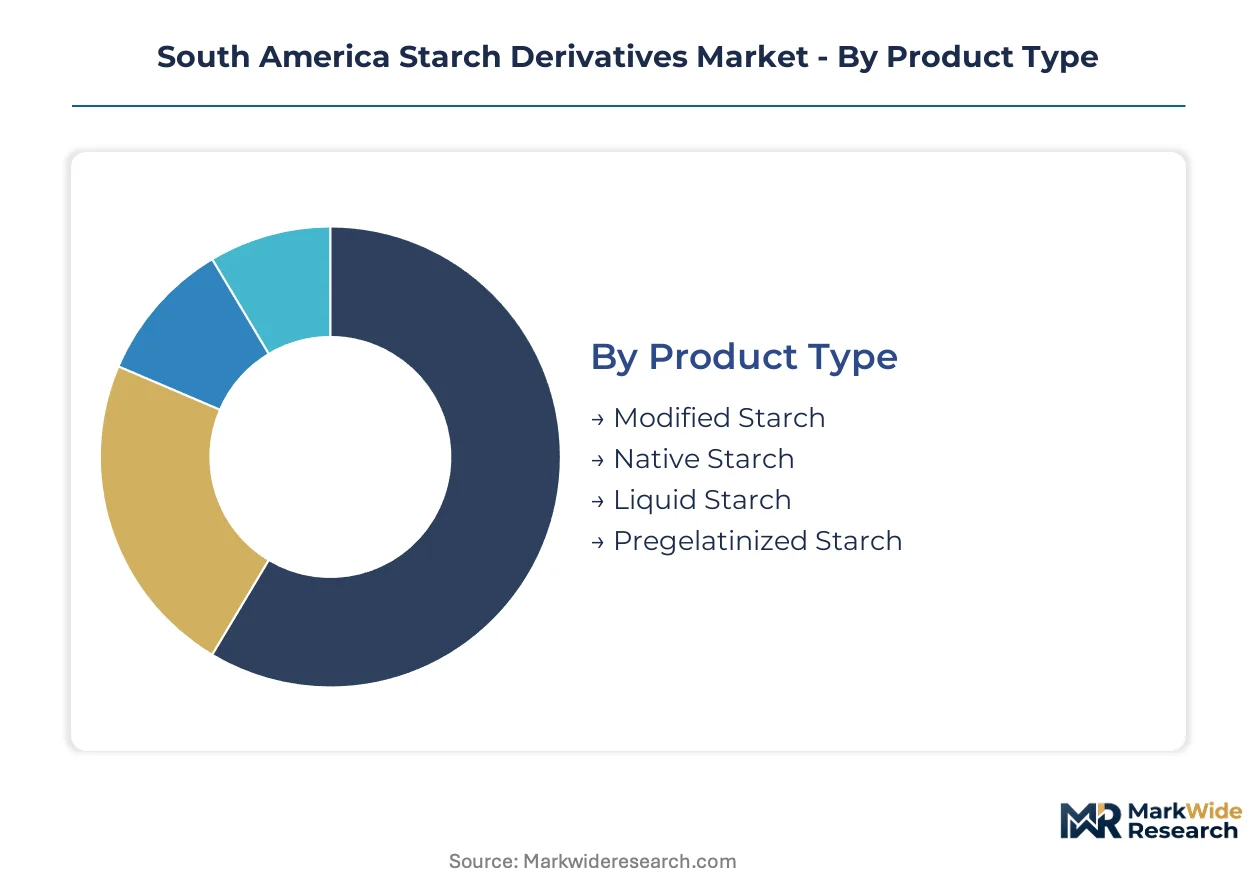
Starch derivative specifications vary sharply across South American industrial applications. Product functionality, regulatory compliance thresholds, and processing requirements drive distinct procurement patterns among Brazilian food manufacturers and Argentine pharmaceutical formulators.
Product Type:
Modified starch dominates value capture through premium pricing for functional performance, while native starch anchors volume throughput in cost-sensitive formulations.
- Modified Starch:Chemically, physically, or enzymatically altered to deliver superior freeze-thaw stability and shear resistance. Brazilian dairy and beverage processors in São Paulo state's industrial corridor specify modified starches for UHT-treated products requiring extended shelf stability under ANVISA additive regulations.
- Pregelatinized Starch:Pre-cooked starches offering instant cold-water solubility without additional heat processing. Chilean and Peruvian instant noodle manufacturers in Santiago and Lima corridors are expanding procurement of pregelatinized grades to streamline ready-meal production workflows.
- Native Starch:Unmodified starches extracted directly from corn, cassava, or potato sources serving basic thickening applications.
- Liquid Starch:Pumpable starch slurries employed in continuous-process industrial applications.
Today's leader: Modified Starch. Tomorrow's challenger: Pregelatinized Starch.
Application:
Food and beverage processing absorbs the majority of regional starch derivative volume, though pharmaceutical applications command the steepest margin premiums.
- Food & Beverage:Starch derivatives function as thickeners, stabilizers, texturizers, and bulking agents across processed food manufacturing. Brazilian confectionery producers seeking clean-label formulations under ANVISA's updated disclosure rules are accelerating substitution of synthetic hydrocolloids with modified starches.
- Pharmaceutical:Excipient-grade starches serve as binders, disintegrants, and fillers in tablet and capsule formulations. ANVISA qualification requirements and local pharmacopeia certification standards create entry barriers that limit supplier competition and sustain premium pricing for approved pharmaceutical-grade material.
- Textile:Starch sizing agents applied to yarn surfaces to strengthen fibers during weaving operations.
- Paper:Surface sizing and coating binders improving sheet strength and printability.
Food & Beverage captures current volume leadership. Pharmaceutical represents the steepest expansion trajectory.
End User:
Procurement consolidation among large-scale food manufacturers is reshaping supplier relationships across the Mercosur region.
- Food Manufacturers:Multinational and domestic processors of dairy, beverages, confectionery, and ready meals. Cooperative purchasing arrangements among mid-sized Brazilian processors in Minas Gerais state are bypassing traditional distributor channels to secure direct modified starch contracts.
- Pharmaceutical Companies:Formulators of solid dosage and parenteral products requiring excipient-grade starches. Extended ANVISA qualification timelines of 18-24 months compress commercialization cycles for new pharmaceutical-grade suppliers.
- Textile Industries:Yarn and fabric producers employing starch sizing in weaving operations.
- Chemical Industries:Industrial applications including adhesives, fermentation feedstocks, and biodegradable polymers.
Food Manufacturers control present procurement volume. Pharmaceutical Companies offer the most defensible margin structure.
Form:
Physical form selection correlates directly with processing equipment configuration and dissolution requirements.
- Powder:Dry-flowing starches dominating bulk ingredient handling systems. Brazilian Southeast corridor food plants specify powder forms for pneumatic conveying compatibility and extended storage stability.
- Granular:Free-flowing particles with controlled particle size distribution. Argentine pharmaceutical tablet press operations prefer granular starches for uniform die filling and consistent compression profiles.
- Liquid:Ready-to-use slurries eliminating hydration steps in continuous processes.
- Flake:Compressed starch products employed in specialty adhesive and coating applications.
Powder leads current industrial preference. Granular is gaining share fastest in pharmaceutical qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized enzymology talent concentrates in Brazil's Southeast industrial corridor, anchoring regional starch derivative processing capacity and shaping cross-border supply dynamics across the Mercosur bloc.
Brazil
Food manufacturers in São Paulo and Minas Gerais states drive modified starch procurement for clean-label beverage and dairy formulations. ANVISA's updated food additive regulations accelerate displacement of synthetic thickeners with native and modified alternatives. The Southeast industrial corridor hosts expanding enzymatic processing investments supported by Plano Nacional de Bioquímicos incentives.
Argentina
Export-oriented confectionery producers seek texture optimization through technical service partnerships with specialty starch suppliers. The national food code administered by the country's food safety authority mandates modified starch labeling disclosures that shape formulation strategies. Buenos Aires province concentrates pharmaceutical-grade starch demand driven by excipient certification requirements.
Chile
Instant noodle and ready-meal manufacturers in the Santiago corridor expand pregelatinized starch procurement for cold-water solubility without additional heat processing. The country's food safety standards align with Mercosur harmonization proposals under active negotiation. Domestic processors leverage Andean trade agreements to source feedstock from regional grain markets.
Peru
Lima-based food processors represent emerging demand vectors for pregelatinized starch grades in convenience food manufacturing. The country's national quality institute maintains additive standards that facilitate cross-border product registration with Brazilian and Chilean markets. Coastal industrial zones attract investment in modified starch blending operations serving Andean distribution networks.
Colombia
Beverage formulators in Bogotá and Medellín metropolitan areas adopt modified starches for UHT product stability under national food processing standards. The country's agricultural ministry supports cassava starch value chain development as an alternative to corn-based derivatives. Pacific and Caribbean port infrastructure enables import substitution strategies for specialty starch grades.
South America Starch Derivatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South American starch derivative supply. The market structure consolidates around integrated agricultural processors with captive feedstock access and regional distribution networks. Three archetypes dominate: multinational agribusiness conglomerates with wet milling infrastructure, regional pure-play starch processors, and pharmaceutical-focused excipient specialists. Competitive moves center on backward integration into corn sourcing and strategic partnerships with food manufacturers seeking formulation technical support.
Among multinational agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland Company exemplify integrated processors leveraging Mercosur region corn supply chains. Ingredion Incorporated and Tate & Lyle PLC occupy positions as specialty formulation partners. Regional specialists including Molinos Juan Semino SA represent domestic pure-play alternatives with localized distribution advantages.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Tereos S.A |
| Tate & Lyle PLC |
| Südzucker Group |
| AGRANA Beteiligungs-AG |
| Molinos Juan Semino SA |
| Roquette Freres |
| Others |
Value Network & Pricing Analysis
Specialized enzymology talent concentration in Brazil's Southeast industrial corridor feeds directly into pricing-tier spreads, with labor-cost differentials between São Paulo state biocatalysis specialists and Argentine process engineers creating measurable gaps between premium modified starch grades and standard native formulations.
Pricing Analysis
Bundled technical service partnerships command measurable premiums over unbundled commodity transactions across South American starch derivative procurement. Three-tier pricing structure across pharmaceutical-grade excipients, food-grade modified starches, and industrial native grades separates ANVISA-certified pharmaceutical material from standard food additives from basic textile sizing agents. Price differentiation stems from certification tier and volume scale, with pharmaceutical-grade excipients carrying the steepest premiums due to ANVISA qualification barriers. Pricing pressure stems from corn feedstock volatility in Mercosur grain markets, compressing margins for dextrose and glucose syrup manufacturers. Mid-sized Brazilian food processors exhibit highest price sensitivity, while multinational pharmaceutical formulators demonstrate lowest elasticity due to excipient switching costs.
Supply Chain Analysis
Corn feedstock supply rests on Brazilian, Argentine, and Paraguayan agricultural output, with regional grain market fluctuations directly transmitting into derivative processor cost structures. Wet milling operations draw from seasonal corn harvests, enzymatic processing inputs, and energy-intensive drying operations. Single-source vulnerability concentrates in Brazil's Southeast industrial corridor, where São Paulo and Minas Gerais states host disproportionate enzymatic processing capacity. Distribution runs through direct supplier contracts with multinational food manufacturers, bypassing traditional distributor markups for large-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with ANVISA's accelerated approval pathways for clean-label starch substitutes creating regulatory cost differentials between Brazilian formulation cycles and Argentine export-oriented disclosure requirements.
For Market Incumbents: Acquire specialized enzymology talent pools to defend against emerging biotech processing entrants. Cargill Incorporated and Ingredion Incorporated should expand backward integration into Mercosur corn sourcing to neutralize feedstock volatility threats. Capacity addition in Chile's Santiago corridor offers geographic diversification beyond Brazil-Argentina concentration. Certification investment in ANVISA pharmaceutical-grade excipient pipelines sustains margin pools against commodity price erosion. For New Entrants and Emerging Players: Begin with pregelatinized starch supply to Peruvian and Chilean instant food manufacturers, the most penetrable segment given cold-water solubility demand growth. Lima-based food processors and Santiago corridor ready-meal producers represent white-space targets with limited incumbent technical service coverage. A technical partnership go-to-market angle with mid-sized Brazilian confectionery producers bypasses direct competition with multinational procurement consolidation. For Investors and Strategic Acquirers: Food and pharmaceutical conglomerates with captive wet milling infrastructure are the most active acquirer in this space, seeking specialty formulation capabilities. Long-term viability centers on enzymatic processing convergence and clean-label regulatory tailwinds across the analysis window. Acquisition target archetype: regional pure-play starch processors with ANVISA pharmaceutical certification pipelines. The signal to watch is Mercosur harmonization progress on unified food additive registration standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Sourcing | Cargill leverages Mercosur grain supply chains to secure consistent enzymatic processing feedstock. |
| Pharmaceutical Excipient Certification | ANVISA qualification barriers create defensible margin pools for approved specialty derivative suppliers. |
| Enzymatic Processing Capacity Expansion | Plano Nacional de Bioquímicos incentives accelerate precision biocatalysis platform adoption in Brazil's Southeast. |
| Technical Service Partnership Models | Tate & Lyle secures texture optimization contracts with Argentine confectionery exporters seeking formulation support. |
| Cross-Border Distribution Network Buildout | Peru and Chile coastal industrial zones enable modified starch blending for Andean distribution networks. |
Research Methodology
Direct dialogue with plant managers at Brazilian wet milling facilities, procurement leads at São Paulo state dairy processors, ANVISA regulatory affairs specialists, and Argentine pharmaceutical formulators grounded qualitative findings in operational reality. Secondary validation drew from ANVISA food additive filings, Brazilian customs and trade data, SEC 10-K disclosures from listed agribusiness conglomerates, and Plano Nacional de Bioquímicos program documentation. Bottom-up volume modeling across product type, application, and end-user segments converged with top-down macroeconomic triangulation.
Segmented outputs across modified starch, pregelatinized starch, native starch, and liquid starch grades projected through food and beverage, pharmaceutical, textile, and paper applications over the analysis window. CAGRs derived from historical volume trajectories, regulatory approval velocity, and enzymatic processing capacity expansion schedules. Forecast inputs incorporated ANVISA disclosure rule implementation timelines and Mercosur harmonization negotiation progress.
Several conditions sit outside the modeled scope, including abrupt ANVISA regulatory reversals, Mercosur trade bloc dissolution scenarios, and corn crop failure events beyond historical yield variance. Forecasts reflect assumptions about continued clean-label substitution momentum and pharmaceutical excipient demand growth. A small set of named triggers warrants ongoing watch: ANVISA accelerated approval pathway modifications, Mercosur food additive standard unification votes, and enzymology talent pipeline constraints in Brazil's Southeast corridor.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Diesel Exhaust Fluid Market