
 Middle-East and Africa Electronics Adhesives Market | 2026-2036
Middle-East and Africa Electronics Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Electronics Adhesives Market Foresight
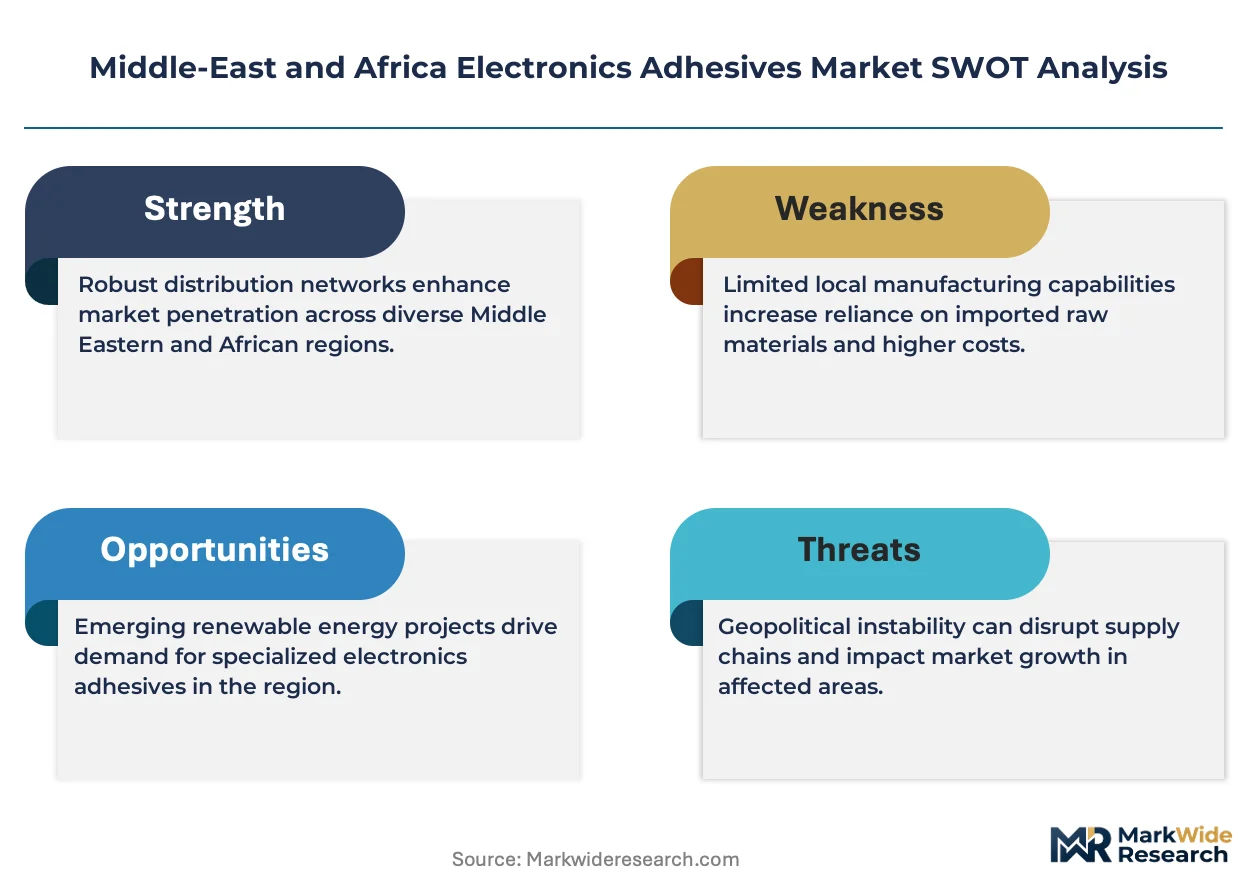
A capital-intensity divergence between integrated resin producers and specialty compounders is reorganizing competitive tiers in the Middle-East and Africa electronics adhesives sector. Henkel AG & Co. KGaA leverages its captive epoxy formulation capacity to serve telecom infrastructure projects across the Gulf. Dow anchors regional supply through localized silicone adhesive production serving automotive electronics customers. H.B. Fuller Company competes via specialized water-based acrylic platforms tailored to consumer electronics assemblers in North Africa.
Electronics adhesives in this region encompass thermally conductive and electrically insulating bonding systems, typically formulated from epoxy resins, silicone elastomers, or polyurethane matrices with filler loadings between 30-80% by weight, designed to secure components, dissipate heat, and protect circuits against mechanical stress and environmental ingress. Epoxy formulations dominate bonding applications for their high shear strength and chemical resistance in harsh desert operating conditions. Silicone adhesives lead encapsulation demand where flexible thermal cycling performance matters, particularly in automotive and aerospace electronics exposed to extreme diurnal temperature swings. Water-based technology remains nascent but attracts investment as Saudi Arabian and UAE environmental compliance tightens around volatile organic compound emissions.
SFDA material safety requirements in Saudi Arabia, UAE's alignment with REACH substance restrictions, and South Africa's BIS-equivalent SABS standards collectively shape product registration pathways and formulation constraints across the Middle-East and Africa. These frameworks elevate compliance costs for imported adhesive portfolios while creating qualified-supplier advantages for manufacturers with regional certification infrastructure. Stakeholders must monitor evolving local-content thresholds in Saudi giga-projects and Egyptian electronics manufacturing zones to calibrate capacity placement and distributor partnerships.
Market Dynamics
Saudi Arabia's giga-project manufacturing zones are concentrating electronics adhesive demand into localized procurement clusters, while UAE's RoHS-aligned material standards simultaneously filter out legacy halogen-containing formulations from regional supply chains.
Growth Catalysts
- Local Content Mandates:Saudi Vision 2030 giga-projects require minimum domestic sourcing thresholds for construction and manufacturing inputs, creating captive demand for regionally produced adhesive compounds.
- SFDA Material Safety Requirements:Saudi Arabia's pharmaceutical-grade safety protocols are extending into electronics manufacturing, elevating adhesive purity standards and disqualifying informal import channels.
- Thermally Conductive Epoxy Systems:Telecom infrastructure deployment across the Gulf is pulling high-fill epoxy formulations rated for desert thermal cycling performance.
Market Restraints
- Specialty Resin Import Dependence:High-purity bisphenol-A epoxies and functional silicone precursors concentrate in Asian supply bases, exposing formulators to freight cost volatility and currency mismatch risks.
- REACH-Aligned Substance Restrictions:UAE's adoption of European chemical hazard classifications is accelerating obsolescence of legacy curing agents and flame retardants still common in lower-cost imported stocks.
- Water-Based Technology Performance Gap:Aqueous acrylic and polyurethane systems lack the thermal conductivity and moisture resistance required for automotive under-hood electronics, limiting substitution potential in high-value segments.
Strategic Opportunities
- Egyptian Electronics Manufacturing Zones:New industrial city developments near Suez Canal logistics corridors offer tariff-advantaged positioning for adhesive compounders serving European-bound contract manufacturers.
- Halogen-Free Epoxy Convergence:Phosphorus-nitrogen synergist chemistry is crossing maturity thresholds, enabling formulators to meet Gulf fire safety codes without brominated additives.
- Direct Technical Service Models:Smartphone assemblers in South Africa are bypassing traditional distribution layers for on-site formulation support and just-in-time inventory programs.
Industry Challenges
- Formulation Chemist Scarcity:Regional universities produce limited graduates with combined polymer science and electronics packaging expertise, forcing manufacturers to import technical talent or extend training cycles.
- Multi-Jurisdiction Certification Overlap:Adhesive portfolios require parallel registration under Saudi SFDA, UAE MOHAP, and South African SABS frameworks, each with distinct testing protocols and documentation languages.
- Legacy Equipment Retrofit Complexity:Water-based adhesive transitions demand humidity-controlled dispensing environments that many North African contract manufacturers lack, delaying environmental compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Electronics Adhesives Market |
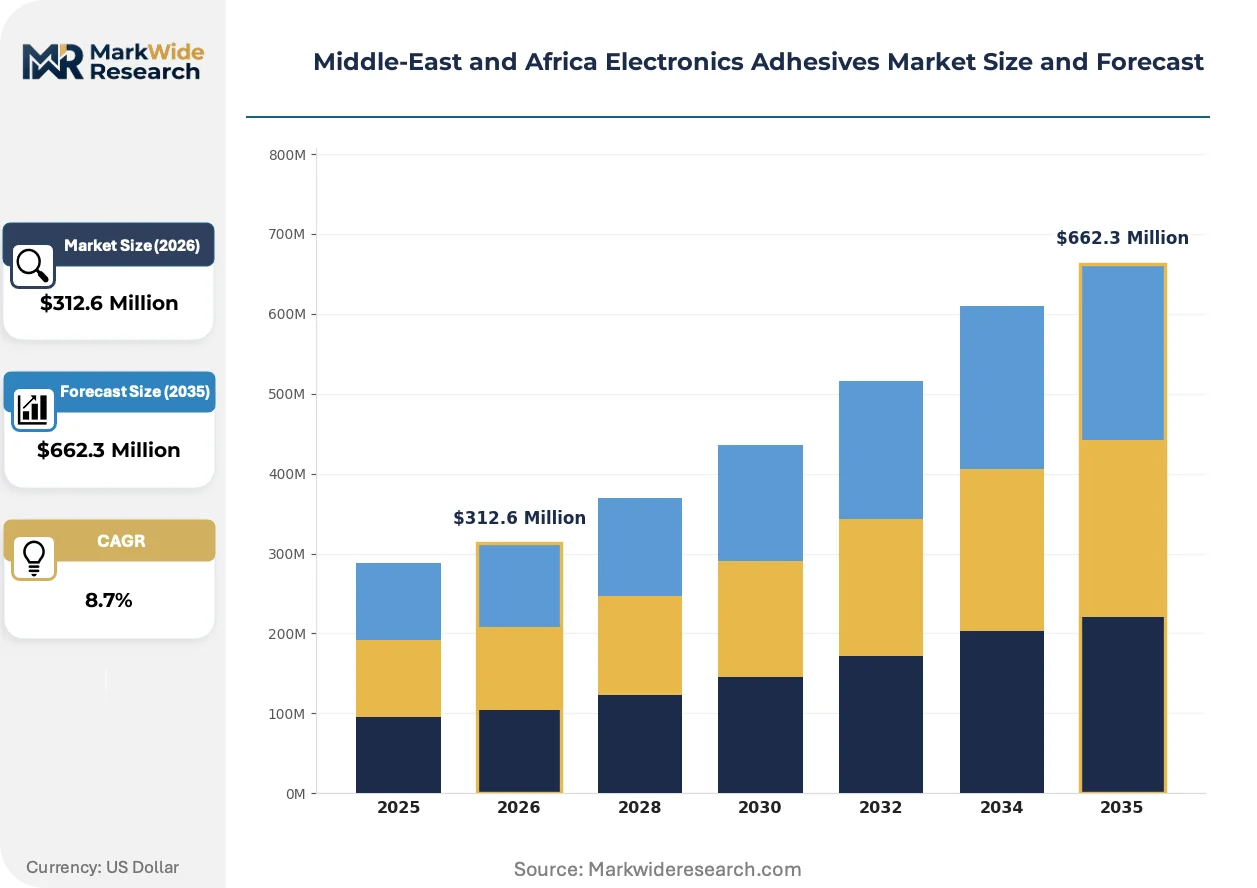
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Polyurethane, Acrylic End User: Consumer Electronics, Automotive, Aerospace, Telecom Application: Bonding, Encapsulation, Coating, Sealing Technology: Thermal Curing, Ultraviolet Curing, Solvent-Based, Water-Based |
| Companies Covered | Henkel AG & Co. KGaA, Dow, H.B. Fuller Company, Arkema Group, 3M Company, Sika AG, The Industrial Group Ltd., Huntsman International LLC, Evonik Industries AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Electronics Adhesives Market Shifts & Advancements
Thermal management priorities in desert-operated electronics are accelerating material substitution cycles, while regulatory alignment with European chemical frameworks is compressing formulation optionality across the Middle-East and Africa.
Two-part thermally conductive epoxies with boron nitride filler loadings above 60% by weight are displacing silicone greases in base station power amplifier assemblies. Telecom infrastructure contractors in the UAE and Saudi Arabia specify these systems for 150°C continuous operation. This material transition is decomposing the traditional segmentation between structural bonding and thermal interface functions, forcing suppliers to consolidate previously separate product lines.
UAE's alignment with REACH substance restrictions is prohibiting certain aromatic amine curing agents and legacy brominated flame retardants in electronics adhesives. Formulators are reformulating portfolios with aliphatic amine alternatives and phosphorus-based fire suppressants. Consumer electronics assemblers in Dubai and Abu Dhabi free trade zones face compressed requalification timelines as these substance bans phase in ahead of Gulf Cooperation Council harmonization.
Smartphone manufacturers in South Africa are consolidating adhesive suppliers from five-plus vendors to two preferred partners with captive technical service capabilities. This concentration eliminates spot-buying flexibility but secures priority allocation during resin shortage periods. The shift is most pronounced in Cape Town and Johannesburg assembly corridors, where just-in-time production models leave minimal buffer inventory for qualification delays.
Middle-East and Africa Electronics Adhesives Market Segmentation
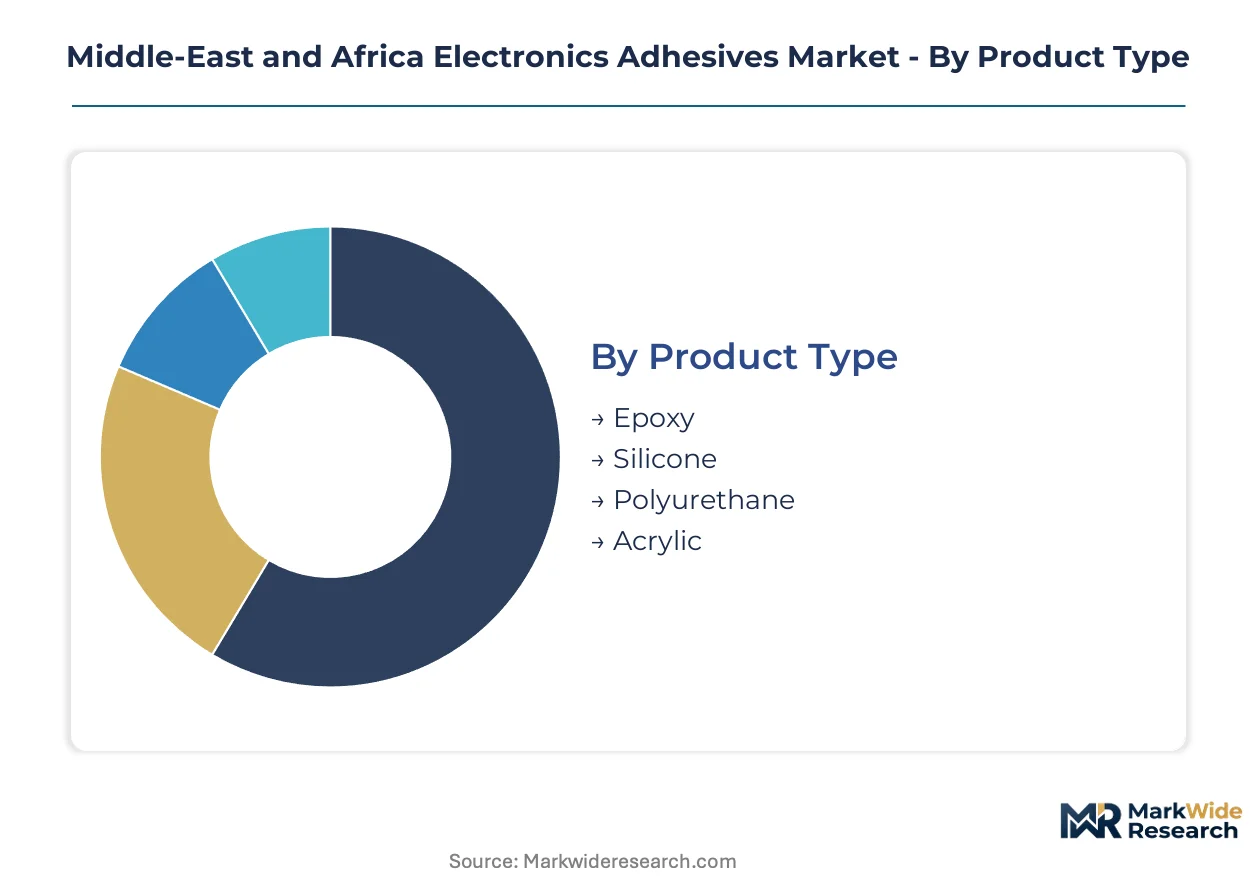
Electronics adhesive selection in the Middle-East and Africa hinges on thermal cycling demands in desert environments and tightening chemical compliance regimes. Formulators must balance performance specifications against registration complexity across Saudi SFDA, UAE MOHAP, and South African SABS frameworks.
Product Type:
Substitution pressure runs highest against solvent-laden legacy systems as water-based and UV-curable alternatives close performance gaps in controlled manufacturing environments.
- Epoxy:Two-part thermally conductive formulations with boron nitride or aluminum oxide fillers above 60% by weight deliver the shear strength and chemical resistance demanded by Saudi telecom infrastructure and UAE aerospace electronics. Giga-project manufacturing zones in Saudi Arabia specify these systems for continuous operation at 150°C, creating qualified-supplier bottlenecks for high-purity bisphenol-A resin feedstocks.
- Silicone:Flexible elastomeric systems accommodate extreme diurnal temperature swings across Gulf automotive and aerospace applications. Dow's localized production in the region anchors supply for under-hood electronics where thermal cycling performance outweighs structural bonding requirements.
- Polyurethane:Moisture-cure systems serve mid-tier consumer electronics assembly in North African contract manufacturing zones where capital equipment for thermal or UV curing remains limited.
- Acrylic:Water-based and solvent-borne pressure-sensitive variants target display lamination and temporary fixturing applications in South African smartphone assembly corridors.
Epoxy retains volume leadership; silicone holds the steepest expansion curve.
End User:
Customer procurement sophistication varies sharply across the value chain, with Gulf telecom operators demanding technical service integration while North African assemblers prioritize spot-buying flexibility.
- Consumer Electronics:South African smartphone and wearable manufacturers are consolidating supplier bases from five-plus vendors to two preferred partners with captive formulation support. Cape Town and Johannesburg assembly corridors operate on just-in-time inventory models that eliminate buffer stock for qualification delays.
- Automotive:Under-hood electronics in Gulf markets expose adhesives to temperature swings exceeding 50°C daily, favoring silicone encapsulants over rigid epoxy alternatives. OEMs specify materials qualified under combined thermal and salt-fog testing protocols.
- Aerospace:UAE-based MRO facilities and Saudi giga-project aviation clusters demand outgassing-tested formulations meeting ASTM E595 or ECSS-Q-ST-70-02 standards for satellite and avionics applications.
- Telecom:5G base station deployment across Saudi Arabia and the UAE pulls high-fill thermally conductive epoxies for power amplifier assemblies, collapsing the traditional separation between structural bonding and thermal interface materials.
Telecom infrastructure commands premium pricing tiers; consumer electronics drives absolute volume scale.
Application:
Functional convergence between bonding and thermal management is compressing product line differentiation as single-formulation solutions displace multi-material stacks.
- Bonding:Structural attachment of heat sinks, housings, and circuit boards relies on epoxy systems with tailored rheology for automated dispensing. Saudi giga-projects specify minimum pull strengths under elevated temperature aging protocols.
- Encapsulation:Silicone and polyurethane systems protect sensitive components against sand ingress and humidity in Gulf outdoor installations. Potting depth and cure shrinkage specifications vary by end-use reliability requirements.
- Coating:Conformal protection for PCBs in aerospace and automotive applications demands thin-film uniformity and repairability under IPC-CC-830 or MIL-I-46058C class ratings.
- Sealing:Gasket and enclosure sealing applications in telecom cabinets and automotive control modules balance compression set resistance against chemical compatibility with cooling fluids and lubricants.
Bonding captures the largest share of formulation development resources; encapsulation faces the most stringent qualification timelines.
Technology:
Environmental compliance trajectories in Saudi Arabia and the UAE are forcing capital allocation decisions between established thermal curing infrastructure and emerging low-VOC alternatives.
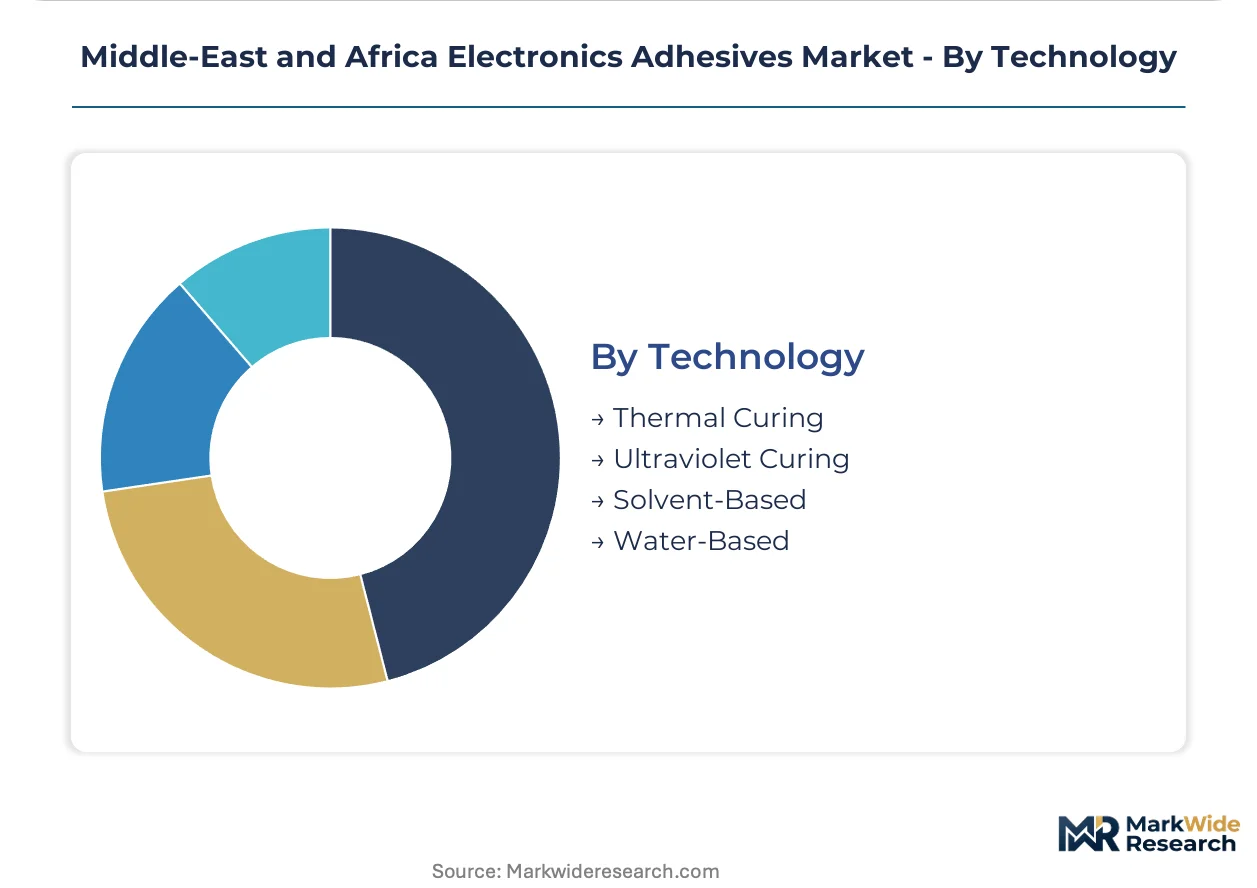
- Thermal Curing:Elevated-temperature epoxy and silicone systems dominate high-reliability applications where complete cure conversion and outgassing control are non-negotiable. Saudi and UAE manufacturers maintain captive batch ovens and continuous conveyor systems.
- Ultraviolet Curing:Acrylate-based systems enable rapid through-put in display lamination and temporary masking operations. South African electronics assemblers favor UV platforms for speed-to-market in smartphone refurbishment lines.
- Solvent-Based:Legacy acrylic and rubber formulations persist in price-sensitive North African contract manufacturing where environmental enforcement remains uneven and capital for equipment conversion is constrained.
- Water-Based:Aqueous acrylic and polyurethane dispersions attract investment as Saudi and UAE VOC emissions regulations tighten, though thermal conductivity and moisture resistance gaps limit penetration in automotive under-hood segments.
Thermal curing maintains installed base dominance; water-based technology climbs the steepest adoption slope where regulatory deadlines enforce compliance investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures sharply across the Middle-East and Africa electronics adhesives market. Gulf buyers absorb premium formulations for telecom and aerospace reliability, while North African contract manufacturers drive hard on spot-buying economics.
Saudi Arabia
NEOM and Red Sea giga-projects concentrate electronics manufacturing demand into captive procurement zones. SFDA material safety protocols now extend purity requirements into industrial adhesives, disqualifying informal import channels. Riyadh and the Eastern Province host the bulk of qualified supplier infrastructure.
United Arab Emirates
Telecom infrastructure deployment and aerospace MRO operations pull high-performance thermally conductive systems. MOHAP alignment with REACH substance restrictions accelerates obsolescence of legacy halogenated formulations. Dubai and Abu Dhabi free trade zones serve as formulation requalification hubs for Gulf-bound products.
South Africa
Smartphone and wearable assembly lines in Cape Town and Johannesburg drive consolidation toward preferred adhesive partners. SABS standards create qualified-supplier barriers for imported portfolios lacking local certification. Cape Town's assembly corridor operates on just-in-time models that punish qualification delays.
Egypt
New industrial cities near Suez Canal logistics corridors attract adhesive compounders targeting European-bound contract manufacturers. The country's national industrial development authority offers tariff-advantaged positioning for regional supply bases. Alexandria and Suez manufacturing zones concentrate electronics assembly investment.
Israel
Defense electronics and medical device clusters demand outgassing-tested formulations meeting ASTM E595 standards. The national standards institute maintains rigorous certification pathways that filter out lower-grade imports. Tel Aviv and Haifa technology corridors anchor precision electronics adhesive consumption.
Middle-East and Africa Electronics Adhesives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle-East and Africa electronics adhesives market. Integrated resin producers leverage captive feedstock positions to serve high-volume Gulf infrastructure projects. Specialty compounders compete on formulation agility for consumer electronics assemblers. Strategic moves center on regional certification infrastructure buildout and direct technical service deployment.
Among the integrated leaders, Henkel AG & Co. KGaA and Dow exemplify divergent geographic anchoring strategies. Henkel represents the European-heritage formulator archetype with regional formulation capacity. Dow occupies a position as the North American-anchored producer with localized silicone manufacturing. H.B. Fuller Company sits within the specialty tier, exemplifying the focused compounder model targeting consumer electronics segments. These three anchors illustrate how competitive positioning fragments across integrated versus specialized capability sets.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Dow |
| H.B. Fuller Company |
| Arkema Group |
| 3M Company |
| Sika AG |
| The Industrial Group Ltd. |
| Huntsman International LLC |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Captive epoxy formulation capacity in Saudi Arabia and the UAE anchors regional supply bases and sets price floors through qualified-supplier premiums. Scale economies at integrated resin producers compress margins for specialty compounders importing high-purity bisphenol-A feedstocks, while local content mandates in giga-projects create captive procurement zones that insulate domestic formulators from spot-price volatility.
Pricing Analysis
After-sales technical service contracts now drive lifetime value for adhesive suppliers serving Gulf telecom infrastructure and South African smartphone assemblers. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified formulations from REACH-aligned systems and uncertified imports. Price differentiation hinges on thermal cycling performance ratings and MOHAP registration status. Cost compression in economy-tier solvent-based acrylics is intensifying because Egyptian contract manufacturers prioritize spot-buying flexibility over qualification investment. North African assemblers exhibit highest price sensitivity; UAE aerospace MRO operations absorb premium tiers without volume negotiation.
Supply Chain Analysis
China and South Korea anchor high-purity bisphenol-A epoxy resin production, while Germany and the United States supply functional silicone precursors for Gulf automotive applications. Regional formulators draw from Asian feedstock bases for boron nitride thermal fillers and aliphatic amine curing agents. Single-source vulnerability concentrates in specialty resin channels exposed to Red Sea logistics disruptions. Distribution runs through authorized distributor networks in Saudi Arabia and direct technical service models in South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story. Halogen-free epoxy convergence and phosphorus-nitrogen synergist chemistry maturity are accelerating substitution away from legacy brominated systems across Gulf manufacturing zones.
For Market Incumbents: Secure SFDA and MOHAP certification infrastructure ahead of substance restriction phase-ins. Expand captive boron nitride filler compounding capacity in Saudi giga-project zones to defend against Asian import price volatility. Lock long-term supply agreements with South Korean epoxy resin producers before currency mismatch risks deepen. For New Entrants and Emerging Players: SABS fast-track certification for water-based acrylic platforms opens entry into South African smartphone assembly corridors. Target Egyptian electronics manufacturing zones near Suez Canal logistics hubs where tariff-advantaged positioning serves European-bound contract manufacturers. Lead with humidity-controlled dispensing equipment partnerships to bypass North African retrofit bottlenecks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty compounders with halogen-free formulation libraries and regional registration infrastructure. Five-to-ten year viability hinges on Gulf regulatory alignment completion and local content threshold escalation. Watch phosphorus-nitrogen fire suppressant patent filings as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive bisphenol-A supply secures margins against Asian feedstock volatility in Saudi zones. |
| SFDA Certification Infrastructure Buildout | Registered supplier status creates qualified-supplier bottlenecks for giga-project procurement clusters. |
| Halogen-Free Formulation Portfolio Conversion | Phosphorus-nitrogen chemistry meets UAE MOHAP REACH alignment ahead of GCC harmonization. |
| Direct Technical Service Deployment | On-site formulation support captures South African smartphone assembler consolidation toward preferred partners. |
| Egyptian Manufacturing Zone Joint Venture | Suez Canal positioning offers tariff-advantaged supply for European contract electronics manufacturers. |
Research Methodology
A spread of perspectives from adhesive formulators, polymer procurement leads at Gulf telecom contractors, South African electronics assemblers, and Egyptian industrial zone operators converged on the working assumptions. Primary fieldwork combined with secondary validation from SFDA substance registration databases, UAE MOHAP chemical hazard classifications, SABS certification records, and customs trade data for epoxy resin and silicone precursor imports. Bottom-up demand modeling across consumer electronics, automotive, and telecom end-uses triangulated against top-down capacity assessments for regional formulation facilities.
Segmentation dimensions modeled include adhesive chemistry type, curing technology platform, thermal conductivity specification tier, end-use industry, and geographic regulatory cluster. Volume and value outputs across the projection horizon reflect adoption curve assumptions for water-based technology and halogen-free formulation conversion. CAGRs were derived from weighted capacity expansion timelines and local content mandate enforcement schedules. Industry-specific forecast inputs incorporated giga-project manufacturing zone commissioning timelines and smartphone assembly line qualification protocols.
Underlying assumptions cover REACH-aligned substance restriction phase-in schedules and SFDA material safety protocol extensions, with deviation risk concentrated in multi-jurisdiction certification timeline slippage and specialty resin freight cost volatility. Forecasts reflect these conditions with recalibration cycles aligning with material shifts in Gulf regulatory harmonization and local content threshold announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market