
 Middle East & Africa Adhesives and Sealants Market | 2026-2036
Middle East & Africa Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Adhesives and Sealants Market Insights
Polyurethane formulations is rebalancing cost-performance tradeoffs for high-temperature construction joints across the Gulf. Henkel AG & Co. KGaA leverages its regional compounding facilities to supply certified structural adhesives for Saudi infrastructure. Sika AG anchors its position through localized manufacturing in Dubai and technical service networks spanning East African markets. Dow competes on silicone chemistry tailored to desert climate exposure cycles.
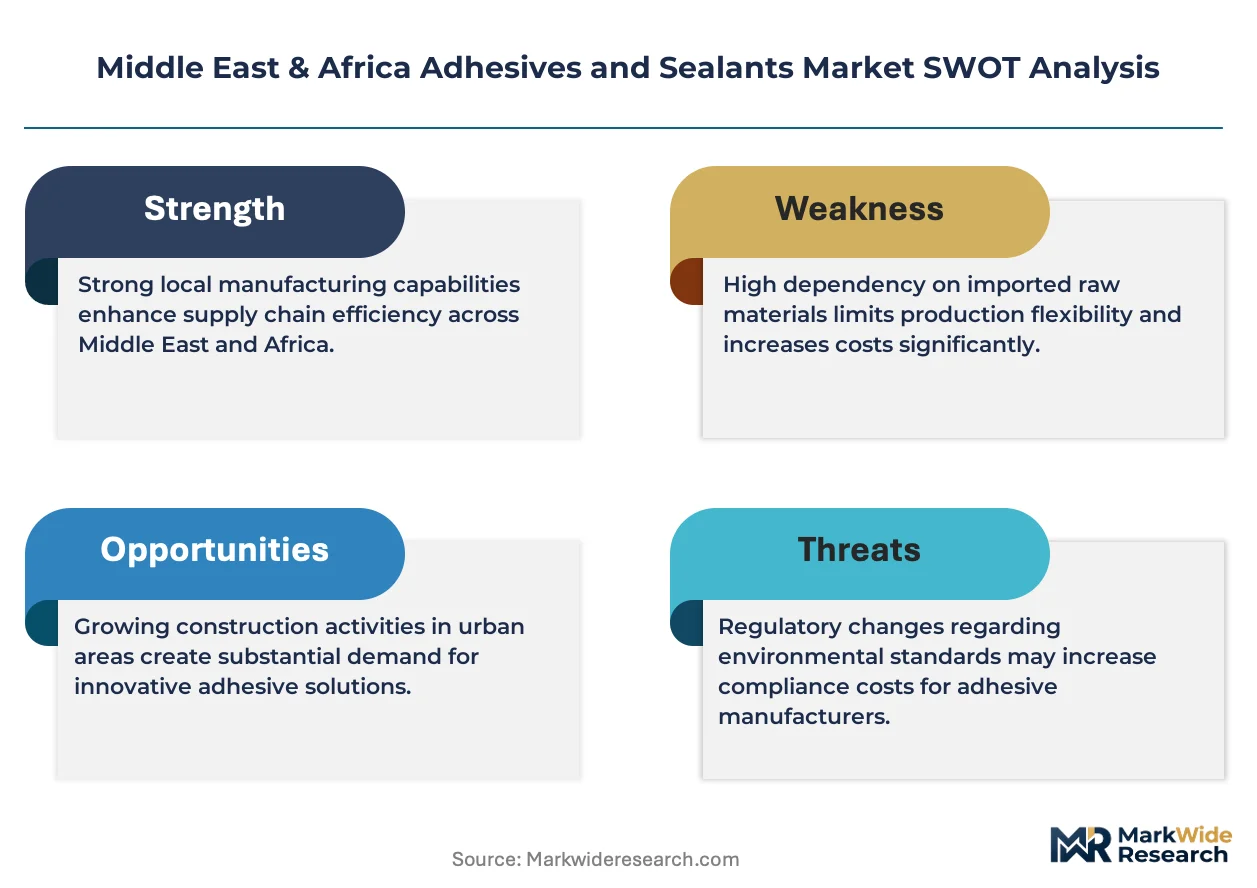
Adhesives and sealants comprise formulated polymer systems—typically 30-60% resin content with fillers, plasticizers, and curing agents—that create permanent or reversible bonds between substrates or seal gaps against environmental ingress. Their primary industrial purpose spans load-transfer in bonded assemblies, weatherproofing envelopes, and encapsulation of sensitive electronic components. Polyurethane and silicone product types command the deepest margin pools in Middle East construction given specification intensity for facade and waterproofing systems. Water-based technology is gaining specification share in UAE and Saudi interior applications as green building standards tighten solvent-content thresholds, though solvent-based systems still dominate exterior structural grades where moisture-cure speed proves critical.
SFDA and Saudi Building Code authorities enforce VOC limits and structural-adhesive performance certification for commercial buildings across the Kingdom. ECHA REACH-equivalent frameworks in South Africa and Kenya's BSI-aligned building product standards shape import compliance and local formulation requirements. Stakeholders must monitor divergence between Gulf harmonization initiatives and sub-Saharan national standards when configuring regional product portfolios and testing investments.
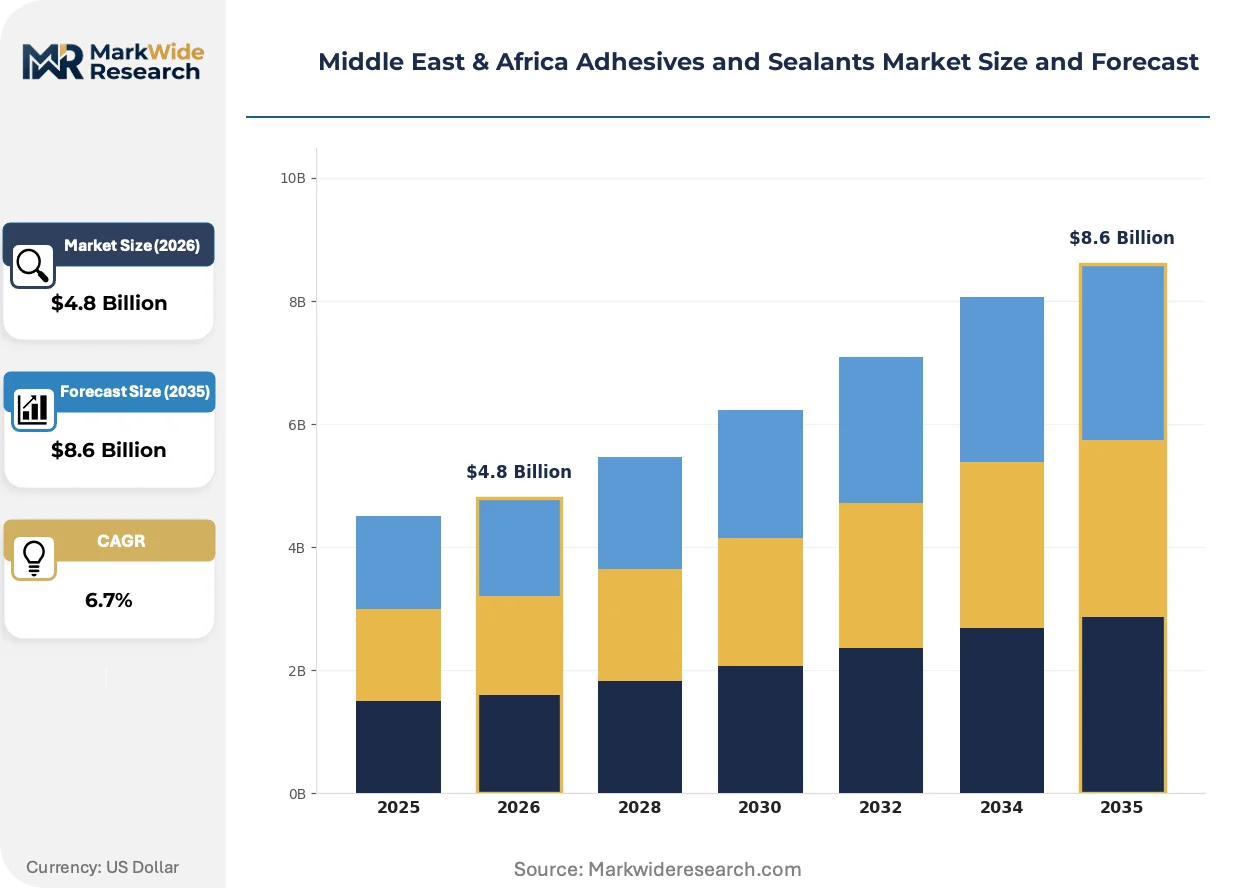
Market Dynamics
Polyurethane and silicone chemistry platforms are consolidating specification control across Gulf megaprojects as Saudi Building Code and UAE green building mandates tighten VOC thresholds and structural certification requirements.
Growth Catalysts
- NEOM and Red Sea Infrastructure Pipeline:Saudi Arabia's gigaproject portfolio is generating concentrated procurement of certified structural bonding systems for facade and waterproofing applications.
- SFDA VOC Compliance Mandates:Saudi Building Code authorities are enforcing emission thresholds that favor water-based interior formulations and certified exterior structural grades.
- Localized Manufacturing Investment:Regional compounding capacity expansion in Dubai and Jeddah is compressing lead times for specification-grade polyurethane systems.
Market Restraints
- Petrochemical Feedstock Volatility:Polyol and isocyanate input costs fluctuate with regional crude derivative pricing, compressing margin visibility for formulated products.
- Import Dependency in Sub-Saharan Africa:Kenya, Nigeria, and South Africa rely on concentrated European and Asian supply for specialty silicone intermediates.
- Moisture-Cure Speed Limitations:Water-based systems face technical barriers in high-temperature exterior applications where solvent-based chemistry retains performance advantages.
Strategic Opportunities
- East African Construction Uptake:Ethiopia and Tanzania infrastructure investment is creating underpenetrated demand for cost-optimized sealant systems in transportation and building envelopes.
- Modular and Prefabricated Building:Factory-assembled unit construction in UAE and Saudi Arabia is expanding adhesive-intensive panel bonding applications.
- ECHA REACH-Equivalent Harmonization:South Africa and Kenya are aligning chemical registration frameworks, streamlining multi-market product registration for regional suppliers.
Industry Challenges
- Formulation Chemist Scarcity:Regional technical talent pools lack depth in moisture-cure polyurethane and two-part epoxy system design.
- Certification Timeline Compression:Saudi Building Code and SFDA structural-adhesive approval cycles extend commercialization timelines for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Adhesives and Sealants Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Silicone, Epoxy Application: Construction, Automotive, Electronics, Packaging End User: Manufacturers, Contractors, Retailers, Distributors Technology: Water-Based, Solvent-Based, Hot Melt, Pressure Sensitive |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, Dow, Arkema Group, H.B. Fuller Company, 3M Company, ITW Performance Polymers, Huntsman International LLC, Pidilite Industries Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Adhesives and Sealants Market Trends and Innovations
Hybrid polymer platforms and digital specification tools are reconfiguring how structural bonding systems are selected, tested, and deployed across Middle East megaprojects and African infrastructure corridors.
MS polymer hybrid formulations combine silicone weathering resistance with polyurethane mechanical strength in single-component systems. Saudi facade contractors are specifying these for movement joints in NEOM and Red Sea developments. This chemistry is expanding into high-performance waterproofing applications previously reserved for two-part epoxies.
UAE green building mandates and Saudi Building Code amendments are tightening interior VOC thresholds below 50 g/L for commercial occupancy. Water-based acrylic and hybrid systems are gaining specification share in interior finishing applications. Paint and coatings distributors in Dubai and Riyadh are expanding adhesive-sell alongside traditional decorative product lines.
Engineering firms and main contractors are consolidating procurement through approved vendor lists with pre-certified structural adhesive portfolios. Traditional open-specification bidding is compressing toward nominated-supplier arrangements on major infrastructure packages. This concentration is most visible in Saudi Arabia's gigaproject procurement desks and UAE developer technical teams.
Middle East & Africa Adhesives and Sealants Market Segmentation
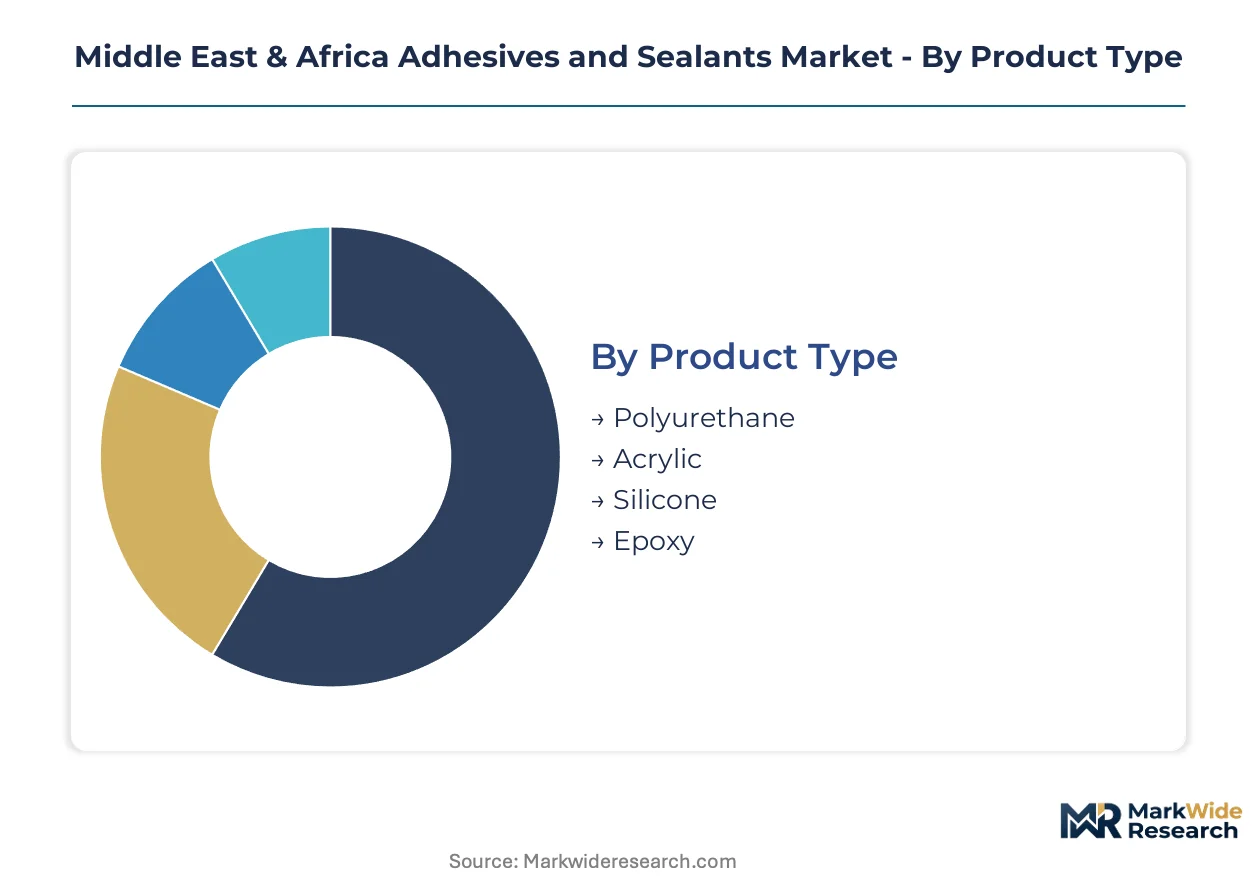
Segmentation in the Middle East & Africa adhesives and sealants market reveals how formulation chemistry, application intensity, and regulatory compliance create distinct competitive battlegrounds. Understanding these divisions exposes where margin pools concentrate and which technology platforms are displacing legacy systems.
Product Type:
Supply concentration among polyurethane and silicone producers in the Gulf has compressed regional pricing power into two chemistry platforms.
- Polyurethane:Moisture-cure systems combine polyol and isocyanate components for structural bonding with high tensile strength and flexibility. NEOM and Red Sea developers specify these for facade joints and waterproofing membranes where thermal cycling demands durability. Saudi Building Code certification requirements favor established regional compounders with tested product portfolios.
- Silicone:RTV formulations deliver UV resistance and temperature stability across desert exposure cycles. UAE green building mandates and Saudi exterior specifications drive procurement for curtain wall glazing and expansion joints. Dow and regional manufacturers compete on tailored desert-grade formulations with accelerated cure profiles.
- Acrylic:Water-based emulsions serve interior finishing applications where SFDA VOC thresholds below 50 g/L apply.
- Epoxy:Two-part systems anchor high-load structural connections in infrastructure and industrial assemblies.
Today's leader: Polyurethane. Tomorrow's challenger: Silicone.
Application:
Project scale and specification intensity vary dramatically across end-use segments, with construction commanding the deepest technical engagement.
- Construction:Structural bonding, waterproofing, and facade systems dominate volume and value. Saudi Arabia's gigaproject pipeline concentrates procurement through approved vendor lists with pre-certified adhesive portfolios. SFDA and Saudi Building Code enforcement tightens compliance costs for new entrants.
- Automotive:Lightweighting trends drive structural adhesive substitution for mechanical fasteners in vehicle assembly. Moroccan and South African manufacturing hubs import specialty grades from European suppliers given limited regional formulation capacity.
- Electronics:Encapsulation and thermal management applications require ultra-pure silicone and epoxy systems. Sub-Saharan markets rely on Asian supply chains for specialty grades.
- Packaging:Hot melt and pressure-sensitive systems serve food and consumer goods sectors with less regulatory complexity than construction grades.
Construction commands current procurement volume. Electronics packaging for Gulf data center infrastructure represents the steepest expansion trajectory.
End User:
Customer type determines technical service intensity and pricing structure, with contractors requiring the most specification support.
- Manufacturers:Industrial OEMs procure adhesives as production inputs with long-term supply agreements and technical partnership requirements. Automotive and electronics assemblers in Morocco, South Africa, and UAE anchor this segment.
- Contractors:Construction firms executing Saudi gigaprojects and UAE developments purchase through nominated-supplier arrangements with pre-approved product lists. Technical service and on-site support differentiate suppliers.
- Retailers:Hardware and building material distributors serve maintenance, repair, and small-scale construction with standard-grade products.
- Distributors:Specialized chemical distributors bridge import supply and local formulation for sub-Saharan markets lacking manufacturing scale.
Contractor channel concentration is tightening around approved vendor lists. Distributor networks in East Africa are gaining share fastest.
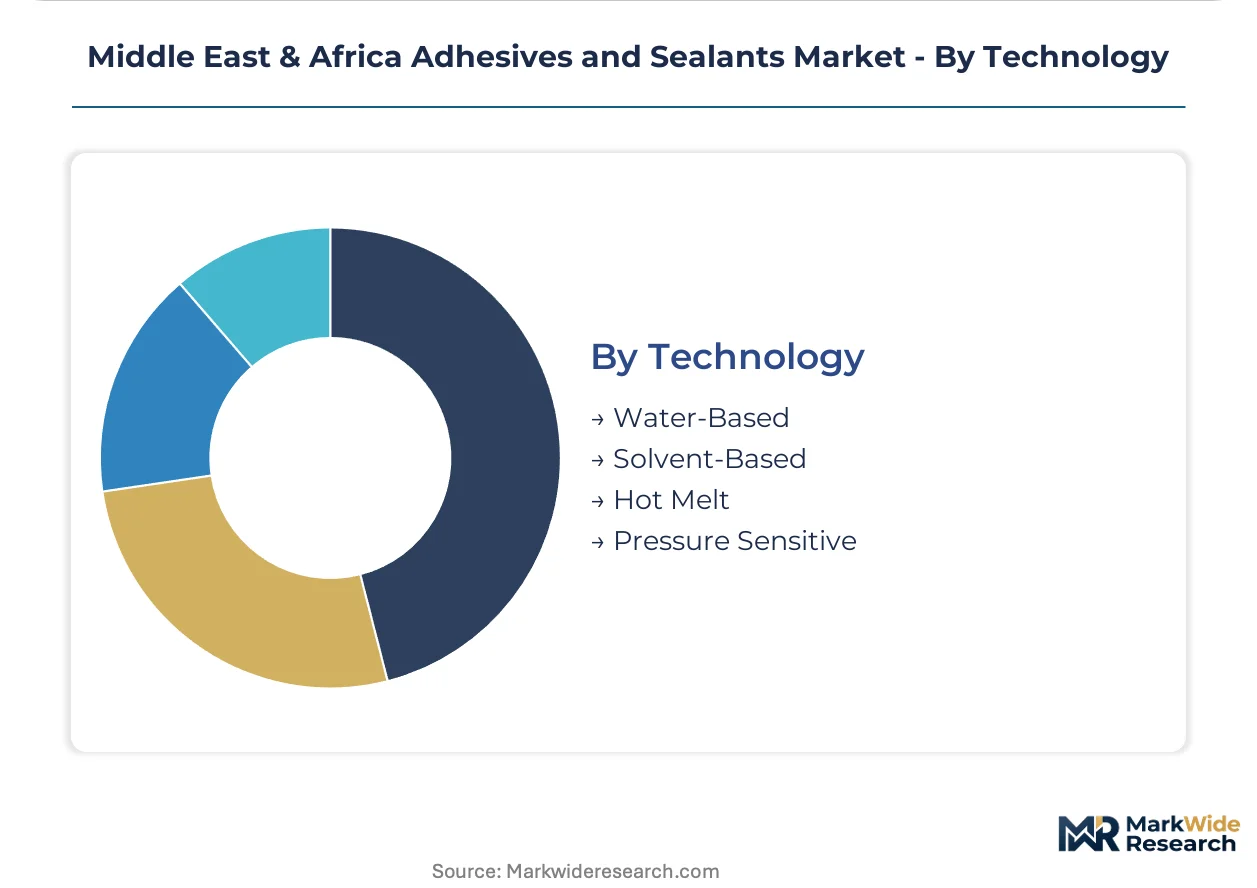
Technology:
Environmental compliance and performance tradeoffs segment technology adoption across interior and exterior applications.
- Water-Based:Acrylic and hybrid emulsions gain specification share in UAE and Saudi interior applications as green building standards tighten solvent-content thresholds. Paint and coatings distributors in Dubai and Riyadh expand adhesive sales alongside decorative product lines.
- Solvent-Based:Polyurethane and epoxy systems retain dominance in exterior structural grades where moisture-cure speed proves critical. Saudi Building Code maintains certification pathways for these high-performance categories.
- Hot Melt:EVA and polyolefin formulations serve packaging and assembly applications with rapid set times and clean processing.
- Pressure Sensitive:Tapes and labels for consumer and industrial applications require less technical specification than structural grades.
Water-based platforms are expanding most quickly in interior commercial construction. Solvent-based chemistry defends structural exterior positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's megaproject pipeline anchors procurement volume across the Middle East & Africa adhesives and sealants market. SFDA and Saudi Building Code authorities enforce structural certification requirements that favor established compounders with tested product portfolios. Construction activity concentrates in Riyadh, Jeddah, and the Red Sea coast.
Saudi Arabia
NEOM and Red Sea developments generate concentrated demand for certified structural bonding systems. SFDA enforces VOC emission thresholds below 50 g/L for interior commercial applications. Riyadh and Jeddah host regional compounding facilities supplying specification-grade polyurethane systems to gigaproject procurement desks.
United Arab Emirates
Green building mandates in Dubai and Abu Dhabi tighten solvent-content thresholds for interior-grade products. MOHAP and local municipality codes align with international sustainability benchmarks. Dubai's manufacturing zone anchors localized production serving facade and waterproofing specifications across Gulf markets.
South Africa
ECHA REACH-equivalent frameworks shape import compliance for specialty silicone intermediates. The country's national chemical regulator enforces registration requirements for formulated polymer systems. Industrial clusters in Gauteng and Western Cape concentrate automotive and electronics adhesive demand.
Kenya
Infrastructure investment in transportation and building envelopes drives cost-optimized sealant procurement. BSI-aligned building product standards govern import quality and local formulation requirements. Nairobi anchors distributor networks bridging European and Asian supply to East African construction markets.
Egypt
New administrative capital development and Suez Canal zone expansion create construction adhesive demand. National building code authorities implement performance certification for structural bonding applications. Cairo-Alexandria corridor concentrates manufacturing and distribution capacity serving North African markets.
Middle East & Africa Adhesives and Sealants Market Competitive Landscape
Global majors compete with regional champions across specification intensity and technical service capability. Market structure consolidates around chemistry platforms with Saudi Building Code and UAE green building certification pathways. Three archetypes dominate: European-headquartered formulation specialists, Gulf-based regional compounders, and Asian import suppliers. Capacity expansion in Dubai and Jeddah compresses lead times, while strategic partnerships with main contractors secure approved vendor list positions.
Among European-headquartered specialists, Henkel AG & Co. KGaA and Sika AG occupy positions anchored by regional compounding infrastructure. Henkel exemplifies the certified structural adhesive supplier archetype through its technical service networks. Sika represents the localized manufacturing model with Dubai-based production serving East African markets. Dow sits within the chemistry innovation tier, competing on silicone platforms tailored to desert climate exposure. These three companies illustrate how global technology access combines with regional compliance capability to secure megaproject specification.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| Dow |
| Arkema Group |
| H.B. Fuller Company |
| 3M Company |
| ITW Performance Polymers |
| Huntsman International LLC |
| Pidilite Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Polyol and isocyanate feedstock costs transmit through Saudi and UAE compounding facilities into three distinct pricing tiers for specification-grade polyurethane systems. SFDA certification requirements and Saudi Building Code structural-adhesive approvals stratify procurement across premium certified grades, standard commercial formulations, and economy import alternatives.
Pricing Analysis
Input-cost pass-through from petrochemical derivatives governs formulated product pricing across Gulf markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from crude-linked polyol volatility compressing margin visibility for regional compounders. Contractor procurement through approved vendor lists shows lowest price sensitivity, while East African distributor channels exhibit highest cost elasticity.
Supply Chain Analysis
SFDA and Saudi Building Code certification requirements gate supply access to Saudi gigaproject procurement desks, compressing qualified supplier pools. Manufacturing concentrates in Saudi Arabia, UAE, and South Africa, with raw material dependencies on Asian silicone intermediates and European epoxy hardeners. Single-source vulnerability runs through concentrated isocyanate import channels from Northeast Asia. Distribution runs through nominated-supplier arrangements on major infrastructure packages and specialized chemical distributors bridging supply to sub-Saharan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East & Africa adhesives and sealants market functions as a stable compounder anchored by Saudi Arabia's decade-long megaproject construction pipeline. Infrastructure investment intensity across Gulf Cooperation Council states generates recurring procurement cycles for certified structural bonding systems.
For Market Incumbents: Deploy technical service network expansion to defend specification control against emerging Asian import competitors. Deepen backward integration into polyol compounding within Jeddah and Dubai manufacturing zones. Invest in Saudi Building Code pre-certification pipelines to compress approval timelines for new product introductions.
For New Entrants and Emerging Players: Capture underpenetrated demand in Ethiopia and Tanzania infrastructure corridors through cost-optimized sealant systems. Target East African distributor networks as the most penetrable channel given limited regional manufacturing scale. Pursue BSI-aligned building product registration in Kenya as a beachhead for multi-market expansion.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity intersects with tightening SFDA certification requirements. The five-to-ten year viability window favors regional compounders with established Saudi Building Code approval pathways. Acquisition target archetype: mid-cap UAE or Saudi manufacturers with tested product portfolios and technical service capabilities. Monitor ECHA REACH-equivalent harmonization progress across South Africa and Kenya as inflection indicator for multi-market registration economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive supply of isocyanate derivatives reduces crude-linked margin volatility for Gulf compounders. |
| Saudi Building Code Pre-Certification Investment | Accelerated SFDA approval timelines secure first-mover positioning on NEOM and Red Sea procurement desks. |
| East African Distributor Network Expansion | Nairobi-based distribution bridges European and Asian supply to Ethiopia and Tanzania infrastructure projects. |
| Hybrid Polymer Platform Development | MS polymer formulations combine silicone weathering with polyurethane strength for NEOM facade specifications. |
| Water-Based Technology Transition | Acrylic emulsion capacity addresses UAE green building mandates tightening interior VOC thresholds below 50 g/L. |
Research Methodology
Multiple input streams — primary interviews with formulation chemists and procurement managers at Saudi gigaproject developers, secondary validation through customs trade data and Saudi Building Code regulatory filings, and technical specification reviews — were reconciled to construct market estimates. Plant managers at UAE compounding facilities, distribution channel partners across Nairobi and Johannesburg, and technical R&D directors at regional adhesive manufacturers provided operational perspective. Bottom-up volume builds across chemistry platforms and top-down cross-checks against construction sector spend data ensured triangulation integrity.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry platform, application intensity, technology type, and regional regulatory cluster. CAGRs were derived from construction sector procurement cycle analysis and megaproject pipeline tracking. Feedstock cost indices for polyol and isocyanate derivatives, plus SFDA certification timeline data, informed trajectory assumptions.
Petrochemical feedstock volatility, Saudi Building Code amendment cycles, and East African currency instability are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about sustained Gulf infrastructure investment and regulatory harmonization progress. A model refresh is warranted upon material change in Saudi gigaproject execution schedules or SFDA structural-adhesive certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market