
 Elastomeric Couplings Market | 2026-2036
Elastomeric Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Couplings Market Analysis
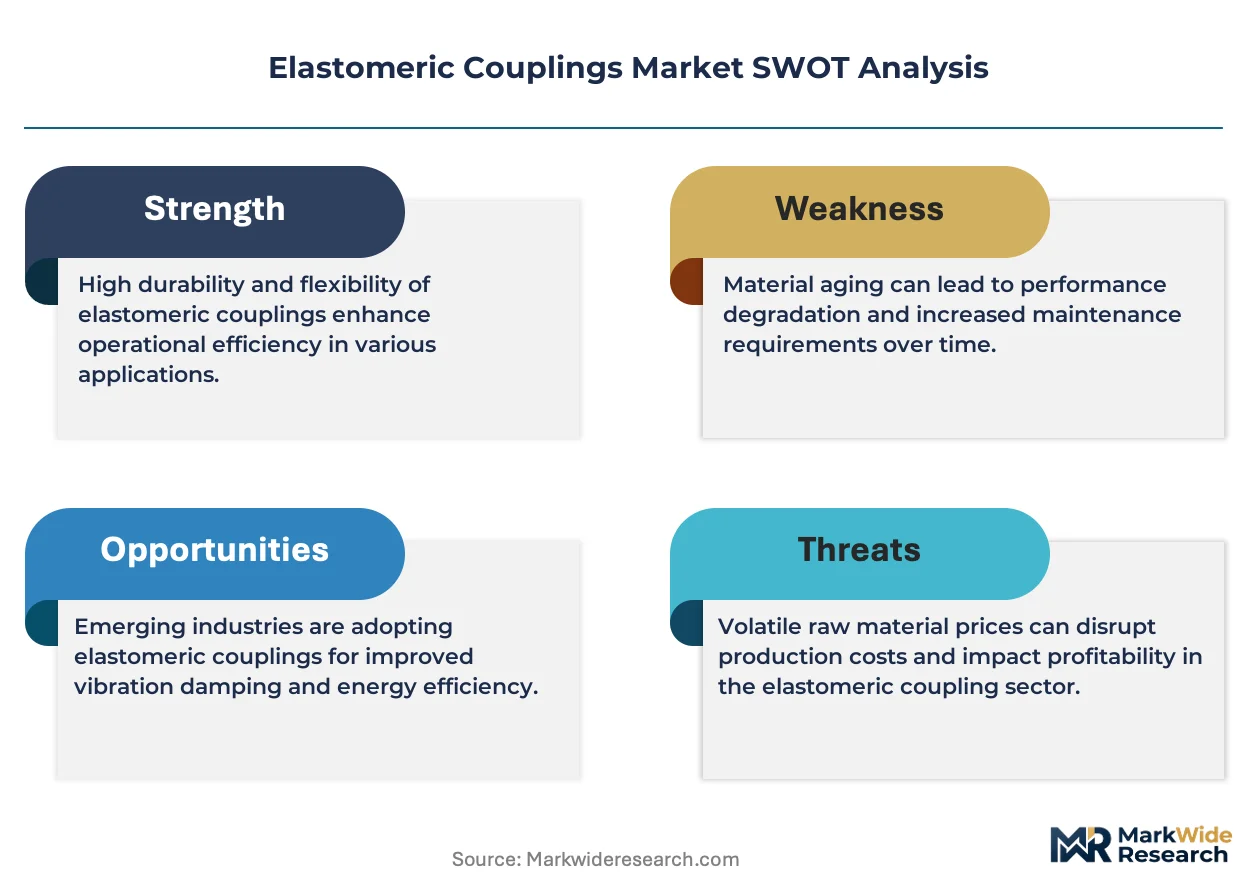
The EU Green Deal is consolidating demand around low-friction, energy-efficient power transmission components across European heavy industry. SKF leverages its integrated bearing-coupling portfolio to anchor premium positioning in Nordic wind turbine OEM supply chains. KTR Systems GmbH specializes in modular polyurethane jaw couplings that dominate German automotive conveyor systems. Rexnord Corporation competes through foundry-to-finish vertical control over cast iron hubs and bonded elastomer elements in North American food processing.
Elastomeric couplings are torsional-flexible mechanical devices comprising a metallic hub assembly with an interposed elastomeric spider or sleeve, typically molded from polyurethane, silicone, or neoprene in hardness ranges of 80-98 Shore A, engineered to transmit torque while accommodating angular, parallel, and axial shaft misalignment. Their primary industrial purpose centers on protecting driven equipment from shock loads, dampening torsional vibrations, and extending bearing life in rotating machinery trains. Flexible couplings occupy the largest revenue share due to universal deployment across pump and compressor skids, while torque limiter couplings represent the fastest-expanding category as semiconductor fabs and battery gigafactories specify overload protection for precision servo drives. Polyurethane material grades command margin premiums over natural rubber variants because of superior abrasion resistance and broader operating temperature windows.
The EPA enforces stationary source efficiency standards that compel US process industries to specify couplings with verified torsional damping coefficients, while REACH restricts certain aromatic amine curatives in EU-sourced elastomer compounds, forcing reformulation of legacy neoprene spiders. China's GB standards under SAMR mandate fatigue-test documentation for couplings deployed in coal-handling and cement applications. Stakeholders must monitor divergence between regional material compliance regimes and assess captive molding capacity against outsourced elastomer supply vulnerability.
Market Dynamics
The EU F-Gas Regulation and parallel industrial efficiency mandates across Asia are forcing material transitions from conventional rubber to high-performance polyurethane compounds, compressing legacy supplier margins while rewarding compounders with captive polymer science capabilities.
Growth Catalysts
- Polyurethane compound advances:Superior abrasion resistance and broader operating temperature windows are displacing neoprene in precision motor systems across German automotive conveyor networks.
- China's GB standards under SAMR:Mandatory fatigue-test documentation for coal-handling and cement applications is filtering out uncertified suppliers and consolidating procurement toward documented manufacturers.
- Battery gigafactory expansion:Torque limiter coupling specifications for overload protection in precision servo drives are accelerating across semiconductor and EV cell manufacturing corridors.
Market Restraints
- REACH aromatic amine restrictions:Legacy neoprene spider reformulation requirements are extending product recertification timelines by 12-18 months for EU-sourced elastomer compounds.
- Cast iron hub supply concentration:Foundry capacity limitations in specific industrial zones are creating procurement bottlenecks for bonded elastomer element assemblies.
- Metallic disc coupling substitution:Zero-backlash alternatives are capturing specification share in ultra-high-precision positioning equipment where torsional windup tolerance approaches zero.
Strategic Opportunities
- Wind turbine OEM supply chains:Integrated bearing-coupling portfolio positioning is opening specification pathways in Nordic offshore installation programs requiring 25-year service life guarantees.
- Dual carbon goals enforcement:China's MEE efficiency mandates are accelerating retrofit demand in eastern manufacturing corridor pump and compressor skids.
- Digital torque monitoring convergence:Sensor-embedded elastomeric elements combining mechanical flexure with IoT condition monitoring are creating premium pricing tiers in predictive maintenance contracts.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing Shore hardness, hysteresis, and chemical resistance across -40°C to 120°C operating windows command compensation premiums that compress R&D staffing.
- Multi-jurisdictional certification complexity:Simultaneous EPA stationary source efficiency verification, REACH substance compliance, and SAMR fatigue documentation requirements are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Couplings Market |
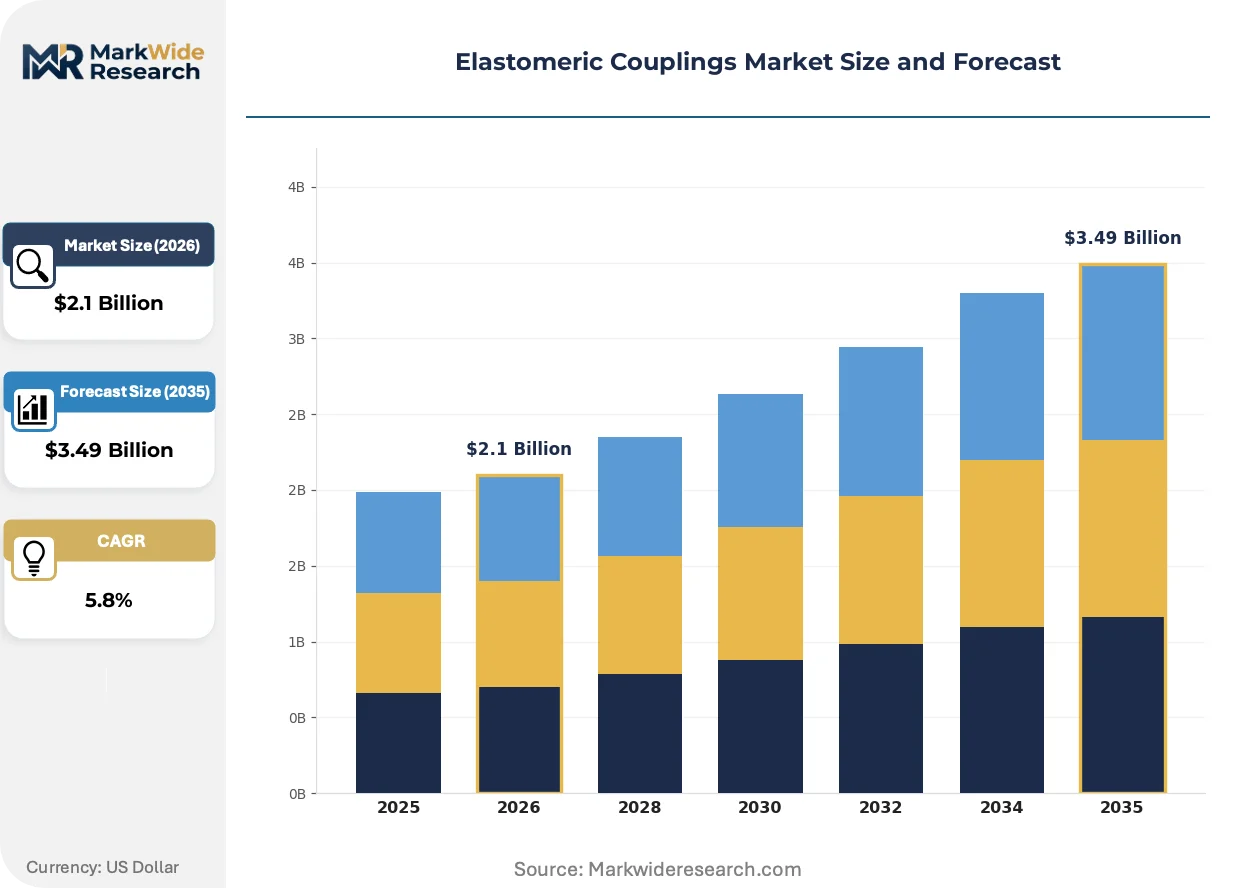
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Couplings, Rigid Couplings, Torque Limiter Couplings, Damping Couplings Material: Polyurethane, Silicone, Natural Rubber, Neoprene End User: Automotive, Manufacturing, Aerospace, Marine Application: Power Transmission, Vibration Isolation, Motor Coupling, Pump Coupling |
| Companies Covered | SKF, John Crane, Altra Industrial Motion Corp., KTR Systems GmbH, Voith GmbH, Rexnord Corporation, The Timken Company, Regal Rexnord Corporation, Lovejoy, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Couplings Market Emerging Trajectories
Material science breakthroughs and embedded sensor convergence are redefining coupling value propositions from passive mechanical components to intelligent power transmission nodes with predictive service capabilities.
High-performance polyurethane grades with tailored hysteresis characteristics are expanding into torsional vibration damping applications previously dominated by metallic spring-damper assemblies. Food processing OEMs in North America are specifying these compounds for washdown environments where corrosion resistance and thermal cycling endurance outweigh initial cost premiums. The technology is expanding into premium retrofit markets as operating cost documentation displaces first-cost procurement criteria.
The EU Green Deal's industrial efficiency mandates are compelling heavy industry procurement departments to specify couplings with verified torsional damping coefficients and lifecycle energy loss documentation. German pump manufacturers are responding by integrating third-party test certification into standard product datasheets. This regulatory pressure is compressing specification cycles for unverified legacy products while accelerating adoption of standardized efficiency rating protocols.
Buyers in precision manufacturing verticals are consolidating vendor relationships around full-train power transmission suppliers capable of integrated bearing-coupling-alignment system documentation. Distributor networks specializing in discrete component sales are losing specification influence to direct OEM engineering engagement models. This concentration is most visible in China's eastern automotive and pump assembly corridors where bulk procurement committees prioritize single-source accountability over multi-vendor price competition.
Elastomeric Couplings Market Segmentation
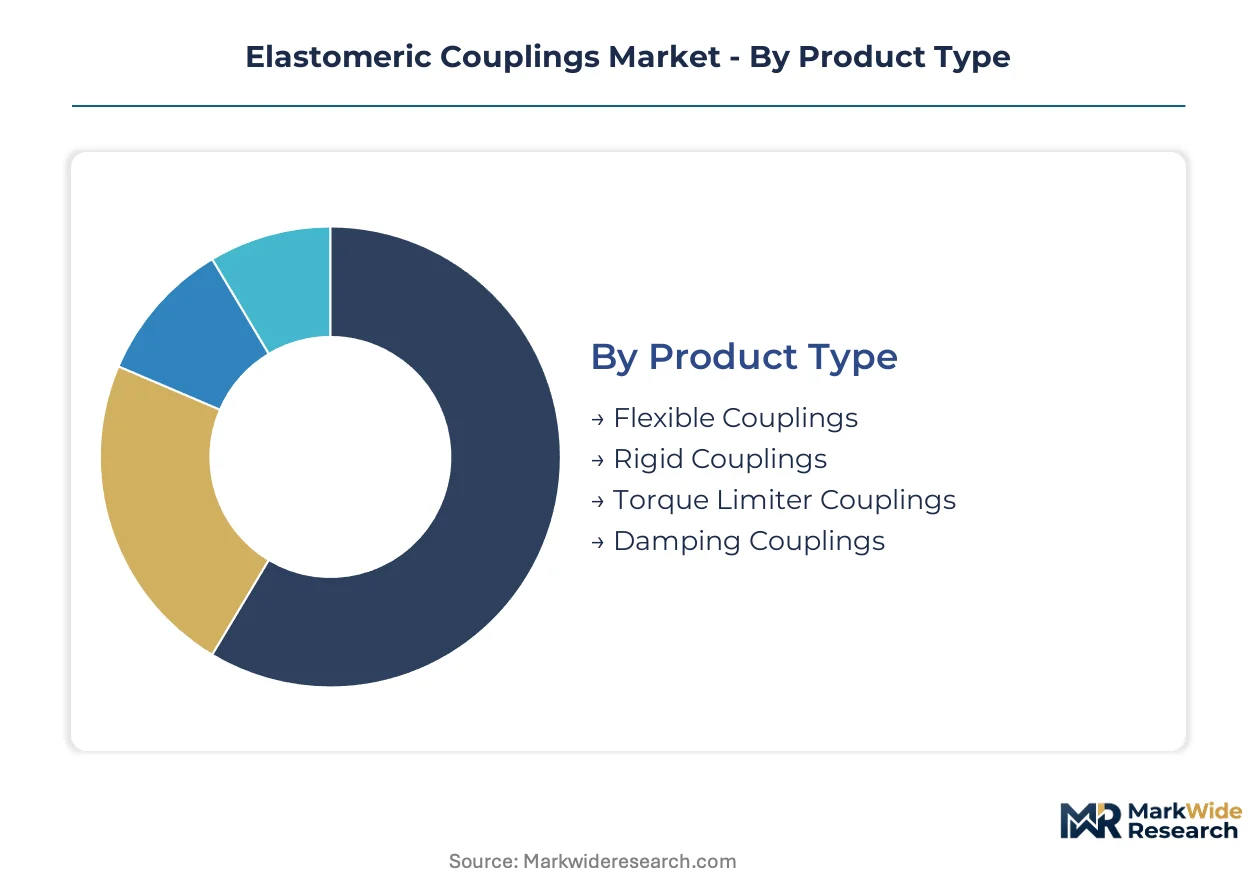
Elastomeric coupling procurement patterns diverge sharply across product architectures, compound chemistries, and end-use operating environments. Specification committees in automotive conveyor networks and semiconductor fabs weight torsional compliance, chemical resistance, and overload protection differently, fragmenting vendor positioning across these dimensions.
Product Type:
Capital intensity concentrates in torque limiter and damping variants requiring precision-machined metallic hubs and bonded elastomer elements with documented fatigue characteristics.
- Flexible Couplings:These torsional-flexible devices incorporate polyurethane or neoprene spiders between metallic hubs to accommodate angular, parallel, and axial shaft misalignment while transmitting torque. German pump and compressor OEMs specify these universally across skid-mounted rotating machinery trains for bearing life extension. Flexible couplings absorb the bulk of installed capacity; torque limiter couplings are expanding most quickly.
- Torque Limiter Couplings:Engineered with shear-pin or friction-plate mechanisms that disengage drive trains at predetermined overload thresholds to protect precision servo systems. Battery gigafactories in China's eastern manufacturing corridor specify these for EV cell assembly line protection against jam-induced damage.
- Rigid Couplings:Solid metallic sleeve or flange designs providing zero misalignment accommodation but maximum torque transmission efficiency in precisely aligned shaft systems.
- Damping Couplings:Specialized elastomeric assemblies with tailored hysteresis characteristics for torsional vibration absorption in reciprocating machinery applications.
Flexible couplings dominate procurement volume across process industries; torque limiter variants command specification share fastest in precision manufacturing corridors.
Material:
Compound selection determines operating temperature windows, abrasion resistance, and regulatory compliance trajectories across regional supply chains.
- Polyurethane:High-performance grades with Shore hardness ranges of 80-98 Shore A deliver superior abrasion resistance and broader temperature tolerance from -40°C to 120°C. EU F-Gas Regulation efficiency mandates are accelerating displacement of neoprene in German automotive conveyor networks. Polyurethane commands margin premiums; silicone is gaining specification fastest in aerospace thermal cycling applications.
- Neoprene:Legacy chloroprene compounds facing REACH aromatic amine curative restrictions requiring 12-18 month reformulation and recertification timelines for EU-sourced production.
- Silicone:Fluorosilicone and VMQ grades engineered for extreme temperature cycling from -60°C to 200°C in aerospace engine nacelle and satellite deployment mechanisms.
- Natural Rubber:Cost-competitive isoprene compounds retaining specification in low-temperature, non-aggressive environments where abrasion resistance requirements remain moderate.
Polyurethane absorbs the bulk of specification investment in new industrial installations; silicone is expanding most quickly in thermal extreme applications.
End User:
Operating duty cycles and failure-cost economics drive segmentation in coupling specification authority and procurement committee composition.
- Manufacturing:Pump, compressor, and conveyor system operators specifying vibration isolation and torque limiting across continuous-process environments. China's SAMR-mandated fatigue documentation requirements are filtering procurement toward certified suppliers in cement and coal-handling applications.
- Automotive:Powertrain and assembly line integrators requiring precision motor coupling with verified torsional damping coefficients for robotic welding and paint system applications.
- Aerospace:Airframe and engine OEMs specifying lightweight, high-temperature-capable damping couplings with 25-year service life documentation for turbine and auxiliary power unit drives.
- Marine:Propulsion shaft and auxiliary system operators prioritizing corrosion-resistant elastomer compounds in saltwater immersion environments.
Manufacturing absorbs the bulk of unit volume procurement; automotive is expanding most quickly in precision servo drive applications.
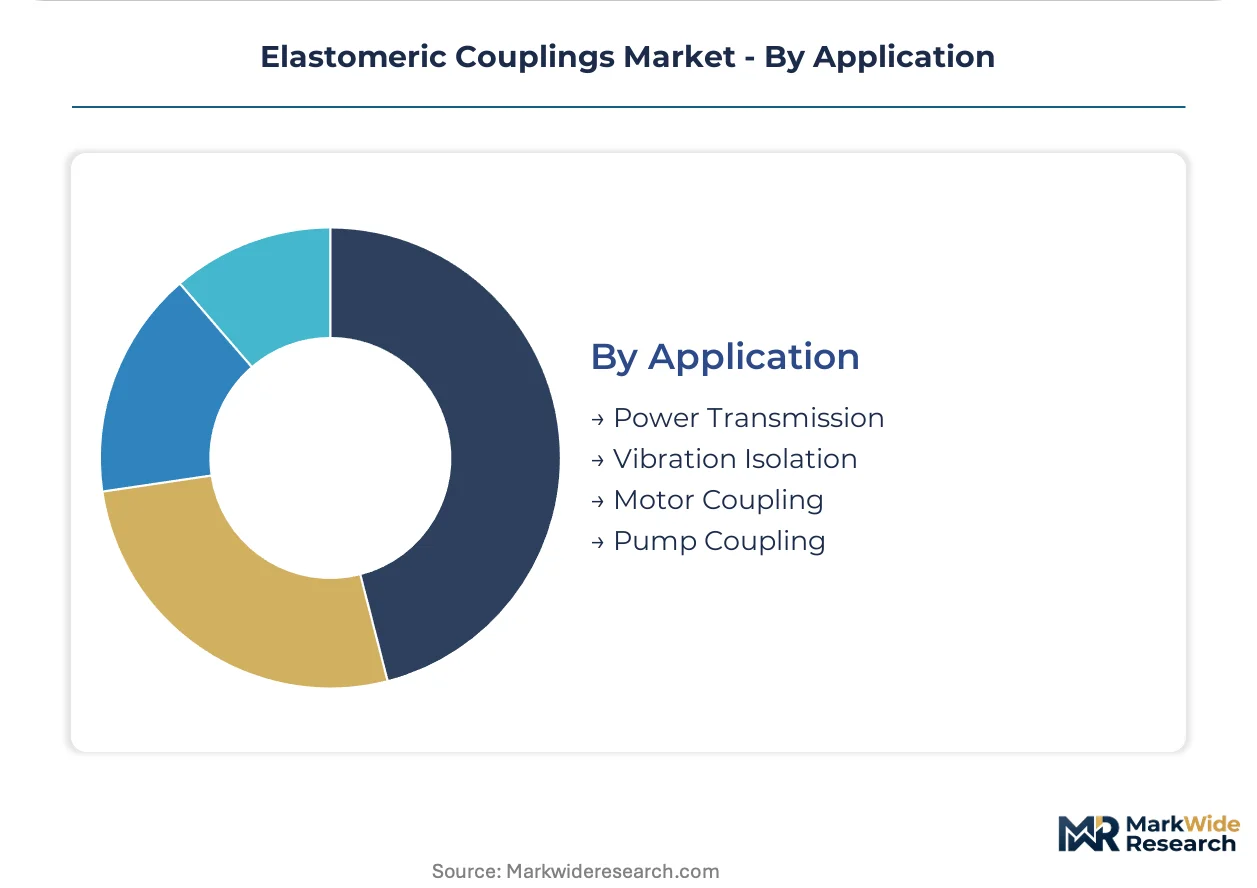
Application:
Functional positioning within rotating machinery trains determines elastomer hardness specification and misalignment accommodation requirements.
- Power Transmission:Primary torque-carrying function between prime movers and driven equipment requiring balanced torsional stiffness and damping characteristics. Wind turbine OEMs in Nordic offshore programs specify integrated bearing-coupling systems with quarter-century service guarantees.
- Vibration Isolation:Elastomeric elements engineered to decouple high-frequency torsional oscillations from sensitive downstream equipment in precision manufacturing environments.
- Motor Coupling:Servo and stepper motor shaft connections demanding zero-backlash or controlled windup characteristics for positioning accuracy.
- Pump Coupling:API and ANSI pump train specifications requiring documented torsional natural frequency separation margins to avoid resonance damage.
Power transmission absorbs the bulk of installed base maintenance spend; motor coupling is expanding most quickly in semiconductor and battery manufacturing equipment specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates the heaviest procurement density, with Shanghai-Suzhou automotive clusters and Ningbo pump assembly networks driving polyurethane jaw coupling specifications at scale.
Germany
Automotive conveyor networks in Stuttgart and Wolfsburg specify KTR Systems' modular polyurethane couplings for vibration isolation. The EU F-Gas Regulation compels material transitions from neoprene to high-performance compounds. Baden-Württemberg's precision motor manufacturers anchor premium demand for documented torsional damping coefficients.
United States
Food processing OEMs in Wisconsin and Minnesota specify corrosion-resistant elastomeric elements for washdown environments. EPA stationary source efficiency standards mandate verified torsional damping documentation. Rexnord's foundry-to-finish vertical control dominates North American bonded hub procurement.
China
Battery gigafactories in Shenzhen and Dongguan specify torque limiter couplings for EV cell assembly line protection. SAMR's GB standards mandate fatigue-test documentation for coal-handling applications. The Yangtze River Delta's cement and pump sectors filter procurement toward certified suppliers.
Japan
Semiconductor fabs in Osaka and Kyoto demand zero-backlash motor couplings for precision servo drives. METI efficiency mandates accelerate retrofit specifications in process industries. Nagoya's automotive powertrain integrators prioritize verified torsional natural frequency separation.
India
Cement plants in Gujarat and Maharashtra specify elastomeric couplings for kiln drive protection under BIS quality protocols. The country's national industrial efficiency regulator pressures material upgrades in continuous-process environments. Tamil Nadu's pump manufacturing clusters consolidate vendor relationships around documented fatigue characteristics.
Elastomeric Couplings Market Vendor Landscape
The competitive structure tilts toward integrated bearing-coupling portfolios and captive polymer compounding capabilities. Tiered positioning separates full-train power transmission suppliers from discrete component distributors. Two archetypes dominate: Nordic-German engineering houses with quarter-century service guarantees, and North American foundry-integrated fabricators with vertical control over cast iron hub supply. Capacity expansion and strategic partnerships represent the primary competitive vectors as procurement committees prioritize single-source accountability.
Within the integrated portfolio tier, SKF anchors premium positioning through combined bearing-coupling-alignment system documentation. KTR Systems GmbH exemplifies the modular polyurethane specialist archetype dominating German automotive conveyor specifications. Rexnord Corporation occupies a position among North American foundry-integrated suppliers controlling bonded elastomer element production from raw casting through finished assembly.
| Leading Market Players |
|---|
| SKF |
| John Crane |
| Altra Industrial Motion Corp. |
| KTR Systems GmbH |
| Voith GmbH |
| Rexnord Corporation |
| The Timken Company |
| Regal Rexnord Corporation |
| Lovejoy, Inc. |
| Others |
Supply Flow & Price Mechanics
High-performance polyurethane compound transitions from conventional neoprene are simultaneously compressing legacy supplier margins and rewarding captive polymer science capabilities, concentrating pricing power among compounders with in-house formulation expertise while forcing procurement committees toward documented fatigue-characteristic suppliers.
Pricing Analysis
Verified torsional damping coefficients anchor value-based pricing tiers across German pump OEM and Nordic wind turbine specification pathways. Three-tier pricing structure across premium, standard, and economy levels separates integrated bearing-coupling portfolios from modular jaw coupling specialists and commodity spider replacement suppliers. Cost compression in economy-tier neoprene variants is intensifying because REACH aromatic amine reformulation requirements extend recertification timelines. Cement and coal-handling procurement committees in China's eastern corridor demonstrate highest price sensitivity, while semiconductor fabs and battery gigafactories prioritize overload protection documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with foundry capacity concentration for cast iron hub production in specific industrial zones. Geographic supply concentration centers on Germany for precision-machined metallic hubs, China for high-volume polyurethane molding capacity, and the United States for corrosion-resistant food-grade compound formulations. Raw material dependencies draw from aromatic amine curatives, cast iron feedstock, and specialized Shore-hardness polyurethane resins. Tariff exposure on bonded elastomer element assemblies creates procurement bottlenecks during trade policy shifts. Distribution runs through direct OEM engineering engagement models that displace discrete component distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer compounding expertise scarcity props pricing premiums across the analysis window, as formulation chemists capable of balancing hysteresis and chemical resistance command compensation premiums that compress R&D staffing at non-captive suppliers.
For Market Incumbents: Anchor specification influence through integrated bearing-coupling-alignment system documentation that locks out modular competitors. Deepen backward integration into captive polyurethane compounding capacity to capture margin premiums from EU F-Gas Regulation-driven material transitions. Defend against metallic disc coupling substitution in ultra-high-precision positioning equipment by accelerating sensor-embedded element development. For New Entrants and Emerging Players: Direct-to-factory digital sales channels bypass entrenched distributor networks that have lost specification influence in China's eastern manufacturing corridor. Target torque limiter coupling white space in battery gigafactory and semiconductor fab servo drive protection, where overload documentation requirements filter out uncertified legacy suppliers. Pursue foundry partnerships in India and Southeast Asia to circumvent cast iron hub supply concentration. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated power transmission conglomerates seeking quarter-century service guarantee capabilities. Long-term viability favors compounders with captive polymer science and documented fatigue-test certification infrastructure. Watch for divergence between regional material compliance regimes as inflection signal for outsourced elastomer supply vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Compounding | Captive formulation capability captures EU F-Gas Regulation-driven margin premiums from neoprene displacement. |
| Sensor-Embedded Coupling Development | IoT condition monitoring convergence creates premium pricing tiers in predictive maintenance contracts. |
| GB Standards Fatigue Certification Investment | SAMR-mandated documentation filters procurement toward certified suppliers in cement and coal-handling. |
| Direct OEM Engineering Engagement Model | Bypasses distributor networks that have lost specification influence in bulk procurement committees. |
| Long-term Supply Agreement with Foundry Networks | Secures cast iron hub capacity against procurement bottlenecks in bonded elastomer element assemblies. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and polymer formulation chemists. Secondary sources included SAMR GB standards documentation, EPA stationary source efficiency filings, REACH substance restriction updates, and SEC 10-K disclosures from listed power transmission suppliers. Bottom-up unit demand modeling triangulated against top-down industrial machinery investment forecasts.
Segment-level granularity modeled product architecture, compound chemistry, end-use operating environment, and regional regulatory cluster across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating machinery replacement cycles and efficiency mandate retrofit schedules. Forecast inputs included wind turbine installation pipelines, battery gigafactory capacity announcements, and semiconductor fab equipment spending patterns.
Inputs from regulatory filings and customs records were available through the study window; gaps in real-time foundry capacity utilization data introduce uncertainty bands around cast iron hub supply assumptions. Forecasts reflect documented machinery investment and mandate implementation trajectories, with revision risk from tariff policy shifts and polymer feedstock price volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Injection Molding Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Industrial Drum Market
Industrial Materials
Shock Mat Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Asia-Pacific Wood Based Panel Market