
 North America Electronics Adhesives Market | 2026-2036
North America Electronics Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electronics Adhesives Market Analytics
Software-defined thermal management features in adhesive procurement is decoupling material specifications from traditional hardware-bound contracts. Henkel AG & Co. KGaA leverages its captive epoxy resin technology to dominate high-reliability automotive under-the-hood applications. Dow anchors its position through upstream silicone polymer control, while 3M differentiates via proprietary acrylic pressure-sensitive tape architectures for flexible circuit bonding.
Electronics adhesives are polymeric formulations engineered to bond, seal, or thermally manage components in electronic assemblies, typically achieving die shear strengths above 10 MPa and thermal conductivities ranging from 0.2 to 3.0 W/m·K depending on filler loading. Their primary purpose is to replace mechanical fasteners in miniaturized devices where solder alone cannot accommodate dissimilar substrates or vibration fatigue. Epoxy formulations lead in structural die-attach due to established reliability databases, while silicone adhesives capture the fastest growth in power electronics where 150°C continuous service temperatures are mandatory. UV-curable technology concentrates margin pools in medical and optical electronics, where seconds-cure throughput justifies premium positioning over thermosetting alternatives.
FDA device manufacturing regulations and EPA VOC emission standards jointly constrain adhesive formulation choices for electronics producers serving medical and industrial end markets. NHTSA automotive safety directives extend these requirements to advanced driver-assistance system modules, where outgassing specifications affect sensor optical clarity. The FCC's equipment authorization process indirectly shapes adhesive selection by validating thermal and mechanical integrity of wireless hardware designs. Stakeholders must monitor how California's Air Resources Board amendments propagate into broader North American procurement specifications.
Market Dynamics
EPA volatile organic compound limits for industrial coatings are compressing formulation timelines across Michigan, Ontario, and Guadalajara assembly corridors, forcing solvent-dependent producers toward UV-curable platforms before their existing product lines mature.
Growth Catalysts
- Electric vehicle battery module bonding:OEMs across Michigan and Ontario assembly plants are expanding adhesive specifications for thermal interface materials in pack assembly, creating specification pull for high-conductivity formulations.
- EPA VOC emission standards:The regulatory pressure is accelerating solvent-free platform adoption, with formulators capturing margin premiums on UV-curable systems that cure in seconds versus traditional thermosetting alternatives.
- Guadalajara electronics corridor scaling:EMS providers in this Mexican cluster are expanding surface-mount assembly capacity for North American OEM supply chains, concentrating demand for die-attach and underfill adhesives.
Market Restraints
- Silicone polymer supply concentration:Upstream silicone monomer production concentrates with a limited supplier base, exposing formulators to input cost volatility when capacity tightens.
- Thermal conductivity ceiling:Epoxy formulations face fundamental filler-loading limits before viscosity compromises dispensing precision in miniaturized die-attach applications.
- California Air Resources Board amendments:CARB's evolving low-VOC rules create regulatory friction as amendments propagate unpredictably into broader North American procurement specifications.
Strategic Opportunities
- Power electronics thermal management:Continuous service temperatures above 150°C in automotive and industrial inverters are opening specification windows for silicone adhesives that epoxies cannot satisfy.
- Medical electronics seconds-cure throughput:FDA device manufacturing regulations favor validated process control, where UV-curable adhesive platforms reduce work-in-process inventory and cleanroom footprint.
- Flexible circuit bonding architectures:Acrylic pressure-sensitive tape formats are capturing share in wearable and foldable device assembly where liquid dispense systems create contamination risk.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required to balance die shear strength, thermal conductivity, and outgassing specifications in automotive ADAS modules exceeds current talent pipeline output.
- NHTSA outgassing validation timelines:Sensor optical clarity requirements extend certification cycles for new adhesive platforms, compressing product development windows against OEM launch schedules.
- Legacy solder joint replacement integration:Adhesive bonding of dissimilar substrates in mixed-technology assemblies requires rework of established reliability testing protocols and failure mode databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electronics Adhesives Market |
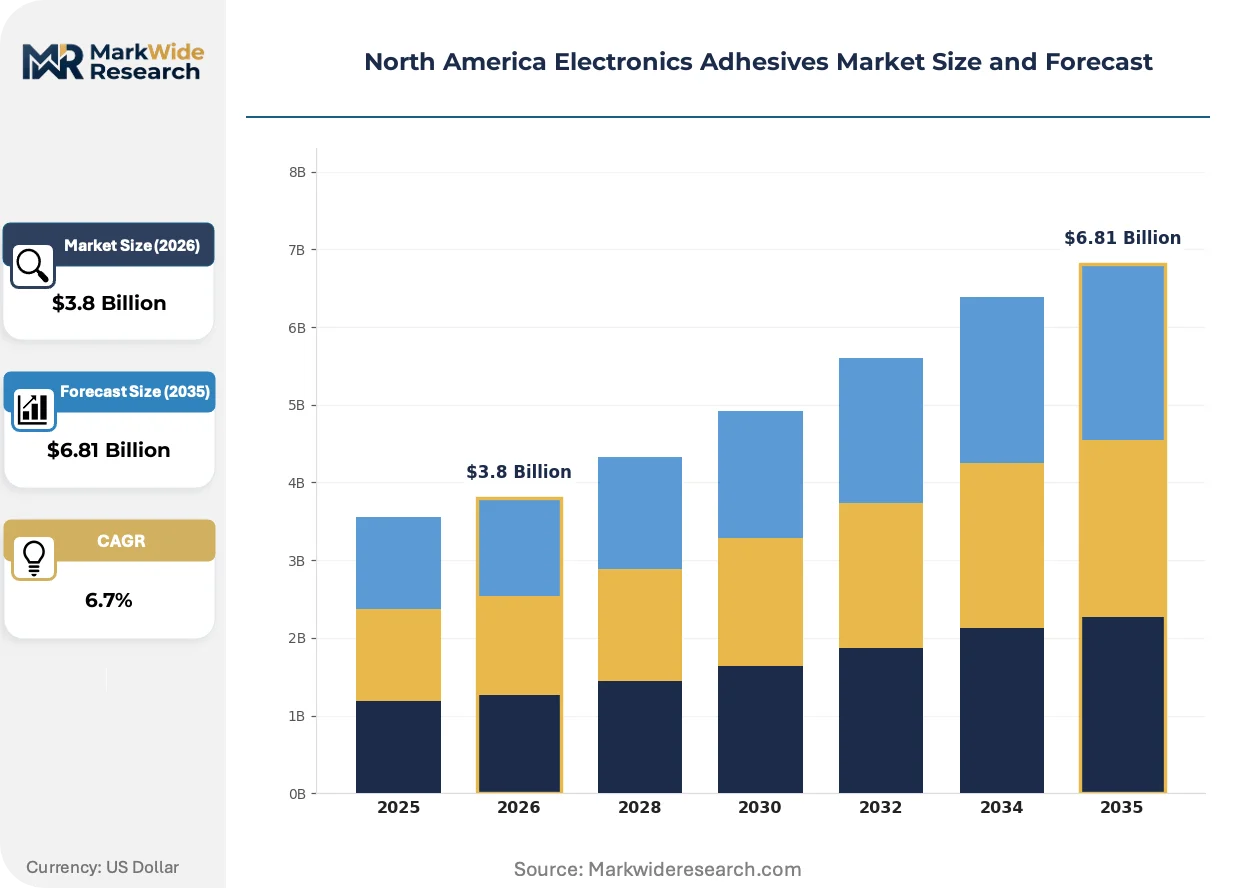
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications End User: OEMs, Aftermarket Providers, Electronic Manufacturing Services, Tier-1 Suppliers Technology: UV-Curable, Thermosetting, Pressure-Sensitive, Thermoplastic |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Dow, H.B. Fuller Company, BASF SE, Sika AG, Arkema, Huntsman International LLC, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electronics Adhesives Market Evolving Landscape
Formulation chemistry is converging with digital procurement systems, creating specification environments where material properties are validated through software-defined thermal modeling rather than hardware-bound qualification cycles alone.
Conductive epoxy formulations with silver flake loading above 80% by weight are electrifying die-attach specifications in automotive power modules, where thermal impedance targets below 0.5 K·cm²/W are mandatory. Tier-1 suppliers in Michigan and Ontario are qualifying these materials for 10-year service life validation. The technology is electrifying competitive positioning by separating formulators with captive resin synthesis from compounders dependent on merchant epoxy supply.
EPA enforcement of tightened VOC limits for industrial coatings is eliminating solvent-borne adhesive options from qualified supplier lists across medical and automotive electronics. Formulators without UV-curable platform investments face specification exclusion from OEM contracts with 2027 compliance deadlines. Medical device producers in Minnesota and Massachusetts are responding fastest, rewriting procurement specifications to require seconds-cure validation data.
Buyer concentration among North American EMS providers is compressing qualification timelines and consolidating adhesive supplier panels. Tier-2 and tier-3 formulators now face 18-month validation cycles versus 36 months historically, as Foxconn, Jabil, and Flex centralize technical sourcing decisions. This pattern concentrates most visibly in Guadalajara, where scaled surface-mount lines demand adhesive platforms with proven interoperability across multiple OEM customer specifications.
North America Electronics Adhesives Market Segmentation
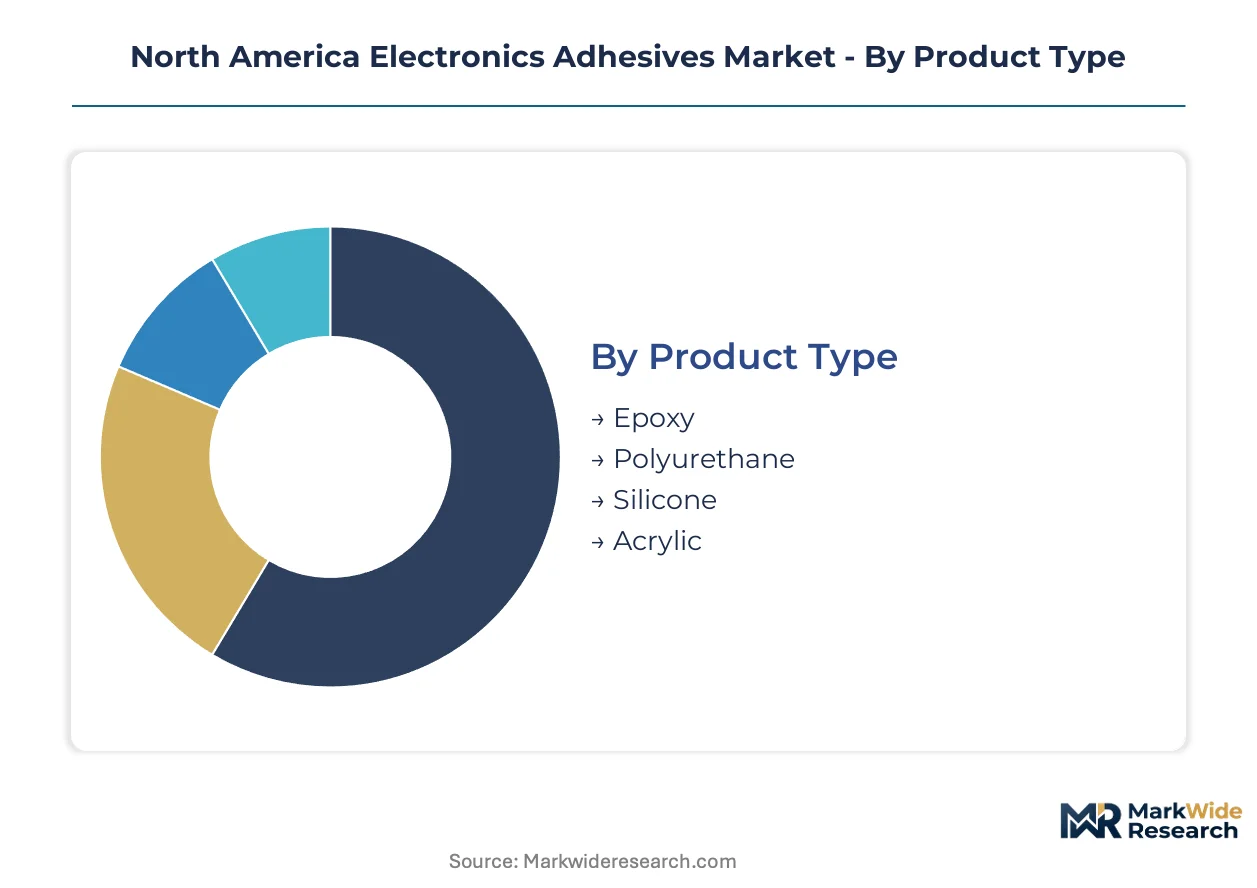
Segmentation in electronics adhesives reveals how formulation chemistry, curing technology, and procurement channel create distinct competitive arenas. Each dimension carries different margin structures, qualification timelines, and supplier concentration patterns that shape strategic positioning.
Product Type:
Supply concentration among resin producers creates tiered access to high-performance formulations, with captive synthesis capabilities separating integrated suppliers from compounders dependent on merchant feedstock.
- Epoxy:These thermosetting polymers achieve die shear strengths above 10 MPa through cross-linked aromatic structures, making them indispensable for structural die-attach in automotive power modules across Michigan and Ontario. Established reliability databases spanning decades of automotive qualification give epoxy formulators defensive moats against newer chemistries.
- Silicone:Organosilicon polymers maintain elastomeric properties through continuous service temperatures exceeding 150°C, capturing specification pull from automotive inverters and industrial power electronics where thermal cycling endurance is mandatory. Upstream monomer concentration with limited producers exposes formulators to input cost volatility during capacity tightness.
- Polyurethane:These segmented copolymers balance toughness and flexibility for potting applications in industrial controllers and outdoor telecommunications equipment.
- Acrylic:Pressure-sensitive variants dominate flexible circuit bonding for wearable devices, leveraging tackifier-modified formulations that eliminate liquid dispense contamination risks.
Today's leader: Epoxy. Tomorrow's challenger: Silicone.
Application:
End-use qualification intensity varies dramatically, with automotive and medical applications demanding multi-year validation cycles that freeze supplier panels and compress margin pressure on unqualified alternatives.
- Automotive:Advanced driver-assistance system modules and battery pack assembly drive specifications for thermally conductive formulations with outgassing profiles validated under NHTSA optical clarity protocols. OEMs in Michigan and Ontario are consolidating qualified supplier lists to three to four adhesive platforms per application.
- Consumer Electronics:Miniaturized smartphones and wearables prioritize seconds-cure throughput and thin-film dispensing precision over thermal extremes, favoring UV-curable acrylics and low-viscosity epoxies.
- Industrial Equipment:Motor drives and automation controllers specify silicone adhesives for 150°C continuous operation in factory environments with vibration fatigue concerns.
- Telecommunications:Base station and optical transceiver assembly demands low-outgassing formulations that protect signal integrity in high-frequency applications.
Automotive commands qualification rigor. Consumer electronics drives volume scale.
End User:
Procurement centralization among contract manufacturers is collapsing traditional distribution channels, with technical sourcing decisions migrating from plant-level engineers to corporate commodity managers.
- Electronic Manufacturing Services:Foxconn, Jabil, and Flex are consolidating adhesive specifications across their Guadalajara surface-mount operations, demanding platforms with proven interoperability across multiple OEM customer requirements. These buyers compress qualification timelines to 18 months versus 36 months historically.
- OEMs:Original equipment manufacturers in automotive and medical verticals retain direct adhesive specification authority for safety-critical modules, maintaining captive formulation development relationships.
- Tier-1 Suppliers:Battery module and ADAS component producers qualify adhesives as part of subsystem validation, creating indirect specification influence.
- Aftermarket Providers:Repair and refurbishment operations prioritize cost-optimized formulations with relaxed thermal performance requirements.
EMS providers concentrate volume leverage. OEMs retain specification authority.
Technology:
Curing mechanism determines capital equipment requirements, work-in-process inventory, and cleanroom footprint, creating divergent economics across manufacturing scale tiers.
- UV-Curable:Photoinitiated polymerization achieves full cure in seconds under 365nm LED arrays, reducing work-in-process inventory and cleanroom square footage for Minnesota and Massachusetts medical device producers facing FDA process validation requirements. EPA VOC enforcement is eliminating solvent-borne alternatives and accelerating UV platform adoption.
- Thermosetting:Heat-activated cross-linking dominates high-reliability automotive applications where thermal resistance and established reliability databases outweigh cure speed considerations.
- Pressure-Sensitive:Tackifier-loaded acrylics enable reworkable bonding for flexible circuits in foldable device prototypes.
- Thermoplastic:Melt-processible formulations serve niche reworkable applications where thermal debonding enables component recovery.
UV-curable gains regulatory tailwinds. Thermosetting defends reliability strongholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's automotive adhesive specifications diverge from Mexico's EMS-driven volume procurement, while the United States bridges both high-reliability validation and scaled manufacturing demand across its industrial corridors.
United States
Michigan battery module assembly and Minnesota medical device production drive divergent adhesive specifications for thermal interface and seconds-cure applications. The EPA's tightened VOC limits for industrial coatings eliminate solvent-borne formulations from qualified supplier lists by 2027. Guadalajara-serving EMS providers in Texas and Arizona are consolidating technical sourcing decisions for cross-border surface-mount operations.
Canada
Ontario automotive OEMs and Quebec industrial electronics producers anchor demand for high-temperature silicone and thermally conductive epoxy platforms. Health Canada's alignment with FDA device manufacturing regulations accelerates UV-curable adoption in Toronto-Waterloo medical technology clusters. The Ontario-Quebec corridor concentrates specification authority for battery pack adhesives serving Detroit Three supply chains.
Mexico
Jalisco's Guadalajara electronics corridor concentrates EMS surface-mount capacity expansion for North American OEM fulfillment. Mexico's environmental enforcement under SEMARNAT lags EPA stringency, creating regulatory arbitrage for solvent-dependent formulations facing US exclusion. Nuevo León automotive tier-1 suppliers are qualifying thermal interface materials for cross-border battery module assembly.
North America Electronics Adhesives Market Competitive Landscape
Top-tier vendors anchor formulation chemistry control, while mid-tier compounders compete on application engineering and regional service density. The supplier base stratifies between integrated resin producers and formulation specialists dependent on merchant feedstock. Three archetypes dominate: captive resin synthesis operators, acrylic pressure-sensitive tape architects, and silicone polymer upstream controllers. Competitive dynamics center on qualification timeline compression and UV-curable platform portfolio expansion.
Within the integrated chemistry tier, Henkel AG & Co. KGaA and Dow exemplify divergent strategic positioning through epoxy resin synthesis control versus silicone polymer upstream integration. 3M occupies a distinct pressure-sensitive tape specialization that serves flexible circuit bonding applications where liquid dispense systems introduce contamination risk.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Dow |
| H.B. Fuller Company |
| BASF SE |
| Sika AG |
| Arkema |
| Huntsman International LLC |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
Performance-grade bifurcation between automotive-qualified thermally conductive epoxies and commodity-grade industrial adhesives manifests in divergent margin structures and procurement channel configurations across Michigan, Ontario, and Guadalajara. Premium formulations command captive resin synthesis relationships and 36-month validation cycles, while economy tiers flow through merchant feedstock compounders serving EMS spot-buy programs.
Pricing Analysis
Capacity additions in Guadalajara are reshaping price floors for standard-grade die-attach epoxies as Foxconn and Jabil consolidate panel awards. Three-tier pricing structure across automotive-qualified, industrial-standard, and EMS-economy levels reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because silicone monomer supply tightness feeds input volatility downstream. EMS providers exhibit highest price sensitivity, while OEM safety-critical specifications tolerate premium positioning for validated reliability databases.
Supply Chain Analysis
Refurbishment flows for automotive battery modules and medical device returns are creating secondary adhesive demand channels that bypass primary formulator relationships. Upstream silicone monomer production concentrates in Germany, Japan, and the United States, while epoxy resin synthesis anchors in the US Gulf Coast and Western Europe. Raw material dependencies span silver flake for conductive formulations, specialty amine hardeners, and photoinitiator chemicals for UV platforms. Single-source vulnerability around silicone monomer exposes formulators to capacity allocation decisions during tightness. Distribution runs through direct OEM contracts for automotive, regional chemical distributors for industrial, and centralized EMS procurement for electronics assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EPA VOC enforcement in the United States and SEMARNAT lag in Mexico creates cost-structure differentiation for solvent-dependent formulations facing qualified supplier list exclusion north of the border.
For Market Incumbents: Cement qualification database advantages by extending automotive reliability validation into 10-year service life protocols before emerging silicone formulators achieve comparable datasets. Deepen backward integration into captive epoxy resin synthesis to defend margin position against merchant-feedstock compounders when raw material volatility spikes. Prioritize UV-curable platform capacity in Guadalajara to capture EMS procurement consolidation.
For New Entrants and Emerging Players: The premium-to-economy price gap in automotive thermal interface materials offers white-space entry for mid-tier silicone formulators with 150°C continuous service validation. Target Minnesota and Massachusetts medical device clusters with seconds-cure UV platforms that reduce cleanroom footprint against thermosetting incumbents. Pursue qualification partnerships with tier-1 battery module suppliers to bypass direct OEM validation timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap silicone formulators possessing automotive inverter qualifications and underutilized capacity in the Ontario-Quebec corridor. Long-term viability hinges on adhesive substitution for solder in power electronics packaging, a 5-10 year technology transition. Monitor EPA enforcement intensity as the inflection signal for UV-curable platform valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer | Captive upstream supply insulates formulators from Dow and Wacker capacity allocation decisions during tightness. |
| UV-Curable Platform Expansion | Seconds-cure validation opens procurement specifications at Minnesota medical device producers facing FDA process pressures. |
| Automotive 10-Year Reliability Qualification | Extended service life databases create defensive moats against emerging competitors in Michigan battery module assembly. |
| Guadalajara Technical Service Density | Localized application engineering accelerates EMS panel consolidation decisions for cross-border surface-mount operations. |
| Flexible Circuit Tape Architecture Development | Acrylic pressure-sensitive formats capture wearable assembly share where liquid dispense risks contamination. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulator R&D directors, EMS procurement leads at Foxconn and Jabil, automotive tier-1 supplier quality engineers, and EPA regulatory affairs specialists with secondary validation. Secondary sources encompassed SEC 10-K filings from listed chemical companies, ACC resin production statistics, customs trade data for epoxy and silicone imports, and NHTSA automotive safety guidance documents. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry segments.
Segment-weighting approaches distributed value estimates across epoxy, silicone, polyurethane, and acrylic chemistries, then by UV-curable, thermosetting, pressure-sensitive, and thermoplastic curing technologies, with further disaggregation by automotive, consumer electronics, industrial equipment, and telecommunications end-uses. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and OEM platform launch cycles. Forecast inputs incorporated EPA compliance timeline assumptions, EV battery production ramp rates in Michigan and Ontario, and Guadalajara EMS capacity expansion schedules.
Caveats apply where EPA enforcement intensity, silicone monomer supply disruptions, or automotive platform delays could materially shift the outlook. Forecasts reflect documented assumptions about regulatory propagation speed and qualification timeline compression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
South America Adhesives Market