
 Pressure Sensitive Adhesives (PSA) Market | 2026-2036
Pressure Sensitive Adhesives (PSA) Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Sensitive Adhesives (PSA) Market Analysis
Software-defined adhesive formulation services is expanding how suppliers monetize technical partnerships beyond resin shipments. 3M Company leverages its patent portfolio in microreplicated tape structures to sustain premium positioning in industrial bonding. Henkel AG & Co. KGaA anchors European automotive assembly lines with specialized acrylic platforms that meet OEM crash-performance specifications. Avery Dennison Corporation competes through vertical control of both adhesive coating and release liner manufacturing.
Pressure sensitive adhesives bond substrates through viscoelastic polymers that wet surfaces at room temperature without solvent activation or thermal curing, typically achieving peel strengths between 0.5 and 5 N/cm depending on formulation. The primary commercial purpose centers on temporary or permanent joining where reworkability, speed, or temperature sensitivity prohibits mechanical fasteners or reactive chemistries. Acrylic formulations dominate volume in packaging and labeling applications where clarity and UV stability command margin pools, while silicone technology leads medical and electronics segments demanding biocompatibility and thermal endurance across extreme operating ranges. Water-based technology growth reflects solvent emission restrictions in regulated manufacturing environments.
EPA volatile organic compound rules and REACH substance restrictions in Europe constrain solvent-based technology expansion while redirecting capital toward hot melt and UV curable platforms. FDA biocompatibility standards for skin-contact medical devices filter supplier qualification in North American healthcare applications. Stakeholders must monitor how dual carbon goals in China and EU Green Deal implementation reshape feedstock availability for petrochemical-derived base polymers.
Market Dynamics
Water-based and UV-curable PSA platforms are capturing capital allocation as EPA volatile organic compound enforcement tightens solvent-based production economics across industrial coating operations.
Growth Catalysts
- REACH substance restrictions:European chemical safety mandates are redirecting formulation R&D toward hot-melt acrylic systems that eliminate solvent handling infrastructure.
- Flexible electronics bonding:Display manufacturers in South Korea and Taiwan are expanding silicone PSA consumption for foldable device assembly where thermal cycling tolerance is critical.
- Medical device skin-contact applications:FDA biocompatibility standards for wearable monitors are qualifying new acrylic copolymer platforms that balance adhesion with hypoallergenic performance.
Market Restraints
- Petrochemical feedstock volatility:Crude-derived acrylic monomer costs fluctuate with naphtha cracking margins, compressing formulation margin pools during upstream price spikes.
- Silicone supply concentration:Silicone PSA base polymer production clusters in Germany and Japan create geographic chokepoints for medical-grade material procurement.
- Performance ceiling in high-temperature bonding:Acrylic platforms soften above 120°C, excluding them from power electronics thermal interface applications where silicone dominates.
Strategic Opportunities
- India packaging conversion:Food and beverage labeling demand in Maharashtra and Gujarat is outpacing domestic PSA coating capacity, creating import substitution openings for regional producers.
- EU Green Deal feedstock mandates:Bio-based acrylic acid pilot plants in the Netherlands are positioning certified renewable PSA formulations for premium consumer goods segments.
- UV-LED curing convergence:Adhesive coating lines are retrofitting mercury lamp systems with UV-LED arrays, enabling instant cure speeds that match high-throughput label printing economics.
Industry Challenges
- Formulation chemist scarcity:Viscoelastic polymer design expertise concentrates at legacy tape manufacturers, constraining specialty startup hiring pipelines.
- ISO 10993 certification timelines:Medical-grade PSA qualification protocols extend 18-24 months, delaying revenue recognition for novel skin-contact formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Sensitive Adhesives (PSA) Market |
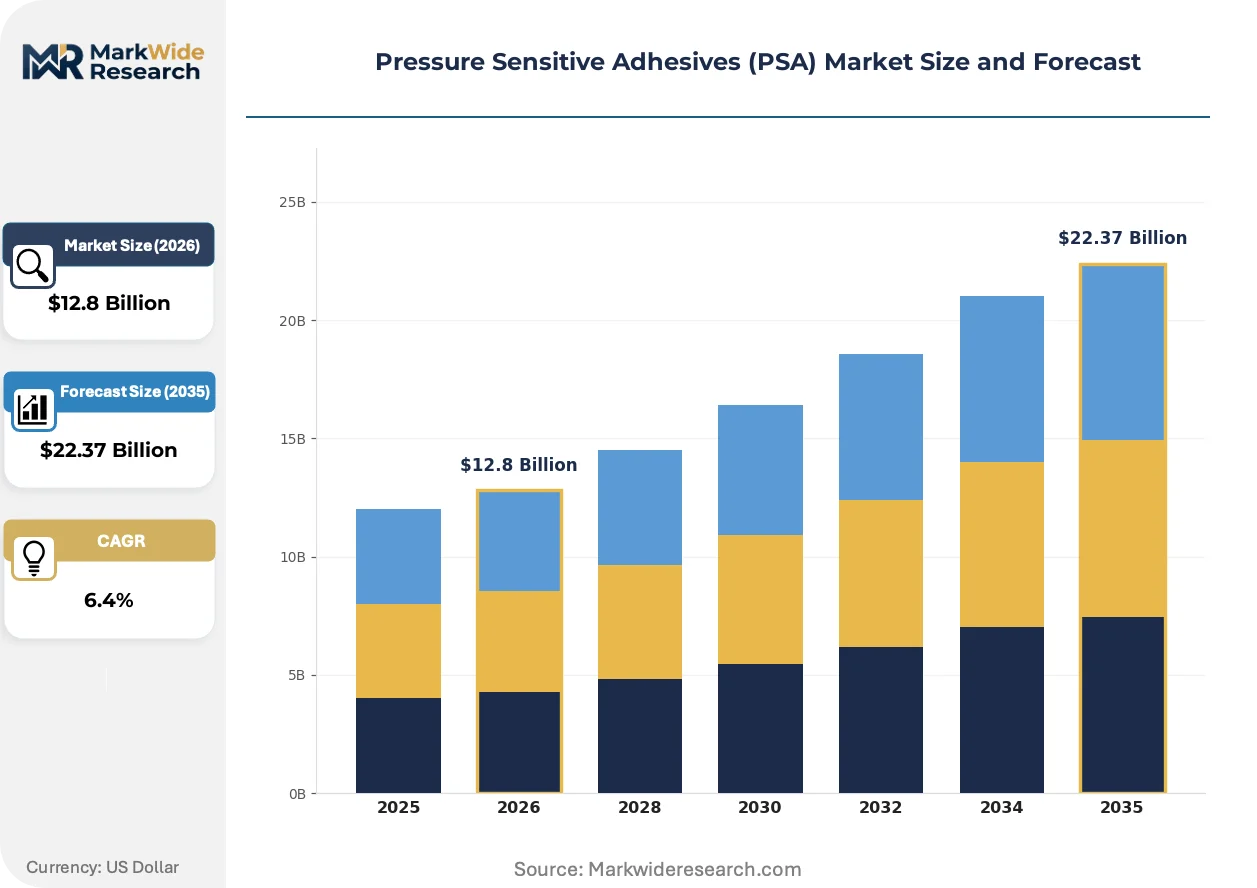
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Rubber, Silicone, Polyethylene Technology: Hot Melt, Water-based, Solvent-based, UV Curable End User: Automotive, Electronics, Packaging, Construction Application: Labeling, Tapes, Medical, Bookbinding |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Avery Dennison Corporation, H.B. Fuller Company, Arkema Group, Dow Chemical Company, Sika AG, Nitto Denko Corporation, Tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Sensitive Adhesives (PSA) Market Emerging Trajectories
Adhesive suppliers are embedding sensing and responsive functionality into PSA layers while regulatory pressure accelerates solvent elimination across coating operations.
Self-healing polymer networks are integrating dynamic covalent bonds that restore adhesion after mechanical damage. Automotive interior assemblers in Germany are piloting these materials for trim bonding where vibration fatigue occurs. This capability is integrating extended service life guarantees into OEM component supply contracts.
REACH authorization requirements for diisocyanate-containing prepolymers are forcing polyurethane PSA producers to reformulate with aliphatic alternatives. Industrial tape manufacturers serving European automotive assembly lines are absorbing 15-20% raw material cost premiums during transition periods. Medical device converters are accelerating silicone platform qualification to bypass polyurethane regulatory exposure entirely.
Consolidated buying at multinational packaging groups is compressing supplier negotiation cycles from annual to quarterly price reviews. Major label converters in North America are unbundling technical service from material supply, selecting lowest-unit-cost PSA sources and contracting formulation troubleshooting separately. This pattern is most pronounced among e-commerce logistics providers where shipping label volumes scale with seasonal demand spikes.
Pressure Sensitive Adhesives (PSA) Market Segmentation
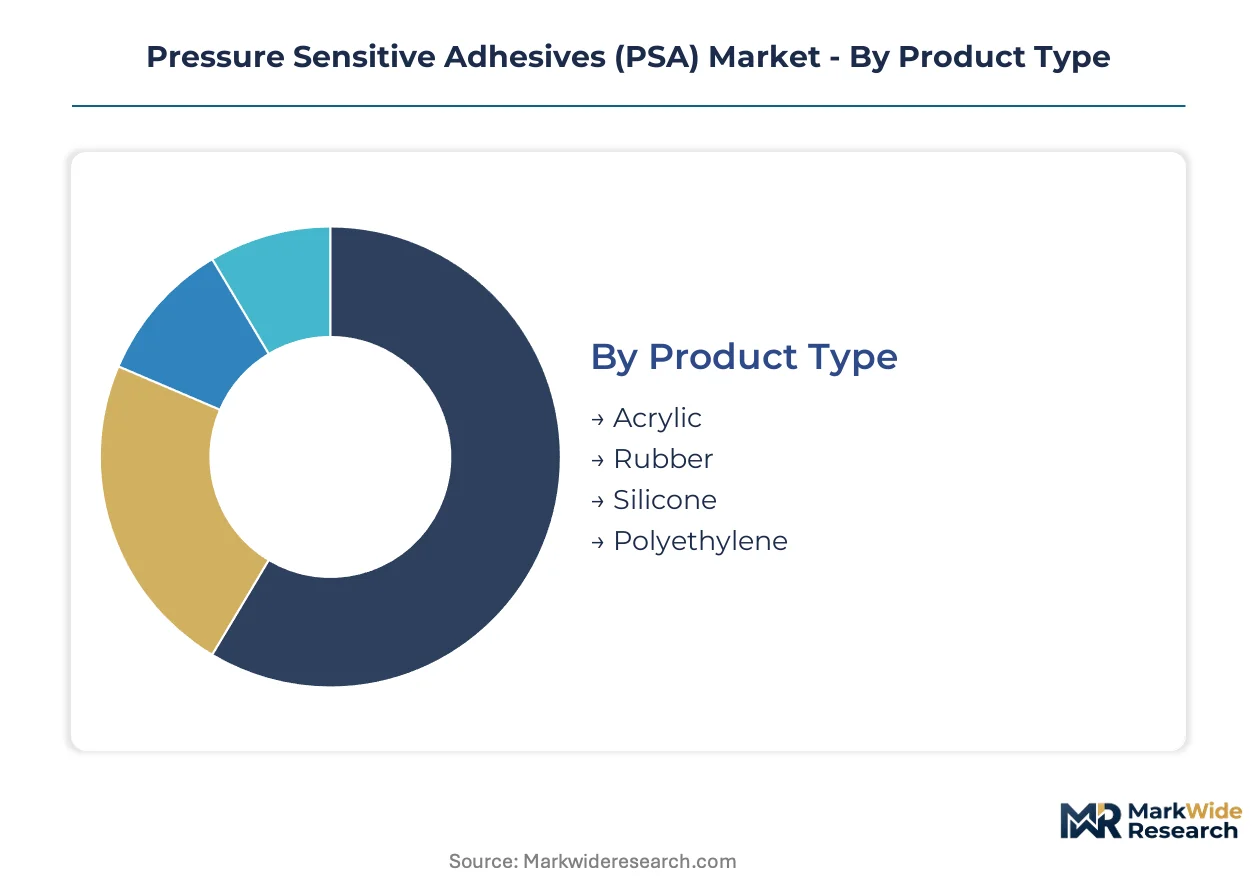
PSA formulation chemistry and curing technology create distinct margin pools that suppliers navigate through specialized production assets. Each segmentation dimension carries unique regulatory exposure and capital intensity requirements that shape competitive positioning.
Product Type:
Supply concentration varies sharply across polymer platforms, with acrylic production anchoring volume economics while silicone commands premium qualification barriers.
- Acrylic:Copolymer formulations built from butyl acrylate and 2-ethylhexyl acrylate monomers deliver optical clarity and UV resistance. Packaging label converters in Germany and the United States absorb the majority of global acrylic PSA volume, driven by shelf-life extension requirements for food contact applications. Acrylic supply chains concentrate around petrochemical cracking complexes in Texas, Rotterdam, and Singapore.
- Silicone:Polydimethylsiloxane-based adhesives tolerate continuous operating temperatures from -50°C to 200°C without degradation. Medical device manufacturers in Massachusetts and Minnesota specify silicone PSA for wearable glucose monitors and transdermal drug delivery patches, where FDA biocompatibility standards filter supplier qualification. Dow and Wacker operate the dominant silicone polymer production clusters.
- Rubber:Natural and synthetic rubber tackifiers dominate masking tape and general industrial bonding where cost sensitivity exceeds performance requirements.
- Polyethylene:Low-density polyethylene hot-melt platforms serve disposable hygiene products and temporary protective films with minimal surface energy demands.
Today's leader: Acrylic. Tomorrow's challenger: Silicone.
Technology:
Environmental compliance costs are redistributing capital across curing platforms, with water-based systems capturing stranded solvent-based capacity.
- Water-based:Emulsion polymerization eliminates volatile organic compound emissions at the coating line. EPA enforcement in Ohio and Pennsylvania automotive assembly plants has accelerated water-based PSA retrofit investments, though energy-intensive drying ovens raise operating costs versus solvent equivalents.
- Hot Melt:100% solid thermoplastic formulations eliminate drying entirely, enabling coating speeds exceeding 500 meters per minute. E-commerce logistics providers in California and New Jersey specify hot-melt PSA for shipping labels where throughput velocity determines contract economics. Henkel and H.B. Fuller control the majority of hot-melt formulation intellectual property.
- Solvent-based:Hydrocarbon carrier systems retain adhesion performance advantages on low-surface-energy substrates, though REACH authorization requirements in European coating operations constrain expansion.
- UV Curable:Photoinitiator-triggered crosslinking enables instant cure under UV-LED arrays, matching the economics of high-speed digital label printing.
Water-based and hot-melt platforms are climbing the fastest; solvent-based technology is plateauing under regulatory weight.
End User:
Application-specific certification requirements fragment demand into discrete qualification silos with limited supplier mobility.
- Automotive:Crash-performance specifications from BMW, Volkswagen, and Ford require PSA platforms that maintain adhesion through vibration fatigue and thermal cycling from -40°C to 85°C. Acrylic foam tapes dominate exterior trim bonding where mechanical fasteners compromise aerodynamics.
- Electronics:Foldable display manufacturers in South Korea specify silicone PSA for OLED bonding layers where 200,000 flex cycles demand viscoelastic recovery without creep. Thermal interface materials for power electronics represent an adjacent growth vector excluded from acrylic platforms by temperature ceiling constraints.
- Packaging:Food and beverage label demand concentrates procurement leverage at multinational converters, compressing supplier margins through quarterly price reviews.
- Construction:Weatherproof flashing tapes and vapor barrier membranes specify butyl-modified acrylics for 30-year service life guarantees.
Electronics applications are expanding most quickly; packaging retains volume dominance with thinning margins.
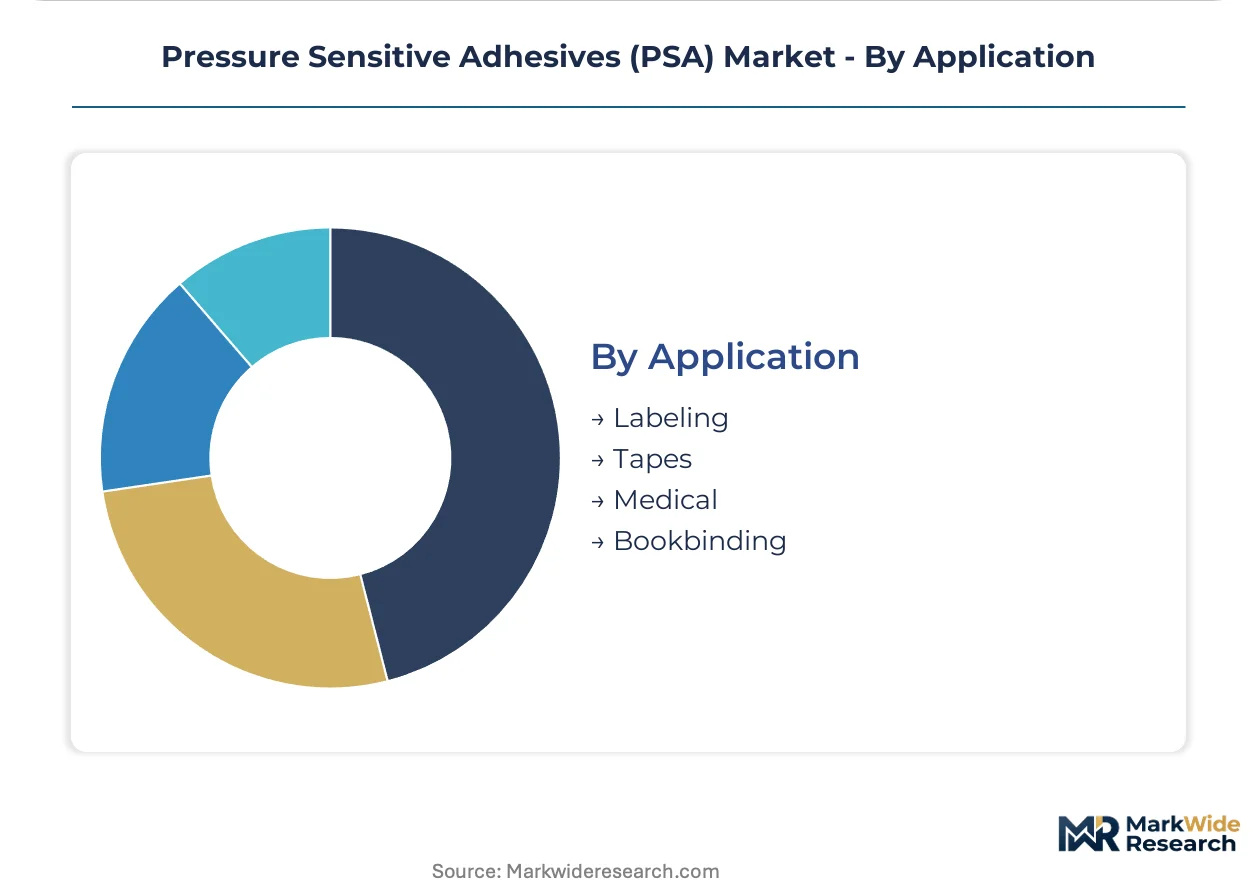
Application:
Functional requirements across bonding, protection, and information transfer create distinct formulation optimization targets.
- Labeling:Face stock adhesion, die-cutting performance, and release liner compatibility must synchronize across converting equipment from Nilpeter and Mark Andy. Direct thermal and thermal transfer coatings require distinct PSA rheology profiles.
- Tapes:Masking, electrical insulation, and structural bonding tapes span performance tiers from commodity paper backing to aerospace-grade polyimide substrates.
- Medical:ISO 10993 biocompatibility certification and FDA 510(k) clearance extend qualification timelines to 18-24 months for novel skin-contact formulations. Wearable device attachment creates demand for gentle-removal acrylic copolymers that balance initial tack with pain-free removal.
- Bookbinding:Hot-melt spine glues and pressure-sensitive tip-in adhesives serve print-on-demand and traditional publishing workflows with divergent flexibility requirements.
Medical applications command the steepest margin structure; labeling drives absolute volume consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting PSA coating capacity toward jurisdictions with lower solvent-handling compliance costs, while feedstock proximity and end-market density determine where new emulsion polymerization plants break ground.
United States
Automotive assembly plants in Michigan and Ohio consume acrylic foam tapes for lightweighting initiatives that replace mechanical fasteners. EPA volatile organic compound enforcement in Pennsylvania and Ohio coating operations has accelerated water-based PSA retrofit investments. Medical device manufacturers in Massachusetts and Minnesota specify silicone PSA for wearable glucose monitors under FDA biocompatibility standards.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg require PSA platforms that maintain adhesion through vibration fatigue and thermal cycling from -40°C to 85°C. REACH substance restrictions and ECHA authorization requirements for diisocyanate-containing prepolymers are forcing polyurethane PSA producers toward aliphatic alternatives. Industrial tape manufacturers serving Stuttgart and Munich assembly lines absorb raw material cost premiums during transition periods.
China
Domestic packaging and automotive production clusters concentrate demand through Yangtze River Delta and Pearl River Delta manufacturing belts. Dual carbon goals and MEE emission standards are reshaping feedstock availability for petrochemical-derived base polymers. Electronics manufacturers in Shenzhen and Suzhou are expanding adhesive consumption for flexible circuit bonding and display assembly.
Japan
Silicone PSA base polymer production clusters create geographic chokepoints for medical-grade material procurement serving global healthcare markets. METI industrial standards and JIS certification requirements filter supplier qualification for domestic electronics and automotive applications. Display manufacturers in Osaka and Nagoya specify silicone PSA for foldable device assembly where thermal cycling tolerance is critical.
India
Food and beverage labeling demand in Maharashtra and Gujarat is outpacing domestic PSA coating capacity, creating import substitution openings for regional producers. BIS standards and FSSAI food contact regulations are tightening material specifications for packaging-grade formulations. Converting operations in Mumbai and Ahmedabad are expanding water-based acrylic capacity to serve e-commerce logistics label demand.
Pressure Sensitive Adhesives (PSA) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation IP holders commanding premium positioning in medical and automotive qualification silos while toll coaters capture volume in commodity packaging applications. The market structure tilts toward consolidated supply in silicone and hot-melt platforms where polymer production requires specialized reactor assets, while acrylic emulsion remains more fragmented among regional coating operations. Three archetypes dominate: vertically integrated resin-to-tape manufacturers, formulation-focused specialists licensing polymer technology, and toll coaters serving private-label demand. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing backward integration into monomer supply or forward integration into converting operations.
Within the integrated multinational tier, 3M Company, Henkel AG & Co. KGaA, and Avery Dennison Corporation exemplify divergent strategic positions. 3M occupies a position anchored in patent-protected microreplicated tape structures that sustain premium industrial bonding margins. Henkel exemplifies the European automotive-focused archetype with specialized acrylic platforms meeting OEM crash-performance specifications. Avery Dennison represents vertical control across both adhesive coating and release liner manufacturing, capturing margin pools that specialists forfeit to disintegrated supply chains.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Arkema Group |
| Dow Chemical Company |
| Sika AG |
| Nitto Denko Corporation |
| Tesa SE |
| Others |
Supply Flow & Price Mechanics
Multinational packaging converters in Germany and the United States exercise consolidated procurement leverage that compresses supplier margins through quarterly price reviews rather than annual negotiations. This buyer concentration forces acrylic PSA producers into volume-based contract structures where technical service bundling once captured premium positioning.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for water-based acrylic emulsions as regional coating lines expand to serve e-commerce logistics label demand. Three-tier pricing structure across medical-grade silicone, automotive-certified acrylics, and commodity packaging formulations separates qualification-intensive segments from volume-driven tiers. Cost compression in standard-grade packaging adhesives is intensifying because consolidated buyers unbundle technical support from material supply. Food and beverage label converters in North America demonstrate highest price sensitivity, while medical device manufacturers in Massachusetts absorb premiums for ISO 10993-certified silicone platforms.
Supply Chain Analysis
Freight cost differentials between Asian manufacturing clusters and European coating operations favor regional production footprints for water-based emulsions with high water content. Acrylic monomer production concentrates in Texas, Rotterdam, and Singapore, while silicone base polymer clusters anchor in Germany and Japan. Raw material dependencies rest on naphtha-derived acrylates, polydimethylsiloxane feedstocks, and specialty tackifier resins. Single-source vulnerability in medical-grade silicone procurement creates geographic chokepoints for FDA-qualified formulations. Distribution runs through toll-coating networks that convert bulk adhesive into finished tape and label products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PSA market functions as a stable compounder where regulatory-driven solvent elimination perpetually redirects formulation R&D spending toward compliant platforms. Electronics bonding applications in foldable displays and power thermal interfaces sustain above-trend growth vectors.
For Market Incumbents: Anchor defensive positioning through captive supply of acrylic monomer feedstocks in Texas and Rotterdam to offset petrochemical price volatility. Deepen ISO 10993 certification pipelines for silicone platforms to preempt polyurethane substitution risks from REACH diisocyanate restrictions. Prioritize hot-melt capacity additions in India to capture import substitution demand from Maharashtra packaging clusters. For New Entrants and Emerging Players: Capture white-space in UV-LED curable PSA retrofit services for European label printing lines transitioning from mercury lamp systems. Target India's domestic coating capacity gap in Gujarat and Maharashtra where food labeling demand outpaces regional supply. Lead with formulation-as-a-service models that unbundle technical troubleshooting from commodity adhesive shipments. For Investors and Strategic Acquirers: Specialty chemical conglomerates with adhesive adjacencies represent the most active acquirer category in this space. The PSA market offers five-to-ten year viability through persistent regulatory complexity that favors incumbents with compliance infrastructure. Acquisition targets should display medical-grade certification assets or hot-melt formulation IP held by Henkel and H.B. Fuller competitors. Monitor EPA enforcement intensity in Ohio and Pennsylvania as an inflection indicator for water-based retrofit capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captures margin pools from naphtha cracking volatility in Texas and Rotterdam. |
| Hot-Melt Capacity Expansion in India | Addresses import substitution demand from Maharashtra e-commerce logistics providers. |
| UV-LED Curing Line Retrofit Services | Matches instant cure economics of high-speed Nilpeter and Mark Andy label presses. |
| Medical-Grade Silicone Platform Qualification | Bypasses REACH diisocyanate exposure while serving FDA biocompatibility requirements. |
| Formulation-as-a-Service Licensing | Monetizes technical partnerships beyond resin shipments for software-defined adhesive design. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with adhesive plant managers, procurement leads at automotive OEMs, medical device regulatory affairs directors, and packaging converter operations heads. Secondary validation draws from EPA enforcement records, ECHA REACH authorization databases, SEC 10-K filings of listed chemical companies, and customs trade data for acrylic monomer flows. Bottom-up capacity modeling triangulates against top-down end-use consumption estimates.
Granularity-level modeling disaggregates volume and value across formulation chemistry, curing technology, end-use industry, and regional production hub clusters. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate automotive lightweighting content per vehicle trajectories, electronics foldable display shipment patterns, and packaging label stock conversion rates.
Petrochemical feedstock price shocks, REACH substance restriction expansions, and FDA biocompatibility standard revisions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution elasticity between solvent-based and water-based platforms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market