
 North America Epoxy Curing Agents Market | 2026-2036
North America Epoxy Curing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
North America Epoxy Curing Agents Market Analytics
The performance gap between aerospace-grade cycloaliphatic systems and commodity amine formulations is broadening across the North American supply base. Hexion Inc. leverages its integrated phenolic resin position to control upstream feedstock costs for specialty curing agent production. Huntsman Corporation anchors its regional footprint through Gulf Coast manufacturing assets that serve both coatings and composite customers. Cardolite Corporation specializes in cashew nutshell liquid-derived modifiers that differentiate its portfolio in low-VOC architectural applications.
Epoxy curing agents are chemical hardeners that crosslink epoxy resins through exothermic reactions, typically requiring precise stoichiometric ratios between amine hydrogen equivalent weight and epoxy equivalent weight to achieve target glass transition temperatures above 120°C for structural applications. The product type landscape shows aromatic amines retaining dominance in high-temperature industrial coatings while cycloaliphatic variants capture share in electrical encapsulation and LED potting where color stability matters. Application segmentation reveals composite materials as the fastest-expanding dimension, driven by pressurized hydrogen storage tanks and wind blade spar caps that demand room-temperature-curing systems with extended working times.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne coating formulations, while OSHA permissible exposure limits for amine vapors shape workplace handling protocols and personal protective equipment requirements. Health Canada's PMRA evaluates new curing agent chemistries for antimicrobial coating applications, creating a dual-track regulatory environment across the US-Canada trade corridor. Stakeholders must monitor emerging state-level green chemistry initiatives in California and New York that could preempt federal standards and reshape formulation roadmaps before the next product registration cycle.
Market Dynamics
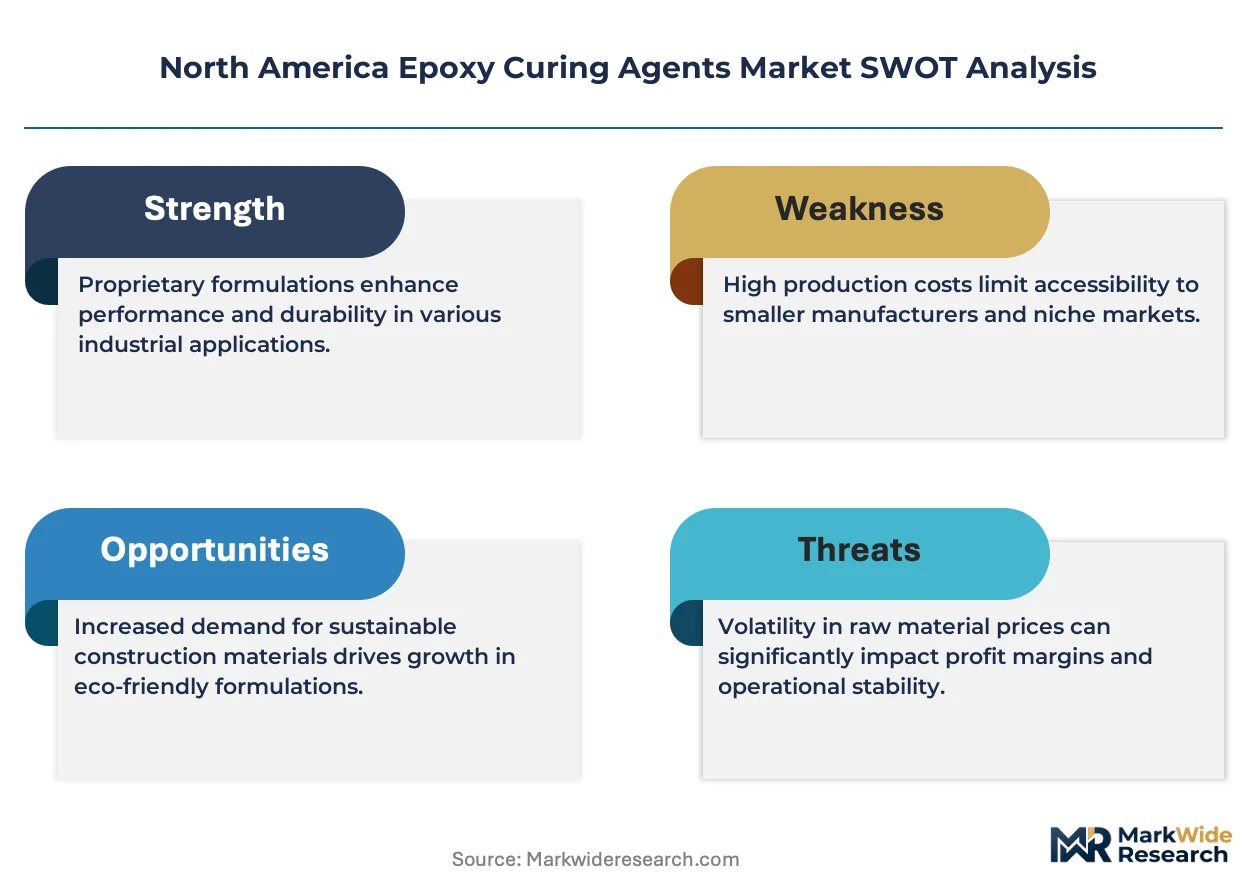
EPA restrictions on volatile organic compound emissions are compressing formulation flexibility across industrial coatings, forcing manufacturers to accelerate cycloaliphatic curing agent adoption despite higher unit costs and extended curing schedules.
Growth Catalysts
- Wind turbine blade manufacturing:The Great Plains corridor is expanding spar cap production, consuming room-temperature-curing systems with extended working times for composite layup operations.
- National Emission Standards for Hazardous Air Pollutants:EPA constraints on solvent-borne coatings are redirecting demand toward low-VOC epoxy formulations that require specialized amine hardeners.
- Hydrogen storage tank fabrication:Pressurized composite vessel manufacturing is pulling cycloaliphatic curing systems for filament-wound pressure containment structures.
Market Restraints
- Petrochemical feedstock volatility:Benzene and propylene derivative costs fluctuate with Gulf Coast refinery output, squeezing margin stability for aromatic amine producers.
- Texas supply concentration:Overreliance on the US Gulf Coast petrochemical hub creates hurricane-related production interruption exposure without redundant capacity elsewhere.
- Amine vapor exposure limits:OSHA permissible exposure thresholds necessitate costly ventilation and personal protective equipment infrastructure at formulation facilities.
Strategic Opportunities
- California green chemistry initiatives:State-level preemptive standards could establish first-mover advantage for bio-based curing agent chemistries before federal harmonization.
- LED potting applications:Electrical encapsulation demand for color-stable cycloaliphatic systems is outpacing supply in semiconductor packaging operations.
- Canada antimicrobial coatings:Health Canada PMRA evaluation tracks for new chemistries create parallel registration pathways distinct from US EPA processes.
Industry Challenges
- Stoichiometric precision requirements:Achieving target glass transition temperatures above 120°C demands specialized formulation chemists with crosslinking kinetics expertise that remains scarce.
- Dual-track regulatory compliance:Manufacturers must simultaneously satisfy EPA NESHAP and Health Canada PMRA protocols, extending product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Epoxy Curing Agents Market |
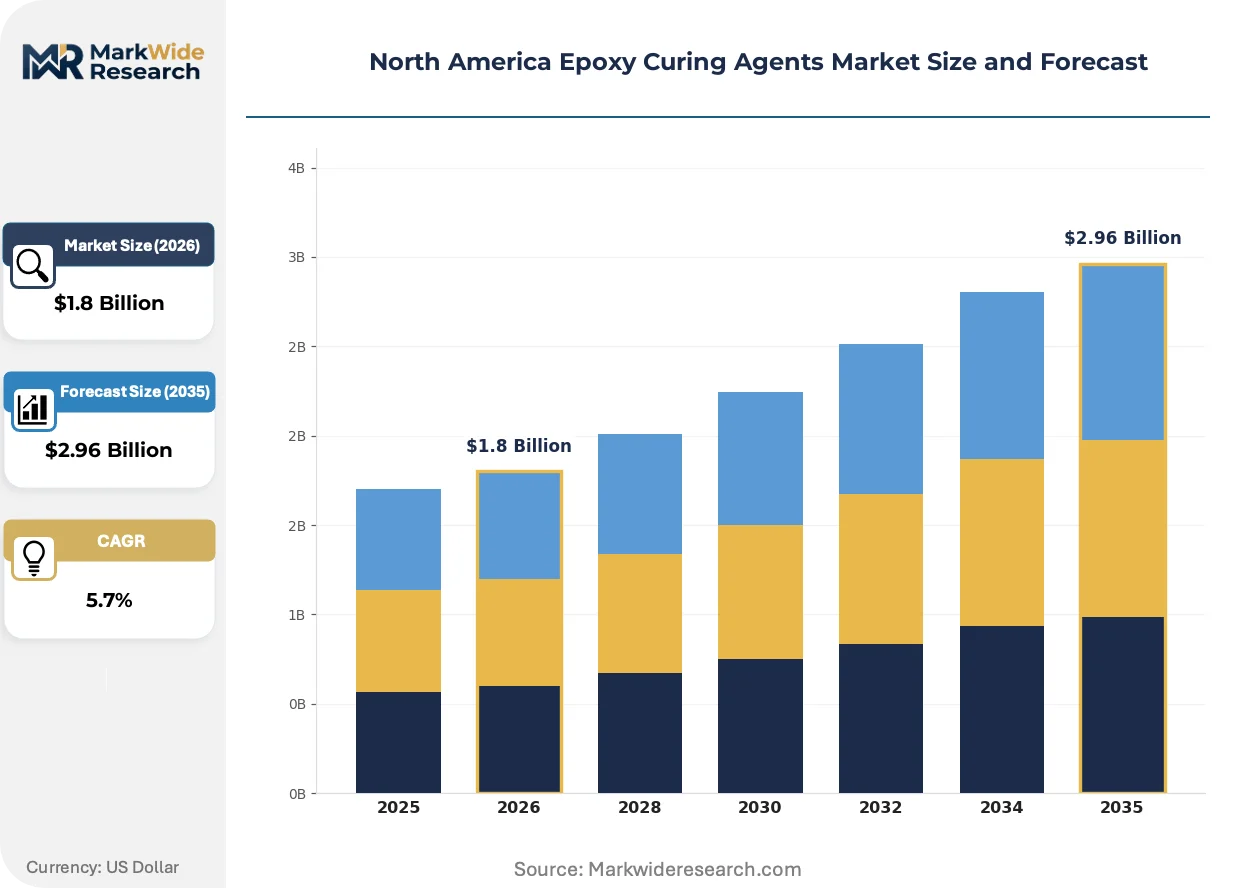
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic, Aliphatic, Cycloaliphatic, Amino Application: Coatings, Adhesives, Composite Materials, Sealants End User: Construction, Automotive, Electrical, Aerospace Curing Technology: Heat Curing, Room Temperature Curing, UV Curing, Chemical Curing |
| Companies Covered | Hexion Inc., Olin Corporation, Huntsman Corporation, Air Products and Chemicals, Westlake Epoxy, Cardolite Corporation, BASF SE, Gabriel Performance Products, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Epoxy Curing Agents Market Evolving Landscape
Formulation architectures are fragmenting as end-users demand application-specific curing profiles rather than commodity amine platforms, compressing batch sizes while multiplying SKU complexity.
Cycloaliphatic epoxy curing systems is modularizing composite manufacturing workflows across wind blade and hydrogen tank production. Turbine OEMs in the Great Plains corridor are adopting these systems for room-temperature spar cap fabrication. The technology is modularizing production scheduling by eliminating oven-curing bottlenecks that constrained throughput in legacy aromatic amine processes.
REACH-aligned substance restrictions in adjacent export markets are preemptively influencing North American formulation decisions. Coatings manufacturers serving EU-bound industrial equipment are reformulating ahead of potential US adoption. The electrical encapsulation segment is responding fastest, qualifying cycloaliphatic alternatives to bisphenol-A-derived hardeners before regulatory mandates crystallize.
Specification-driven procurement is consolidating buyer power among wind turbine OEMs and hydrogen infrastructure developers. These end-users are bypassing distributor channels to contract directly with Gulf Coast curing agent producers for dedicated capacity allocations. The phenomenon is most pronounced in Texas, where petrochemical proximity enables just-in-time delivery commitments that distant competitors cannot match.
North America Epoxy Curing Agents Market Segmentation
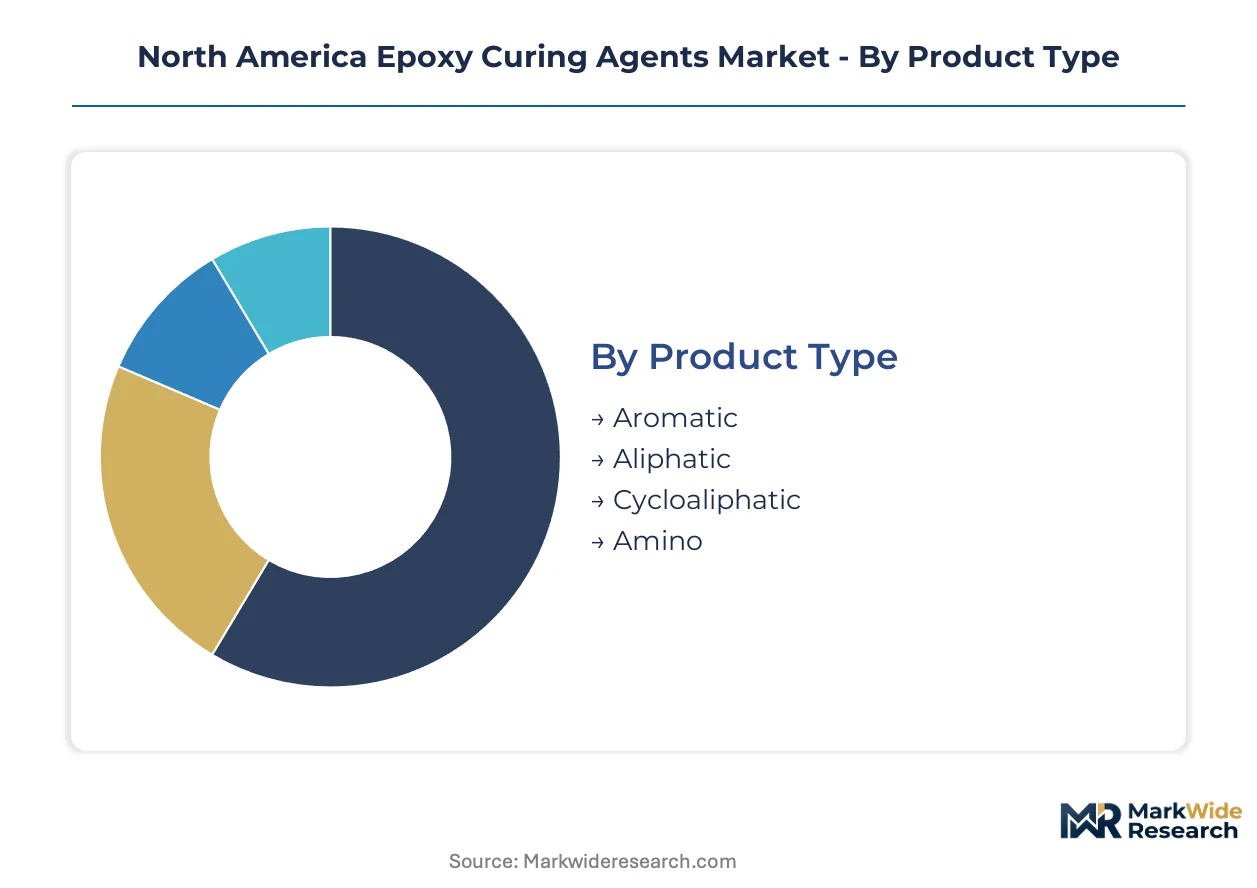
Epoxy curing agent selection in North America hinges on crosslinking kinetics, thermal performance thresholds, and regulatory compliance pathways that vary sharply across end-use specifications. Formulation architects must reconcile stoichiometric precision with supply chain concentration risks that concentrate production in Gulf Coast petrochemical corridors.
Product Type:
Integration depth varies sharply: aromatic systems dominate standalone industrial coatings while cycloaliphatic variants embed into complex composite manufacturing workflows requiring extended working times.
- Aromatic:These amine-based systems deliver glass transition temperatures exceeding 150°C through densely crosslinked polymer networks. Demand concentrates in Texas refinery maintenance coatings and marine protective systems where thermal resistance outweighs color stability concerns. EPA NESHAP compliance costs are compressing formulation flexibility for solvent-borne aromatic applications.
- Cycloaliphatic:Low-viscosity hardeners enable room-temperature curing with superior UV resistance and electrical insulation properties. Wind turbine spar cap fabrication across the Great Plains corridor consumes these systems for vacuum-assisted resin transfer molding, while LED potting operations in semiconductor packaging value their color stability over thermal cycling.
- Aliphatic:Flexible backbone structures yield tough, impact-resistant cured films for flooring and secondary containment applications.
- Amino:Modified polyamides and amidoamines balance cost-performance ratios in high-build protective coatings.
Aromatic systems lead volumes today; cycloaliphatic variants are gaining share fastest.
Application:
Cost tier stratification separates specification-grade composite materials from commodity coatings, with price differentials reflecting certification requirements and batch traceability standards.
- Composite Materials:Filament-wound pressure vessels and wind blade spar caps demand precise rheological control and extended gel times. Hydrogen storage tank fabricators in Oklahoma and Kansas specify cycloaliphatic systems for Type IV composite overwrap pressure containment, where fiber-matrix interface integrity determines safety margins.
- Coatings:Industrial maintenance and marine applications drive aromatic amine consumption despite tightening VOC regulations. Gulf Coast offshore platform operators specify high-solids epoxy systems for splash zone protection, where NACE certification requirements limit formulation substitutions.
- Adhesives:Structural bonding applications in transportation assembly require tailored cure speed and lap shear strength profiles.
- Sealants:Joint sealing and crack injection formulations prioritize elongation and substrate adhesion over structural load-bearing.
Coatings anchor current revenue; composite materials are expanding most quickly.
End User:
Customer procurement sophistication fragments the landscape: aerospace primes demand full supply chain documentation while construction contractors prioritize unit economics and availability.
- Construction:Concrete repair, flooring, and waterproofing applications consume aliphatic and modified amine systems across commercial and infrastructure projects. California green chemistry initiatives are preemptively influencing specification trends for low-emission formulations in public works contracts.
- Automotive:Composite structural components and adhesive bonding in electric vehicle battery enclosures require flame-retardant curing systems. Michigan and Ohio assembly plants specify automotive-grade epoxies with documented thermal runaway resistance for battery pack integration.
- Electrical:Transformer encapsulation and printed circuit board protection demand electrical-grade cycloaliphatic systems with defined dielectric strength.
- Aerospace:FAA-certified prepregs and structural adhesives require qualification protocols that lock in approved curing agent sources for multi-year production runs.
Construction leads absolute consumption; aerospace commands the steepest premium tier.
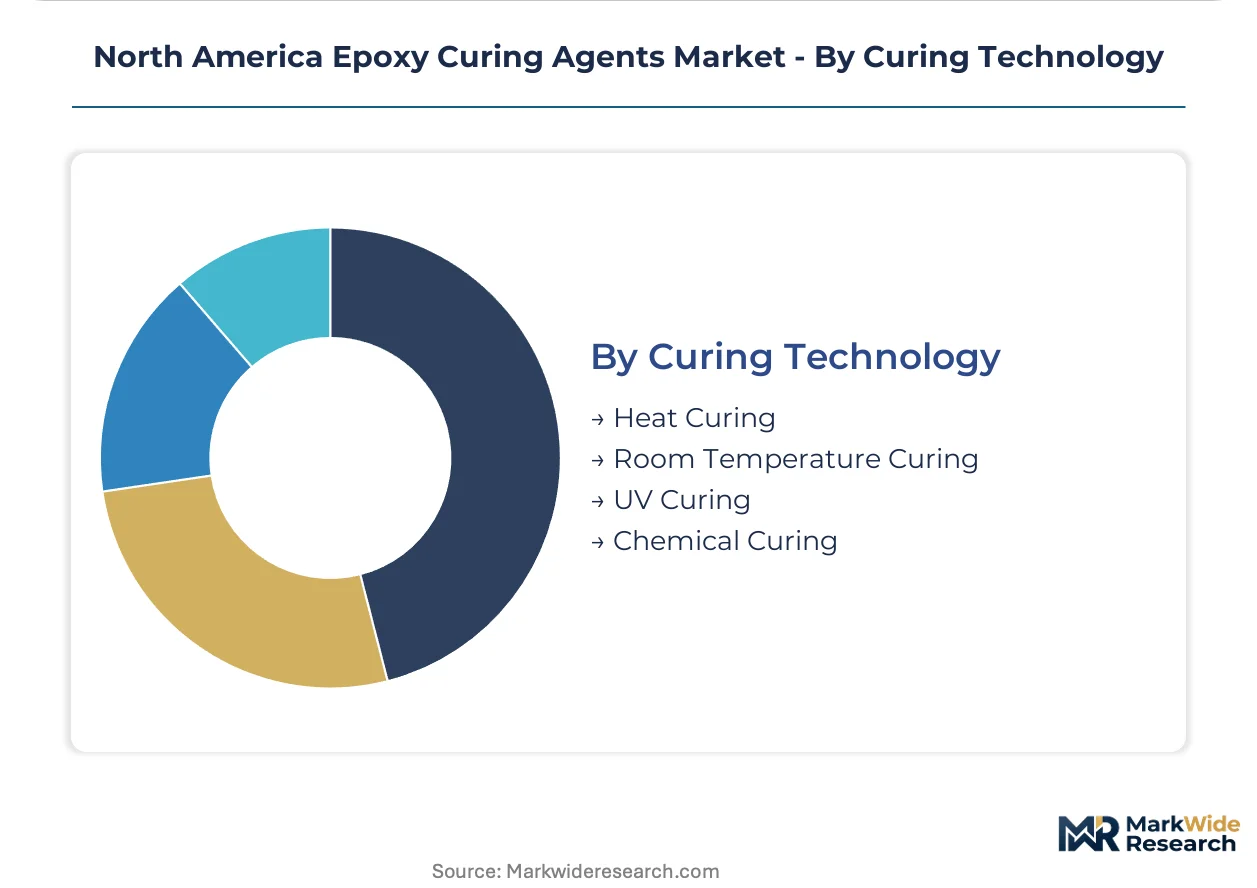
Curing Technology:
Supply concentration in Gulf Coast chemical manufacturing favors heat-curing aromatic systems with established infrastructure, while distributed wind and hydrogen fabrication pulls room-temperature alternatives.
- Room Temperature Curing:Cycloaliphatic and modified aliphatic systems enable field fabrication without oven infrastructure. Wind blade manufacturing across Iowa, Kansas, and Oklahoma relies on ambient cure schedules that eliminate capital-intensive thermal processing equipment from production lines.
- Heat Curing:Aromatic amines achieve full property development through controlled thermal ramps in factory environments. Texas and Louisiana petrochemical facilities maintain dedicated curing ovens for pipeline coating and tank lining applications where production volume justifies energy investment.
- UV Curing:Cationic photoinitiator systems serve niche electronics and graphic arts applications with instantaneous cure requirements.
- Chemical Curing:Anhydride and phenolic hardeners enable high-temperature service in specialized electrical and tooling applications.
Heat curing retains volume leadership; room temperature systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Texas and Louisiana petrochemical corridors, anchoring North American epoxy curing agent production capacity. Gulf Coast infrastructure supports both aromatic amine bulk manufacturing and cycloaliphatic specialty synthesis. Cross-border regulatory coordination between EPA and Health Canada shapes formulation roadmaps across the trade corridor.
United States
Wind turbine blade fabrication across Iowa, Kansas, and Oklahoma consumes room-temperature-curing cycloaliphatic systems for vacuum-assisted resin transfer molding. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-borne coating formulations, redirecting demand toward low-VOC amine hardeners. Houston and Beaumont petrochemical complexes maintain integrated epoxy resin and curing agent production serving continental supply chains.
Canada
Antimicrobial coating applications in healthcare infrastructure drive evaluation of novel curing agent chemistries under Health Canada PMRA protocols. The country's national chemical regulator maintains distinct registration tracks from US EPA processes, creating parallel compliance requirements. Ontario manufacturing corridors near Sarnia and Hamilton host formulation facilities serving Great Lakes industrial markets.
Mexico
Automotive assembly plants in Nuevo León and Bajío Region specify flame-retardant epoxy systems for electric vehicle battery enclosures. The country's federal environmental regulator enforces VOC emission standards that increasingly align with US EPA thresholds. Querétaro and Guanajuato industrial parks attract coating formulation investments serving North American automotive supply chains.
North America Epoxy Curing Agents Market Competitive Landscape
Top-tier vendors anchor Gulf Coast petrochemical integration, while mid-scale specialists occupy differentiated modifier niches. The supplier base stratifies across three tiers: integrated resin-curing agent producers controlling upstream feedstocks, standalone hardener manufacturers serving specification-grade applications, and regional compounders addressing commodity coatings demand. Two dominant competitive moves define current positioning: backward integration into phenolic and amine feedstocks, and dedicated capacity allocations for wind and hydrogen infrastructure OEMs bypassing distributor channels.
Within the integrated chemical producer tier, Hexion Inc., Huntsman Corporation, and Olin Corporation exemplify distinct strategic archetypes. Hexion represents phenolic resin integration models leveraging upstream control over specialty curing agent feedstocks. Huntsman anchors Gulf Coast manufacturing assets serving both coatings and composite customers through concentrated petrochemical corridor positioning. Olin occupies a scale-driven position spanning chlor-alkali derivatives into epoxy value chains. These three entities collectively illustrate how feedstock access, geographic concentration, and end-use diversification separate premium-tier suppliers from regional competitors.
| Leading Market Players |
|---|
| Hexion Inc. |
| Olin Corporation |
| Huntsman Corporation |
| Air Products and Chemicals |
| Westlake Epoxy |
| Cardolite Corporation |
| BASF SE |
| Gabriel Performance Products |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Captive phenolic resin integration at Hexion and Huntsman anchors both upstream feedstock security and pricing power across specialty curing agent tiers. This backward control insulates integrated producers from benzene derivative volatility while forcing standalone hardener manufacturers to absorb commodity cost swings.
Pricing Analysis
Bundled technical service contracts dominate specification-grade composite applications, while unbundled commodity spot transactions prevail in construction coatings. Three-tier pricing structure across aerospace-certified, industrial-grade, and economy construction tiers separates buyers by certification burden and batch traceability requirements. Cost compression in commodity aromatic amine segments is intensifying because Gulf Coast overcapacity and import competition squeeze margins. Construction contractors exhibit the highest price sensitivity due to project-based procurement and limited formulation expertise, while wind turbine OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Elevated freight costs from Texas Gulf Coast to Great Plains wind fabrication sites favor just-in-time delivery contracts over inventory-heavy distribution models. Production concentrates in the United States, Canada, and Mexico, with Texas petrochemical corridors feeding continental demand. Raw material flows draw from benzene, propylene, and cashew nutshell liquid feedstocks. Single-source vulnerability around cycloaliphatic specialty intermediates creates supply interruption exposure. Distribution runs through direct OEM contracts for composite applications and regional chemical distributors for construction coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hydrogen storage and wind blade specifications shift demand toward premium cycloaliphatic systems with extended working times and certified traceability.
For Market Incumbents: Deploy dedicated capacity allocations as the primary lever to lock in wind turbine OEM and hydrogen tank fabricator relationships before competitors replicate Gulf Coast logistics advantages. Incumbents should deepen backward integration into phenolic and amine feedstocks to defend margin position against benzene cost volatility, while accelerating cycloaliphatic R&D to meet emerging LED potting specifications ahead of regulatory mandates.
For New Entrants and Emerging Players: Begin with bio-based curing agent development targeting California green chemistry procurement preferences and Health Canada antimicrobial coating evaluation tracks. The most penetrable white space sits in cashew nutshell liquid-derived modifiers for low-VOC architectural applications, where Cardolite has demonstrated viable positioning without integrated petrochemical scale. A technical partnership route with regional construction coating formulators offers faster market entry than direct OEM qualification.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale specialty hardener producers because customer qualification protocols and EPA dual-track registration requirements create sticky revenue streams that resist commoditization. Acquisition targets should demonstrate established wind or hydrogen OEM approvals and Health Canada PMRA registration progress. The signal to watch is specification-driven procurement consolidation among Great Plains wind blade manufacturers bypassing distributor channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Feedstocks | Hexion's captive resin supply secures margin stability against benzene derivative volatility. |
| Dedicated Capacity Allocation Contracts | Huntsman anchors wind turbine OEM relationships through Gulf Coast proximity and just-in-time logistics. |
| Health Canada PMRA Registration Investment | Parallel antimicrobial coating approval tracks open Canadian healthcare infrastructure demand distinct from EPA pathways. |
| California Green Chemistry Pre-Positioning | Bio-based formulation development anticipates state-level standards before federal harmonization. |
| Cycloaliphatic R&D for LED Potting | Color-stable electrical encapsulation systems address semiconductor packaging demand outpacing current supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with epoxy formulators, wind turbine procurement directors, hydrogen tank fabricators, and Gulf Coast plant managers with secondary validation through EPA NESHAP filings, ACC industry reports, SEC 10-K disclosures, and customs trade data. Bottom-up volume builds across product type, application, and curing technology segments were cross-checked against top-down market sizing from petrochemical production disclosures and regional demand indicators.
Comparable historical periods anchored growth trajectory assumptions across the projection horizon, with segmentation modeling spanning aromatic versus cycloaliphatic grade tiers, composite versus coatings end-use industries, and room-temperature versus heat-curing technology formats. CAGRs were derived from elasticity-adjusted demand curves incorporating wind turbine installation forecasts and hydrogen infrastructure deployment timelines without specifying base or terminal years.
Several conditions sit outside the modeled scope, including hurricane-related production interruptions at Gulf Coast facilities, abrupt OSHA amine vapor exposure limit revisions, and REACH-aligned substance restrictions accelerating faster than anticipated. Forecasts reflect documented assumptions about regulatory stability and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context and stress-test for petrochemical corridor concentration risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
North America Adhesives and Sealants Market