
 North America Activated Alumina Market | 2026-2036
North America Activated Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
North America Activated Alumina Market Insights
Aftermarket service revenue for spent alumina regeneration and reactivation is narrowing as buyers shift toward longer-life formulations and captive recycling programs. BASF SE leverages its integrated catalyst manufacturing network to sustain technical service contracts across Gulf Coast refineries. Huber Engineered Materials dominates specialty fluoride adsorbent supply for municipal water districts, while Porocel Corporation anchors the regeneration services segment with facilities concentrated in the US South.
Activated alumina is a highly porous, granular form of aluminum oxide manufactured through controlled calcination of aluminum hydroxide, yielding surface areas typically exceeding 200 square meters per gram for adsorption and catalytic applications. Its primary industrial purpose centers on selective adsorption of polar molecules, fluoride ions, and moisture from gas and liquid process streams. The desiccant product category leads volume shipments due to entrenched demand from compressed air and natural gas processing infrastructure. Powder and pellet forms are gaining traction in chemical manufacturing where precise dosing and minimal attrition losses command operational priority.
EPA drinking water regulations under the Safe Drinking Water Act and state-level fluoride maximum contaminant level enforcements shape product certification requirements and procurement specifications for municipal buyers. OSHA workplace exposure limits and DOT hazardous material classifications govern handling protocols throughout the activated alumina supply chain. Stakeholders must monitor evolving PFAS treatment standards where activated alumina competes against emerging resin technologies for remediation contracts.
Market Dynamics
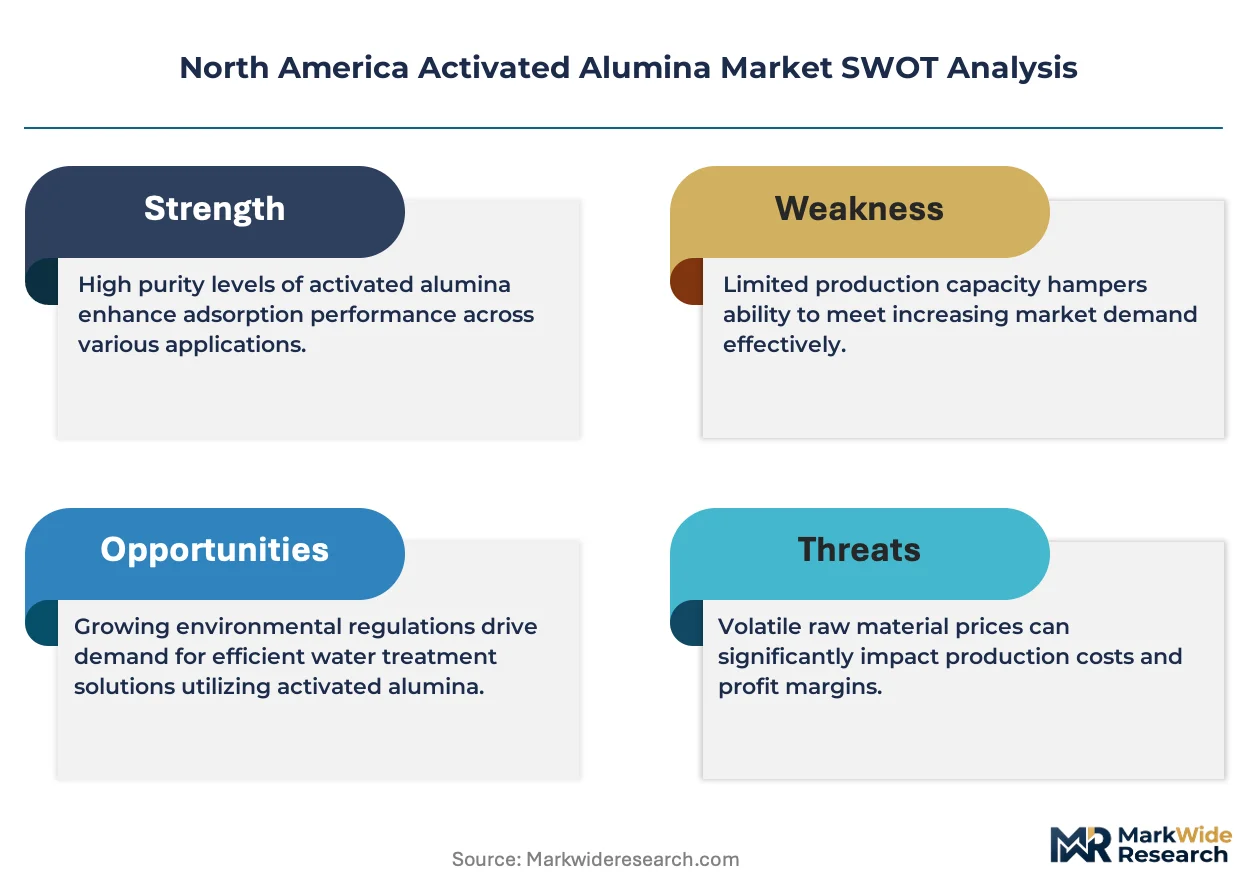
The North America activated alumina market is being fundamentally restructured by tightening EPA drinking water standards that compress compliance timelines for arsenic and fluoride removal, forcing municipal utilities toward higher-performance adsorbent formulations and integrated service contracts.
Growth Catalysts
- Safe Drinking Water Act enforcement:EPA maximum contaminant level reductions for arsenic and fluoride are mandating activated alumina deployment across municipal water treatment facilities in Texas and California.
- Petrochemical infrastructure expansion:Gulf Coast refinery and natural gas processing investments are driving desiccant demand for moisture control in compressed air and hydrocarbon streams.
- Spent media reactivation services:Captive recycling programs at industrial sites are extending product lifecycles and creating recurring revenue streams for regeneration providers concentrated in the US South.
Market Restraints
- Bauxite and caustic soda input volatility:Feedstock cost swings squeeze margin structures for domestic calcination operations dependent on imported alumina hydrate.
- Single-source supply concentration:Specialty fluoride-grade activated alumina production clusters among limited domestic manufacturers, creating procurement vulnerability for municipal districts.
- Ion exchange resin substitution:Emerging synthetic resin technologies for PFAS remediation threaten to displace activated alumina in next-generation contaminant treatment applications.
Strategic Opportunities
- PFAS treatment regulatory gap:Anticipated EPA drinking water standards for per- and polyfluoroalkyl substances position activated alumina as a bridging technology before resin systems achieve cost parity.
- Canada municipal infrastructure:Underpenetrated water treatment upgrade cycles in Ontario and Alberta provinces offer expansion terrain for US-based technical service providers.
- Digital monitoring integration:IoT-enabled adsorbent bed performance tracking is converging with predictive maintenance platforms to enable outcome-based service contracting.
Industry Challenges
- NSF/ANSI 61 certification timelines:Extended product validation periods for drinking water contact applications delay new formulation commercialization and lock in incumbent suppliers.
- Spent media hazardous classification:DOT shipping requirements for arsenic-laden alumina create logistics complexity and liability exposure for municipal operators lacking on-site regeneration capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Activated Alumina Market |
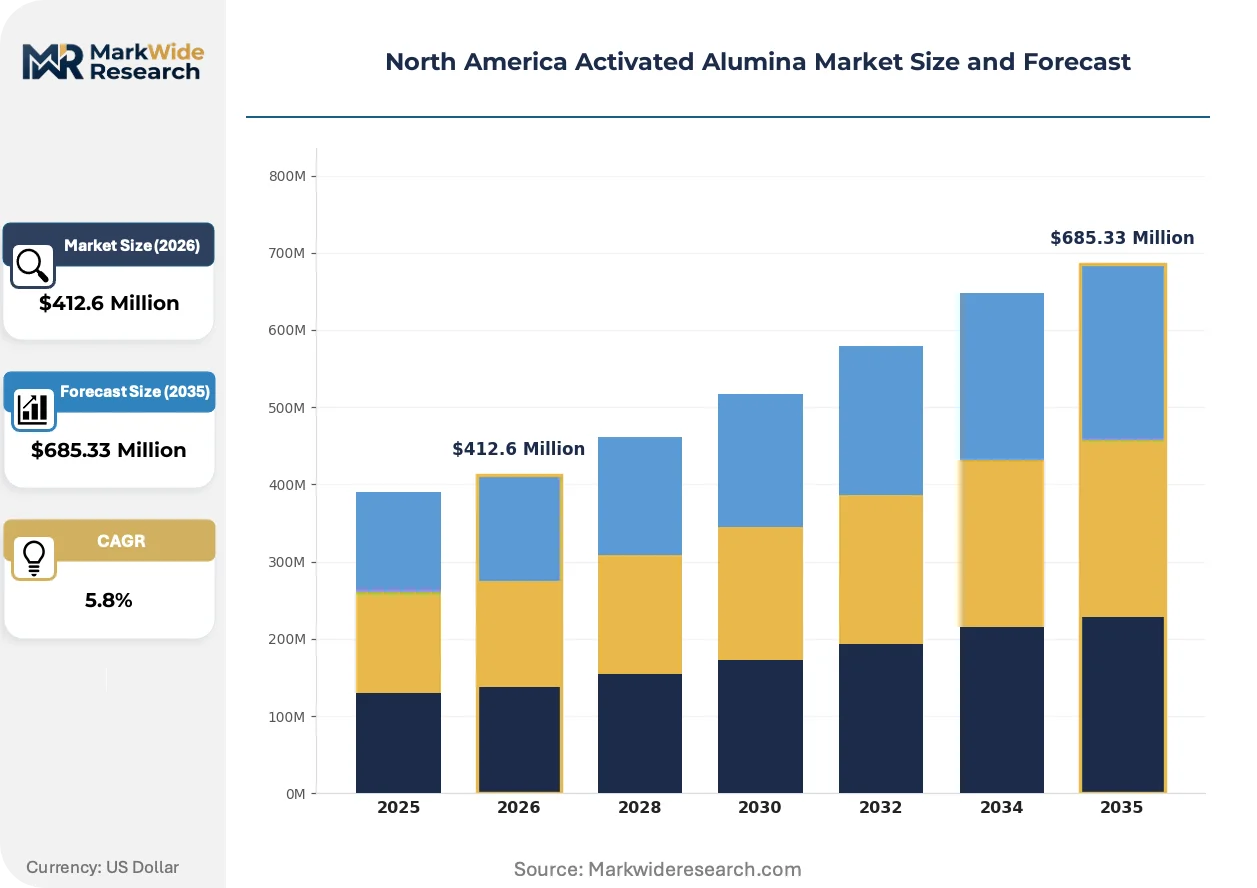
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desiccant, Catalyst, Fluoride Adsorbent, Process Component End User: Water Treatment, Oil & Gas, Air Separation, Chemical Manufacturing Form: Spherical, Granular, Powder, Pellets Application: Drying Agent, Purification, Reverse Osmosis, Catalysis |
| Companies Covered | BASF SE, Axens, Evonik Industries AG, Huber Engineered Materials, Honeywell International Inc., Porocel Corporation, Dynamic Adsorbents, Inc., W. R. Grace & Co.-Conn., Axens North America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Activated Alumina Market Trends and Innovations
Activated alumina product development is pivoting toward application-specific surface modifications and service-integrated delivery models that embed suppliers deeper into customer operations.
Engineered surface chemistries with enhanced fluoride selectivity are collapsing the performance gap between standard desiccant grades and specialty water treatment formulations. Municipal utilities in the Great Lakes corridor are adopting these modified aluminas to reduce bed replacement frequency. The technology is collapsing procurement patterns that historically separated commodity desiccant purchases from certified water-grade contracts.
EPA's anticipated PFAS maximum contaminant level rulemaking is accelerating adsorbent testing protocols and certification investments. Industrial water treatment operators are pre-qualifying activated alumina for multi-contaminant removal trains. The regulation is reshaping competitive positioning among suppliers capable of demonstrating simultaneous arsenic, fluoride, and PFAS performance.
Integrated supply contracts bundling media, installation, and regeneration services are displacing transactional spot purchasing. Petrochemical facilities along the Texas Gulf Coast are consolidating vendor relationships under multi-year technical service agreements. This consolidation is concentrating procurement authority among engineering-procurement-construction firms acting as intermediaries.
North America Activated Alumina Market Segmentation
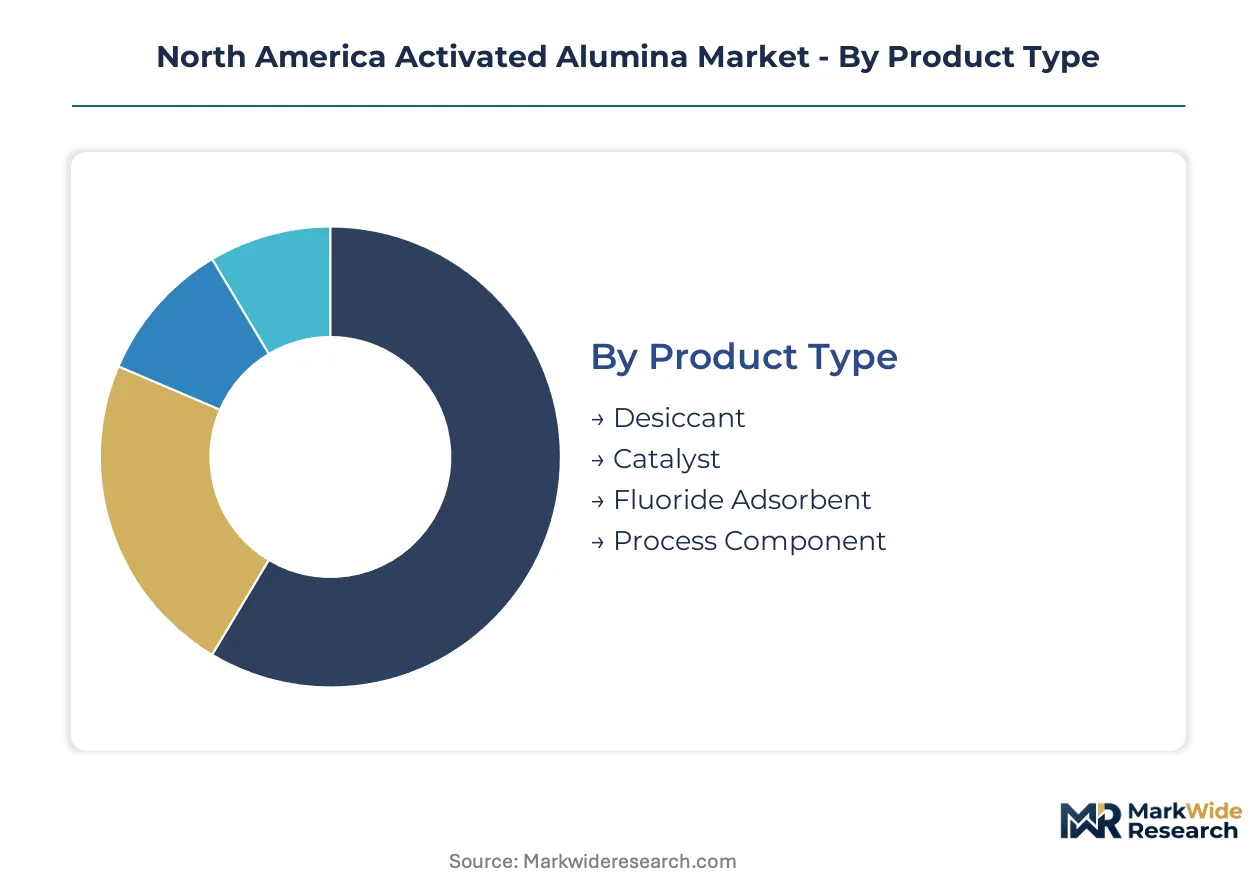
Segmentation in the North America activated alumina market reveals how technical specifications and regulatory requirements fragment procurement patterns across municipal, industrial, and petrochemical buyers. Understanding these divisions exposes where formulation premiums command pricing power versus where commodity desiccant volumes dominate.
Product Type:
Use-case spectrum spans moisture control in natural gas infrastructure to contaminant removal in drinking water systems, with each product category carrying distinct certification burdens and lifecycle economics.
- Desiccant:High-purity aluminum oxide spheres engineered for water adsorption from compressed air and hydrocarbon streams, with surface areas exceeding 300 square meters per gram. Demand concentrates across Texas and Louisiana Gulf Coast petrochemical complexes where moisture specifications in natural gas processing are tightening. Pipeline infrastructure investments and LNG export facility expansions are extending replacement cycles through larger bed designs.
- Fluoride Adsorbent:Surface-modified aluminas with enhanced selectivity for fluoride ion exchange, requiring NSF/ANSI 61 certification for potable water contact. Municipal utilities in California and Texas are standardizing on these formulations as EPA maximum contaminant level enforcement compresses compliance timelines. The segment carries the steepest formulation premiums due to extended validation periods and limited domestic manufacturing capacity.
- Catalyst:Low-sodium aluminas serving as support media for petrochemical and refining process catalysts, with controlled pore distributions for metal dispersion.
- Process Component:Technical-grade aluminas integrated into chemical manufacturing equipment as inert packing or filtration media, with specifications driven by process compatibility rather than adsorption performance.
Established volume favors Desiccant; emerging adoption favors Fluoride Adsorbent.
End User:
Customer type determines procurement authority structure, with municipal water districts operating under public bidding rules while petrochemical buyers negotiate integrated service contracts.
- Oil & Gas:Integrated majors and midstream operators specifying desiccant media for natural gas dehydration and refinery hydrogen purification, with procurement consolidated under engineering-procurement-construction firm intermediaries. Gulf Coast concentration of LNG export terminals and ethylene crackers is extending contract durations and bundling regeneration services.
- Water Treatment:Municipal utilities and industrial water operators deploying fluoride adsorbents and arsenic removal media under EPA Safe Drinking Water Act compliance mandates. California and Texas districts are consolidating specifications to reduce qualification overhead, while Great Lakes corridor utilities are adopting modified aluminas for multi-contaminant trains.
- Chemical Manufacturing:Specialty chemical and polymer producers requiring precise moisture control in reactant streams and inert atmospheres.
- Air Separation:Cryogenic gas producers using activated alumina pre-treatment beds to protect molecular sieve units from moisture and carbon dioxide contamination.
Procurement scale favors Oil & Gas; regulatory tailwinds favor Water Treatment.
Form:
Physical configuration governs handling economics and bed performance, with attrition resistance and pressure drop characteristics driving selection for specific reactor designs.
- Spherical:Uniform diameter beads optimized for packed bed applications where pressure drop minimization and flow distribution uniformity are critical. Natural gas processing facilities across the Permian Basin and Appalachian shale plays are standardizing on spherical desiccants to extend bed life between regeneration cycles.
- Granular:Irregular particles produced by crushing and screening calcined alumina, offering cost advantages in applications where precise sizing is secondary to adsorption capacity. Municipal water treatment plants in the US South are adopting granular fluoride adsorbents for gravity-fed systems where head loss tolerance is higher.
- Pellets:Extruded cylinders with controlled length-to-diameter ratios for applications requiring mechanical strength in high-velocity gas streams.
- Powder:Fine particulate aluminas for specialized chemical manufacturing where rapid dispersion and high surface area exposure are required.
Operational reliability favors Spherical; installed cost favors Granular.
Application:
Functional role in process flow determines performance specifications, with drying applications commanding volume leadership while purification requirements drive formulation complexity.
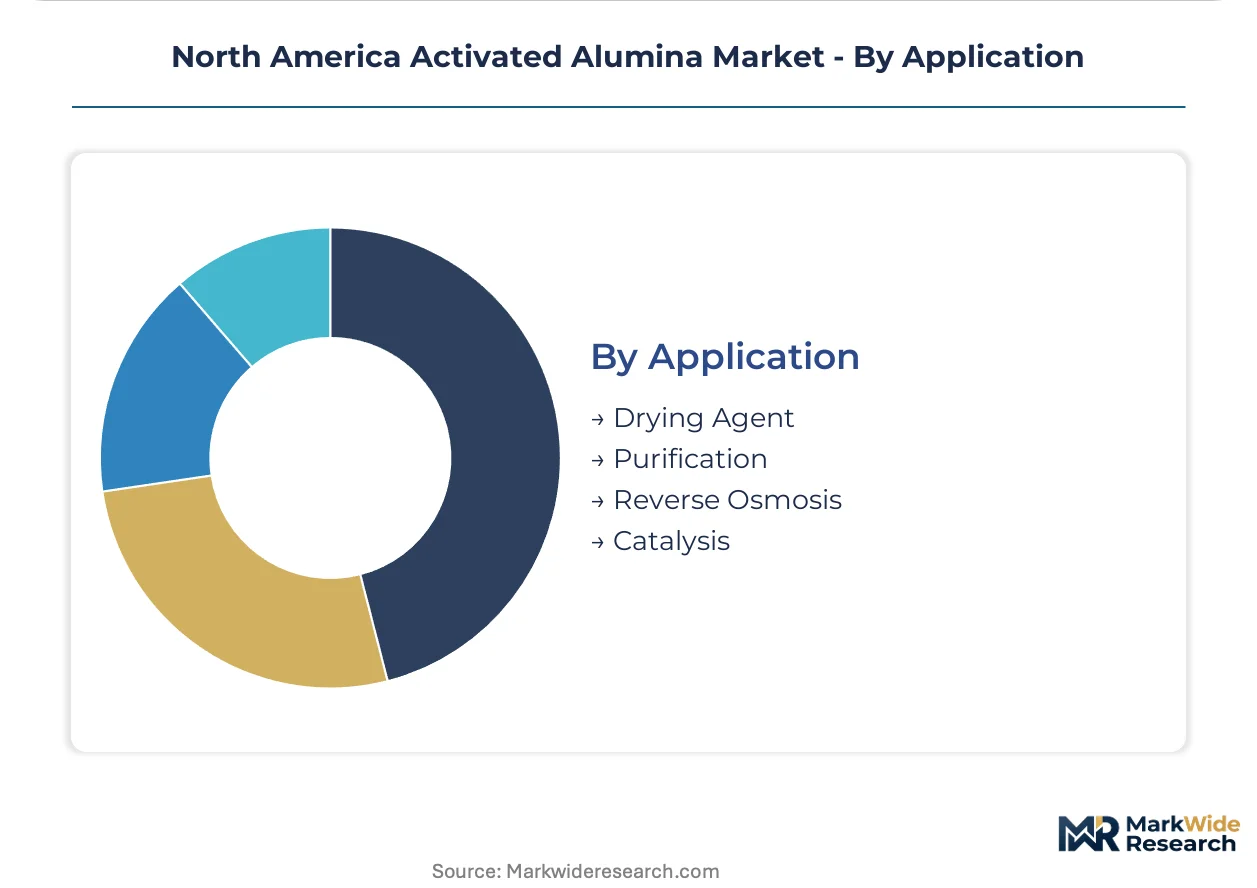
- Drying Agent:Moisture removal from compressed air, natural gas, and organic liquid streams, representing the foundational activated alumina application with established supply chains and standardized specifications. Petrochemical infrastructure expansion across the US Gulf Coast is reinforcing demand for high-capacity desiccant formulations with extended service intervals.
- Purification:Contaminant removal from process streams and drinking water, encompassing fluoride, arsenic, and emerging PFAS treatment applications. EPA regulatory development for per- and polyfluoroalkyl substances is accelerating qualification testing and expanding the addressable market for modified aluminas before resin technologies achieve cost parity.
- Catalysis:Support media and active catalyst components in petrochemical and refining processes, with pore structure engineering tailored to specific reaction chemistries.
- Reverse Osmosis:Pre-treatment media protecting membrane systems from chlorine and particulate fouling in desalination and water reuse applications.
Volume concentration favors Drying Agent; regulatory expansion favors Purification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the region. Municipal water districts in the United States absorb steep formulation premiums for certified fluoride adsorbents, while Canadian industrial buyers negotiate aggressively on desiccant volumes. Mexico's petrochemical sector operates at the most elastic end of the demand curve.
United States
EPA Safe Drinking Water Act enforcement compresses compliance timelines for arsenic and fluoride removal across Texas and California municipal utilities. The agency's anticipated PFAS maximum contaminant level rulemaking is accelerating adsorbent testing protocols nationwide. Gulf Coast petrochemical clusters around Houston and Corpus Christi are consolidating procurement under multi-year technical service agreements for desiccant supply.
Canada
Ontario and Alberta water treatment upgrade cycles remain underpenetrated relative to US municipal infrastructure spending levels. Health Canada drinking water guidelines for fluoride and emerging contaminants are tightening procurement specifications for provincial utilities. The Sarnia-Lambton petrochemical corridor and Alberta's oil sands processing facilities anchor industrial desiccant demand in the absence of domestic activated alumina manufacturing.
Mexico
Pemex refinery modernization and private midstream natural gas investments are extending desiccant replacement cycles across Veracruz and Tamaulipas processing facilities. Mexican environmental regulators are adopting NOM-127-SSA1 drinking water standards that reference EPA contaminant limits for arsenic and fluoride. The Altamira petrochemical complex and Reynosa manufacturing corridor concentrate demand for cost-optimized desiccant formulations with minimal certification overhead.
North America Activated Alumina Market Competitive Landscape
Capability concentration sits with specialty fluoride-grade formulators; scale advantage sits with integrated petrochemical chemical suppliers. The market structures around three tiers: multinational chemical conglomerates with catalyst manufacturing networks, domestic engineered materials specialists with municipal water certifications, and regional regeneration service providers with spent media reactivation infrastructure. Dominant competitive moves include backward integration into alumina hydrate feedstock sourcing and outcome-based service contracting that bundles media supply with performance guarantees.
Within the multinational tier, BASF SE and Evonik Industries AG exemplify integrated chemical suppliers leveraging catalyst manufacturing infrastructure to sustain technical service relationships. Huber Engineered Materials occupies a position among domestic specialists with concentrated municipal water district relationships. Porocel Corporation represents the regeneration services archetype, anchoring spent media reactivation capacity in the US South.
| Leading Market Players |
|---|
| BASF SE |
| Axens |
| Evonik Industries AG |
| Huber Engineered Materials |
| Honeywell International Inc. |
| Porocel Corporation |
| Dynamic Adsorbents, Inc. |
| W. R. Grace & Co.-Conn. |
| Axens North America, Inc. |
| Others |
Pricing and Supply Chain Analysis
Bauxite and caustic soda feedstock concentration in China and Australia compresses margin pools for North American calcination operators, forcing domestic manufacturers to capture value through NSF/ANSI 61 certification premiums and captive regeneration service bundling. Municipal water districts absorb steep formulation markups for fluoride-grade material while petrochemical buyers negotiate volume discounts on standardized desiccant spheres.
Pricing Analysis
Aftermarket regeneration service contracts now drive lifetime value as buyers shift from spot media purchases to integrated technical service agreements. Three-tier pricing structure across premium fluoride-adsorbent, standard desiccant, and economy technical-grade formulations separates certified potable water products from industrial moisture-control media. Cost compression in the desiccant tier is intensifying because Gulf Coast petrochemical buyers are consolidating procurement under engineering-procurement-construction intermediaries. Municipal water districts exhibit the lowest price sensitivity due to EPA compliance mandates, while Mexican industrial operators demonstrate the highest elasticity.
Supply Chain Analysis
Alumina hydrate feedstock draws from Chinese and Australian bauxite refining capacity, with caustic soda sourcing tethered to chlor-alkali production clusters along the US Gulf Coast. Domestic activated alumina manufacturing rests on imported precursor materials and specialized calcination equipment from European suppliers. Single-source vulnerability concentrates in specialty fluoride-grade production, where limited domestic NSF/ANSI 61 certified capacity creates procurement bottlenecks for municipal utilities. Distribution runs through regional chemical distributors for industrial desiccant volumes and direct manufacturer relationships for certified water treatment grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward municipal water districts consolidating specifications across Texas and California, compressing supplier margins and locking in incumbent fluoride-grade formulators through multi-year technical service agreements.
For Market Incumbents: Build regulatory certification moats by accelerating NSF/ANSI 61 validation investments for modified aluminas targeting PFAS pre-qualification. Defend against ion exchange resin substitution by embedding IoT-enabled bed monitoring into outcome-based service contracts. Capacity addition in the US South for spent media reactivation infrastructure will anchor recurring revenue streams as captive recycling programs extend product lifecycles. For New Entrants and Emerging Players: Build out regeneration service capabilities in Ontario and Alberta, where Health Canada guideline tightening precedes infrastructure upgrade cycles. White-space concentrates in digital monitoring integration for predictive maintenance platforms serving Great Lakes corridor utilities. A go-to-market angle bundling media supply with performance guarantees bypasses entrenched municipal procurement relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialty fluoride-grade formulators with locked municipal water district relationships and pending PFAS certification investments. Long-term viability centers on suppliers capable of demonstrating simultaneous arsenic, fluoride, and per- and polyfluoroalkyl substances removal performance before resin technologies achieve cost parity. The signal to watch is EPA PFAS maximum contaminant level rulemaking acceleration, which would expand the addressable market for modified aluminas as a bridging technology.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Hydrate Sourcing | Reduces exposure to Chinese bauxite refining volatility for domestic calcination operators. |
| NSF/ANSI 61 Certification Investment | Accelerates municipal water district procurement qualification timelines for fluoride-grade formulations. |
| IoT-Enabled Bed Performance Monitoring | Enables outcome-based service contracting with predictive maintenance platforms for industrial buyers. |
| Spent Media Reactivation Capacity Expansion | Captures recurring revenue from captive recycling programs extending product lifecycles. |
| PFAS Pre-Qualification Testing | Positions modified aluminas for multi-contaminant removal trains before resin cost parity emerges. |
Research Methodology
Operator-level perspectives from municipal water treatment plant managers, petrochemical procurement leads at Gulf Coast refineries, activated alumina manufacturing technical directors, and regeneration service facility operators anchored the qualitative base for this study. Primary interview insights were cross-referenced against EPA Safe Drinking Water Act enforcement records, customs and trade data for alumina hydrate imports, SEC 10-K filings from integrated chemical suppliers, and American Chemistry Council sector reports. Bottom-up volume modeling triangulated against top-down market sizing derived from desiccant replacement cycle analysis and municipal infrastructure spending databases.
Scenario-bracketing around EPA PFAS rulemaking timing and bauxite price volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry, physical form configuration, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle compression factors. Industry-specific forecast inputs incorporated natural gas processing capacity expansions along the Texas and Louisiana Gulf Coast and Health Canada drinking water guideline adoption trajectories in Ontario and Alberta.
Sensitivities concentrate around EPA PFAS maximum contaminant level promulgation delays, Chinese bauxite export restriction scenarios, and ion exchange resin technology cost reduction curves. Forecasts reflect assumptions regarding municipal infrastructure spending continuity and petrochemical capital investment cycles. Cross-checking against EPA enforcement action databases and provincial utility procurement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Medical Ceramics Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Thermal Spray Powder Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Global Barium Carbonate Market
Ceramics
Lithium Silicate Market
Ceramics
Calcium Oxide Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Active Calcium Silicate Market
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market