
 PVA Glue Market | 2026-2036
PVA Glue Market Size, Share, and Industry Trends Forecast 2026-2036
PVA Glue Market Analytics
Ethylene-vinyl acetate copolymer is rebalancing cost-performance trade-offs in adhesive formulations as manufacturers reduce reliance on solvent-based alternatives. Henkel AG & Co. KGaA leverages its European distribution network to sustain industrial-grade supply contracts. BASF SE anchors polymer feedstock quality through captive ethylene sourcing. H.B. Fuller Company competes in North American packaging adhesives with specialized hot-melt PVA hybrids.
Polyvinyl acetate adhesive consists of a thermoplastic polymer emulsified in water, typically containing 40-60% solids by weight with a viscosity range of 500-5000 cP depending on molecular weight grade; manufacturers polymerize vinyl acetate monomer via free-radical emulsion polymerization to produce bonds that cure through water evaporation at room temperature. White glue formulations dominate volume in education and paper bonding applications where repositionability and easy cleanup define purchasing criteria. Waterproof PVA variants command premium positioning in construction end uses where ANSI/HPVA Type I moisture resistance certification separates professional-grade products from commodity school glue. DIY enthusiasts increasingly drive demand for tube and bottle packaging formats that enable precise application control in home repair projects.
EPA regulates VOC emissions from consumer adhesives under 40 CFR Part 59 Subpart D, limiting formaldehyde content and driving reformulation toward lower-emission PVA emulsions. REACH restricts hazardous substance migration in European imported finished goods, compelling Asian exporters to certify adhesive inputs through ECHA-registered supply chains. ISO 10993 biocompatibility standards govern PVA glue use in medical device assembly, creating a compliance moat for qualified manufacturers. Stakeholders must monitor how California's Department of Toxic Substances Control expands its Safer Consumer Products program to prioritize adhesive chemistries for alternative analysis.
Market Dynamics
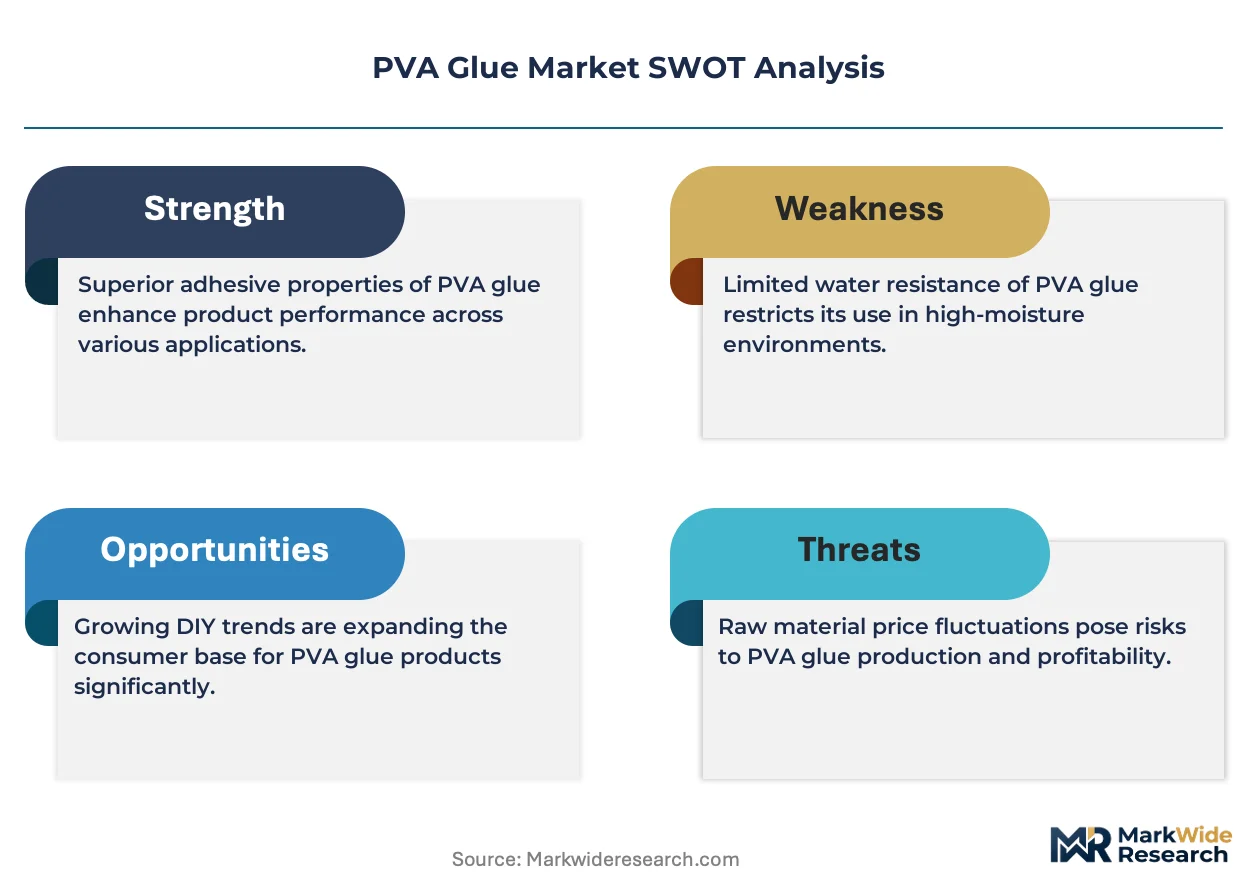
Waterborne PVA emulsion chemistry faces mounting pressure from EU Green Deal VOC limits and China's dual carbon goals, forcing reformulation investments that compress margin structures for commodity-grade producers.
Growth Catalysts
- EU Green Deal chemical safety protocols:Germany's residential construction sector accelerates woodworking adhesive demand as builders phase out solvent-based alternatives under tightening formaldehyde emission limits.
- Furniture export manufacturing:Coastal provinces in China concentrate industrial-grade yellow PVA consumption at scale, driven by integrated supply chains serving European and North American retail channels.
- ANSI/HPVA Type I certification:Waterproof PVA variants capture construction end-use premiums as contractors specify moisture-resistant grades for exterior joinery and wet-area applications.
Market Restraints
- Vinyl acetate monomer price volatility:Feedstock costs fluctuate with ethylene and acetic acid supply disruptions, squeezing margins for non-integrated emulsion producers.
- Coastal China supply concentration:Manufacturing clusters in Guangdong and Zhejiang create geographic risk exposure to port congestion, energy rationing, and regional environmental enforcement actions.
- Hot-melt EVA substitution:Ethylene-vinyl acetate copolymers displace PVA in high-speed packaging lines where instant green strength and thermal processing efficiency outweigh waterborne advantages.
Strategic Opportunities
- India BIS standardization gap:Domestic furniture and paperboard manufacturers seek certified adhesive suppliers as import substitution policies expand local production capacity.
- Medical device assembly:ISO 10993 biocompatibility qualification opens specialty PVA applications in wound closure and transdermal patch manufacturing.
- DIY channel digitization:E-commerce platforms and home improvement marketplaces enable direct-to-consumer tube and bottle formats with precision applicator attachments.
Industry Challenges
- REACH supply chain documentation:Asian exporters face ECHA registration burdens and SVHC screening complexity for finished goods entering European distribution.
- Emulsion polymerization scale-up:Batch-to-batch viscosity consistency requires capital-intensive reactor automation and inline quality monitoring systems.
- California Safer Consumer Products prioritization:DTSC alternative analysis procedures create compliance timeline uncertainty for adhesive chemistries under review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVA Glue Market |
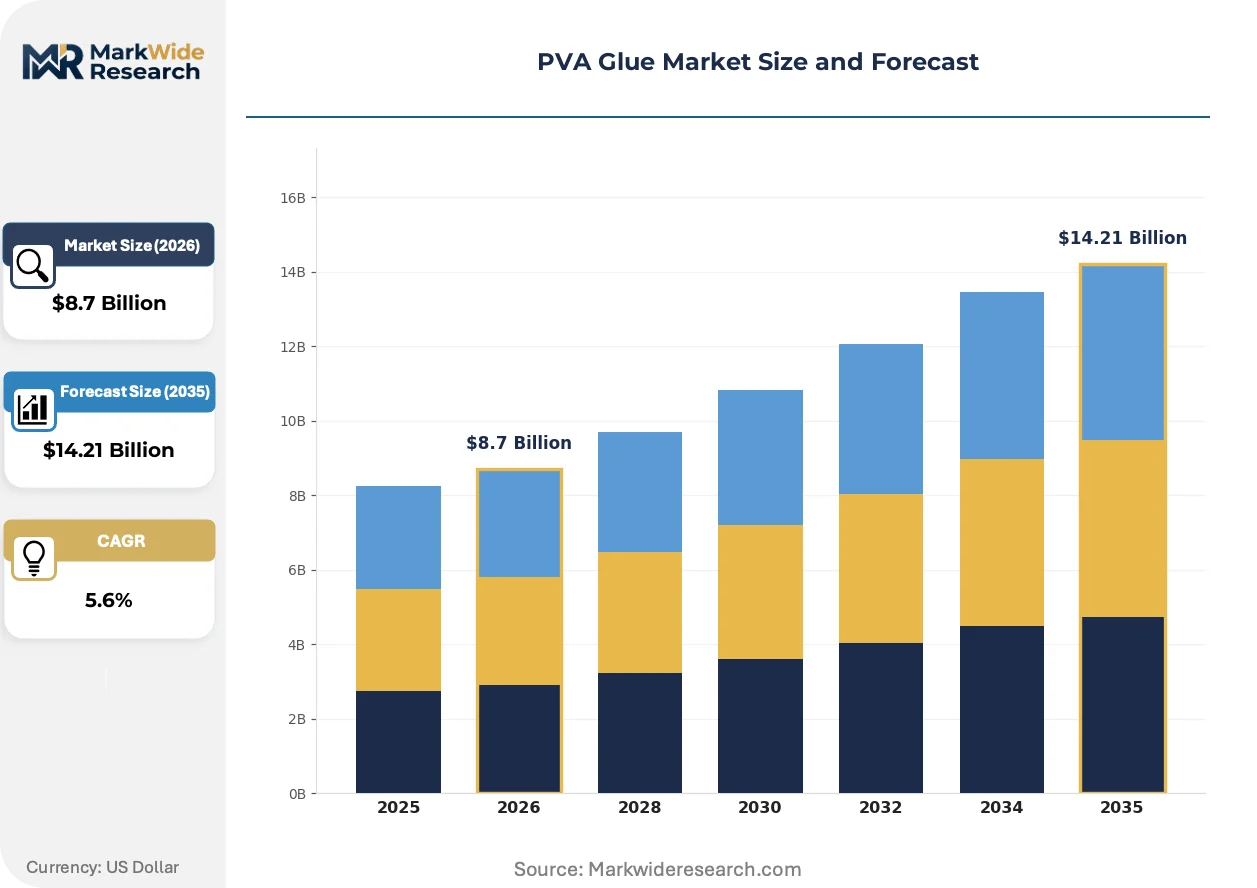
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Glue, Yellow Glue, Waterproof Glue, School Glue Application: Paper, Wood, Textiles, Arts & Crafts End User: Education, Construction, Manufacturing, DIY Enthusiasts Packaging Type: Bottles, Tubes, Tubs, Pails |
| Companies Covered | Sinopec Corporation, BASF SE, 3M Company, Bostik, Jowat SE, Henkel AG & Co. KGaA, H.B. Fuller Company, Gorilla Glue, Inc., Elmer's Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVA Glue Market Evolving Landscape
Formulation chemistry and application methods are diverging sharply between industrial performance grades and consumer convenience formats, with regulatory pressure acting as the primary segmentation force.
Crosslinking PVA copolymers with N-methylolacrylamide or metal salt additives is decentralizing moisture-resistant adhesive production away from specialized chemical manufacturers toward integrated woodworking operations. Mid-sized German and Austrian furniture producers now operate in-house compounding lines to customize open time and bond strength. This capability diffusion compresses the addressable market for standardized industrial emulsions.
REACH restriction of hazardous substance migration in imported finished goods is compelling Asian exporters to certify adhesive inputs through ECHA-registered supply chains. European customs authorities now demand substance volume tracking and safety data sheet alignment at border entry. Construction-grade PVA shipments face heightened scrutiny compared with education and paper bonding grades.
Certification-driven specification behavior is fragmenting procurement authority within large construction and furniture manufacturing organizations. Sustainability officers now override traditional purchasing decisions, mandating EPD-verified and low-VOC formulations regardless of unit cost premiums. This shift concentrates volume with qualified suppliers in Germany, Austria, and Scandinavia while disqualifying commodity traders.
PVA Glue Market Segmentation
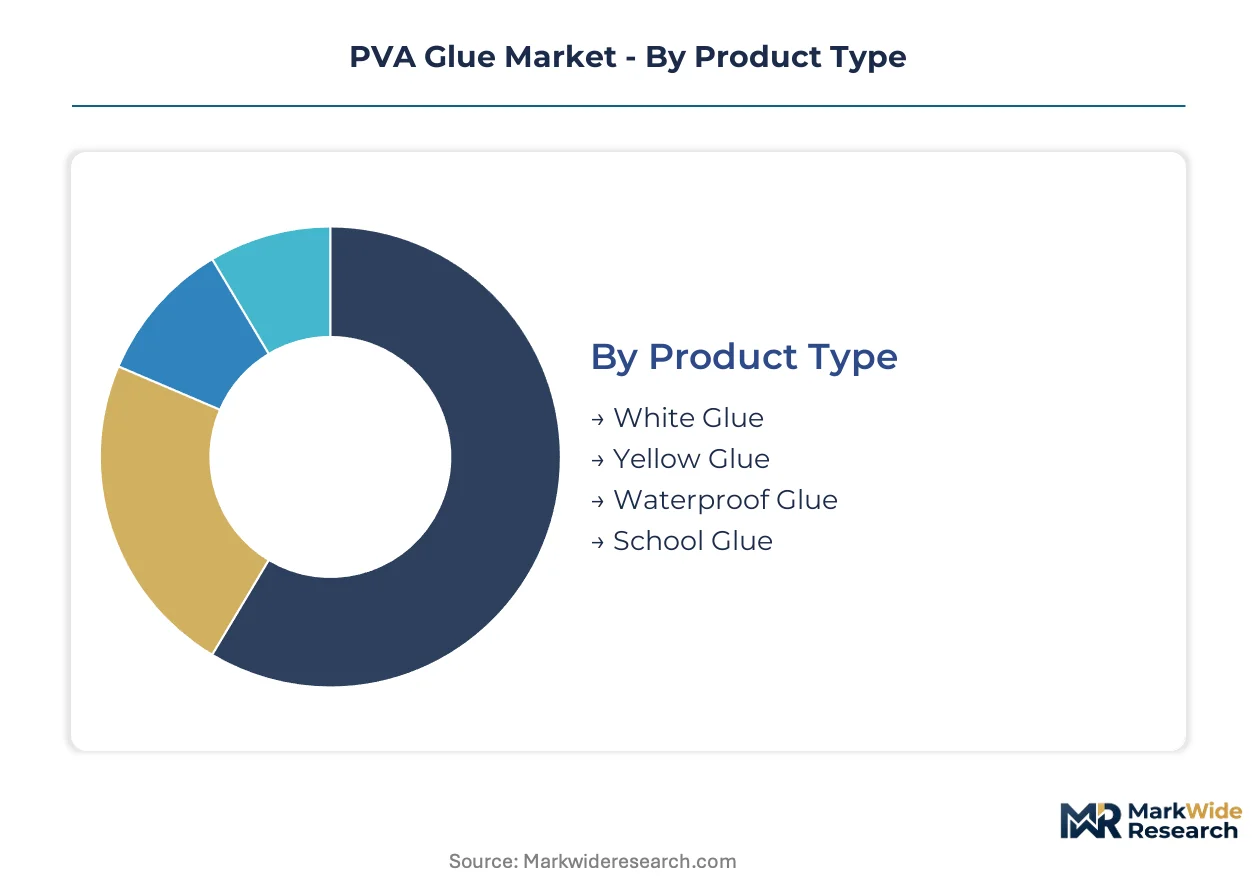
Segmentation in the PVA glue market reveals how capital intensity, regulatory compliance, and end-use performance requirements fragment manufacturing priorities across adhesive grades. Understanding these divides clarifies why certain producers concentrate on commodity volume while others pursue certified specialty positioning.
Product Type:
Capital intensity varies sharply across product categories, with waterproof formulations demanding crosslinking reactor investments that white glue producers avoid entirely.
- White Glue:Standard PVA emulsion with 40-50% solids content serves paper bonding and light woodworking where repositionability matters. German educational suppliers specify this grade for classroom safety under EU Green Deal VOC protocols, though margin compression limits producer differentiation.
- Yellow Glue:Higher solids content (50-60%) and faster tack development target furniture manufacturing in China's Guangdong and Zhejiang export clusters. Coastal manufacturers consume industrial volumes under tight delivery schedules for European retail channels.
- Waterproof Glue:ANSI/HPVA Type I certification requires N-methylolacrylamide crosslinking or metal salt additives, elevating capital requirements for moisture-resistant polymerization. German and Austrian woodworking operations increasingly compound in-house, compressing third-party demand.
- School Glue:Washable, low-toxicity formulations prioritize child safety labeling over performance metrics. Washability standards and easy cleanup properties dominate procurement criteria for institutional buyers.
Yellow glue absorbs the bulk of installed capacity; waterproof glue is expanding most quickly as construction specifications harden against moisture failure.
Application:
Application segmentation tracks how bond strength requirements and substrate compatibility determine formulation chemistry and pricing tiers.
- Paper:Low-shear, repositionable bonds suit bookbinding and packaging where fiber tear failure mode is acceptable. White glue dominates this segment with minimal regulatory friction.
- Wood:Structural load-bearing demands drive yellow and waterproof grade consumption. German residential construction accelerates woodworking adhesive demand as builders phase out solvent-based alternatives under tightening formaldehyde emission limits.
- Textiles:Flexible, wash-resistant bonds require specialized plasticizers and crosslinking chemistry. Niche positioning limits volume scale for most producers.
- Arts & Crafts:Non-toxic, easy-cleanup properties define purchasing for hobby and educational markets. Repositionability and washability outweigh bond strength specifications.
Wood applications command the highest value per kilogram; paper applications move the largest absolute tonnage through distribution channels.
End User:
End user segmentation exposes how procurement authority fragmentation—between sustainability officers, purchasing managers, and production engineers—reshapes supplier relationships.
- Education:Institutional buyers prioritize non-toxic certification and bulk packaging economy. School glue specifications emphasize child safety over bond performance.
- Construction:Contractors specify ANSI/HPVA Type I waterproof grades for exterior joinery and wet-area applications. Certification-driven procurement concentrates volume with qualified suppliers in Germany, Austria, and Scandinavia.
- Manufacturing:Furniture and paperboard producers seek viscosity consistency and open-time customization. China's coastal manufacturing provinces concentrate industrial-grade consumption at scale.
- DIY Enthusiasts:Precision applicator attachments and tube/bottle formats enable home repair project control. E-commerce platforms and home improvement marketplaces reshape distribution access.
Manufacturing absorbs the majority of industrial-grade volume; DIY enthusiasts are gaining share fastest as direct-to-consumer channels mature.
Packaging Type:
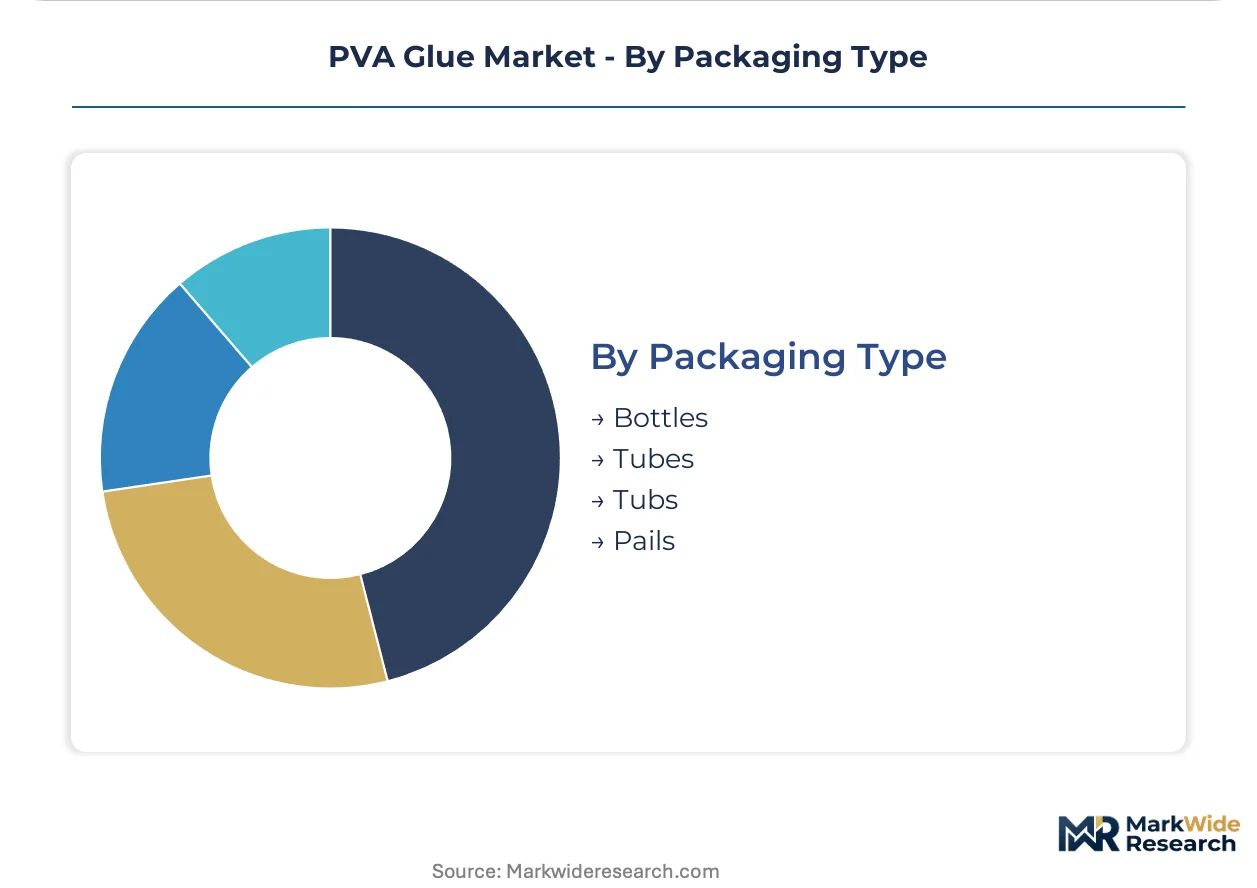
Packaging segmentation reflects how application precision, volume scale, and storage shelf life determine container engineering investments.
- Bottles:Squeeze-dispense designs suit school and white glue applications where controlled flow rates matter. Education and arts & crafts channels favor this format for accessibility.
- Tubes:Precision nozzle attachments target DIY repair and small-project woodworking. Home improvement retailers specify this format for premium placement.
- Tubs:Wide-mouth containers serve institutional bulk users and manufacturing floor dispensing. Construction contractors favor this format for brush-application efficiency.
- Pails:Industrial-scale volumes for manufacturing operations with automated or semi-automated dispensing systems. Furniture producers in China's export clusters consume pail formats at highest velocity.
Pails dominate manufacturing procurement by volume; tubes are climbing the fastest as DIY channel digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong and Zhejiang provinces concentrate industrial-grade PVA manufacturing capacity, attracting furniture exporters through tax incentives and bonded logistics infrastructure. These coastal clusters process raw material imports and finished goods exports under streamlined customs protocols.
China
Furniture export manufacturing in Guangdong and Zhejiang provinces consumes industrial-grade yellow PVA at scale, serving European and North American retail channels. MIIT enforces dual carbon goals that tighten energy intensity standards on emulsion polymerization facilities. The Pearl River Delta integrates vinyl acetate monomer supply with woodworking adhesive finishing in vertically configured chemical parks.
Germany
Residential construction accelerates woodworking adhesive demand as builders phase out solvent-based alternatives. EU Green Deal chemical safety protocols tighten formaldehyde emission limits on adhesive formulations under REACH annex restrictions. Bavarian and Baden-Württemberg furniture producers increasingly operate in-house compounding lines for customized open-time specifications.
United States
DIY enthusiasts drive demand for precision tube and bottle formats through home improvement retail channels. EPA regulates VOC emissions from consumer adhesives under 40 CFR Part 59 Subpart D, limiting formaldehyde content and driving reformulation. The Southeast and Midwest concentrate construction-grade consumption where contractors specify ANSI/HPVA Type I waterproof variants for exterior applications.
India
Domestic furniture and paperboard manufacturers seek certified adhesive suppliers as import substitution policies expand local production capacity. BIS standardization gaps create compliance uncertainty for imported formulations. Maharashtra and Gujarat host emerging manufacturing clusters where producers target institutional education and construction end uses with economy-grade emulsions.
Japan
Precision electronics and packaging applications demand high-viscosity consistency grades for automated dispensing systems. METI promotes low-carbon manufacturing transitions that affect emulsion polymerization energy profiles. The Kansai region maintains specialty adhesive compounding capabilities serving domestic automotive interior and medical device assembly markets.
PVA Glue Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply in industrial grades and fragmented competition in consumer formats. Three archetypes dominate: integrated chemical conglomerates with captive monomer supply, adhesive specialists with formulation IP, and private-label converters serving retail channels. Competitive moves concentrate on backward integration into vinyl acetate monomer production and geographic expansion through distribution partnerships in high-growth Asian markets.
Among European chemical conglomerates, BASF SE anchors polymer feedstock quality through captive ethylene sourcing, while Henkel AG & Co. KGaA leverages its distribution network to sustain industrial-grade supply contracts. H.B. Fuller Company occupies a position in North American packaging adhesives, competing with specialized hot-melt PVA hybrid formulations. These three exemplify how scale-driven producers balance commodity volume with certified specialty positioning across regional markets.
| Leading Market Players |
|---|
| Sinopec Corporation |
| BASF SE |
| 3M Company |
| Bostik |
| Jowat SE |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Gorilla Glue, Inc. |
| Elmer's Products, Inc. |
| Others |
Value Network & Pricing Analysis
Vinyl acetate monomer spot pricing on Asian petrochemical exchanges cascades through PVA emulsion manufacturing into three distinct procurement tiers: construction-grade waterproof formulations, industrial yellow glue for export furniture, and commodity white glue for education markets. Buyers with captive ethylene sourcing or long-term offtake agreements capture margin insulation unavailable to spot-market purchasers.
Pricing Analysis
Short lead-time premiums separate urgent construction procurement from scheduled manufacturing orders, with contractors paying 15-25% above contract rates for ANSI/HPVA Type I certified waterproof grades. Pricing stratifies across premium, standard, and economy tiers driven by crosslinking chemistry investment and ECHA registration documentation. Cost compression in commodity white glue intensifies because German educational suppliers consolidate volume under EU Green Deal VOC compliance mandates. DIY enthusiasts demonstrate lowest price sensitivity, accepting applicator premiums for tube-format convenience.
Supply Chain Analysis
ECHA-registered supply chain qualification gates entry to European distribution, compelling Asian exporters to document SVHC screening and substance volume tracking at customs entry. Manufacturing concentrates in China, Germany, and the United States, with Guangdong and Zhejiang provinces hosting vertically integrated chemical parks. Feedstock draws from ethylene crackers and acetic acid producers, with polymerization batch consistency requiring reactor automation investment. Single-source vulnerability concentrates in coastal China port infrastructure. Distribution runs through industrial chemical distributors for manufacturing accounts and home improvement retailers for consumer formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players securing captive vinyl acetate monomer supply or backward integration into emulsion polymerization capacity. The race for upstream control separates margin-defensible specialists from commodity traders facing feedstock volatility.
For Market Incumbents: Lock in ECHA-registered supply chain documentation to disqualify unqualified Asian competitors from European construction specifications. Expand reactor automation in Germany and Austria to match in-house compounding capabilities diffusing among mid-sized furniture producers. EVA hot-melt substitution in packaging lines threatens PVA volume; defend through waterproof grade certification concentration. For New Entrants and Emerging Players: Begin with India's BIS standardization gap, where domestic furniture and paperboard manufacturers seek certified adhesive suppliers under import substitution policies. Maharashtra and Gujarat offer manufacturing cluster proximity with lower regulatory compliance burdens than coastal China. Pursue direct e-commerce distribution of precision tube formats to DIY enthusiasts, bypassing established retail channel gatekeepers. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with ISO 10993 biocompatibility qualification serving medical device assembly. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch California DTSC Safer Consumer Products prioritization decisions as inflection indicators for adhesive chemistry substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VAM Production | Captive ethylene sourcing insulates BASF and Sinopec from petrochemical price volatility. |
| ECHA Registration Investment | Documentation compliance opens European construction procurement to qualified Asian exporters. |
| Reactor Automation Scale-Up | Inline viscosity monitoring enables batch consistency for furniture manufacturers demanding open-time customization. |
| Medical Device Biocompatibility Certification | ISO 10993 qualification creates specialty positioning in wound closure and transdermal patch assembly. |
| DIY Channel Digitization | E-commerce platform partnerships enable direct-to-consumer tube formats with precision applicator attachments. |
Research Methodology
Document review covered customs trade databases, SEC 10-K filings from listed chemical producers, and ECHA substance registration records, complemented by interviews with plant managers at emulsion polymerization facilities, procurement leads at German furniture manufacturers, distribution channel partners serving European retail networks, and technical R&D directors at adhesive formulators. Secondary validation drew from ACC and Cefic industry reports, MIIT energy intensity disclosures, and EPA regulatory filings. Bottom-up capacity assessments triangulated against top-down consumption estimates across end-use segments.
Output modeling generated volume and value trajectories across the projection horizon by disaggregating grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from historical elasticity analysis applied to forecast feedstock cost movements and regulatory compliance investment requirements. Key inputs included vinyl acetate monomer price series, EU Green Deal implementation timelines, and China dual carbon enforcement intensity.
Underlying measurement precision varies by segment; waterproof and medical-grade applications carry tighter precision than commodity school glue. Forecasts reflect assumptions about REACH enforcement consistency and MIIT energy rationing protocols. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Brazil Sealants Market