
 Paper Based Laminates Market | 2026-2036
Paper Based Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Based Laminates Market Analytics
Aftermarket surface refurbishment is reshaping margin distribution in paper based laminates, diverting value from virgin panel sales toward recoating and overlay replacement services. UPM-Kymmene leverages its integrated pulp-to-laminate chain to control raw material quality for high-pressure grades. Mondi Group anchors European supply through specialized kraft paper mills serving industrial laminate backers. WestRock competes in North American cabinetry with coated containerboard substrates optimized for low-pressure bonding cycles.
Paper based laminates are multi-layer composites formed by impregnating kraft or decorative paper with thermosetting resins, then curing under heat and pressure to create dimensionally stable sheets with wear-resistant surfaces. Decorative laminates lead product type revenue due to premium surfacing contracts in commercial interiors, while industrial laminates sustain volume through electrical insulation and transformer core applications. The residential end-user segment dominates unit consumption for kitchen cabinets and flooring, though healthcare application demand accelerates fastest behind antimicrobial surface specifications and infection-control renovations.
EPA formaldehyde emission standards under TSCA Title VI constrain adhesive formulations in US-bound panels, while REACH restricts phenolic resin chemistry in European laminate production. China's GB standards for indoor air quality enforce E0-grade limits on finished panels entering commercial buildings. ISO 4586 governs high-pressure decorative laminate performance testing across export markets. Stakeholders must monitor evolving bio-based resin certifications and regional carbon-border adjustments that will determine qualified supplier status in the next planning cycle.
Market Dynamics
REACH compliance and the EU Green Deal's material traceability mandates are compressing converter margins while forcing substrate certification upgrades across European laminate supply chains.
Growth Catalysts
- Antimicrobial surface specifications:Healthcare renovation contracts specify infection-control laminates for clinical interiors, accelerating specification upgrades in hospital and aged-care procurement.
- GB standards enforcement:China's E0-grade indoor air quality mandates for commercial buildings are disqualifying uncertified panel imports and consolidating qualified supplier pools.
- Aftermarket refurbishment services:Surface recoating and overlay replacement divert maintenance budgets from virgin panel purchases, extending laminate lifecycle revenue capture.
Market Restraints
- Phenolic resin chemistry restrictions:REACH limits on formaldehyde and phenol derivatives constrain European adhesive formulations and raise compliance costs for regional producers.
- Kraft paper supply concentration:Specialized pulp mills in Nordic regions and Guangdong province control high-purity substrate flows, creating bottleneck vulnerability for decorative grade manufacturers.
- Thin-film polymer substitutes:PVC and PET overlay films compete for low-wear cabinetry applications, compressing entry-level laminate pricing bands.
Strategic Opportunities
- Bio-based resin certifications:EU carbon-border adjustment mechanisms reward verified renewable content, creating first-mover advantage for converters with certified supply chains.
- Transformer core insulation:Industrial laminates for electrical applications face undersupply against grid infrastructure expansion, particularly in South Asian and Southeast Asian markets.
- Direct-to-fabricator digital platforms:Panel producers in Guangdong province are bypassing traditional distribution tiers through integrated e-procurement portals.
Industry Challenges
- Resin formulation chemist scarcity:Thermoset polymer expertise pools concentrate at legacy phenolic producers, constraining R&D velocity for bio-based alternatives.
- ISO 4586 testing timeline compression:Export certification cycles for high-pressure decorative grades extend lead times, complicating just-in-time contract fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Based Laminates Market |
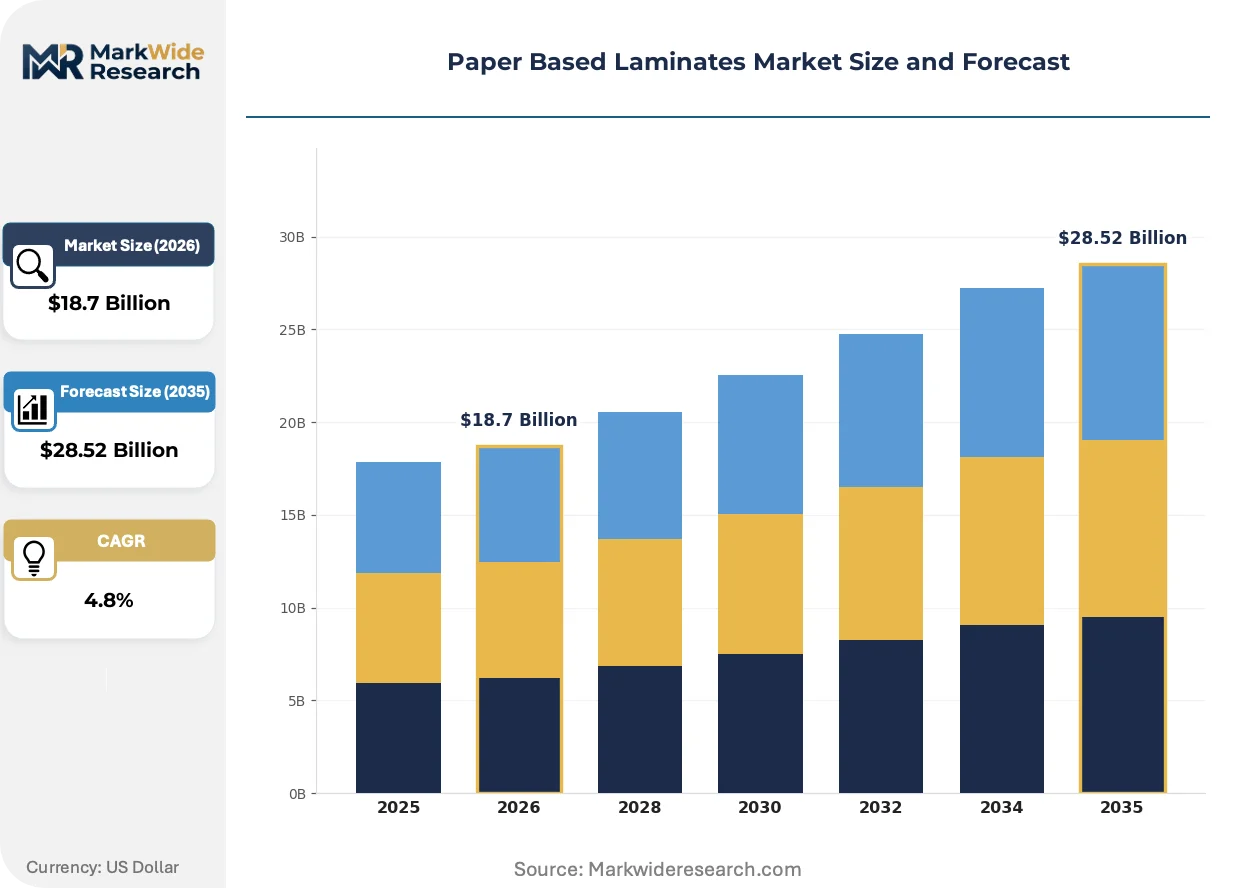
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Laminates, Industrial Laminates, High-Pressure Laminates, Low-Pressure Laminates End User: Furniture, Flooring, Wall Panels, Cabinets Application: Residential, Commercial, Healthcare, Education Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | UPM-Kymmene, BillerudKorsnäs, Amcor, Constantia Flexibles, Huhtamaki, Mondi Group, Sappi Limited, Sonoco, WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Based Laminates Market Evolving Landscape
Digital workflow integration and resin chemistry substitution are compressing traditional production cycles while opening specification pathways previously blocked by certification barriers.
Digital impregnation control systems are digitizing resin saturation monitoring across kraft paper webs, enabling real-time viscosity adjustments that reduce curing defects. Cabinetry producers in Germany and Italy are retrofitting lines with these sensors to meet narrow thickness tolerances for premium interior fittings. The technology is digitizing quality assurance workflows that previously required offline laboratory verification.
EPA formaldehyde emission standards under TSCA Title VI are constraining adhesive formulations in US-bound panels, forcing reformulation investments at cross-border suppliers. The regulation most acutely affects medium-density fiberboard backers bonded with urea-formaldehyde resins. Canadian and Mexican panel exporters are responding by shifting toward phenolic resin systems or seeking EPA-recognized third-party certification.
Specification-driven procurement now dominates commercial interior contracts, with architects and facility managers demanding chain-of-custody documentation before qualifying laminates for healthcare and hospitality installations. Traditional distributor-led selling is yielding to direct technical collaboration between converters and design firms. This pattern concentrates in Nordic markets where public procurement mandates transparency scoring for building material selections.
Paper Based Laminates Market Segmentation
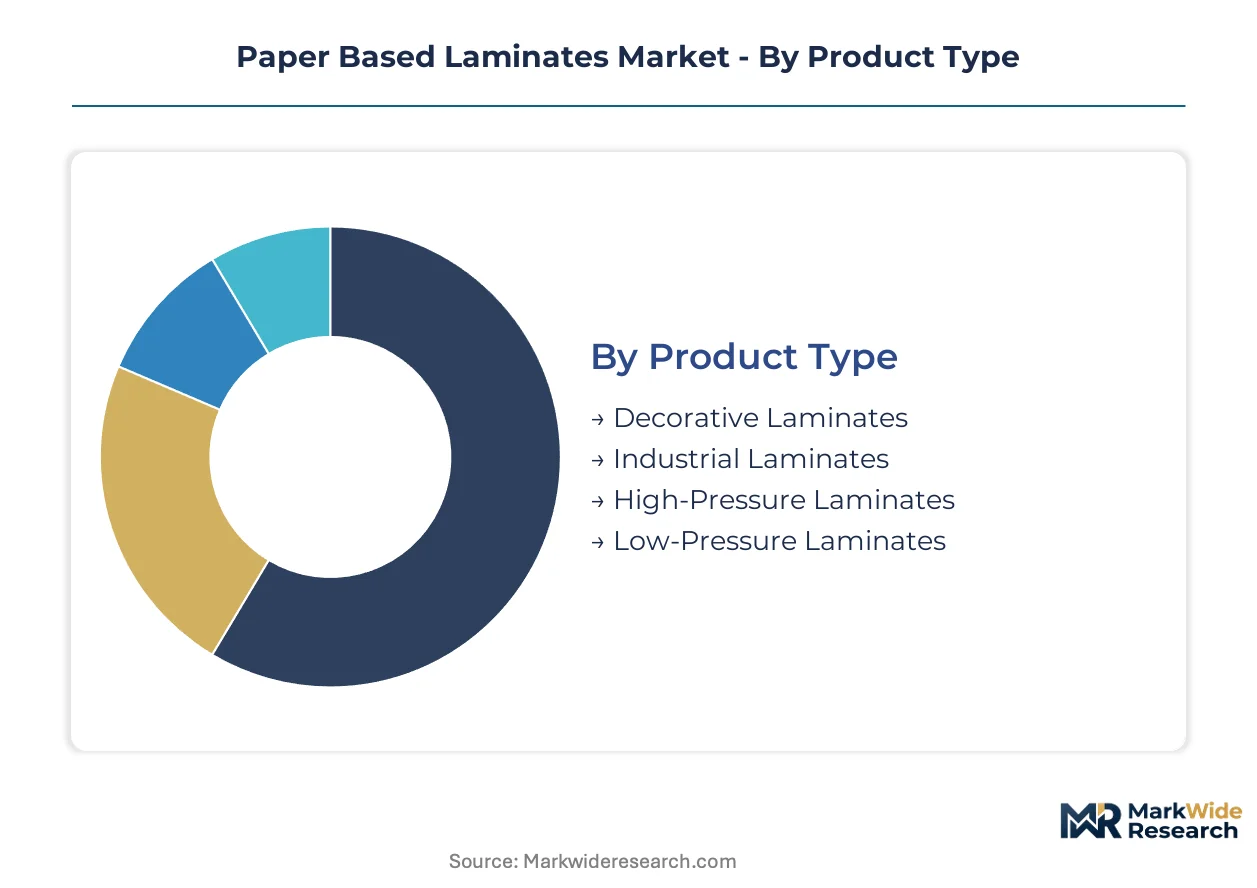
Paper based laminates serve fundamentally different performance requirements across decorative surfacing and industrial insulation roles. Segment boundaries determine resin chemistry, curing pressure, and certification pathways that suppliers must navigate separately.
Product Type:
Cycle times vary dramatically: decorative grades turn on interior renovation schedules measured in years, while industrial laminates for electrical equipment align with infrastructure investment waves lasting decades.
- Decorative Laminates:Multi-layer kraft and decorative paper composites impregnated with melamine-formaldehyde resins, cured under high pressure to create wear-resistant surfacing materials. Procurement concentrates in Germany and Italy for premium cabinetry and interior fittings, driven by REACH compliance mandates pushing converters toward certified kraft-paper substrates.
- Industrial Laminates:High-density phenolic-impregnated paper sheets engineered for electrical insulation, transformer cores, and mechanical applications. Demand clusters in South Asian and Southeast Asian markets where grid infrastructure expansion strains existing supply capacity.
- High-Pressure Laminates:Sheets cured above 7 MPa pressure delivering superior impact resistance and dimensional stability for heavy-traffic commercial surfaces.
- Low-Pressure Laminates:Bonded under 2-5 MPa onto MDF or particleboard backers, dominating residential cabinetry cost tiers.
Decorative laminates dominate installed base. Industrial laminates are where expansion concentrates.
End User:
Cost tier stratification separates specification-driven commercial contracts from price-sensitive residential procurement channels.
- Furniture:Surface materials for tables, case goods, and seating frames requiring scratch resistance and aesthetic consistency. German and Italian manufacturers are expanding decorative laminate procurement for cabinetry production.
- Flooring:Wear-layer applications in commercial and residential installations demanding slip resistance and acoustic dampening properties.
- Wall Panels:Vertical surfacing for commercial interiors and healthcare environments where antimicrobial specifications command premium positioning.
- Cabinets:Kitchen and storage unit surfacing represents the largest volume consumption segment, with China's Guangdong province integrated panel producers feeding construction and export channels.
Cabinets anchor volume throughput. Wall panels are climbing the fastest on infection-control renovation specifications.
Application:
Customer type determines certification burden: institutional buyers mandate chain-of-custody documentation while residential channels prioritize cost efficiency.
- Residential:Kitchen cabinets, flooring, and furniture surfacing where E0-grade indoor air quality standards in China disqualify uncertified imports. China's GB standards enforcement consolidates qualified supplier pools for panels entering commercial buildings.
- Commercial:Office interiors, hospitality, and retail environments requiring fire-rated and wear-tested surfacing materials with documented performance testing.
- Healthcare:Hospital and aged-care facilities specifying infection-control laminates with antimicrobial surface properties. Healthcare renovation contracts accelerate specification upgrades in clinical interiors.
- Education:Schools and universities balancing durability requirements against constrained capital budgets for furniture and fixture replacement.
Residential commands unit volume. Healthcare shows the steepest expansion trajectory behind antimicrobial surface specifications.
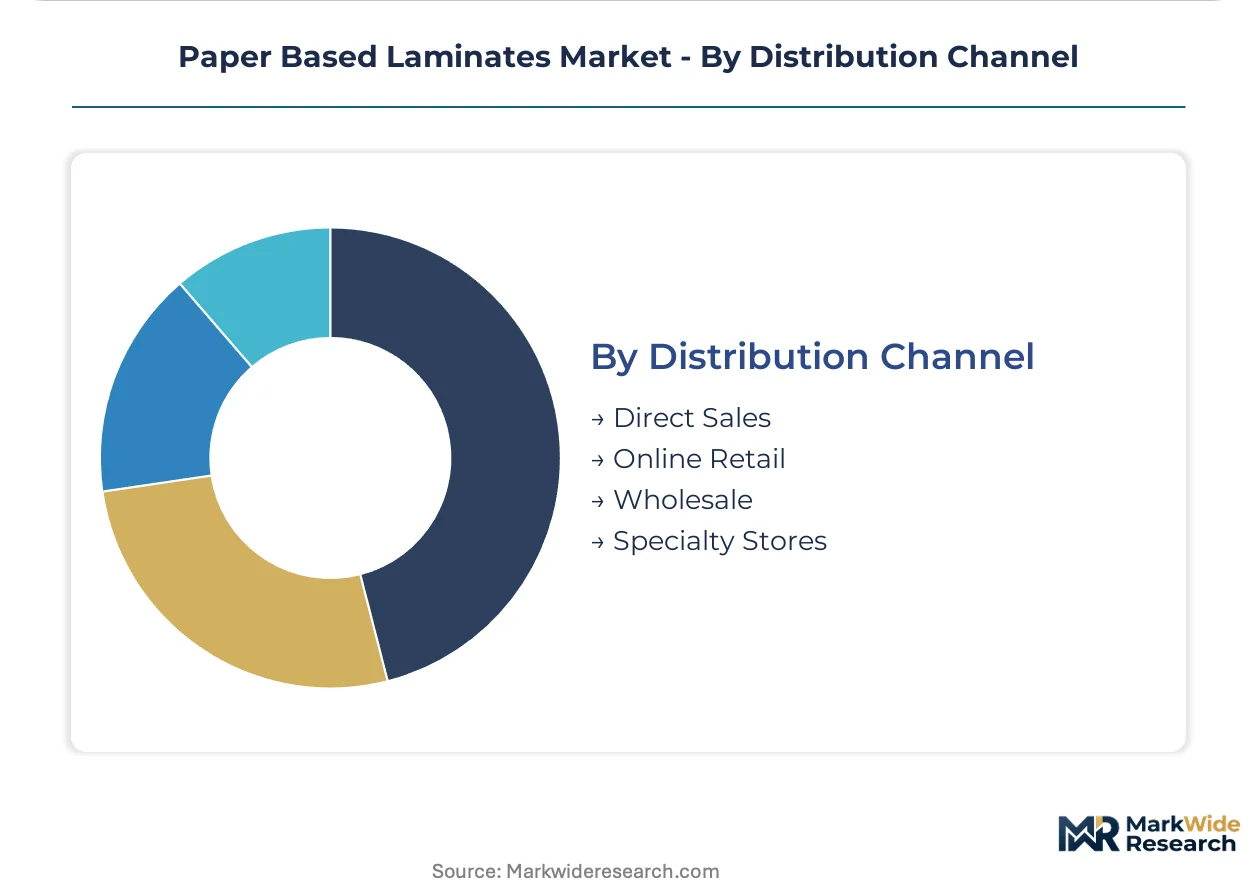
Distribution Channel:
Supply concentration in Nordic pulp mills and Guangdong province converters shapes which channels can guarantee certified substrate provenance.
- Direct Sales:Converter-to-fabricator relationships for large panel producers and OEM furniture manufacturers requiring technical collaboration on specification compliance. Panel producers in Guangdong province are bypassing traditional distribution tiers through integrated e-procurement portals.
- Online Retail:Digital platforms serving small-scale contractors and renovation contractors with standardized grade offerings and rapid fulfillment.
- Wholesale:Traditional distributor networks stocking inventory for regional fabrication shops and construction supply houses.
- Specialty Stores:Showroom-based specification support for architects and interior designers selecting premium decorative grades with chain-of-custody documentation.
Direct sales capture institutional contract value. Online retail is gaining share fastest among small-scale renovation contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized kraft paper mills in Nordic regions and Guangdong province control high-purity substrate flows, creating geographic chokepoints that shape converter procurement patterns worldwide.
China
Guangdong province's integrated panel producers feed construction and export channels with laminated cabinetry surfacing. GB standards for indoor air quality enforce E0-grade limits on finished panels entering commercial buildings. Shenzhen and Dongguan manufacturing clusters are consolidating qualified supplier pools as uncertified imports face disqualification.
Germany
Furniture manufacturers are expanding decorative laminate procurement for cabinetry and interior fittings across Baden-Württemberg and Bavaria. REACH compliance and the EU Green Deal's material traceability mandates push converters toward certified kraft-paper substrates. The Rhine-Main industrial corridor hosts specialized converters retrofitting lines with digital impregnation control systems.
United States
EPA formaldehyde emission standards under TSCA Title VI constrain adhesive formulations in US-bound panels, forcing reformulation investments at cross-border suppliers. Cabinetry producers in the Southeast and Midwest are shifting toward phenolic resin systems or seeking EPA-recognized third-party certification. North Carolina and Wisconsin fabrication hubs face compressed lead times from ISO 4586 testing timeline requirements.
Italy
Premium interior fittings manufacturers in Lombardy and Veneto are driving specification-driven procurement for decorative laminate surfacing. EU Green Deal material traceability mandates compress converter margins while forcing substrate certification upgrades. The Brianza furniture district anchors European demand for high-pressure decorative grades with chain-of-custody documentation.
India
Grid infrastructure expansion strains existing industrial laminate supply capacity for transformer core insulation across Maharashtra and Gujarat. Electrical equipment manufacturers face undersupply against transmission network buildout targets. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors are emerging as procurement centers for phenolic-impregnated paper sheets.
Paper Based Laminates Market Competitive Landscape
Integrated pulp-to-laminate chains and specialized substrate converters split the market between captive supply control and flexible procurement service models. Three archetypes dominate: Nordic pulp producers with backward integration into kraft paper grades, European converters with REACH-certified specialty lines, and Asian integrated panel manufacturers with direct-to-fabricator digital platforms. Consolidation pressure concentrates around M&A targeting certified substrate capacity and strategic partnerships bridging resin chemistry expertise gaps.
Among Nordic pulp producers with laminate-grade kraft paper operations, UPM-Kymmene and Mondi Group exemplify the integrated archetype controlling raw material quality for high-pressure decorative grades. WestRock anchors North American cabinetry supply through coated containerboard substrates. BillerudKorsnäs and Sappi Limited occupy positions within European specialty paper tiers serving industrial laminate backer specifications.
| Leading Market Players |
|---|
| UPM-Kymmene |
| BillerudKorsnäs |
| Amcor |
| Constantia Flexibles |
| Huhtamaki |
| Mondi Group |
| Sappi Limited |
| Sonoco |
| WestRock |
| Others |
Value Network & Pricing Analysis
Nordic kraft paper mills in Finland and Sweden concentrate high-purity substrate supply, anchoring margin capture upstream while downstream converters in Germany and Italy absorb certification cost compression from REACH mandates. Decorative laminate pricing stratifies across premium, standard, and economy tiers, with certified kraft-paper grades commanding substantial premiums over uncertified alternatives.
Pricing Analysis
Aftermarket refurbishment services now drive lifetime value capture, diverting maintenance budgets from virgin panel purchases toward recoating and overlay replacement contracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified decorative grades from industrial backer specifications and entry-level cabinetry surfacing. Cost compression in standard-tier laminates is intensifying because thin-film polymer substitutes compete for low-wear cabinetry applications. Residential cabinetry buyers exhibit highest price sensitivity, while healthcare procurement committees prioritize antimicrobial certification over unit cost.
Supply Chain Analysis
Contract manufacturing for high-pressure decorative grades concentrates among integrated panel producers in China's Guangdong province and specialized converters along Germany's Rhine-Main corridor. Raw material flows draw from Nordic pulp mills, South Asian phenolic resin producers, and regional MDF backer manufacturers. Single-source vulnerability runs through Guangdong's integrated producers, where digital e-procurement portals are bypassing traditional distribution tiers. Distribution runs through direct converter-to-fabricator relationships for large panel producers, supplemented by wholesale networks serving regional fabrication shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoset polymer expertise pools concentrate at legacy phenolic producers, creating a bottleneck for bio-based resin development that constrains R&D velocity across the industry. This capability scarcity rewards first-movers who secure resin chemistry talent or partnership access.
For Market Incumbents: Entrench certified substrate supply through backward integration into Nordic kraft paper mills or long-term offtake agreements with Guangdong panel producers. Secure REACH-compliant resin formulation capacity before carbon-border adjustments tighten qualified supplier pools. Defend against thin-film polymer substitutes by embedding digital impregnation control systems that guarantee thickness tolerances for premium interior fittings. For New Entrants and Emerging Players: Establish a beachhead in industrial laminate supply for transformer core insulation across South Asian markets, where grid infrastructure expansion strains existing capacity. Target healthcare renovation contracts specifying infection-control laminates, as antimicrobial surface requirements create specification barriers that favor specialized entrants over commodity converters. Pursue direct technical collaboration with architects and facility managers rather than distributor-led selling. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based resin certification pathways as EU carbon-border adjustment mechanisms reward verified renewable content. Long-term viability favors converters with integrated pulp-to-laminate chains or captive phenolic resin production. Watch for consolidation signals around M&A targeting certified substrate capacity, as qualified kraft-paper mill acquisitions separate viable platforms from margin-compressed assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | UPM-Kymmene and Mondi Group control raw material quality for high-pressure decorative grades through captive Nordic mills. |
| Bio-Based Resin Certification Program | Converters with verified renewable content gain first-mover advantage under EU carbon-border adjustment mechanisms. |
| Digital Impregnation Control Deployment | German and Italian cabinetry producers retrofit lines with real-time viscosity sensors to meet narrow thickness tolerances. |
| Direct-to-Fabricator E-Procurement Portal | Guangdong panel producers bypass traditional distribution tiers, capturing margin from integrated digital platforms. |
| Antimicrobial Surface Specification Development | Healthcare renovation contracts accelerate demand for infection-control laminates with documented chain-of-custody. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across laminate converters, furniture manufacturers, and electrical equipment OEMs. Primary interviews with plant managers at Nordic pulp mills, procurement leads at German cabinetry producers, and technical R&D directors at resin formulators were cross-referenced against secondary validation from customs trade data, SEC filings of integrated paper producers, REACH registration databases, and GB standards enforcement records. Bottom-up volume estimates from panel production capacities were triangulated against top-down spending analysis across construction and healthcare renovation sectors.
Calibration against historical price realizations and capacity utilization rates anchored projections across the analysis window. Segmentation dimensions modeled include product type (decorative versus industrial laminates), curing pressure tier (high-pressure versus low-pressure), end-use application (furniture, flooring, wall panels, cabinets), and regional regulatory cluster (REACH-compliant Europe, EPA-constrained North America, GB-standard China). CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure investment cycles and renovation spending patterns.
Stress conditions across phenolic resin price volatility, kraft paper supply disruptions, and regulatory timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of antimicrobial specification adoption rates, carbon-border adjustment implementation timelines, and transformer core insulation order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Chemical Pulp Market
Paper Products
Carbonless Paper Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Cheque Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Pulp Market
Paper Products
Global Security Paper Market
Paper Products
Acrylic Paper Market
Paper Products
White Top Testliner Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Fluff Pulp Market
Paper Products
Solar Paper Market
Paper Products
Printing Paper Market
Paper Products
Global Thin Papers Market