
 Carpet Adhesive Market | 2026-2036
Carpet Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Adhesive Market Analytics
The split between premium specification-grade carpet adhesives and commodity bulk formulations is rebalancing as commercial contractors tighten VOC compliance and residential builders prioritize cost-per-square-meter. H.B. Fuller leverages its polyurethane technology leadership to anchor high-performance commercial specifications. Bostik competes through geographic dominance in European flooring distribution channels. Sika AG differentiates via vertical integration into construction chemicals that bundle adhesives with complementary subfloor systems.
Carpet adhesive comprises bonding agents formulated from polyurethane, acrylic, latex, or epoxy bases, designed to secure carpet materials to subfloors with specified peel strength and open-time parameters. Water-based formulations dominate residential volume due to lower odor profiles and simplified cleanup, while pressure-sensitive adhesives capture expanding share in commercial modular carpet tile installations where removability drives specification. Hot melt systems occupy industrial and sports facility segments where rapid set speed offsets higher application equipment requirements.
EPA VOC regulations in the United States and EU REACH compliance frameworks in Europe directly constrain solvent-based formulation availability, redirecting R&D investment toward water-based and bio-based polymer platforms. OSHA workplace exposure standards further shape installer-side product selection in commercial construction. Stakeholders must monitor evolving state-level chemical disclosure requirements and certification shifts from Green Seal to Cradle to Cradle as these will determine which material platforms retain specification access across major end-use channels.
Market Dynamics
EPA VOC limits and EU REACH compliance are compressing solvent-based formulation availability while redirecting R&D investment toward water-based and bio-based polymer platforms across commercial and residential channels.
Growth Catalysts
- Healthcare Retrofit Cycles:Hospital renovation schedules in the United States sustain specification-grade adhesive procurement through infection-control flooring upgrades requiring rapid-cure, low-odor systems.
- REACH Phase-Down Mandates:ECHA restrictions on volatile organic compounds in construction products are accelerating water-based formulation adoption across German, French, and Dutch commercial flooring contractors.
- Modular Carpet Tile Expansion:Pressure-sensitive adhesive demand is concentrating in commercial office fit-outs where removability and reconfiguration flexibility dominate specification criteria.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane precursor costs fluctuate with crude oil derivatives, compressing margin stability for formulation houses dependent on isocyanate supply chains.
- Specialty Additive Concentration:Performance-enhancing rheology modifiers and bio-based plasticizers source predominantly from German and Swiss chemical suppliers, creating geographic supply risk.
- Cure Speed Limitations:Water-based systems require extended open times and controlled humidity conditions, restricting deployment in cold-climate winter construction windows.
Strategic Opportunities
- Indian Commercial Real Estate:IT park and co-working space construction in Bengaluru, Hyderabad, and Mumbai is generating specification-grade demand currently served by imported formulations.
- Green Building Certification Tailwinds:LEED v4.1 and BREEAM point structures reward low-emitting adhesives, creating specification pull for Cradle to Cradle certified products in premium commercial segments.
- Hybrid Polymer Convergence:Silane-terminated polyurethane technology is bridging the performance gap between conventional urethanes and acrylics, enabling single-product platforms across substrate types.
Industry Challenges
- Certification Timeline Compression:Green Seal and FloorScore recertification cycles demand continuous reformulation investment as emission thresholds tighten, straining mid-tier manufacturer R&D bandwidth.
- Installer Skill Stratification:Application technique requirements for moisture-cure urethanes and epoxy systems outpace vocational training availability in secondary US metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Adhesive Market |
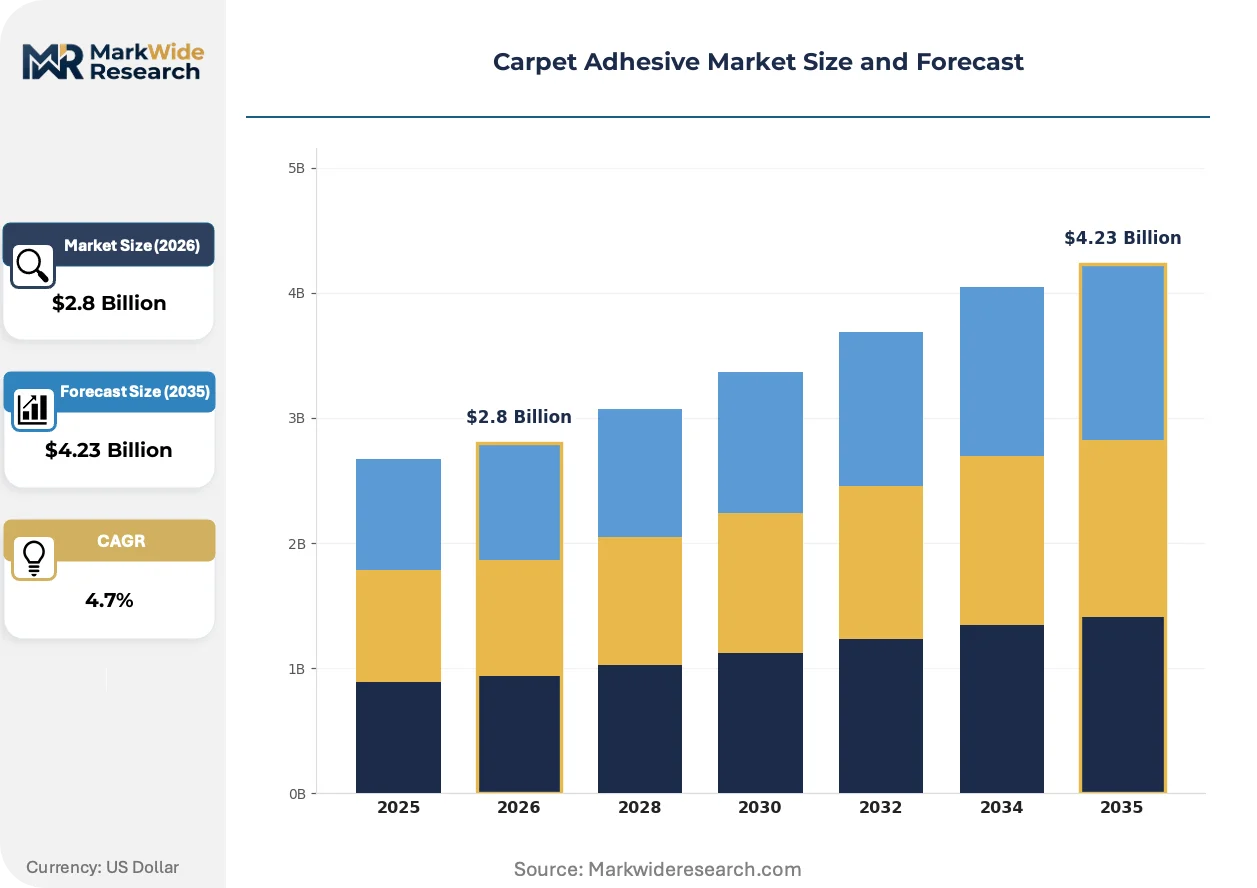
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential, Commercial, Industrial, Sports Facilities Type: Water-Based, Solvent-Based, Pressure-Sensitive, Hot Melt Material: Polyurethane, Acrylic, Latex, Epoxy Packaging Type: Drums, Buckets, Tubs, Sachets |
| Companies Covered | H.B. Fuller, Bostik, Henkel AG & Co. KGaA, MAPEI, Sika AG, Dow, Forbo Holdings AG, Wacker Chemie AG, LATICRETE International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Adhesive Market Evolving Landscape
Bio-based polymer feedstocks, regulatory disclosure mandates, and procurement centralization are restructuring how carpet adhesive specifications flow from manufacturer to subfloor.
Hybrid silane-modified polyurethane technology is decentralizing the traditional split between residential water-based and commercial solvent-based product categories. Multi-family housing developers in Texas and Florida are specifying these systems for combined carpet and luxury vinyl tile installations. The technology is decentralizing procurement decisions away from substrate-specific product lines toward unified flooring adhesive platforms.
REACH SCIP database requirements and US state-level chemical disclosure laws in California and New York are forcing formulation transparency down to 0.1% w/w substance thresholds. Manufacturers must now map full supply chain chemistry or forfeit specification access in public-sector construction. Commercial contractors in the Netherlands and Belgium are prioritizing suppliers with pre-submitted SCIP declarations to avoid project delays.
Consolidated procurement through national flooring distributors is compressing regional adhesive brand diversity. Large commercial contractors in the United Kingdom are centralizing purchasing through Wolseley and SIG distribution networks, displacing direct manufacturer relationships. This concentration is most visible in London and Southeast England office renovation markets where specification authority has shifted from installers to distributor technical teams.
Carpet Adhesive Market Segmentation
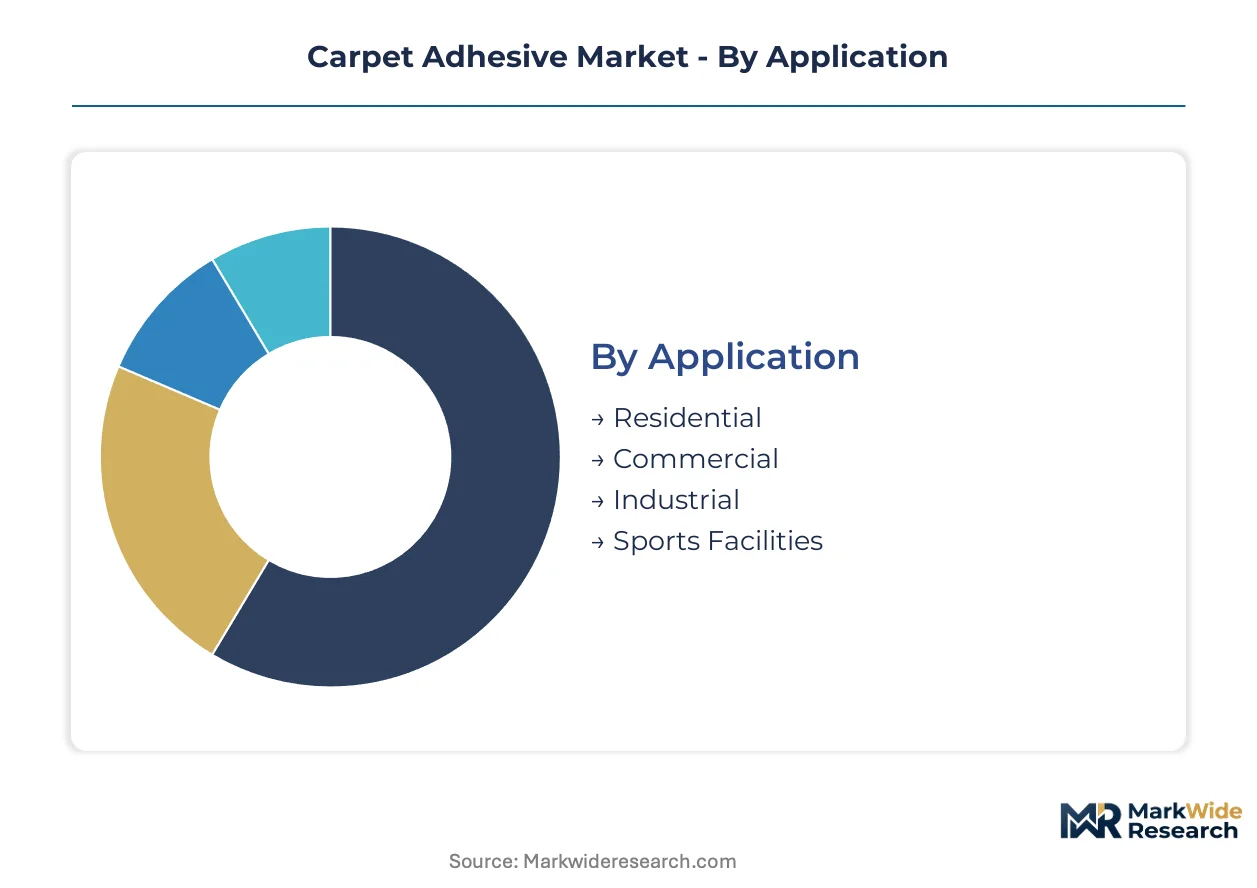
Carpet adhesive specifications diverge sharply across installation environments, with formulation chemistry and packaging logistics calibrated to project scale, substrate demands, and regulatory exposure. Segmentation reveals how procurement authority concentrates in commercial channels while residential volume sustains commodity formulation economics.
Application:
Volume concentrates in residential roll-goods installation, but premium pricing and specification-grade compliance concentrate in commercial retrofit cycles.
- Residential:Water-based latex formulations dominate this channel due to lower odor profiles and consumer-friendly cleanup protocols. Demand clusters in United States single-family construction and multi-family housing developments across Texas and Florida, where builder-grade procurement prioritizes cost-per-square-meter over extended durability specifications.
- Commercial:Pressure-sensitive and moisture-cure urethane systems capture specification authority in office fit-outs, hospitality renovations, and healthcare facility upgrades. German commercial contractors are expanding procurement of low-VOC formulations ahead of tightened ECHA phase-down mandates.
- Industrial:Epoxy-based systems with enhanced chemical resistance serve manufacturing floors and warehouse facilities requiring heavy-load tolerance.
- Sports Facilities:Rapid-cure polyurethane platforms address installation windows in gymnasiums and arena surfaces where downtime minimization drives adhesive selection.
Mature deployment sits with Residential. Newer deployment is concentrated in Commercial.
Type:
Regulatory pressure on volatile organic compound emissions is accelerating substitution patterns between conventional solvent platforms and compliant water-based alternatives.
- Water-Based:Acrylic and latex polymer dispersions deliver simplified application and reduced installer exposure. United States residential builders specify these systems for their alignment with EPA VOC limits and Green Seal certification pathways.
- Solvent-Based:Traditional urethane and neoprene formulations retain niche specification in cold-climate construction where rapid cure speed overrides emission concerns. Availability is compressing under REACH and state-level disclosure requirements in California and New York.
- Pressure-Sensitive:Permanent-tack acrylics enable modular carpet tile removability in commercial office reconfigurations. Dutch and Belgian contractors prioritize suppliers with pre-submitted SCIP database declarations to avoid project delays.
- Hot Melt:Thermoplastic formulations deliver sub-60-second set speeds for industrial-scale sports facility installations requiring minimal downtime.
Specification authority is migrating fastest toward Pressure-Sensitive platforms in commercial channels.
Material:
Polymer selection directly determines peel strength, open-time windows, and compatibility with moisture-barrier subfloor systems.
- Polyurethane:Moisture-cure and silane-terminated systems anchor high-performance commercial specifications requiring superior dimensional stability and substrate adhesion. H.B. Fuller technology leadership concentrates in this material platform.
- Acrylic:Water-borne dispersions serve residential volume and pressure-sensitive commercial applications where cost efficiency and simplified cleanup outweigh extreme durability requirements.
- Latex:Styrene-butadiene and natural rubber emulsions retain commodity positioning in residential carpet padding attachment and budget-tier installations.
- Epoxy:Two-component systems penetrate industrial flooring and heavy-traffic commercial environments demanding chemical resistance and load-bearing capacity.
Hybrid silane-modified polyurethane formulations are bridging performance gaps across material categories.
Packaging Type:
Packaging configuration aligns with project scale, installer workflow, and distributor logistics rather than formulation chemistry.
- Drums:Bulk containers serve large-scale commercial contractors and national flooring distributors consolidating procurement through Wolseley and SIG networks in the United Kingdom.
- Buckets:Mid-volume packaging dominates residential and light commercial installations where portability and partial-use convenience matter.
- Tubs:Wide-mouth containers facilitate trowel access for thick-bed adhesive application in heavy-traffic specifications.
- Sachets:Single-use pouches address repair work, small-area installations, and markets with limited cold-chain storage infrastructure.
Drum and bucket formats are gaining procurement share through distributor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's commercial office renovation cluster drives specification-grade adhesive procurement across Germany, with hospital retrofit cycles in Texas and Florida sustaining parallel demand corridors in the United States.
United States
Healthcare facility upgrades in Houston and Miami sustain moisture-cure urethane demand for infection-control flooring systems. EPA VOC limits under the Clean Air Act constrain solvent-based formulation availability in California and New York state procurement. Dallas-Fort Worth multi-family developers specify hybrid silane-modified systems for combined carpet and LVT installations.
Germany
Commercial office fit-outs in Berlin and Hamburg accelerate low-VOC water-based adhesive adoption ahead of ECHA phase-down mandates. REACH SCIP database requirements force formulation transparency to 0.1% substance thresholds for public-sector construction. Bavarian flooring contractors consolidate procurement through distributor technical teams rather than direct manufacturer relationships.
India
IT park construction in Bengaluru and Hyderabad generates specification-grade demand currently served by imported polyurethane formulations. BIS certification requirements for construction chemicals create compliance barriers for regional manufacturers. Mumbai co-working space developers prioritize rapid-cure systems to minimize installation downtime in high-occupancy buildings.
United Kingdom
London office renovation markets shift specification authority toward Wolseley and SIG distribution networks. HSE workplace exposure standards shape installer-side product selection in commercial construction. Southeast England contractors prioritize suppliers with pre-submitted environmental product declarations for BREEAM point accumulation.
Netherlands
Dutch commercial flooring contractors demand SCIP-declared pressure-sensitive adhesives for modular carpet tile installations in Amsterdam and Rotterdam. EU Green Deal construction product regulations accelerate bio-based polymer platform adoption. Belgian distributors extend procurement consolidation patterns across the Benelux region.
Carpet Adhesive Market Competitive Landscape
Capital-heavy producers with captive polymer supply chains compete with asset-light formulation specialists sourcing additives from third-party chemical houses. The vendor base concentrates among diversified construction chemical conglomerates, regional flooring distributors with private-label portfolios, and specialty adhesive houses with polyurethane technology leadership. Three archetypes dominate: specification-grade technology leaders, geographic channel captors, and vertically integrated construction chemical bundlers. Competitive moves center on distributor consolidation through national flooring networks and hybrid polymer R&D convergence across material categories.
Among diversified chemical conglomerates, H.B. Fuller, Bostik, and Sika AG occupy positions spanning multiple competitive archetypes. H.B. Fuller exemplifies technology leadership in moisture-cure and silane-terminated polyurethane platforms. Bostik represents geographic channel dominance through European flooring distribution penetration. Sika AG anchors vertically integrated construction chemical positioning, bundling adhesives with complementary subfloor preparation systems. Henkel AG & Co. KGaA and MAPEI sit within the same tier, competing through formulation breadth and regional manufacturing presence. Dow and Wacker Chemie AG supply upstream polymer building blocks that downstream formulators depend upon, creating captive demand relationships across the value chain.
| Leading Market Players |
|---|
| H.B. Fuller |
| Bostik |
| Henkel AG & Co. KGaA |
| MAPEI |
| Sika AG |
| Dow |
| Forbo Holdings AG |
| Wacker Chemie AG |
| LATICRETE International, Inc. |
| Others |
Value Network & Pricing Analysis
Consolidated procurement through national flooring distributors in the United Kingdom and Germany anchors value-based pricing tied to specification-grade performance outcomes rather than commodity volume metrics. Pricing stratifies across premium, standard, and economy tiers calibrated to certification level and project scale.
Pricing Analysis
Performance-linked pricing tied to peel strength guarantees and open-time windows dominates specification-grade commercial channels. Price differentiation separates Cradle to Cradle certified formulations from builder-grade alternatives through compliance investment and technical service bundling. Cost compression in water-based residential tiers intensifies because of petrochemical feedstock volatility and Asian import competition. Residential builders in Texas and Florida exhibit highest price sensitivity, while German hospital procurement committees prioritize emission compliance over unit cost.
Supply Chain Analysis
Skilled formulation chemist availability in Germany, Switzerland, and the Netherlands constrains specialty additive production capacity for rheology modifiers and bio-based plasticizers. Polyurethane precursor supply draws from isocyanate production clusters in Belgium and the Netherlands, with acrylic dispersions sourcing from German chemical complexes. Single-source vulnerability concentrates in Swiss suppliers of performance-enhancing additives. Distribution runs through Wolseley and SIG networks in the United Kingdom, with Bostik and Sika AG maintaining direct contractor relationships in German commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carpet adhesive market is becoming a vertical-integration race as players pursue captive control over silane-terminated polyurethane precursor supply to defend margin position against petrochemical volatility.
For Market Incumbents: Deploy hybrid polymer R&D convergence to unify residential and commercial product lines under single-platform specifications. Consolidate distributor technical team relationships in London and Southeast England to preempt specification authority migration. Counter emerging pressure-sensitive adhesive specialists through pre-submitted REACH SCIP database declarations that accelerate contractor procurement decisions. For New Entrants and Emerging Players: EU Green Deal construction product regulations in the Netherlands and Belgium open a window for bio-based polymer platforms targeting BREEAM point accumulation in premium commercial fit-outs. Focus initial penetration on Indian IT park construction in Bengaluru and Hyderabad where specification-grade demand exceeds domestic supply capacity. Pursue rapid-cure system positioning to minimize installation downtime in high-occupancy Mumbai co-working developments. For Investors and Strategic Acquirers: The window for entry favors mid-tier formulation houses with captive additive sourcing relationships and pre-certified emission compliance portfolios. Long-term viability hinges on backward integration into polymer building blocks or downstream control through distributor network ownership. Watch for ECHA phase-down mandate acceleration as the inflection signal triggering consolidation among solvent-dependent regional manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursors | Captive isocyanate supply secures margin stability against crude derivative volatility. |
| REACH SCIP Database Pre-Submission | Pre-declared formulations accelerate Dutch and Belgian contractor procurement decisions. |
| Hybrid Silane-Modified Polymer Launch | Single-platform systems capture multi-family housing specifications in Texas and Florida. |
| Distributor Technical Team Partnership | Wolseley and SIG network relationships shift specification authority toward integrated suppliers. |
| Bio-Based Platform Certification Investment | Cradle to Cradle pathways unlock LEED v4.1 point structures in premium commercial segments. |
Research Methodology
Multi-period observation of formulation technology shifts and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with commercial flooring contractors, distributor technical directors, adhesive R&D chemists, and hospital procurement managers. Secondary validation drew from ECHA substance restriction databases, EPA VOC limit filings, customs trade records for polyurethane precursors, and SEC disclosures from construction chemical conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across application segments.
Segment-weighting applied differential growth assumptions to water-based residential formulations versus pressure-sensitive commercial systems across the projection horizon. Modeling incorporated material chemistry, packaging format, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from fitted trend extrapolation adjusted for ECHA phase-down implementation pacing and healthcare retrofit cycle timing. Forecast inputs included petrochemical feedstock price indices and Green Seal certification threshold evolution.
The model assumes a particular technology adoption path; alternative pathways for silane-modified polyurethane convergence would alter the outlook if moisture-cure systems retain substrate-specific dominance. Forecasts reflect assumptions regarding REACH enforcement consistency and Indian BIS certification timeline progression. Material deviation in ECHA substance restriction acceleration or crude oil derivative volatility spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Flooring Adhesive Market