
 India Tile Adhesive Market | 2026-2036
India Tile Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
India Tile Adhesive Market Outlook
Multi-source procurement among large construction firms is expanding as developers diversify away from single-brand dependencies for critical flooring and wall tiling projects. Sika India leverages its Swiss parent company's polymer technology portfolio to sustain premium positioning in epoxy-based systems. Pidilite Industries anchors the mass-market tier through extensive hardware store distribution across tier-2 and tier-3 cities. MYK LATICRETE INDIA PVT LTD specializes in contractor-direct technical service models that differentiate it in complex commercial applications.
India tile adhesive comprises cementitious or resin-based bonding compounds formulated with Portland cement, graded silica sand, and redispersible polymer powders to achieve shear adhesion strengths exceeding 1.0 N/mm² for ceramic and vitrified tile installation. The primary commercial purpose is to eliminate void formation and moisture ingress at the tile-substrate interface, particularly critical for high-rise exterior cladding where wind loads and thermal cycling stress conventional mortar. Cement-based formulations occupy the volume core due to cost accessibility across residential flooring, though polymer-modified systems are capturing margin pools in demanding wall tiling and outdoor segments where flexibility and waterproofing specifications command price premiums. Epoxy-based adhesives lead the technical frontier for chemical-resistant industrial flooring, while hardware stores remain the dominant distribution channel despite online retail encroachment in contractor replenishment buying.
BIS mandates IS 15477 compliance for cement-based tile adhesives, while the CEA's building energy codes indirectly shape product selection through thermal performance requirements for envelope systems. The DGFT's import tariff structures on raw polymer emulsions influence domestic formulation economics and backward integration incentives among manufacturers. Stakeholders must monitor how impending amendments to India's National Building Code affect specification thresholds for high-rise tile cladding, as these will determine whether epoxy and polymer-modified systems displace conventional cementitious products in structural exterior applications.
Market Dynamics
Polymer-modified formulations are electrifying specification preferences across India's high-rise construction sector, as developers confront wind-load and thermal-cycling stresses that conventional cementitious systems cannot reliably manage. BIS certification thresholds under IS 15477 are simultaneously compressing the supplier base, forcing reformulation investments that favor capital-backed manufacturers over commodity compounders.
Growth Catalysts
- Mumbai-Pune corridor concentration:Metro rail expansion and slum rehabilitation projects sustain bulk procurement volumes for polymer-modified adhesives in Maharashtra's dense urban corridor.
- IS 15477 compliance mandates:BIS tightening of cement-based tile adhesive standards is accelerating displacement of unorganized compounders by certified manufacturers.
- Epoxy system penetration:Chemical-resistant industrial flooring specifications in pharmaceutical and food processing plants are pulling premium resin-based formulations into commercial segments.
Market Restraints
- Redispersible polymer powder import dependency:DGFT tariff structures on raw polymer emulsions inflate formulation costs for domestic manufacturers lacking backward integration into emulsion production.
- Skilled applicator scarcity:Epoxy and specialized polymer-modified systems require trained contractor labor that remains concentrated in tier-1 cities, constraining penetration into tier-2 and tier-3 markets.
- Cement price volatility:Portland cement input costs fluctuate with energy and logistics pricing, compressing margins on volume-dominant cementitious formulations.
Strategic Opportunities
- Tamil Nadu and Karnataka underpenetration:Southern states outside Kerala show adhesive penetration gaps in residential flooring, creating whitespace for hardware store distribution expansion.
- CEA thermal performance codes:Building energy efficiency mandates for envelope systems are creating specification pathways for polymer-modified adhesives in exterior cladding applications.
- Contractor-direct technical service models:Complex commercial projects favor suppliers offering on-site application support, differentiating against hardware-store-dependent competitors.
Industry Challenges
- IS 15477 certification timelines:BIS testing protocols and documentation requirements delay product launches by 8-14 months, constraining rapid response to formulation innovations.
- Hardware store inventory fragmentation:Mass-market distribution through thousands of independent retailers complicates brand consistency and technical training at the point of sale.
- Substrate variability in field conditions:Inconsistent surface preparation standards across India's construction labor force generate application failures that damage brand reputation regardless of product quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Tile Adhesive Market |
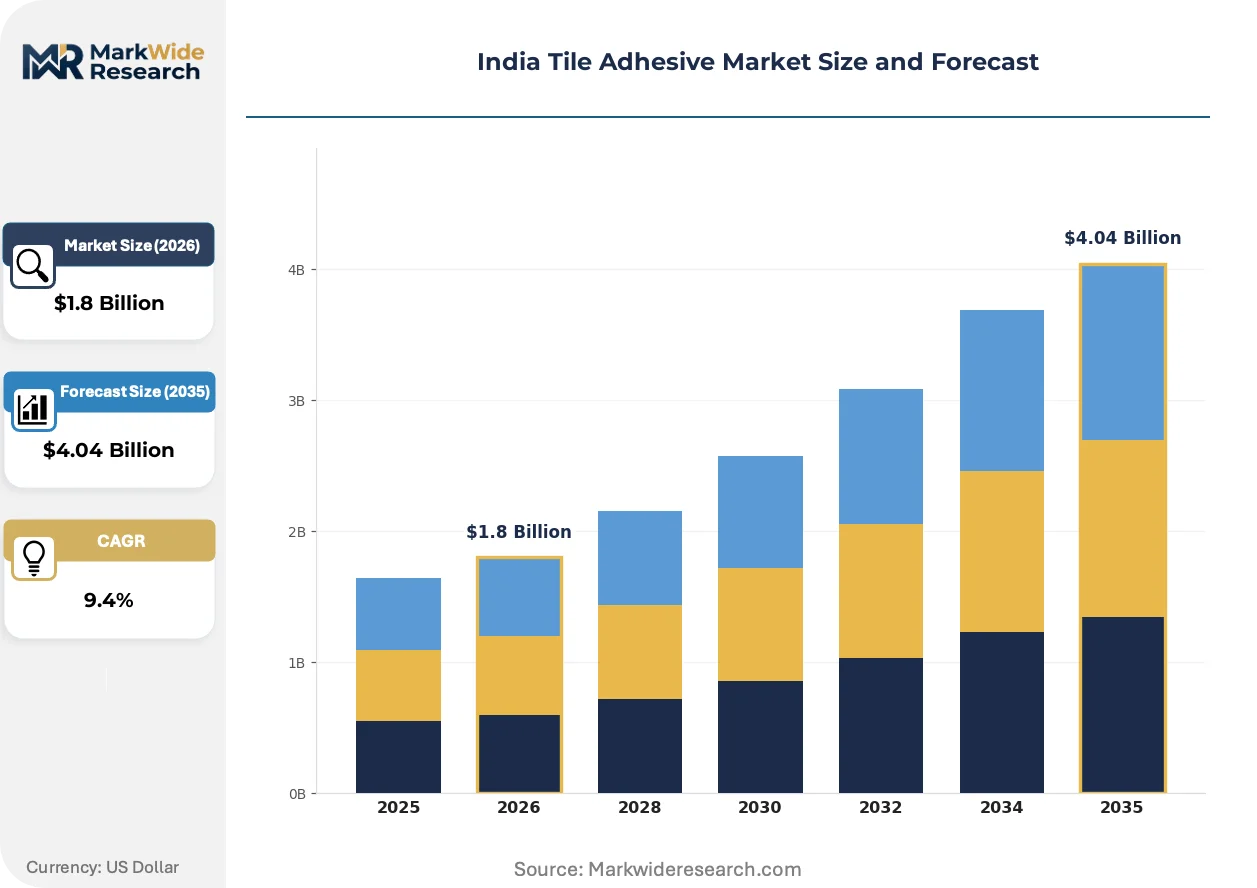
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement-Based, Epoxy-Based, Polymer-Modified, Others Application: Flooring, Wall Tiling, Outdoor, Interior Finishing Distribution Channel: Online Retail, Wholesale, Direct Sales, Hardware Stores End User: Contractors, Homeowners, Construction Companies, Architects |
| Companies Covered | Fosroc India, Sika India, Pidilite Industries, Kajaria Ceramics Limited, Henkel AG & Co. KGaA, MYK LATICRETE INDIA PVT LTD, BASF India Ltd, H.B. Fuller Company, Saint-Gobain Weber, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Tile Adhesive Market Strategic Shifts
Formulation chemistry and specification behavior are diverging sharply across India's construction value chain, with premium systems electrifying high-rise applications while cost-engineered compounds defend residential flooring volumes. Three interconnected developments are compressing traditional competitive boundaries.
Hybrid polymer-cement systems are electrifying facade specification preferences among Mumbai and Pune developers confronting IS 15477 performance thresholds for wind-load resistance. These formulations combine Portland cement bases with styrene-acrylic or vinyl acetate-ethylene copolymers to achieve shear adhesion above 1.5 N/mm². High-rise contractors are specifying hybrid systems at accelerating rates for exterior cladding, compressing market share for conventional thick-bed mortar applications.
BIS amendments to IS 15477 testing protocols are mandating extended water immersion and freeze-thaw cycling for cement-based adhesive certification. The industrial consequence is laboratory investment requirements that exclude small compounders from formal compliance. Maharashtra and Gujarat manufacturers with captive testing facilities are capturing specification share in government-funded infrastructure projects where BIS certification is contractually mandatory.
Multi-brand procurement contracts are consolidating purchasing power among large residential developers operating across the Mumbai-Pune corridor. Developer technical teams now specify approved manufacturer lists rather than single-source dependencies, forcing adhesive suppliers to compete on application support and inventory reliability. This pattern is most visible in slum rehabilitation authority projects where bulk volumes and penalty clauses for stockouts favor suppliers with regional warehousing infrastructure.
India Tile Adhesive Market Segmentation
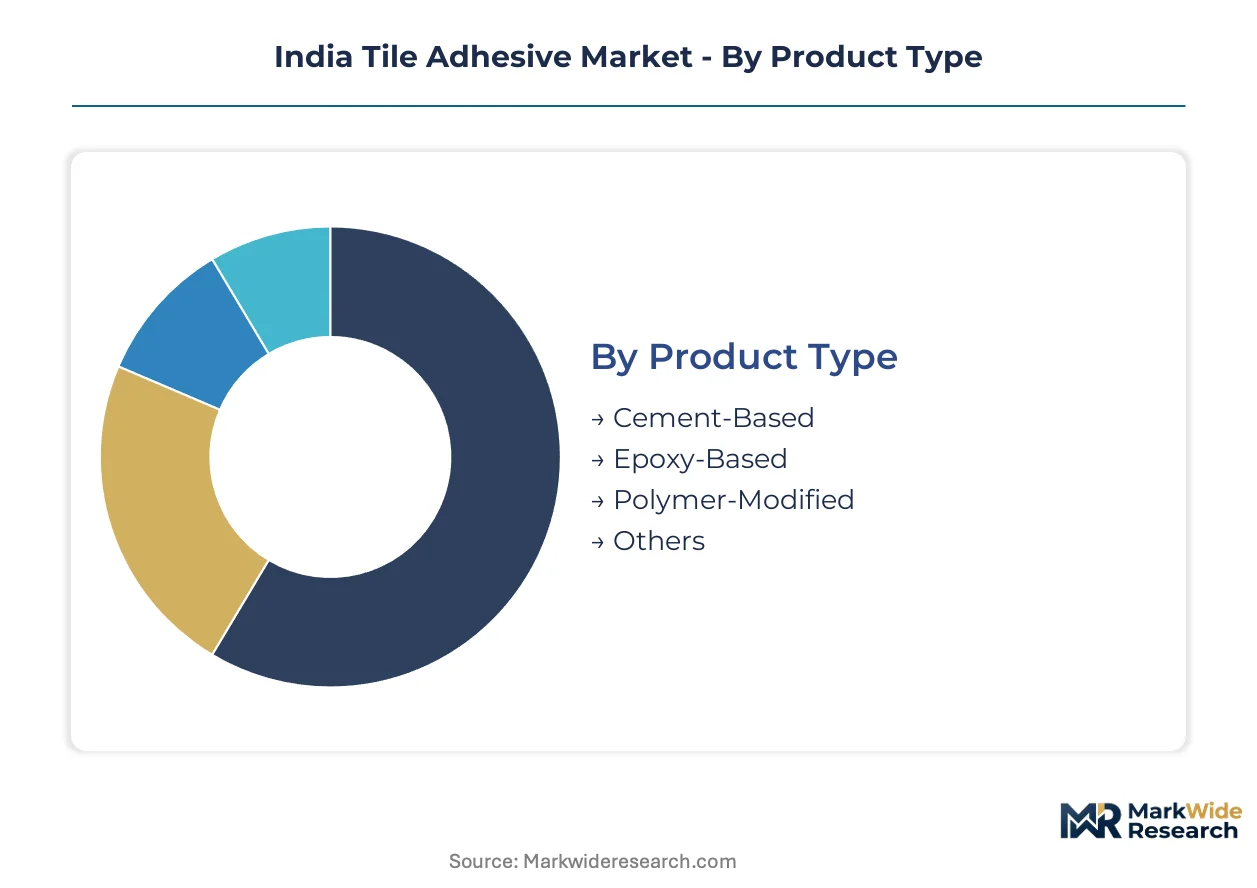
India's tile adhesive market fragments across formulation chemistry, application intensity, and procurement behavior. Each segmentation axis reveals distinct margin pools and competitive entry barriers that shape supplier positioning strategies.
Product Type:
Cement-based formulations dominate procurement volumes across cost-sensitive residential flooring, while polymer-modified and epoxy systems capture specification premiums in demanding commercial applications.
- Cement-Based:Portland cement bonded with graded silica sand occupies the volume core through hardware store accessibility. Demand concentrates in Maharashtra's Mumbai-Pune corridor slum rehabilitation projects where bulk procurement favors lowest-cost compliant formulations meeting IS 15477 baseline thresholds.
- Polymer-Modified:Styrene-acrylic or vinyl acetate-ethylene copolymers blended with cement bases achieve shear adhesion exceeding 1.5 N/mm². High-rise facade developers in Mumbai specify these systems for wind-load resistance, displacing conventional thick-bed mortar in exterior cladding applications.
- Epoxy-Based:Two-component resin systems command technical premiums in pharmaceutical and food processing plant flooring where chemical resistance specifications apply.
- Others:Specialty formulations including polyurethane and silicone-modified systems serve niche industrial substrates.
Volume sits with cement-based compounds; growth tilts toward polymer-modified formulations.
Application:
Surface exposure conditions and structural load requirements differentiate adhesive specification behavior across India's construction value chain.
- Flooring:Cementitious systems anchor residential volume through cost accessibility and simpler application protocols. Tier-2 and tier-3 city hardware stores move flooring adhesives in bagged quantities for independent contractor purchase.
- Wall Tiling:Vertical installation demands higher shear adhesion and sag resistance, pulling polymer-modified formulations into specification. Mumbai high-rise contractors increasingly reject conventional mortar for interior wall applications above 15 stories.
- Outdoor:Thermal cycling and moisture exposure mandate waterproofing performance that cement-based systems struggle to deliver consistently.
- Interior Finishing:Lower-stress residential applications tolerate economy-grade formulations with reduced polymer loading.
Flooring absorbs the largest volume share; wall tiling applications are climbing the fastest as high-rise construction intensifies.
Distribution Channel:
Procurement scale and technical support requirements fragment channel strategy across India's adhesive suppliers.
- Hardware Stores:Thousands of independent retailers in tier-2 and tier-3 cities anchor mass-market cementitious sales. Pidilite Industries leverages this infrastructure for homeowner and small contractor access.
- Direct Sales:Large construction companies and slum rehabilitation authorities negotiate multi-brand procurement contracts with approved manufacturer lists. Regional warehousing infrastructure determines supplier eligibility for these penalty-clad agreements.
- Wholesale:Distributor networks serve mid-tier contractors with inventory consolidation and credit terms.
- Online Retail:Contractor replenishment buying migrates toward digital platforms for standardized product reordering.
Hardware stores retain volume dominance; direct sales channels show the steepest expansion trajectory as developer procurement consolidates.
End User:
Technical sophistication and project scale separate adhesive buyers into distinct service requirement tiers.
- Construction Companies:Slum rehabilitation authorities and metro rail contractors specify BIS-certified products with mandatory batch testing documentation. These buyers demand inventory reliability and penalty protection against stockouts.
- Contractors:Skilled applicators in tier-1 cities drive specification of polymer-modified and epoxy systems requiring trained labor. MYK LATICRETE INDIA targets this segment with on-site technical service differentiation.
- Architects:Design-phase influencers specify performance thresholds that constrain downstream procurement choices, particularly for facade cladding.
- Homeowners:Price-sensitive retail buyers in tier-2 and tier-3 markets rely on hardware store recommendations without independent technical assessment.
Construction companies command the largest procurement volumes; contractor-direct relationships are gaining share fastest in complex commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Maharashtra's Mumbai-Pune corridor, where metro rail expansion and slum rehabilitation projects sustain bulk procurement volumes for polymer-modified adhesives.
Maharashtra
Metro rail expansion and slum rehabilitation authorities drive bulk procurement volumes across Mumbai and Pune. BIS mandates IS 15477 compliance for all cement-based tile adhesives in government-funded infrastructure. The Mumbai-Pune industrial corridor hosts the highest concentration of certified adhesive manufacturers serving high-rise facade applications.
Gujarat
Pharmaceutical and food processing plant construction pulls premium epoxy-based formulations into industrial flooring specifications. DGFT tariff structures on raw polymer emulsions influence formulation economics for domestic compounders. The Ahmedabad-Surat belt anchors chemical-resistant adhesive demand from processing facility expansions.
Karnataka
Residential flooring penetration gaps in Bengaluru's peripheral districts create whitespace for hardware store distribution expansion. CEA building energy codes shape specification pathways for exterior cladding adhesives in commercial envelope systems. The Bengaluru-Chennai industrial corridor shows accelerating specification of polymer-modified systems for IT park construction.
Tamil Nadu
Automotive and electronics manufacturing clusters generate specialized industrial flooring demand across Chennai and Coimbatore. State-level building codes increasingly reference BIS standards for construction chemical compliance. The Sriperumbudur-Oragadam automotive belt sustains procurement of chemical-resistant adhesive systems for plant flooring.
Delhi-NCR
High-rise residential towers in Gurugram and Noida intensify specification of wind-load-resistant facade adhesives. The National Building Code amendments under review will tighten performance thresholds for exterior tile cladding. The NCR construction corridor represents the most price-sensitive volume market for cementitious formulations.
India Tile Adhesive Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers invest in captive testing facilities to accelerate IS 15477 certification timelines. The supplier base compresses into three tiers: capital-backed integrated manufacturers, regional compounders with limited backward integration, and unorganized local blenders facing compliance displacement. Strategic archetypes separate polymer technology licensors from hardware-store-dependent mass-market suppliers and contractor-direct technical service specialists. M&A activity and regional warehousing infrastructure deployment constitute the dominant competitive moves.
Among foreign-origin integrated manufacturers, Sika India, Henkel AG & Co. KGaA, and BASF India Ltd represent the technology-licensing tier leveraging parent-company polymer portfolios. These entities occupy positions where premium formulation capabilities intersect with BIS certification infrastructure. Pidilite Industries and MYK LATICRETE INDIA PVT LTD exemplify contrasting distribution archetypes—mass-market hardware store penetration versus contractor-direct technical service models. Saint-Gobain Weber and Fosroc India sit within the construction-chemical-specialist cluster where cross-selling opportunities with waterproofing and repair mortars reinforce adhesive positioning.
| Leading Market Players |
|---|
| Fosroc India |
| Sika India |
| Pidilite Industries |
| Kajaria Ceramics Limited |
| Henkel AG & Co. KGaA |
| MYK LATICRETE INDIA PVT LTD |
| BASF India Ltd |
| H.B. Fuller Company |
| Saint-Gobain Weber |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between BIS-compliant manufacturers and unorganized compounders manifests in divergent pricing power and procurement channel configurations across India's tile adhesive market. Polymer-modified systems command application-support premiums through direct sales channels, while cementitious volumes flow through fragmented hardware retail networks shaped by DGFT tariff exposure on redispersible polymer powders.
Pricing Analysis
Volume-margin splits separate cementitious flooring compounds from polymer-modified facade systems and epoxy industrial formulations. Three-tier pricing structure across premium, standard, and economy levels tracks IS 15477 certification grade and polymer loading ratios. Cost compression in cement-based tiers intensifies because Portland cement input volatility and energy logistics pricing squeeze compounder margins. Slum rehabilitation authorities and bulk procurement contractors show highest price sensitivity, while pharmaceutical and food processing plant operators accept technical premiums for chemical-resistant specifications.
Supply Chain Analysis
Reverse-logistics flows for expired or moisture-compromised adhesive batches remain underdeveloped, constraining circular economy participation among Indian manufacturers. Raw material sourcing concentrates in China, Germany, and South Korea for redispersible polymer powders and specialty epoxy resins. Domestic formulation economics hinge on DGFT tariff structures for polymer emulsion imports, creating single-source vulnerability for non-integrated compounders. Distribution runs through thousands of independent hardware stores in tier-2 and tier-3 cities, supplemented by direct sales contracts with slum rehabilitation authorities and metro rail contractors requiring regional warehousing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's tile adhesive market operates as a supply-constrained environment where BIS certification bottlenecks prop pricing premiums for compliant manufacturers. IS 15477 testing facility scarcity and 8-14 month approval timelines restrict rapid capacity response to formulation innovations.
For Market Incumbents: Lock in certification infrastructure advantages by expanding captive testing laboratories in Maharashtra and Gujarat to accelerate IS 15477 compliance timelines. Deepen backward integration into redispersible polymer powder production to mitigate DGFT tariff exposure on imported emulsions. Defend against emerging regional compounders by securing multi-brand procurement slots with slum rehabilitation authorities through penalty-protected inventory guarantees. For New Entrants and Emerging Players: Enter via Tamil Nadu and Karnataka residential flooring whitespace where hardware store penetration gaps persist beneath incumbent radar. Target Bengaluru peripheral districts and Chennai suburban corridors with economy-grade cementitious formulations distributed through independent retailer networks. Accelerate specification capture by offering contractor-direct technical service models that differentiate against hardware-store-dependent mass-market suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in regional warehousing infrastructure plays and BIS-certified manufacturing assets with captive testing capabilities. Long-term viability favors integrated manufacturers with polymer technology licensing relationships and direct sales channel control. Monitor DGFT tariff amendment announcements on polymer emulsion imports as inflection indicators for domestic formulation economics and backward integration incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Emulsion Production | DGFT tariff exposure on imported redispersible powders compresses margins for non-integrated compounders. |
| Captive BIS Testing Laboratory Expansion | IS 15477 certification timelines of 8-14 months constrain rapid product launches for uncertified facilities. |
| Regional Warehousing Infrastructure Deployment | Slum rehabilitation authority contracts impose penalty clauses for stockouts that favor localized inventory. |
| Contractor-Direct Technical Service Model | Complex commercial applications favor on-site application support over hardware store distribution. |
| Multi-Brand Procurement Contract Consolidation | Large developers specify approved manufacturer lists rather than single-source dependencies across projects. |
Study Parameters
Independent corroboration across adhesive formulator technical directors, slum rehabilitation authority procurement officers, and hardware store channel partners underwrites the qualitative findings in this study. Primary interviews with BIS certification laboratory managers, polymer emulsion import distributors, and high-rise facade contractors combined with secondary validation from DGFT tariff notifications, BIS IS 15477 amendment drafts, and CEA building energy code disclosures. Bottom-up volume estimates from state-level construction project databases triangulate against top-down formulation chemistry segmentation.
Comparable-period anchoring to historical metro rail and slum rehabilitation project completion schedules established the forecast window baseline across the analysis window. Segmentation modeling spans formulation chemistry, application intensity, distribution channel, and end-user technical sophistication tiers. CAGRs derive from project pipeline visibility and polymer-modified specification penetration curves. Forecast inputs incorporate BIS certification queue lengths and DGFT policy review cycles without specific year references.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt BIS standard amendments or DGFT tariff restructuring. Practitioners should monitor IS 15477 testing protocol amendments and National Building Code exterior cladding revisions for early signals of specification threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
United Kingdom Sealants Market