
 Europe Construction Adhesives and Sealants Market | 2026-2036
Europe Construction Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Construction Adhesives and Sealants Market Foresight
Italy's Po Valley chemical corridor is narrowing its specialty monomer deficit through dedicated silane production investments. Henkel AG & Co. KGaA leverages its Bergheim facility to anchor European distribution of reactive polyurethane systems. Sika AG sustains formulation leadership through captive R&D centers in Zurich and Munich. Wacker Chemie AG dominates silicone intermediate supply, extending backward integration into quartz processing.
Construction adhesives and sealants comprise formulated polymer systems—typically 30-60% solids content—engineered to bond dissimilar substrates or seal joints against moisture, air, and thermal bridging in built structures. Their primary purpose is structural integrity and building envelope performance across residential, commercial, and civil engineering applications. Water-based acrylics occupy the volume-intensive residential segment, where low-VOC compliance and ease of application drive specification. Reactive polyurethanes capture premium margin pools in industrial flooring and infrastructure joint sealing, where cure speed and dynamic-load resistance justify higher formulation cost. Hot melt technologies remain concentrated in prefabricated wall panel assembly, benefiting from automated application speed in controlled factory environments.
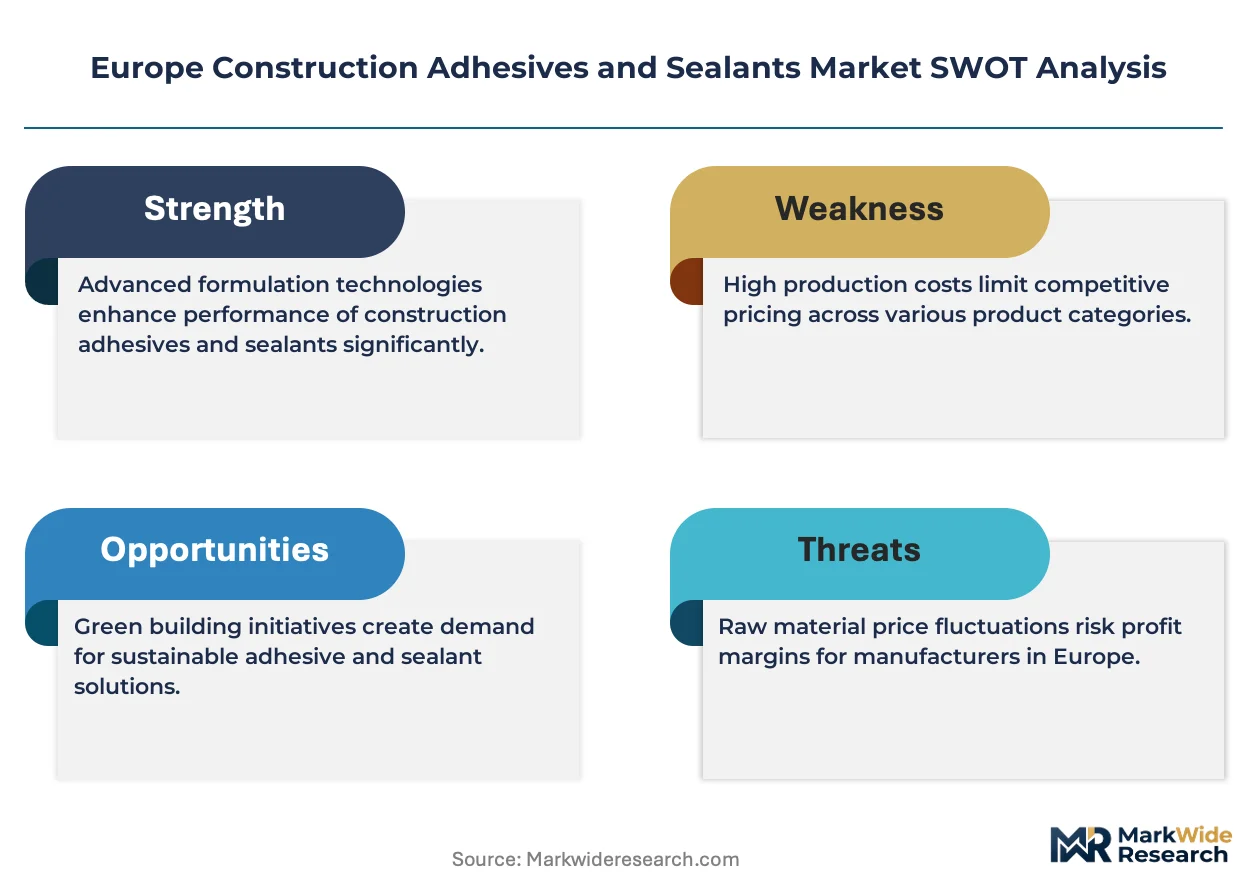
REACH restrictions on isocyanate exposure and the EU Green Deal's carbon-border adjustments are elevating bio-based content requirements and tightening market access for imported conventional formulations. ECHA's ongoing substance evaluations for siloxanes are forcing reformulation timelines among silicone sealant producers. France's RE2020 environmental regulation and Germany's Gebäudeenergiegesetz are converging on whole-life carbon metrics, reshaping how adhesive and sealant specifications enter architectural tender documents. Stakeholders must monitor regulatory divergence between national building codes and EU-level chemical frameworks to anticipate compliance cost allocation across their product portfolios.
Market Dynamics
REACH restrictions on isocyanate exposure are forcing polyurethane adhesive producers to accelerate solvent-free formulation development or exit industrial flooring segments entirely. The EU Green Deal's carbon-border adjustments are simultaneously redirecting raw material sourcing toward European bio-refineries, compressing margins for importers of conventional petrochemical feedstocks.
Growth Catalysts
- Germany's Gebäudeenergiegesetz:Deep energy retrofit mandates are accelerating specification of high-performance polyurethane adhesives in building envelope applications. Residential contractors face binding thermal bridging limits that only reactive systems can satisfy.
- Transit-oriented development clusters:France's Ile-de-France corridor is intensifying demand for movement-capable joint sealants in rail-adjacent commercial construction. Specification density in this corridor exceeds national averages by substantial margins.
- Silane-terminated polymer technology:Hybrid systems combining polyurethane backbone with silane crosslinking are capturing specification share in moisture-cure applications. These materials eliminate isocyanate handling concerns while maintaining structural performance.
Market Restraints
- MDI price volatility:Methylene diphenyl diisocyanate feedstock costs swing with crude oil and benzene pricing, destabilizing polyurethane adhesive margin structures. Formulators lack pass-through mechanisms in fixed-price construction contracts.
- Silicone intermediate concentration:Wacker Chemie AG's dominance in European silicone supply creates single-source risk for sealant producers. Quartz processing bottlenecks in Bavaria propagate through the value chain during energy price spikes.
- Hot-melt performance ceiling:Ethylene-vinyl acetate systems fail in exterior structural glazing applications, limiting penetration beyond controlled factory environments. Field-cure requirements exclude this technology from high-performance building envelopes.
Strategic Opportunities
- Poland's construction acceleration:EU cohesion fund infrastructure deployment is outpacing domestic adhesive formulation capacity. Import substitution opportunities exist for Western European producers with logistics flexibility.
- RE2020 whole-life carbon mandates:France's environmental regulation rewards bio-based content in public procurement scoring. Adhesives with certified renewable feedstock content gain tender preference in social housing and municipal projects.
- Prefabrication channel expansion:Off-site construction growth in the Netherlands and Scandinavia favors hot-melt and reactive hot-melt systems compatible with automated dispensing. Factory-controlled application eliminates field-cure variability concerns.
Industry Challenges
- Formulation chemist scarcity:European universities produce insufficient polymer science graduates with construction adhesive specialization. Retirements at major producers are outpacing knowledge transfer to junior staff.
- ECHA substance evaluation timelines:Pending siloxane restrictions force silicone sealant producers to maintain parallel formulation tracks. Dual development drains R&D resources without guaranteed regulatory clarity.
- Cross-border specification fragmentation:Divergent national building codes between Germany, France, and Benelux require product-line customization. SKU proliferation complicates inventory management and dilutes batch economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Construction Adhesives and Sealants Market |
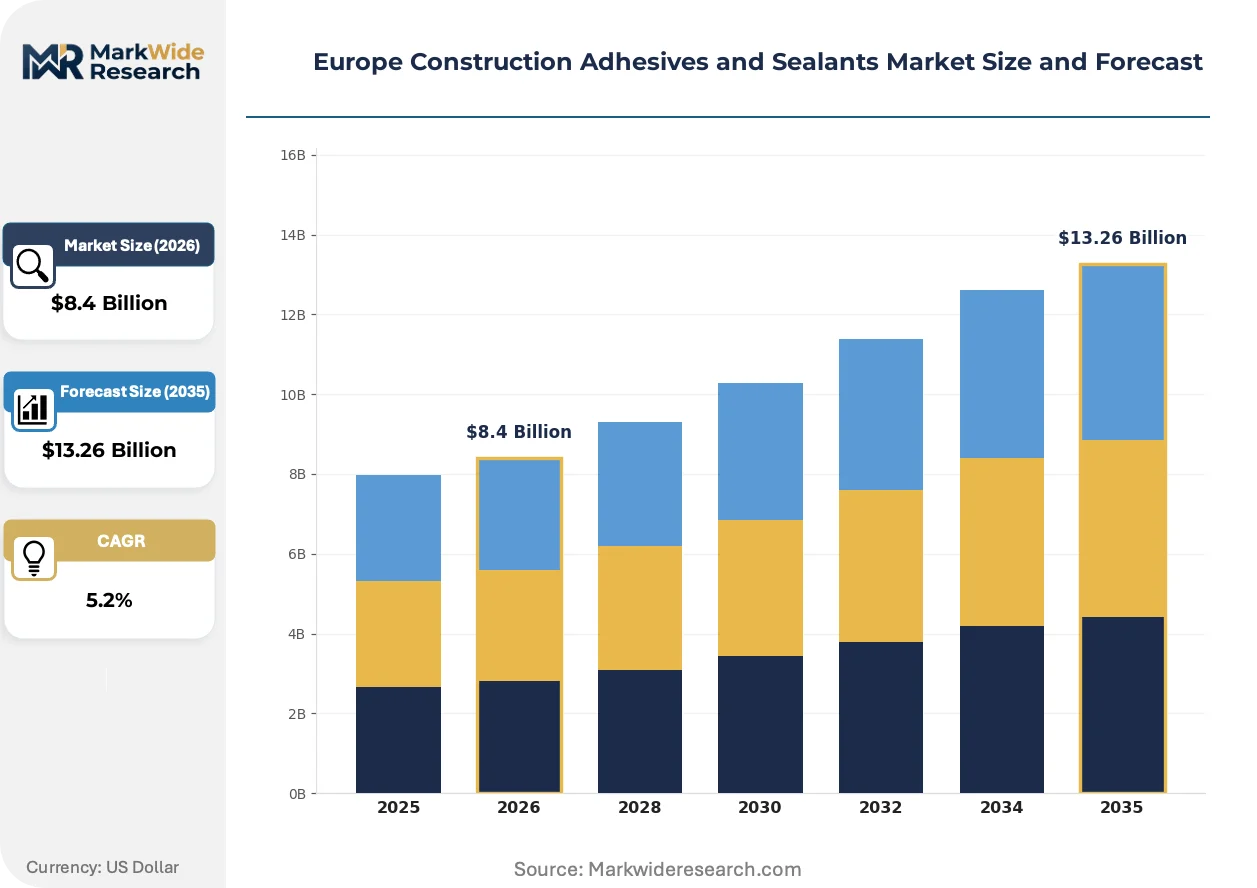
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Acrylic, Epoxy Technology: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Residential, Commercial, Industrial, Infrastructure Application: Flooring, Roofing, Wall Covering, Joint Sealing |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, Arkema Group, MAPEI S.p.A, H.B. Fuller Company, Soudal Holding N.V., Wacker Chemie AG, 3M, Illinois Tool Works Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Construction Adhesives and Sealants Market Shifts & Advancements
Bio-based feedstock integration is shifting from marketing differentiation to compliance necessity across European construction adhesive portfolios. Formulation strategies now prioritize carbon accounting traceability over traditional performance-cost optimization.
Silane-terminated polyurethane technology is rendering obsolete conventional moisture-cure systems in high-humidity construction environments. Scandinavian contractors facing compressed outdoor work seasons are specifying these hybrids for reliable cure performance. The technology is rendering obsolete established product categories that require extended dry-period protection during application.
REACH authorization requirements for diisocyanates are forcing industrial flooring contractors toward water-based or hybrid alternatives. ECHA's restriction entry into force in August 2023 triggered wholesale reformulation across professional-grade adhesive portfolios. Flooring applicators in Germany and Austria are absorbing retraining costs to maintain certification compliance.
Public procurement scoring systems are elevating Environmental Product Declaration documentation above traditional supplier relationships. French and Dutch specifiers now weight embodied carbon metrics at parity with unit pricing in tender evaluations. Municipal construction authorities in Copenhagen and Vienna are piloting mandatory EPD submission for sealant categories above threshold contract values.
Europe Construction Adhesives and Sealants Market Segmentation
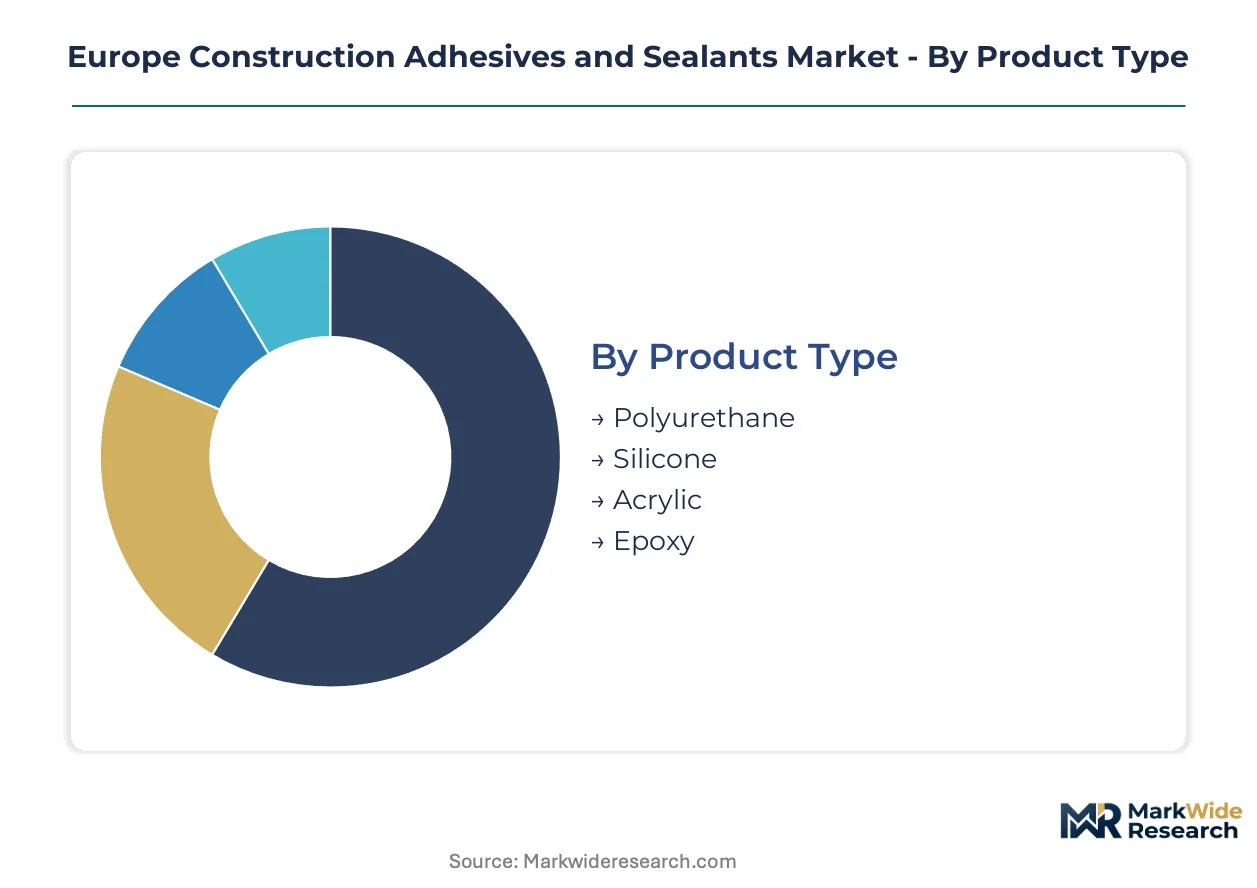
Segmentation in European construction adhesives and sealants reflects divergent technical requirements across building codes, cure conditions, and substrate compatibility. Formulators must align product architectures with specific performance thresholds rather than pursuing universal solutions.
Product Type:
Mature commodity chemistries dominate volume, while emerging hybrid systems capture specification share in high-performance niches.
- Polyurethane:Reactive systems with isocyanate-terminated prepolymers deliver structural bonding strength and dynamic-load tolerance. German Gebäudeenergiegesetz retrofit mandates are concentrating demand in thermal-bridge-free envelope applications where only these systems satisfy binding performance criteria.
- Silicone:Cross-linked polydimethylsiloxane formulations provide unmatched UV stability and movement accommodation in exterior joint sealing. France's Ile-de-France corridor specifications for rail-adjacent commercial construction favor these materials for their vibration-damping properties in transit-oriented development clusters.
- Acrylic:Water-dispersed polymers serve residential interior applications with low-VOC compliance and tool-cleanup convenience.
- Epoxy:Two-part thermoset systems anchor industrial flooring and structural repair segments demanding chemical resistance.
Polyurethane retains volume leadership; silicone holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium reactive systems from economy water-based alternatives, with application environment dictating technology selection.
- Water-Based:Acrylic and polyurethane dispersions with 40-60% solids content serve interior residential markets. Scandinavian contractors specify these for occupied-space applications where solvent exposure is prohibited by workplace regulations.
- Reactive:Moisture-cure and two-part systems command premium positioning through structural performance. Silane-terminated polyurethane hybrids are displacing conventional moisture-cure technology in high-humidity construction environments across the Netherlands and Belgium.
- Solvent-Based:Declining share in professional applications due to REACH occupational exposure limits and site ventilation requirements.
- Hot Melt:Ethylene-vinyl acetate and reactive polyurethane systems enable automated dispensing in prefabricated panel assembly. Factory-controlled application in Dutch and Scandinavian off-site construction eliminates field-cure variability.
Water-based technology retains volume leadership; reactive systems command the steepest margin expansion.
End User:
Application scale and regulatory exposure separate commercial project specifications from residential retrofit economics.
- Residential:Single-family and multi-family construction drives specification of low-VOC, easy-application systems. Germany's deep energy retrofit programs are accelerating polyurethane adhesive uptake in building envelope upgrades.
- Commercial:Office, retail, and hospitality projects demand performance documentation and warranty support. France's RE2020 whole-life carbon mandates are elevating bio-based content requirements in public procurement scoring for social housing and municipal construction.
- Industrial:Manufacturing facility flooring and containment applications require chemical resistance and dynamic-load tolerance.
- Infrastructure:Transportation and utility projects specify movement-capable joint sealants with extended service life guarantees.
Residential retains volume leadership; commercial holds the steepest specification-value expansion.
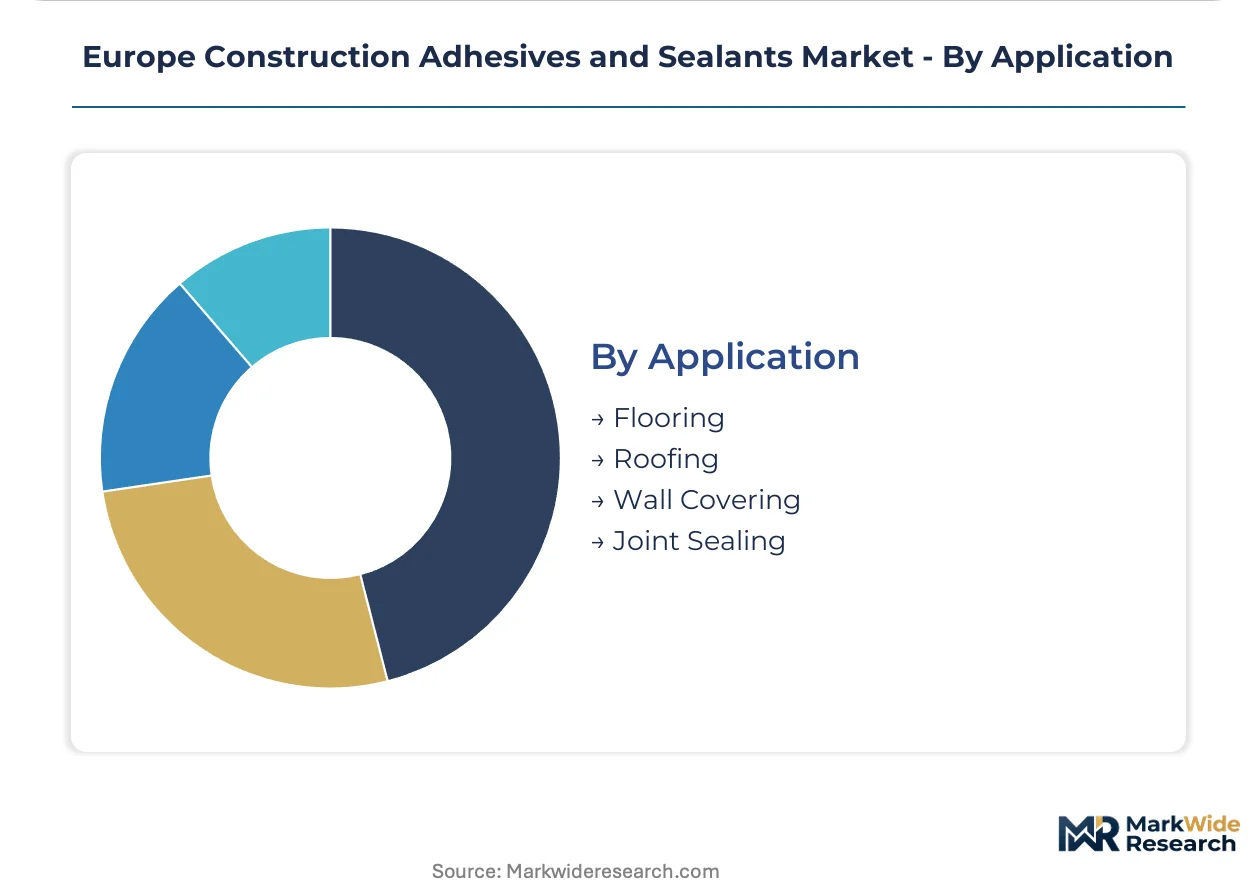
Application:
Substrate exposure conditions and movement requirements segment demand across building envelope functions.
- Joint Sealing:Elastomeric sealants accommodating thermal and structural movement in exterior envelopes. Transit-oriented development in France's Ile-de-France corridor intensifies demand for vibration-resistant formulations in rail-adjacent construction.
- Flooring:Substrate bonding and surface finishing systems for residential and commercial interiors. REACH diisocyanate restrictions are forcing reformulation toward water-based and hybrid alternatives in German and Austrian industrial flooring applications.
- Roofing:Membrane bonding and flashing sealants exposed to thermal cycling and UV degradation.
- Wall Covering:Panel adhesive and surface preparation systems for interior finish applications.
Joint sealing retains value leadership; flooring holds the steepest regulatory-driven transformation curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters along the Rhine corridor and northern Italy, with raw material access and building code stringency determining sub-regional specialization. REACH enforcement intensity and national retrofit mandates create divergent demand profiles across member states.
Germany
Deep energy retrofit mandates under the Gebäudeenergiegesetz are concentrating polyurethane adhesive demand in thermal-bridge-free envelope applications. ECHA diisocyanate restrictions are accelerating solvent-free formulation transitions among industrial flooring contractors. The Bergheim-Rhine complex anchors reactive system production for Central European distribution.
France
RE2020 whole-life carbon scoring is elevating bio-based content requirements in public procurement for social housing and municipal construction. Transit-oriented development in the Ile-de-France corridor intensifies specification of vibration-resistant joint sealants for rail-adjacent commercial projects. Marseille-Fos chemical processing supports silicone intermediate supply for southern European markets.
Italy
The Po Valley chemical corridor is narrowing specialty monomer deficits through dedicated silane production investments. MAPEI's Milan-R&D hub drives formulation adaptation for Mediterranean climate exposure conditions. Lombardy's prefabricated construction sector favors hot-melt systems compatible with automated panel assembly.
Netherlands
Off-site construction growth in Randstad metropolitan clusters favors reactive hot-melt technologies with factory-controlled application parameters. Circular building mandates under national environmental regulation reward adhesive systems with certified recycled content. Eindhoven's materials science ecosystem supports hybrid polymer development for moisture-cure applications.
Poland
EU cohesion fund infrastructure deployment is outpacing domestic adhesive formulation capacity, creating import substitution openings for Western European producers. Warsaw-Krakow construction corridors specify mid-tier water-based systems for residential volume applications. Logistics flexibility determines competitive positioning in this demand-acceleration zone.
Europe Construction Adhesives and Sealants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in intermediate supply. The European construction adhesives sector exhibits tiered consolidation, with full-line formulators holding specification influence over specialty producers. Three archetypes dominate: integrated chemical conglomerates with captive raw material positions, construction-focused specialists with application engineering depth, and regional formulators serving price-sensitive volume segments. Capacity expansion and portfolio diversification toward bio-based content represent the dominant competitive vectors.
Among integrated chemical producers, Henkel AG & Co. KGaA and Wacker Chemie AG occupy positions reflecting upstream control over key feedstock categories. Sika AG exemplifies the construction-specialist archetype, anchoring formulation leadership through captive R&D infrastructure. These three entities represent distinct strategic postures: petrochemical integration, silicone intermediate dominance, and application-focused specification engineering.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| MAPEI S.p.A |
| H.B. Fuller Company |
| Soudal Holding N.V. |
| Wacker Chemie AG |
| 3M |
| Illinois Tool Works Inc |
| Others |
Supply & Pricing Matrix
Wacker Chemie AG's quartz-to-silicone verticality in Bavaria concentrates intermediate supply power, pushing margin capture downstream toward formulated sealant producers with captive R&D and specification relationships. This upstream concentration shapes how pricing power distributes across reactive polyurethane and silicone system tiers.
Pricing Analysis
REACH authorization requirements for diisocyanates dictate the pricing tier structure across professional-grade adhesive portfolios. Three-tier pricing stratifies across certified low-exposure formulations, standard reactive systems, and economy water-based alternatives. Price differentiation rests on ECHA compliance tier and embodied carbon documentation rather than raw performance metrics. Cost compression in solvent-based tiers is intensifying because flooring contractors absorb retraining expenses to maintain certification. Residential retrofit contractors exhibit highest price sensitivity; infrastructure joint-sealing specifications show lowest.
Supply Chain Analysis
Contract manufacturing for construction adhesives concentrates among German Rhine corridor toll compounders and northern Italian specialty chemical processors. Raw material sourcing draws from Belgian MDI production, Bavarian silicone intermediates, and Po Valley silane derivatives. Single-source vulnerability runs through Wacker Chemie AG's European silicone supply during energy price spikes. Distribution runs through construction chemical distributors with application engineering support, anchored by regional logistics hubs in Düsseldorf and Milan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as specification influence shifts toward integrated system providers with EPD documentation capabilities and digital tender-integration tools. Interoperability between formulation databases and building information modeling software is redistributing competitive advantage.
For Market Incumbents: Harden specification lock-in through mandatory EPD submission portals for municipal tender pre-qualification. Deepen backward integration into bio-based feedstock certification to defend margin pools against carbon-border adjustment exposure. Captive silane production investments at Bergheim and Po Valley facilities represent the priority defensive lever against hybrid polymer disruption.
For New Entrants and Emerging Players: Build out Poland's demand-acceleration corridor where EU cohesion fund deployment outpaces domestic formulation capacity. Target mid-tier water-based residential applications in Warsaw-Krakow construction zones with logistics-flexible import substitution. Go-to-market positioning should anchor on rapid EPD certification turnaround for RE2020-compliant public procurement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators in Benelux and Scandinavia lacking bio-based portfolio transition. Long-term viability in this sector hinges on carbon-accounting infrastructure and specification database integration. Watch siloxane regulatory clarity from ECHA as the inflection signal for silicone sealant portfolio repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captive supply of certified renewable content secures RE2020 tender preference in French public procurement. |
| Silane Production Capacity Expansion | Dedicated Po Valley investments narrow specialty monomer deficits for hybrid polyurethane-silane systems. |
| EPD Documentation Platform Development | Digital Environmental Product Declaration submission tools lock specification influence with municipal authorities. |
| Reactive Hot-melt Technology Deployment | Factory-controlled application systems capture prefabrication channel growth in Dutch and Scandinavian off-site construction. |
| Logistics Hub Establishment in Poland | Warsaw-Krakow distribution positioning enables import substitution in EU cohesion fund infrastructure deployment. |
Research Methodology
A standing panel of formulation chemists at major producers, procurement leads at German flooring contractors, French municipal construction authorities, and Dutch prefabrication plant managers provided ongoing calibration across the study period. Primary interview data combined with secondary validation from ECHA substance evaluation dockets, EU customs trade statistics, Cefic sector reports, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates from construction chemical distributor revenue proxies.
Scenario bracketing around REACH enforcement intensity, carbon-border adjustment implementation, and bio-based feedstock availability anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry type, cure technology, end-use sector, application function, and national regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating retrofit mandate timelines and infrastructure deployment schedules. Siloxane restriction probability and prefabrication adoption curves served as key forecast inputs.
Stress conditions across MDI price volatility, energy cost spikes, and ECHA evaluation timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and construction sector investment cycles. Quarterly review of ECHA substance evaluation progress, EU carbon-border adjustment phase-in dates, and municipal EPD mandate expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market