
 Soft Skin Adhesives Market | 2026-2036
Soft Skin Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Skin Adhesives Market Insights
Waterborne silicone dispersion technology is rewriting manufacturing economics for skin-contact adhesives by eliminating solvent recovery costs and shortening curing cycles. 3M Company leverages its polymer science portfolio to sustain premium positioning across hospital procurement channels. Henkel AG & Co. KGaA anchors European supply security through captive resin production near Düsseldorf. Avery Dennison Corporation differentiates via die-cut customization capabilities serving transdermal patch developers in North America.
Soft skin adhesives comprise pressure-sensitive formulations engineered for gentle adhesion to human epidermis with peel strengths typically below 1 N/cm, designed for repeated or extended wear without trauma upon removal. Silicone adhesives command margin pools in advanced wound care due to their breathability and minimal skin irritation profiles, while acrylic adhesives dominate high-volume medical tape production where cost efficiency outweighs extended wear requirements. Polyurethane adhesives represent the fastest-growing chemistry segment as manufacturers engineer hybrid systems combining silicone gentleness with acrylic processing speeds.
FDA 21 CFR Part 175.105 compliance and ISO 10993 biocompatibility testing frameworks govern material approval timelines for skin-contact applications, with EMA MDR requirements in Europe adding clinical evidence burdens for novel adhesive platforms. The EU Green Deal chemical sustainability targets are forcing reformulation investments away from petroleum-derived tackifiers toward bio-based alternatives. Stakeholders must monitor evolving reimbursement codes for home-based wound management as clinical site-of-care migration accelerates material performance demands beyond traditional hospital specifications.
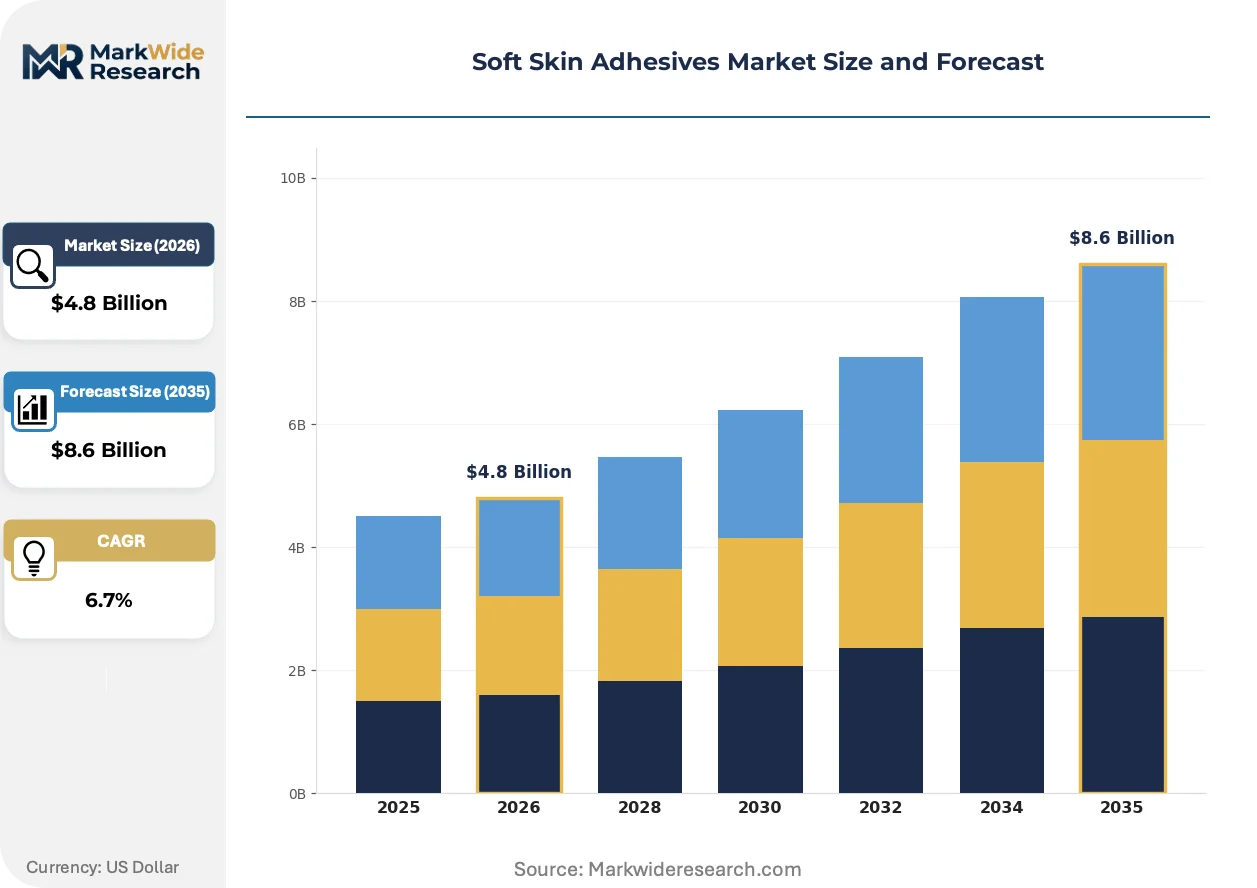
Market Dynamics
Waterborne silicone dispersion technology is compressing manufacturing costs and curing cycles, while FDA and EMA biocompatibility tightening is extending material approval timelines and forcing reformulation investments across the value chain.
Growth Catalysts
- ISO 10993 biocompatibility frameworks:Standardized testing protocols reduce regulatory uncertainty for skin-contact adhesive developers, accelerating hospital procurement decisions for wound care applications.
- Wearable medical device proliferation:Continuous glucose monitors and cardiac patches require gentle, breathable adhesion for multi-day wear, expanding addressable demand beyond traditional medical tape.
- Home-based wound management migration:Reimbursement codes shifting toward outpatient care elevate performance requirements for patient-applied adhesives in the United States and Germany.
Market Restraints
- Petroleum-derived tackifier dependency:Crude oil price volatility feeds directly into acrylic adhesive input costs, compressing margins for high-volume medical tape producers.
- Silicone raw material concentration:Specialty silicone resin supply clusters in Northeast Asia, creating geographic single-point-of-failure exposure for Western formulators.
- EU Green Deal chemical sustainability targets:Mandatory bio-based content thresholds force premature equipment obsolescence for solvent-based coating lines in European manufacturing.
Strategic Opportunities
- Underpenetrated transdermal drug delivery:Japan's aging population and PMDA streamlined patch approval pathways create whitespace for advanced silicone adhesive platforms in pain management.
- Hybrid polyurethane-silicone systems:Converging silicone gentleness with acrylic processing speeds enables formulators to capture margin pools in premium wearable segments.
- Direct-to-device-manufacturer channels:Bypassing traditional medical distributors, adhesive suppliers build specification relationships with CGM and insulin pump designers in Minnesota and California clusters.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with simultaneous expertise in pressure-sensitive rheology and biocompatibility testing command premium compensation, constraining R&D expansion.
- ISO 10993-5 cytotoxicity certification timelines:Extended in-vitro and sensitization study durations delay product launches by 14-18 months for novel adhesive chemistries.
- Legacy hospital procurement system integration:Electronic health record compatibility requirements and group purchasing organization compliance create friction for adhesive suppliers targeting acute care.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Skin Adhesives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Adhesives, Acrylic Adhesives, Polyurethane Adhesives, Rubber Adhesives Application: Medical Tapes, Wound Dressings, Transdermal Patches, Prosthetics End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Distribution Channel: Online Retail, Distributors, Direct Sales, Medical Supply Stores |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Avery Dennison Corporation, Adhesives Research, Inc., Scapa Group plc, Johnson & Johnson, Nitto Denko Corporation, DuPont de Nemours, Inc., Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Skin Adhesives Market Trends and Innovations
Digital twin modeling of adhesive-skin interaction is compressing development cycles and enabling predictive wear performance before physical prototyping, fundamentally altering how formulators approach biocompatibility validation.
Waterborne silicone dispersion is virtualizing the solvent recovery infrastructure that once anchored manufacturing economics for skin-contact adhesives. Transdermal patch developers in North America and Western Europe are adopting these systems at accelerating pace to eliminate volatile organic compound emissions. The technology is virtualizing capital allocation patterns, redirecting investment from environmental compliance equipment toward precision coating and die-cutting capabilities.
EMA MDR clinical evidence requirements are extending approval burdens for novel adhesive platforms beyond traditional material safety documentation. Manufacturers must now generate patient outcome data for wear duration and skin trauma incidence, elevating development costs. Advanced wound care segments in Germany, France, and the Netherlands are responding by consolidating supplier relationships toward established ISO 13485-certified formulators with existing clinical dossiers.
Hospital procurement departments are unbundling adhesive specifications from finished device contracts, creating direct specification authority for wound care nurses and materials managers. This behavioral shift disrupts traditional distributor-mediated supply relationships, favoring adhesive suppliers with dedicated clinical liaison teams. The pattern is most visible in United States academic medical centers and German university hospitals, where value-analysis committees now include frontline clinicians in adhesive selection decisions.
Soft Skin Adhesives Market Segmentation
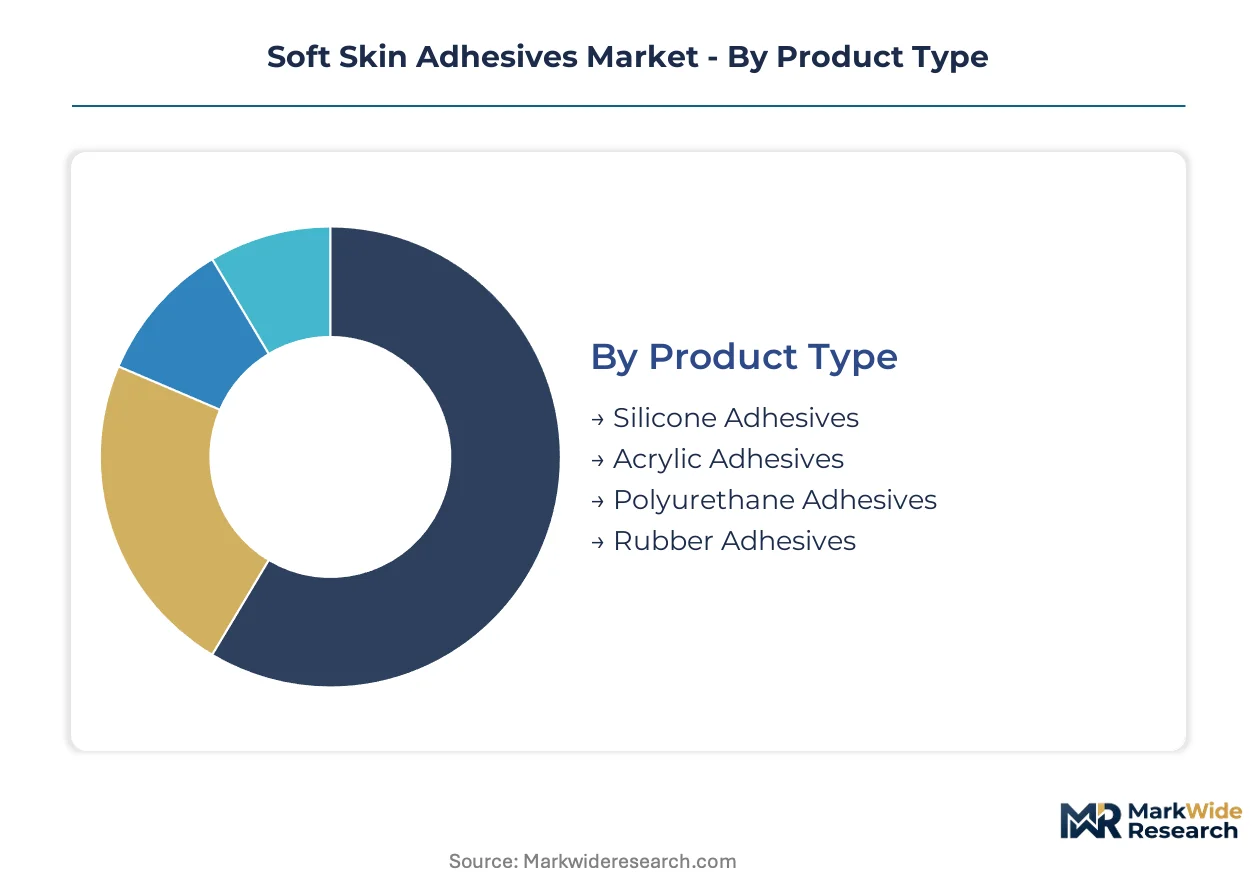
Soft skin adhesives demand fragments across chemistry platforms, clinical settings, and procurement channels that each impose distinct performance specifications and margin structures. Formulators must align R&D investment with segment-specific wear duration, biocompatibility certification, and reimbursement pathway requirements.
Product Type:
After-sales technical support intensity varies sharply by chemistry platform, with silicone formulations requiring clinical liaison teams for wound care training while acrylic systems demand logistics coordination for high-volume tape replenishment.
- Silicone Adhesives:These breathable, low-trauma formulations rely on polydimethylsiloxane backbones with controlled tack for multi-day wear. Demand concentrates in German and Japanese hospital systems where aging populations expand advanced wound care procurement and FDA 21 CFR Part 175.105 compliance elevates specification barriers for new entrants.
- Acrylic Adhesives:Cost-optimized pressure-sensitive systems dominate high-volume medical tape production through solvent or emulsion polymerization. United States group purchasing organizations drive procurement consolidation toward ISO 10993-certified suppliers with established die-cutting partnerships in Minnesota and Ohio manufacturing clusters.
- Polyurethane Adhesives:Hybrid systems combining silicone gentleness with acrylic processing speeds are gaining formulation investment for wearable device applications.
- Rubber Adhesives:Natural and synthetic rubber formulations serve cost-sensitive single-use applications with limited breathability requirements.
Silicone adhesives hold the largest share; momentum sits with polyurethane hybrid systems.
Application:
Application-level pricing stratifies by clinical outcome documentation burden, with transdermal patches commanding premium validation investment versus commodity tape segments.
- Medical Tapes:Standardized fixation products for catheter and tubing securement rely on acrylic pressure-sensitive adhesives with peel strengths optimized for 24-48 hour wear. United States home care reimbursement codes are shifting procurement volume toward patient-applied formats with simplified removal mechanics.
- Wound Dressings:Advanced care formats incorporate silicone contact layers for moist wound healing with minimal periwound maceration. German and Dutch hospital value-analysis committees are unbundling adhesive specifications from finished dressing contracts, creating direct procurement authority for materials managers with ISO 13485 certification requirements.
- Transdermal Patches:Drug delivery platforms require adhesive matrices with precise permeation control and extended 7-day wear profiles.
- Prosthetics:Skin-contact adhesives for limb and facial prostheses demand high moisture resistance and repeated daily reapplication durability.
Medical tapes capture the highest volume base; transdermal patches are climbing the fastest on PMDA streamlined approval pathways in Japan.
End User:
End-user concentration determines specification complexity, with acute care sites demanding EHR-compatible procurement systems while home care elevates patient self-application requirements.
- Hospitals:Academic medical centers in the United States and university hospitals in Germany are consolidating supplier relationships toward established formulators with existing clinical dossiers and dedicated wound care nurse training programs.
- Clinics:Outpatient wound care centers require rapid-turn adhesive replenishment with standardized sizing for debridement and negative pressure wound therapy applications.
- Home Care:Patient-directed application is elevating demand for low-trauma removal and intuitive packaging design.
- Long-Term Care Facilities:Staff turnover challenges are driving specification toward foolproof application systems with visual wear indicators.
Hospitals retain the dominant procurement volume; home care is expanding most quickly on site-of-care migration trends.
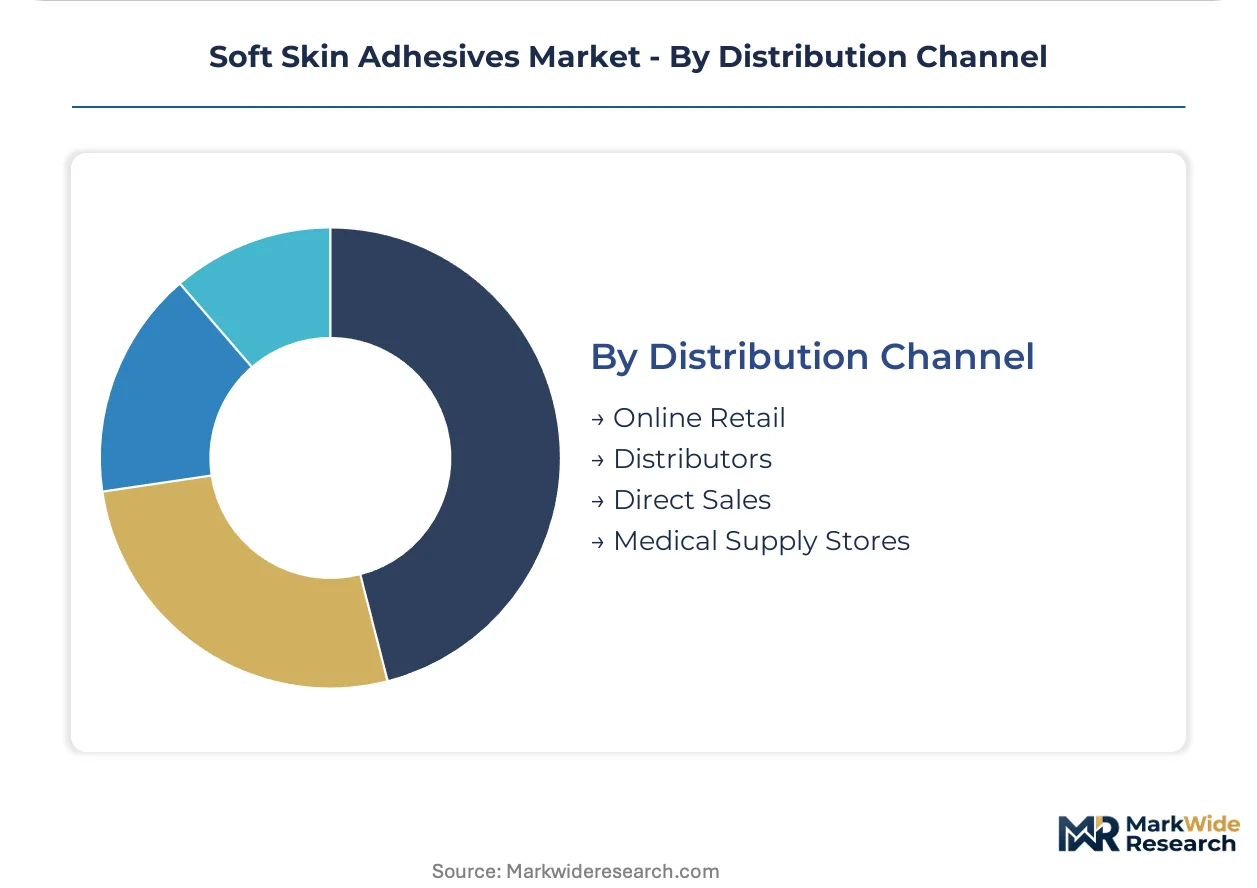
Distribution Channel:
Channel economics fragment by customer scale and specification complexity, with direct sales capturing premium wearable device accounts while distributors serve fragmented clinic demand.
- Direct Sales:CGM and insulin pump manufacturers in California and Minnesota clusters are bypassing traditional medical distributors to build specification relationships directly with adhesive formulators, compressing approval timelines for custom die-cut geometries.
- Distributors:Regional medical supply networks dominate hospital and clinic procurement for standardized tape and dressing formats with established logistics contracts.
- Online Retail:E-commerce platforms are capturing patient-direct demand for home care and over-the-counter wound management products.
- Medical Supply Stores:Brick-and-mortar retail serves emergency replenishment and small-practice procurement with limited inventory depth.
Distributors maintain the broadest reach; direct sales channels are gaining share fastest on wearable device proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German silicone resin exports supply wound care manufacturers across Western Europe, while Japanese adhesive formulators serve transdermal patch developers throughout East Asia. Raw material trade corridors concentrate specialty polymer flows between Northeast Asian production clusters and North American medical device assembly plants.
United States
Continuous glucose monitor manufacturers in Minnesota and California clusters drive specification demand for multi-day wear adhesives. FDA 21 CFR Part 175.105 compliance timelines extend material approval cycles for novel chemistries. Academic medical centers in Boston and Philadelphia consolidate procurement toward ISO 13485-certified suppliers with dedicated wound care training programs.
Germany
Advanced wound care procurement expands through university hospitals serving aging populations in Bavaria and North Rhine-Westphalia. EMA MDR clinical evidence requirements elevate development costs for novel adhesive platforms. Henkel's captive resin production near Düsseldorf anchors European supply security for silicone-based formulations.
Japan
PMDA streamlined patch approval pathways accelerate transdermal drug delivery commercialization for pain management applications. METI chemical sustainability targets pressure reformulation away from petroleum-derived tackifiers. Osaka-based formulators develop hybrid polyurethane-silicone systems for premium wearable segments.
United Kingdom
NHS procurement unbundling creates direct specification authority for wound care nurses in London and Manchester hospital systems. MHRA post-Brexit regulatory divergence extends dual-track compliance burdens for adhesive suppliers. Cambridge medical device clusters demand custom die-cut geometries for cardiac monitoring patches.
China
Domestic CGM and insulin pump assembly expands in Shenzhen and Shanghai manufacturing zones. NMPA biocompatibility testing frameworks lengthen approval timelines for imported adhesive platforms. Yangtze River Delta chemical producers invest in waterborne silicone dispersion capacity to serve regional medical tape demand.
Soft Skin Adhesives Market Competitive Landscape
On the supply side, the industry is consolidating around established polymer science portfolios with ISO 10993 certification dossiers. Three strategic archetypes dominate: diversified materials conglomerates with medical divisions, specialized adhesive formulators with clinical liaison capabilities, and integrated resin producers with captive coating operations. Competitive moves center on backward integration into specialty silicone supply and direct specification relationships with wearable device manufacturers bypassing traditional distributors.
Within the diversified materials tier, 3M Company and DuPont de Nemours, Inc. exemplify scale-driven positioning across hospital procurement channels. Among European specialists, Henkel AG & Co. KGaA and Lohmann GmbH & Co. KG occupy positions anchored by regional production assets and clinical training infrastructure. Nitto Denko Corporation represents the Asia-Pacific formulator archetype with concentration in transdermal patch supply chains.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Adhesives Research, Inc. |
| Scapa Group plc |
| Johnson & Johnson |
| Nitto Denko Corporation |
| DuPont de Nemours, Inc. |
| Lohmann GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Specialty silicone resin concentration in Northeast Asia creates geographic single-point-of-failure exposure that simultaneously widens premium-tier spreads for ISO 10993-certified formulations and forces Western formulators into backward integration investments or long-term offtake contracts.
Pricing Analysis
Waterborne silicone dispersion technology commands a 40-60% premium over solvent-based acrylic systems, while next-generation hybrid polyurethane-silicone platforms sit at the apex of the pricing hierarchy. Three-tier pricing structure across premium, standard, and economy levels separates multi-day wearable adhesives with full biocompatibility dossiers from commodity medical tapes with basic ISO 10993-5 screening. Price differentiation rests on certification depth and clinical evidence burden rather than raw material cost alone. Cost compression in high-volume acrylic tape segments is intensifying because United States group purchasing organizations consolidate procurement toward die-cutting-integrated suppliers with established logistics contracts. Home care patient-direct buyers exhibit highest price sensitivity; CGM manufacturers in Minnesota and California clusters demonstrate lowest sensitivity due to adhesive performance directly determining device wear duration and patient retention.
Supply Chain Analysis
Contract manufacturing concentration for precision coating and die-cutting sits with Avery Dennison's North American facilities, Lohmann's German operations, and Nitto Denko's Japanese plants. Raw material flows draw from Chinese silicone monomer production, German specialty resin synthesis near Düsseldorf, and South Korean polyurethane precursor manufacturing. Supply chain risk centers on tariff exposure for Northeast Asian silicone resin imports into North American and European formulating facilities. Distribution runs through regional medical supply distributors for hospital and clinic procurement, with direct sales channels gaining share for wearable device manufacturer accounts requiring custom geometry development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 10993 certification dossiers and clinical evidence libraries function as defensive moats with switching costs that lock hospital procurement committees into established supplier relationships and extend replacement timelines for novel adhesive platforms to 36-48 months.
For Market Incumbents: Entrench market position by deepening captive silicone resin production in Germany and expanding ISO 13485-certified coating capacity for waterborne dispersion platforms. Acquire specialized die-cutting capabilities in Minnesota to secure CGM manufacturer specification relationships. Counter threat from hybrid polyurethane-silicone entrants by accelerating clinical wear studies for next-generation breathable formulations. For New Entrants and Emerging Players: Pursue whitespace in Japan's transdermal patch segment where PMDA streamlined approval pathways reduce time-to-revenue for pain management adhesive platforms. Target underpenetrated home care wound management in Germany where reimbursement code shifts elevate demand for patient-applied low-trauma formats. Establish go-to-market presence through direct clinical liaison teams rather than distributor mediation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulators with existing biocompatibility dossiers and backward-integrated resin supply. Long-term viability rests on regulatory entrenchment deepening through EMA MDR clinical evidence requirements and FDA 21 CFR Part 175.105 compliance timelines. Acquisition target archetype: mid-cap European adhesive specialists with ISO 13485 certification and established German hospital relationships. Monitor quarterly FDA 510(k) submission volumes for novel adhesive chemistries as inflection indicator for competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Silicone Resin | Henkel's captive production near Düsseldorf eliminates Northeast Asian supply vulnerability for European wound care formulators. |
| Waterborne Dispersion Capacity Expansion | Elimination of solvent recovery infrastructure redirects capital toward precision coating capabilities serving transdermal patch developers. |
| Direct-to-Device-Manufacturer Channel Development | Bypassing traditional distributors accelerates specification timelines for CGM and insulin pump adhesive geometries in Minnesota clusters. |
| Clinical Evidence Library Investment | EMA MDR patient outcome data requirements elevate development costs and consolidate procurement toward established ISO 13485-certified suppliers. |
| Hybrid Polyurethane-Silicone R&D Program | Converging silicone gentleness with acrylic processing speeds captures margin pools in premium wearable segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation chemists, hospital procurement managers, biomedical engineers, and wound care nurse specialists; and secondary validation through FDA 510(k) filings, EMA MDR submission databases, SEC 10-K disclosures from listed materials conglomerates, and customs trade data for silicone resin flows. Bottom-up triangulation across chemistry platform production volumes and top-down reconciliation against end-use application demand established market sizing boundaries.
Forecast inputs considered chemistry platform evolution, regulatory approval pathway timelines, site-of-care migration patterns, and wearable device proliferation rates across the projection horizon. Segmentation dimensions modeled include adhesive chemistry, clinical application setting, end-user procurement authority, and distribution channel structure. CAGRs were derived from weighted scenario analysis of waterborne technology adoption curves and biocompatibility certification completion rates.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, Northeast Asian logistics costs, or EMA MDR enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution elasticities and hospital procurement consolidation rates. Quarterly review of FDA 510(k) clearance timelines and German hospital value-analysis committee composition changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Germany Adhesives Market