

Debonding-on-Demand Adhesives for EV Battery Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Debonding-on-Demand Adhesives for EV Battery Modules Market Insights
Subscription-based adhesive performance monitoring is recalibrating how suppliers monetize bonding solutions beyond initial material sales. Henkel leverages its scale in automotive electronics to sustain R&D intensity in thermally triggered debonding chemistries. Arkema anchors its position through specialty polymer expertise that competes on temperature-precision activation thresholds.
Debonding-on-demand adhesives for EV battery modules are engineered bonding systems incorporating thermally labile linkages, conductive fillers, or photoresponsive moieties that fracture predictably upon external stimulus, enabling non-destructive cell extraction and pack reconfiguration. These materials typically activate between 80°C and 150°C or under controlled UV exposure, serving the industrial purpose of circular battery economics by preserving cell integrity during end-of-life disassembly. Thermal activation mechanisms dominate current procurement volumes due to compatibility with existing pack heating infrastructure, while UV-triggered systems represent the fastest-growing segment owing to sub-second debond speeds that align with automated disassembly line economics. Epoxy-based formulations retain the deepest margin pools because their structural integrity under vibration and thermal cycling commands premium positioning in module assembly applications.
The EU Battery Regulation and REACH compliance frameworks are mandating design-for-recycling protocols that reshape adhesive selection criteria across European cell production facilities. EPA hazardous waste classifications and OSHA workplace exposure limits in the United States further constrain solvent-based chemical debonding alternatives, steering investment toward thermal and electrical activation pathways. Stakeholders must track how China's GB standards and NMPA-adjacent industrial material certifications evolve to determine whether domestic cell producers adopt reversible bonding architectures or maintain permanent adhesion conventions.
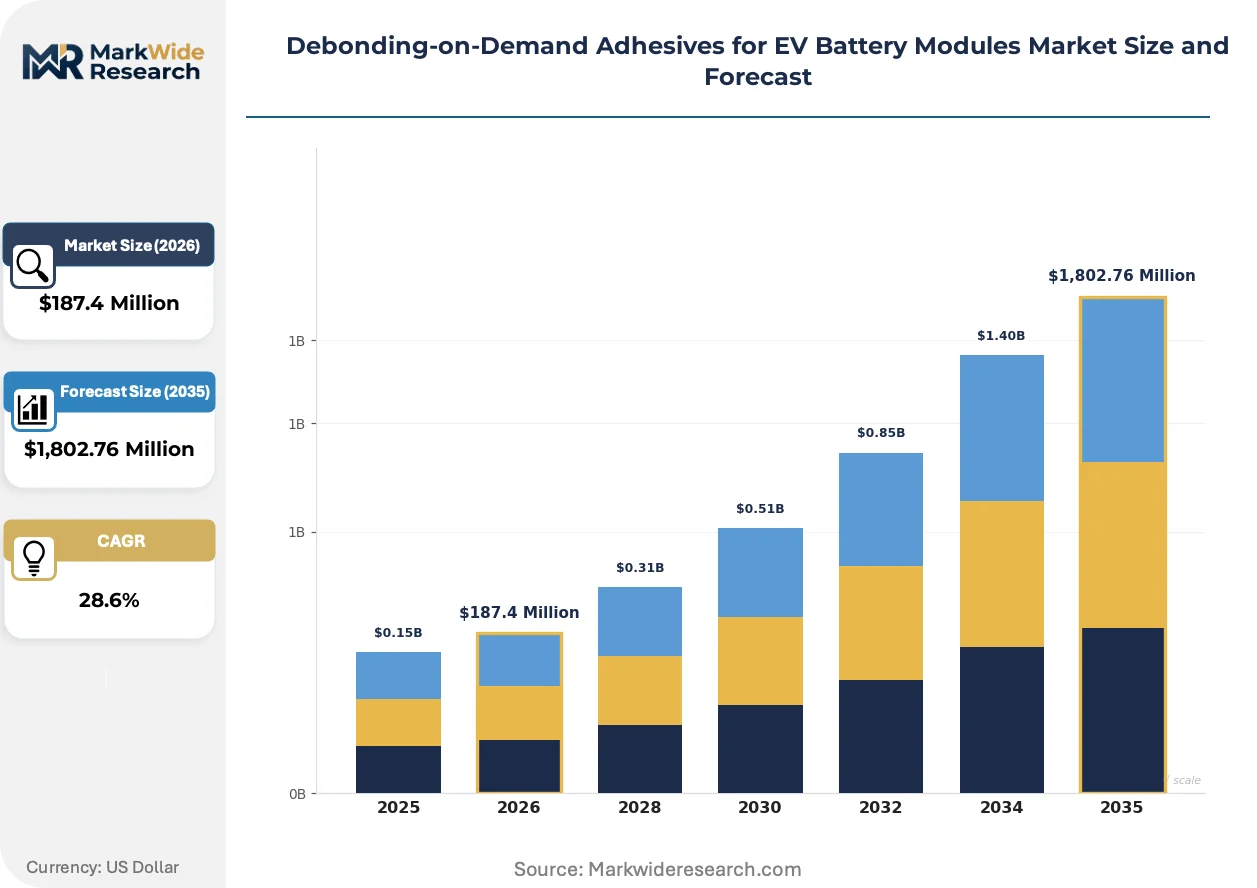
Market Dynamics
The EU Battery Regulation's design-for-recycling mandate is forcing automakers to reengineer module architectures around reversible bonding systems, creating immediate procurement pressure for thermally labile adhesives that preserve cell integrity during end-of-life extraction.
Growth Catalysts
- REACH compliance frameworks:Chemical registration requirements in Europe are eliminating solvent-based debonding alternatives, directing capital toward thermal and electrical activation chemistries that align with workplace exposure limits.
- Second-life battery economics:Stationary energy storage integrators require non-destructive cell extraction to harvest viable cells from retired EV packs, creating pull-through demand for precision debonding materials.
- German automaker consortiums:Volkswagen, BMW, and Mercedes-Benz are co-developing reversible adhesive specifications with cell producers, establishing technical standards that cascade through European supply chains.
Market Restraints
- Epoxy resin price volatility:Structural formulations depend on bisphenol-A and specialty hardeners whose feedstock costs fluctuate with crude oil and natural gas benchmarks, compressing margin stability for adhesive compounders.
- Asian conductive filler concentration:Silver flake and carbon nanotube supply concentrates in Chinese and Japanese chemical processors, exposing Western formulators to geopolitical trade friction and export licensing delays.
- Thermal activation speed limitations:Heat-triggered systems require 5-15 minutes to reach debond thresholds, creating throughput bottlenecks that UV-triggered alternatives have yet to scale sufficiently to offset.
Strategic Opportunities
- Indian PLI scheme alignment:Production-linked incentives for domestic cell manufacturing create openings for adhesive suppliers to establish localized formulation facilities serving Tata and Reliance battery ventures.
- Photoresponsive moiety convergence:UV-triggered debonding is merging with machine vision-guided robotic disassembly, enabling sub-second activation cycles that match automated line speeds in planned European recycling facilities.
- Subscription performance monitoring:Adhesive suppliers can capture recurring revenue through embedded thermal sensors and predictive debonding analytics, shifting monetization from material sales to outcome-based service tiers.
Industry Challenges
- Thermal engineering talent scarcity:Formulation chemists with expertise in labile linkage design and conductive filler dispersion command premium compensation, constraining R&D expansion at mid-tier suppliers.
- Automotive qualification timelines:OEM validation cycles for battery module adhesives extend 24-36 months, delaying revenue recognition for novel debonding chemistries even after technical proof-of-concept.
- Legacy pack heating incompatibility:Existing thermal management systems in deployed EV fleets lack precision temperature control, requiring retrofit hardware to enable safe debonding without cell damage.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debonding-on-Demand Adhesives for EV Battery Modules Market Trends and Innovations
Activation mechanism diversification is fragmenting technical roadmaps as suppliers place competing bets on thermal precision versus speed economics, while regulatory pressure accelerates standardization efforts across European and North American jurisdictions.
UV-triggered photoresponsive adhesives are overtaking thermal systems in pilot recycling lines where robotic disassembly demands sub-second cycle times. European pack dismantlers are retrofitting UV arrays alongside existing heating infrastructure to benchmark throughput gains. This speed advantage is compressing the investment window for thermal-only equipment and favoring hybrid-activation formulations.
The EU Battery Regulation's recycled content mandates are forcing cell producers to document end-of-life material recovery rates. Germany's KBA and France's ANSM are developing certification protocols for reversible bonding systems that satisfy these traceability requirements. Module suppliers serving Stellantis and Renault are prioritizing adhesives with pre-qualified regulatory documentation to accelerate homologation timelines.
Automotive procurement teams are consolidating adhesive specifications across multiple cell platforms to reduce qualification overhead. Tier-1 module integrators are replacing discrete material sourcing with multi-year performance contracts that bundle formulation supply with disassembly technical support. This consolidation is most visible in Germany and South Korea, where Hyundai and SK On are standardizing on single-supplier debonding architectures.
Debonding-on-Demand Adhesives for EV Battery Modules Market Segmentation
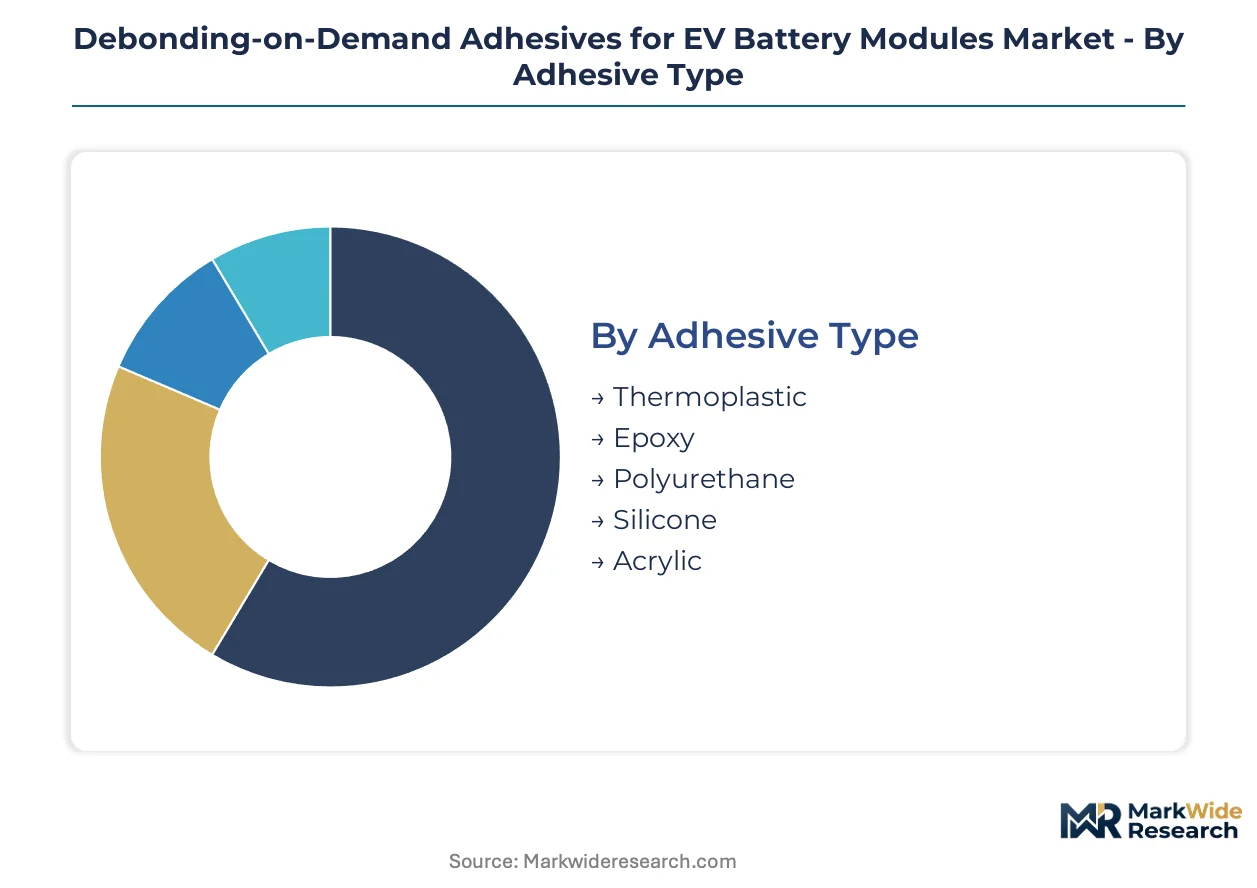
Debonding-on-demand adhesives fragment across four structural dimensions that determine procurement priorities. Adhesive type and activation mechanism define the technical solution set, while end-user sector and application area dictate commercial engagement models and margin capture potential.
Adhesive Type:
Epoxy and polyurethane formulations anchor structural bonding applications where load-bearing integrity under thermal cycling is non-negotiable, while thermoplastic and silicone variants serve modular, repositionable use cases requiring lower bond strength.
- Epoxy:Cross-linked thermoset systems incorporating thermally labile linkages deliver structural rigidity and vibration damping for prismatic cell module assemblies. German OEM procurement teams specify these formulations for premium EV platforms where bond failure under crash loads is unacceptable.
- Polyurethane:Two-part systems with tunable modulus characteristics bridge the gap between structural and flexible bonding requirements. Component suppliers serving South Korean cell producers favor polyurethane for pouch cell stack assemblies where thermal expansion mismatch demands compliance.
- Thermoplastic:Reversible physical bonding enables repeated assembly-disassembly cycles without chemical degradation.
- Silicone:High-temperature stability and dielectric properties suit thermal interface applications.
- Acrylic:UV-curable variants offer rapid processing speeds for high-throughput production lines.
Epoxy leads volumes today; acrylic is gaining share fastest.
Activation Mechanism:
Procurement economics diverge sharply between thermal systems that leverage existing pack infrastructure and UV-triggered alternatives that demand capital-intensive retrofitting.
- Thermal:Heat-activated debonding between 80°C and 150°C integrates with standard battery thermal management systems. European recycling facilities in Belgium and the Netherlands prioritize thermal activation for compatibility with legacy pack designs.
- UV Light:Sub-second photoresponsive debonding aligns with robotic disassembly line speeds. Pilot facilities in France are trialing UV arrays alongside machine vision systems to achieve throughput targets mandated by EU Battery Regulation timelines.
- Electrical:Joule heating through conductive filler networks enables localized, cell-specific activation without bulk temperature elevation.
- Chemical:Solvent-triggered systems face declining procurement due to REACH workplace exposure constraints.
- Microwave:Selective dielectric heating offers rapid debonding for specific polymer matrices.
Thermal activation dominates installed base; UV Light climbs the fastest.
End User Sector:
Customer type determines contract structure, with OEMs driving standardization and aftermarket services capturing margin through technical disassembly support.
- Battery Pack Manufacturers:Tier-1 integrators specify adhesive systems during module design phase, locking in multi-year supply agreements. CATL and BYD procurement teams in China are qualifying debondable formulations for export-bound platforms.
- OEMs:Volkswagen, BMW, and Mercedes-Benz co-develop reversible adhesive specifications with suppliers, establishing technical standards that cascade through European supply chains.
- Component Suppliers:Cell producers and subsystem integrators procure adhesives as specified by downstream customers.
- Aftermarket Services:Independent recyclers and second-life battery integrators demand debonding technical support bundled with material supply.
Battery Pack Manufacturers lead volumes today; Aftermarket Services is expanding most quickly.
Application Area:
Functional requirements vary dramatically between structural load-bearing applications and thermal management interfaces where dielectric properties dominate selection criteria.
- Module Assembly:Structural bonding of cells to frames and cooling plates demands highest bond strength and thermal cycling resistance. German automakers specify module-grade epoxies with documented debonding protocols for end-of-life compliance.
- Cell Encapsulation:Potting and sealing applications protect electrochemical components from moisture and mechanical shock. SK On in South Korea is piloting debondable encapsulants that enable cell harvesting without electrolyte contamination.
- Thermal Management:Interface materials between cells and cooling systems prioritize thermal conductivity and electrical isolation.
- Electrical Insulation:Dielectric coatings prevent short circuits while maintaining debondability for maintenance access.
Module Assembly leads volumes today; Cell Encapsulation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest procurement volumes for debondable adhesives, while China's cell producers are rapidly qualifying reversible bonding systems for export-bound platforms. The United States trails on regulatory momentum but maintains significant R&D concentration. South Korea and Japan anchor specialized formulation expertise for high-performance thermal management applications.
Germany
Volkswagen, BMW, and Mercedes-Benz procurement teams are co-developing reversible adhesive specifications with cell producers, establishing technical standards that cascade through European supply chains. The EU Battery Regulation's design-for-recycling mandate directly favors debondable bonding systems, with KBA developing certification protocols for traceable end-of-life recovery. Stuttgart and Munich industrial clusters concentrate adhesive qualification laboratories serving premium EV platforms.
China
CATL and BYD are qualifying debondable formulations for battery packs bound for European and North American export markets. GB standards evolution and MIIT industrial material certifications determine whether domestic producers adopt reversible bonding architectures or maintain permanent adhesion conventions. Shenzhen and Ningbo manufacturing hubs host pilot lines testing thermally labile adhesive systems for prismatic cell modules.
United States
EPA hazardous waste classifications and OSHA workplace exposure limits constrain solvent-based chemical debonding alternatives, steering investment toward thermal and electrical activation pathways. The Inflation Reduction Act's domestic content incentives support localized adhesive formulation facilities. Michigan and California R&D centers focus on Joule heating through conductive filler networks for cell-specific activation.
South Korea
SK On and Hyundai are standardizing on single-supplier debonding architectures across multiple cell platforms to reduce qualification overhead. MFDS-adjacent industrial material certifications shape adhesive selection criteria for domestic battery production. Seoul and Ulsan industrial corridors concentrate module integrators piloting debondable encapsulants that enable cell harvesting without electrolyte contamination.
Japan
Specialty chemical producers leverage expertise in precision polymer synthesis to compete on temperature-precision activation thresholds. METI industrial technology roadmaps support R&D in photoresponsive moiety convergence for sub-second debond speeds. Osaka and Nagoya chemical clusters develop hybrid-activation formulations merging thermal infrastructure compatibility with UV-triggered speed economics.
Debonding-on-Demand Adhesives for EV Battery Modules Market Competitive Landscape
Top-tier vendors anchor premium structural formulations, while mid-scale compounders occupy specialized thermal management niches. The vendor base stratifies across three tiers: multinational chemical conglomerates with automotive electronics scale, regional adhesive specialists with battery-specific expertise, and emerging technology developers focused on novel activation mechanisms. Strategic consolidation through formulation-supply-plus-technical-support bundles is displacing discrete material sourcing. Geographic expansion into Indian and Southeast Asian cell manufacturing zones represents the dominant competitive move alongside multi-year performance contracting with tier-1 module integrators.
Within the multinational chemical tier, Henkel and Arkema occupy positions exemplifying divergent competitive approaches to reversible bonding system development. Henkel leverages scale in automotive electronics to sustain R&D intensity across thermally triggered debonding chemistries, while Arkema anchors its market presence through specialty polymer expertise competing on precise activation thresholds. H.B. Fuller represents the mid-tier specialist archetype, with its adhesive formulation heritage positioning it for qualification cycles with emerging cell producers in India and Southeast Asia. These three entities collectively illustrate how competitive positioning fragments across scale-driven platform coverage versus precision-specialization vectors.
| Leading Market Players |
|---|
| Henkel |
| Arkema |
| H.B. Fuller |
| Sika |
| tesa |
| DuPont |
| Avery Dennison |
| 3M |
| Delo Industrial Adhesives |
| Others |
Pricing and Supply Chain Analysis
German automaker procurement teams are consolidating adhesive specifications across multiple cell platforms, forcing suppliers to absorb qualification overhead into long-term contract pricing or risk volume displacement to qualified competitors.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for conductive filler inputs, compressing margin pools for Western compounders. Three-tier pricing structure across premium, standard, and economy levels separates Henkel and Arkema formulations from mid-tier polyurethane suppliers and commodity acrylic entrants. Cost compression in thermal activation epoxies is intensifying because bisphenol-A feedstock costs track volatile natural gas benchmarks. Aftermarket recyclers exhibit highest price sensitivity; OEM co-development programs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese silver flake and carbon nanotube processors, exposing Western formulators to export licensing delays. Manufacturing concentrates in Germany, South Korea, and Japan for specialty polymer synthesis; formulation compounding clusters in Belgium and the Netherlands for European recycling facility proximity. Raw material dependencies include epoxy resins, conductive fillers, and photoresponsive initiators. Tariff exposure on Asian filler imports feeds into pricing. Distribution runs through Tier-1 module integrators with multi-year performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU Battery Regulation traceability mandates are shifting procurement criteria toward certified debonding protocols with documented end-of-life recovery rates.
For Market Incumbents: Acquire formulation-supply-plus-technical-support bundles to lock in multi-year performance contracts before qualification cycles complete. Deepen backward integration into conductive filler networks to offset Asian supply concentration. Defend against UV-triggered entrants by accelerating hybrid-activation R&D in Stuttgart and Munich industrial clusters. For New Entrants and Emerging Players: Enter via Indian PLI scheme alignment, establishing localized facilities to serve Tata and Reliance battery ventures before incumbent qualification cycles conclude. Target aftermarket services for second-life battery integrators demanding disassembly technical support. Pursue photoresponsive moiety convergence with machine vision-guided robotic disassembly as the go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty polymer developers holding precision activation threshold expertise. Five-to-ten year viability hinges on regulatory ratchet effects from EU Battery Regulation recycled content mandates. Watch for KBA certification protocol finalization as inflection indicator for standardization-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Fillers | Captive supply of silver flake reduces exposure to Chinese export licensing delays. |
| Hybrid-Activation Formulation Launch | Henkel and Arkema R&D in thermal-UV convergence matches European recycling line speeds. |
| Indian Manufacturing Footprint Expansion | Localized compounding facilities capture PLI scheme benefits for Tata and Reliance supply. |
| Long-term Performance Contracting | Multi-year agreements with SK On and Hyundai reduce qualification overhead per platform. |
| Photoresponsive Patent Portfolio Acquisition | Specialty polymer expertise in sub-second activation thresholds commands premium positioning. |
Research Methodology
Direct dialogue with adhesive formulation chemists, Tier-1 module integrator procurement leads, European recycling facility operators, and OEM platform engineers grounded qualitative assessments in operational reality. Secondary validation drew from ECHA REACH registration databases, EU Battery Regulation implementation guidance, KBA technical documentation, customs trade data for epoxy resin and conductive filler flows, and SEC filings from listed chemical conglomerates. Bottom-up volume estimates triangulated against top-down market sizing from adhesive consumption per battery pack.
Segmented projections across adhesive type, activation mechanism, end-user sector, and application area fed into analytical framework spanning the projection horizon. CAGRs derived from regression against EV production forecasts, EU Battery Regulation compliance timelines, and second-life battery market formation curves. Industry-specific inputs included thermal cycling performance requirements, debonding activation energy thresholds, and robotic disassembly line throughput specifications.
Inputs from KBA pre-certification protocols and ECHA substance registration databases were available through the study window; gaps in Chinese GB standards evolution and MIIT industrial material certification timelines introduce uncertainty bands around China adoption trajectory. Forecasts reflect assumptions on regulatory ratchet speed, conductive filler supply continuity, and thermal engineering talent availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.