
 Global Disposable Hygiene Adhesives Market | 2026-2036
Global Disposable Hygiene Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Hygiene Adhesives Market Intelligence
The substitution of traditional solvent-based formulations with advanced bio-based hot melt adhesives is restructuring product economics and sustainability profiles. H.B. Fuller Company leverages its extensive R&D in polymer science to develop high-performance, skin-friendly solutions for baby diapers. Henkel AG & Co. KGaA competes on a global scale with a broad portfolio catering to both personal care and medical applications. Bostik specializes in smart adhesive technologies for complex multi-layer hygiene products.
Disposable hygiene adhesives are specialized bonding agents designed for assembling multi-layer nonwoven consumer goods. These materials must exhibit low odor, high cohesion, and appropriate peel strength for skin contact safety and product integrity. Hot melt adhesives command the largest share of the market due to their rapid set times and suitability for high-speed manufacturing lines. While baby diapers remain the primary application, the adult incontinence segment represents the fastest-growing area of consumption.
Regulatory frameworks significantly influence material selection and market access for adhesive formulators. In Europe, the ECHA's REACH regulation restricts specific chemical substances, while the US FDA governs materials used in products with skin contact. Compliance with standards from bodies like Japan's METI is also critical for market entry. Navigating the trade-off between material performance, production cost, and escalating demands for sustainable, bio-compatible ingredients remains the central challenge for all stakeholders.
Market Dynamics
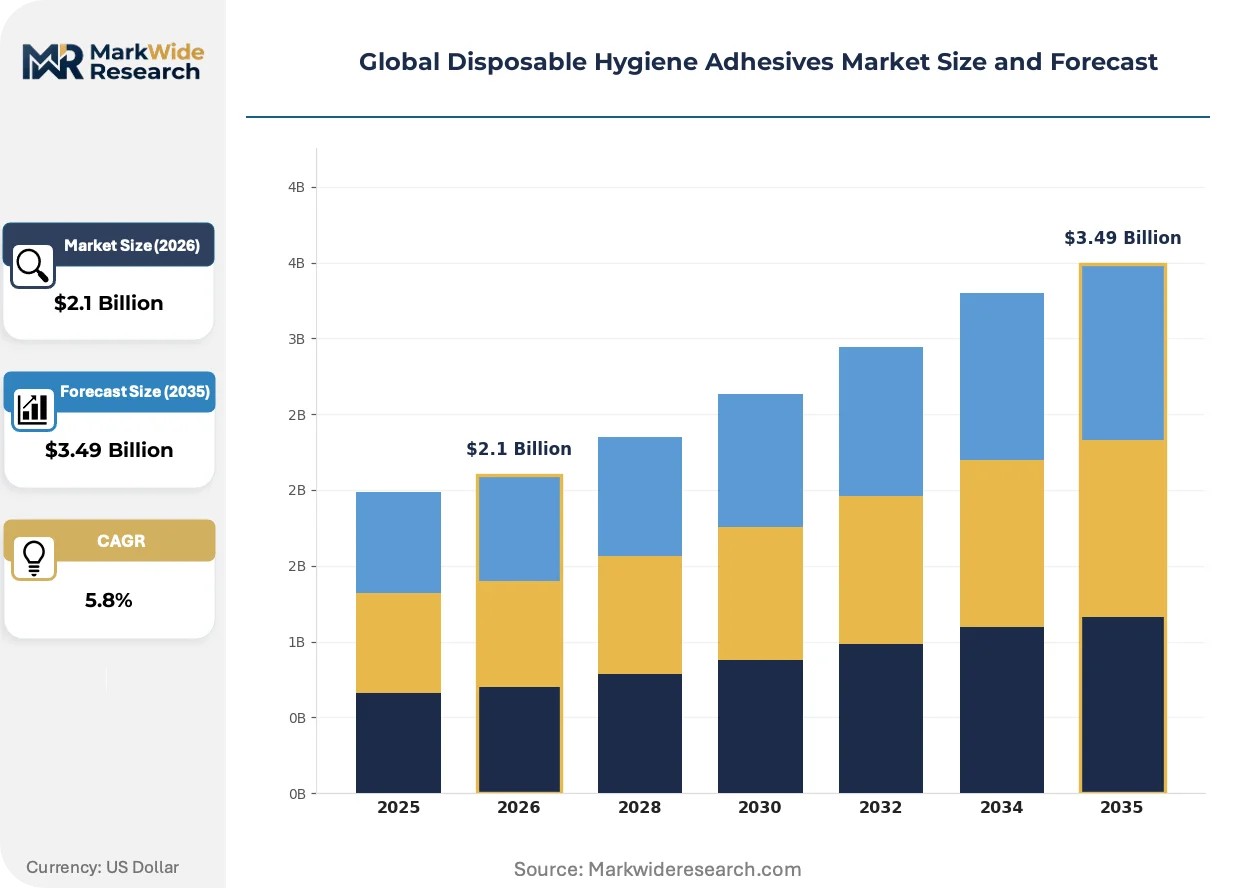
The central dynamic in the disposable hygiene adhesives market is the tension between escalating raw material costs for traditional petrochemical-based adhesives and intensifying regulatory and consumer pressure for sustainable, skin-friendly bio-based alternatives, particularly in mature markets.
Growth Catalysts
- Aging Demographics:The expanding elderly population in countries like Japan, Germany, and Italy directly stimulates consumption of adult incontinence products, which are a primary application for high-performance, skin-safe adhesives that offer both security and comfort.
- Regulatory Scrutiny:Regulations such as Europe's ECHA REACH framework push formulators toward developing safer materials by restricting certain chemicals, creating a built-in demand for innovative, compliant adhesive solutions in the baby diaper and feminine care segments.
- Manufacturing Automation:The adoption of high-speed automated assembly lines in nonwoven product manufacturing favors hot melt adhesives due to their rapid setting times, which are essential for maintaining production efficiency and minimizing unit costs.
Market Restraints
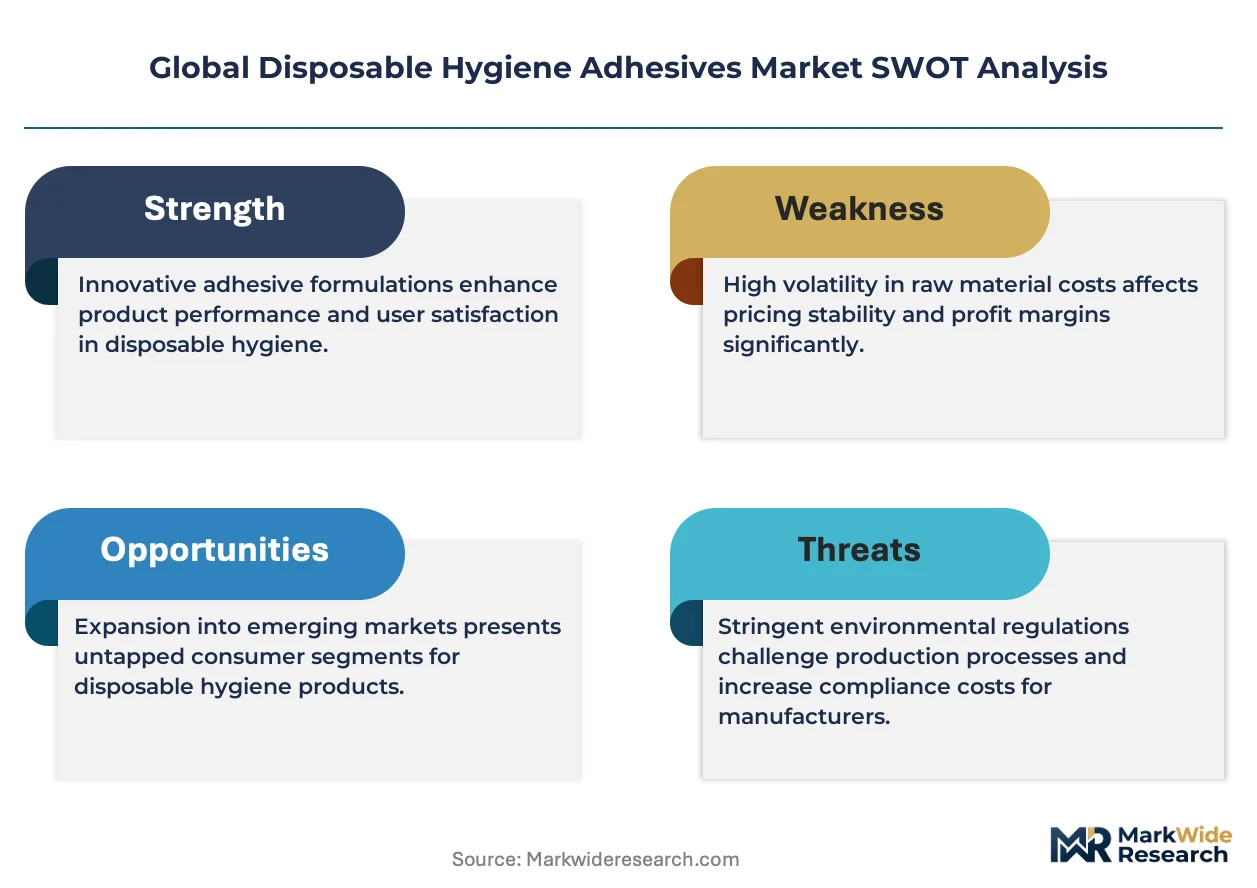
- Raw Material Volatility:The market is vulnerable to price fluctuations in petroleum-derived feedstocks, such as styrenic block copolymers (SBCs) and polyolefins, which can compress formulator margins and create pricing instability for finished goods manufacturers.
- Technical Performance Trade-offs:Developing bio-based adhesives that match the peel strength, cohesion, and processing speed of traditional synthetic hot melts without a significant cost premium remains a considerable technical barrier for material scientists.
- Substitution from Alternative Bonding:In some product layers, the threat of substitution from non-adhesive bonding methods, such as ultrasonic welding or thermal bonding, can limit the total addressable volume for adhesives, especially for simpler product constructions.
Strategic Opportunities
- Bio-Based Formulations:There is a significant opportunity to develop and commercialize adhesives derived from renewable resources like plant-based resins and oils, meeting corporate sustainability goals and consumer demand for "greener" disposable products.
- Expansion into Medical Applications:Adhesive technologies developed for sensitive skin in hygiene products can be adapted for adjacent medical markets, including wound care dressings and medical device fixation, which require stringent biocompatibility and gentle removal.
- Emerging Market Penetration:Increasing disposable incomes and hygiene awareness in large-population countries across Southeast Asia and Latin America present untapped geographic markets for both standard and premium disposable hygiene products and their adhesive components.
Industry Challenges
- Complex Compliance Pathways:Navigating the fragmented and evolving regulatory landscape, including compliance with the US FDA for skin-contact materials and Japan's METI standards, presents a significant operational hurdle and extends product development timelines.
- Balancing Cost and Sustainability:Formulators face the persistent challenge of managing the cost-performance balance, as sustainable and bio-compatible ingredients often carry a price premium that is difficult to pass on in a competitive, high-volume market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Hygiene Adhesives Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Solvent Based, Water Based, Reactive Adhesives, UV Curable Application: Baby Diapers, Feminine Hygiene, Adult Incontinence, Medical Dressings, Industrial Wipes End User: Personal Care Manufacturers, Medical Device Makers, Institutional Consumers, Industrial Fabricators Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Specialty Stores |
| Companies Covered | 3M Company, Dow Inc., H.B. Fuller Company, Nordson Corporation, Huntsman International, Henkel AG & Co. KGaA, Avery Dennison Corporation, Arkema Group, Bostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Hygiene Adhesives Market Strategic Shifts & Innovations
The competitive landscape is being defined by a fundamental pivot toward materials that satisfy both sustainability mandates and advanced performance requirements. This dual focus compels innovation in polymer science to create adhesives that are both environmentally responsible and compatible with high-speed manufacturing.
Advanced bio-based hot melt adhesives are formulated from renewable feedstocks like plant-derived resins. Manufacturers of premium baby diapers and adult incontinence products are adopting these materials to enhance their products' sustainability profiles. This shift is rewriting the material science playbook, forcing a re-evaluation of supply chains and performance benchmarks for skin-contact bonding agents in consumer goods.
European chemical safety legislation, specifically the ECHA's REACH regulation, restricts the use of certain substances of very high concern (SVHCs). This directly impacts adhesive formulations by requiring the phase-out of specific plasticizers, tackifiers, and antioxidants. The baby care and feminine hygiene segments are most affected, prompting accelerated research into safer, compliant alternative ingredients that maintain product integrity.
Consumer demand for products marketed as skin-friendly and hypoallergenic is altering purchasing criteria for hygiene goods. This behavioral shift disrupts traditional procurement, which once prioritized bond strength and cost, by adding criteria like low odor and third-party dermatological testing certification. This trend is particularly visible in the competitive direct-to-consumer diaper and feminine care markets across North America and Europe.
Global Disposable Hygiene Adhesives Market Segmentation
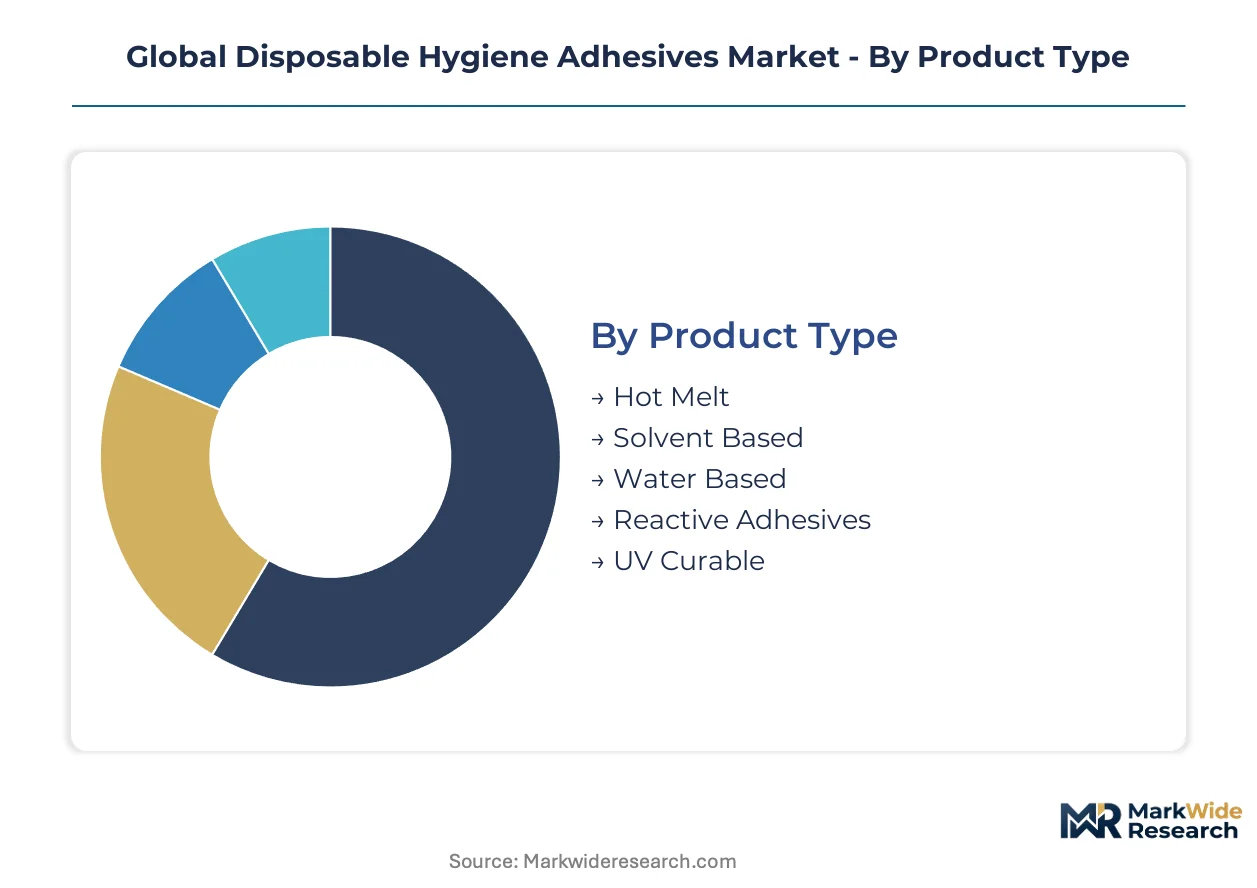
Understanding the segmentation of the global disposable hygiene adhesives market provides crucial insights into product development priorities and market penetration strategies. Each segment reflects distinct performance requirements, regulatory landscapes, and consumer expectations, influencing material selection and supplier specialization. This granular view helps stakeholders identify areas of high growth and emerging competitive dynamics.
Product Type:
The product type segment navigates a spectrum from highly customized formulations to standardized, high-volume offerings. Manufacturers balance specific application needs with the economies of scale offered by widely adopted adhesive technologies.
- Hot Melt:These thermoplastic adhesives are applied in a molten state and solidify rapidly upon cooling, facilitating high-speed manufacturing lines. Demand concentrates in baby diapers and adult incontinence products, driven by their rapid setting times and strong bond strength.
- Water Based:These adhesives utilize water as a carrier, offering environmental benefits and easier cleanup compared to solvent-based alternatives. Adoption is increasing across Europe for feminine hygiene products, driven by regulatory pressures for reduced VOCs and consumer demand for "greener" products.
- Solvent Based:Formulations rely on organic solvents for adhesion, providing strong bonds but facing increasing regulatory scrutiny in regions like the EU under REACH.
- Reactive Adhesives:These adhesives undergo a chemical reaction to cure, forming durable bonds often used in more complex, multi-layer constructions.
- UV Curable:Adhesives that cure upon exposure to ultraviolet light offer precise control over setting times and are gaining traction in specialized medical applications.
Most installed capacity flows through Hot Melt. Expansion is steepest in Water Based formulations.
Application:
This category highlights the varied end-uses for disposable hygiene adhesives, with distinct volume requirements and performance criteria defining each application's market size.
- Baby Diapers:This application demands adhesives with high cohesion, appropriate peel strength, and skin-friendly properties for sensitive infant skin. High-volume production in Asia and North America drives the need for efficient, cost-effective bonding solutions.
- Adult Incontinence:Products for adult incontinence require adhesives offering superior absorbency, leak protection, and comfort for an aging demographic. Markets in Japan and Germany are seeing significant growth due to expanding elderly populations.
- Feminine Hygiene:Adhesives for feminine hygiene products prioritize flexibility, discretion, and secure attachment to undergarments, often incorporating low-odor formulations.
- Medical Dressings:These specialized applications require biocompatible adhesives with gentle adhesion and removal properties, adhering to stringent standards set by bodies like the US FDA.
- Industrial Wipes:Adhesives used in industrial wipes must withstand various chemicals and provide robust bonding for demanding cleaning tasks in commercial settings.
Baby Diapers represent the largest volume segment. The Adult Incontinence segment is expanding most quickly.
End User:
The end-user segmentation reveals the diverse customer base for hygiene adhesives, each with unique procurement processes and product specifications shaped by their operational maturity.
- Personal Care Manufacturers:These large-scale producers of baby diapers, feminine hygiene products, and adult incontinence items require consistent supply, technical support, and competitive pricing for high-volume production. Their procurement often prioritizes cost-efficiency and supply chain reliability.
- Medical Device Makers:Manufacturers of medical dressings and related healthcare products demand adhesives with stringent biocompatibility, sterilization compatibility, and regulatory compliance, adhering to standards from agencies like Europe's EMA. Their focus is on product safety and performance validation.
- Institutional Consumers:This segment includes hospitals, nursing homes, and other care facilities that procure hygiene products in bulk for patient and resident care. Their purchasing decisions emphasize comfort, absorbency, and cost-effectiveness.
- Industrial Fabricators:Companies that produce industrial wipes and other nonwoven components utilize adhesives for specialized bonding tasks in manufacturing processes. Their requirements often focus on specific technical performance and processing compatibility.
Personal Care Manufacturers command the largest share of adhesive procurement. Medical Device Makers are increasingly influencing advanced adhesive development.
Distribution Channel:
The distribution channels illustrate how disposable hygiene adhesives reach their end-users, reflecting varying levels of supply chain concentration and direct engagement.
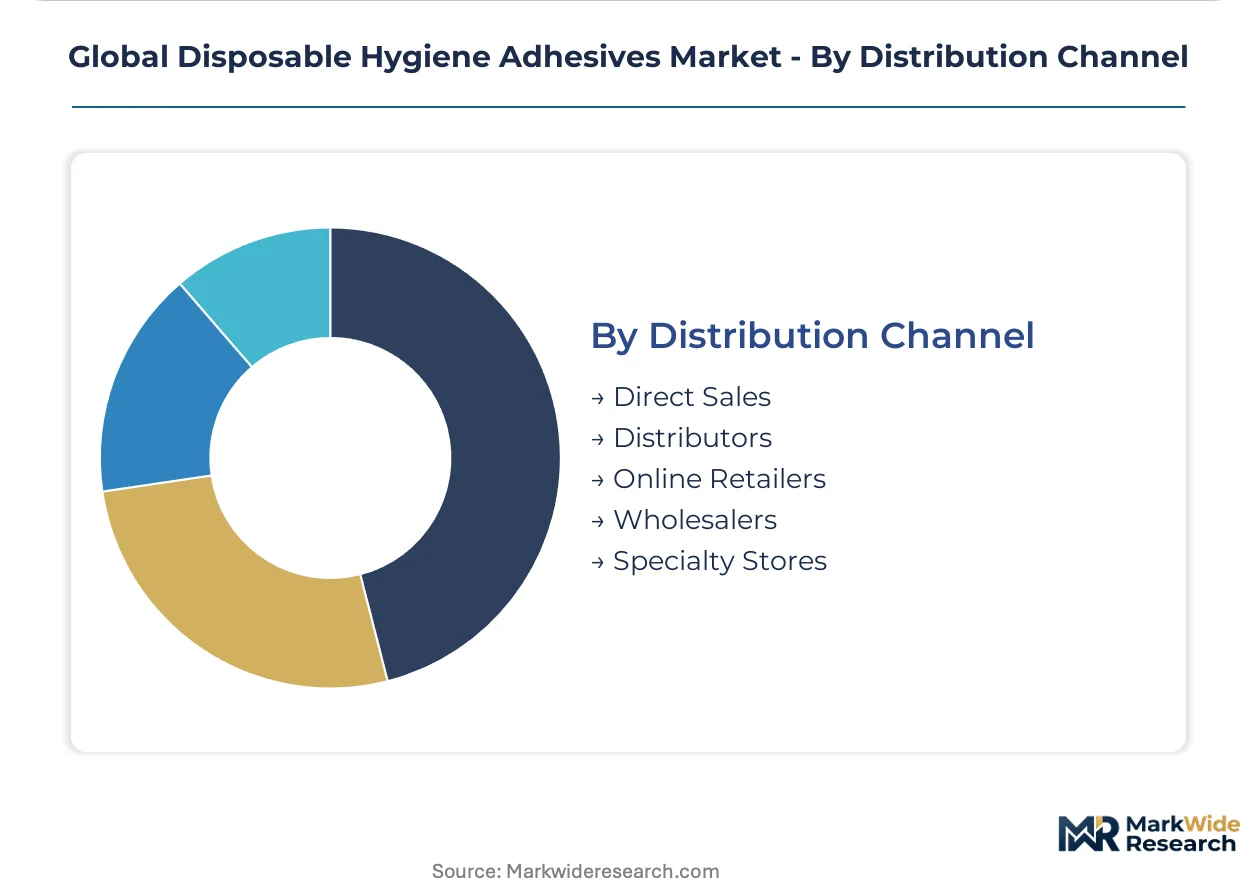
- Direct Sales:Adhesive manufacturers engage directly with large-volume end-users, offering customized solutions, technical support, and direct supply chain integration. This channel is critical for strategic partnerships with major personal care manufacturers.
- Distributors:These intermediaries manage logistics and sales for smaller and mid-sized end-users, offering a broader range of products and localized inventory. Distributors play a vital role in reaching diverse regional markets.
- Online Retailers:While less common for bulk industrial adhesives, online platforms facilitate procurement for smaller businesses or specialized niche products, offering convenience and broader product discovery.
- Wholesalers:Wholesalers purchase adhesives in bulk from manufacturers and resell to distributors or larger end-users, often serving as a bridge in fragmented supply chains.
- Specialty Stores:This channel typically caters to very specific, niche adhesive requirements or smaller-scale industrial users, often providing expert advice and tailored product selections.
The majority of adhesive volume moves through Direct Sales. Online Retailers are gaining share fastest for specialized or smaller-batch orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta's extensive manufacturing infrastructure underpins a significant portion of global disposable hygiene adhesive demand. This region, alongside key markets in Europe and North America, drives innovation and consumption patterns. Expanding applications in adult incontinence products shape regional growth trajectories.
Japan
Demand for adult incontinence products increases due to aging demographics. METI standards influence material selection for product safety and environmental impact. Tokyo's advanced materials research centers drive innovation in bio-based adhesive formulations.
Germany
European ECHA REACH regulations mandate the use of safer chemical substances. This pushes formulators toward compliant and sustainable adhesive solutions. The Rhine-Main region fosters specialized chemical manufacturing and adhesive development for personal care.
United States
Baby diapers represent a substantial volume segment, requiring high-performance adhesives. The US FDA governs materials used in skin-contact products, ensuring consumer safety. North Carolina's nonwovens industry concentrates on high-speed production lines for disposable goods.
China
Expanding disposable incomes accelerate demand for premium baby diapers and feminine hygiene products. National quality standards and local environmental regulations shape adhesive formulations. Major manufacturing hubs like the Yangtze River Delta lead in adopting advanced adhesive technologies.
Brazil
Growing hygiene awareness across Latin America stimulates consumption of disposable products. ANVISA regulations influence the import and local production of compliant adhesive materials. São Paulo's industrial zones develop local production capabilities for hygiene product components.
Global Disposable Hygiene Adhesives Market Key Industry Players
Global majors compete with regional champions across product innovation and market access within the disposable hygiene adhesives market. The market structure exhibits consolidation among top-tier suppliers, while a fragmented base of specialized manufacturers serves niche applications. Strategic archetypes include diversified chemical conglomerates and dedicated adhesive solution providers. Companies pursue portfolio diversification and strategic partnerships to strengthen their market positions.
At the scale-driven end, H.B. Fuller Company (a US-based Inc.) occupies a position as a specialized adhesive provider with extensive polymer science R&D. Henkel AG & Co. KGaA (a German AG & Co. KGaA) represents a diversified chemical conglomerate with a broad portfolio across personal care and medical applications. Bostik (a French-origin company) sits within the archetype of smart adhesive technology innovators, focusing on complex multi-layer hygiene products. These entities anchor distinct segments of the adhesive supply chain.
| Leading Market Players |
|---|
| 3M Company |
| Dow Inc. |
| H.B. Fuller Company |
| Nordson Corporation |
| Huntsman International |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Arkema Group |
| Bostik |
| Others |
Cost & Logistics Intelligence
The ECHA REACH regulation, an environmental mandate, significantly gates qualified supply and premium-tier pricing access for disposable hygiene adhesives. This framework drives formulators towards compliant, often higher-cost, bio-based materials, influencing procurement decisions across Europe.
Pricing Analysis
Input-cost pass-through mechanisms are critical for adhesive formulators, particularly given the volatility of petrochemical-derived feedstocks like styrenic block copolymers. The dominant pricing model involves contract-based long-term offtake agreements, often with raw material adjustment clauses. Price differentiation stems from bio-based content certification and specialized technical performance required for high-speed manufacturing lines. Pricing softness is evident in commodity-grade segments due to intense competition among suppliers. Medical Device Makers exhibit lower price sensitivity, prioritizing stringent biocompatibility and regulatory compliance, unlike Personal Care Manufacturers who remain highly cost-conscious for high-volume products.
Supply Chain Analysis
Japan's METI standards and Europe's ECHA regulations increasingly reshape sourcing towards locally compliant or regionally produced materials. Geographic supply concentration for base petrochemicals draws from regions with significant refining capacity, while advanced bio-based ingredients often originate from specialized producers in Europe and North America. The market depends on raw material inputs such as styrenic block copolymers, polyolefins, and plant-based resins. Commodity price volatility for petrochemical feedstocks represents a significant structural risk. Direct Sales to major Personal Care Manufacturers dominate the downstream distribution model, ensuring technical support and customized solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ECHA REACH regulation acts as a regulatory compounder in this market, driving demand for innovative, compliant adhesive solutions across the hygiene sector.
For Market Incumbents:
Anticipate continued raw material volatility by securing diversified feedstock agreements, including long-term contracts for bio-based inputs. Invest heavily in polymer science R&D to develop next-generation, cost-effective bio-based hot melt adhesives that match synthetic performance. Diversify manufacturing footprints to mitigate geopolitical risks and improve regional supply chain resilience. Obtain advanced certifications like FDA biocompatibility to address the growing medical applications segment, countering the threat of substitution from alternative bonding methods.
For New Entrants and Emerging Players:
Specialized distributors offer a viable entry point for novel adhesive technologies, particularly for smaller-batch, high-value applications. Target the underpenetrated adult incontinence segment in rapidly aging markets like Japan and Germany with premium, skin-friendly bio-based formulations. Focus on developing adhesives with superior environmental profiles and obtaining strong sustainability certifications, providing a distinct go-to-market angle. Pursue partnerships with direct-to-consumer brands in the feminine care and baby diaper segments, which value product differentiation.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized adhesive formulators because of the fragmented nature of niche bio-based ingredient suppliers and regional compliance requirements. The long-term viability of this market is strong, driven by sustained global hygiene awareness and aging demographics over the next 5-10 years. Target mid-sized companies with proprietary bio-based adhesive technologies or strong regional market shares in compliant formulations. A key signal to watch is the successful commercialization of cost-competitive, high-performance bio-based adhesives at scale, indicating market readiness for broader adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based R&D Acceleration | Drives product differentiation and market share in the sustainability-conscious hygiene sector. |
| Regional Manufacturing Expansion | Enhances supply chain resilience and compliance with local regulatory frameworks like METI standards. |
| Strategic Bio-Feedstock Partnerships | Secures stable, cost-effective supply of renewable resources for advanced adhesive formulations. |
| Enhanced Regulatory Compliance Certification | Unlocks access to premium medical and personal care segments with stringent safety requirements. |
| Targeted Acquisition of Niche Formulators | Expands technology portfolio and market presence in specialized, high-growth application areas. |
Research Approach
Bottom-up application (end-use) modeling reconciled against top-down adhesive supply-side tracking forms the analytical core of this study. This approach integrates insights from primary interviews with R&D directors, procurement managers at personal care manufacturers, regulatory affairs specialists, and nonwoven product engineers. Secondary validation draws from ECHA publications, FDA guidance documents, METI standards, and industry association reports.
Historical trendline analysis provides the foundation for projecting market trajectories across the analysis window. The quantitative framework models volume and value outputs across key segmentation dimensions including product type, application, end-user, distribution channel, and bio-based content percentage. Compound Annual Growth Rates (CAGRs) are derived through a rigorous statistical approach, incorporating industry-specific forecast inputs such as global demographic shifts and petrochemical feedstock price forecasts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts and rapid advancements in non-adhesive bonding methods. The projections reflect assumptions regarding technological evolution and market dynamics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Butyl Adhesive Market