
 Access Control As a Service Market | 2026-2036
Access Control As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Access Control As a Service Market Intelligence
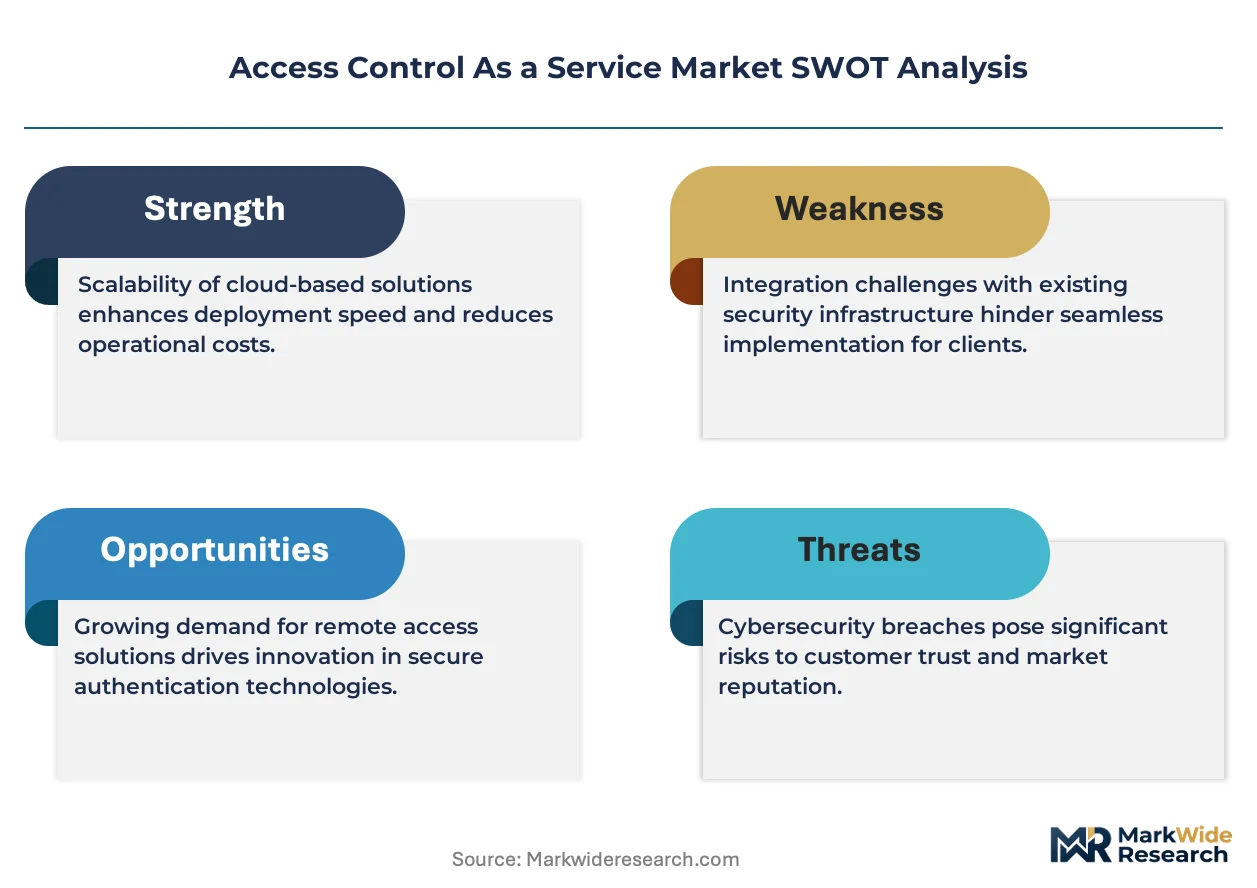
The capital investment barrier between legacy hardware installers and cloud-native service providers is collapsing due to the commoditization of IP-based controllers. Established players like Johnson Controls leverage vast installation networks to bundle ACaaS with other building management services. In contrast, specialists such as Brivo Inc. and Kisi Inc. differentiate through open API platforms and user experience design.
Access Control as a Service (ACaaS) is a security delivery model where a third-party provider hosts and manages the software and infrastructure for physical access control. The service utilizes cloud-based platforms to manage credentials and monitor entry points via IP-connected hardware. The cloud-based service model constitutes the largest share of the market. Within authentication technologies, mobile credentials exhibit the highest adoption velocity, displacing legacy smart cards in corporate campus deployments.
Data privacy regulations, including the EU's GDPR and the US's HIPAA, mandate stringent access logging and auditing capabilities. ACaaS platforms are well-positioned to meet these requirements, and conformance with ISO 27001 also shapes procurement decisions. The critical decision for facility managers and IT administrators is how to integrate these physical security systems with their existing logical access and identity management frameworks.
Market Dynamics
The convergence of physical security infrastructure with IT identity management frameworks, compelled by data sovereignty regulations like the EU's GDPR, is the central force structuring the market. This integration transforms access control from a siloed facility function into a core component of enterprise-wide security and compliance strategy.
Growth Catalysts
- Regulatory Mandates:Data privacy laws such as the EU's GDPR and the US's HIPAA require stringent, auditable access logs for facilities handling sensitive information, making ACaaS platforms a preferred solution for compliance.
- Technology Commoditization:The falling cost of IP-based controllers and the widespread availability of cloud computing infrastructure lower the barrier to entry for new service providers and reduce deployment costs for end-users.
- Data Center Expansion:Proliferation of hyper-scale data centers, particularly in the United States and Germany, creates sustained demand for scalable, remotely managed physical access control systems to secure critical infrastructure.
Market Restraints
- Retrofit Costs:The significant capital expense and operational disruption associated with replacing legacy analog wiring and door hardware in older commercial buildings can delay or prevent upgrades to IP-based systems.
- Interoperability Hurdles:A lack of universal standards between hardware manufacturers creates proprietary ecosystems, locking customers into a single vendor and complicating integration with third-party software or platforms.
- Legacy System Inertia:Small to medium-sized businesses often retain traditional mechanical lock-and-key or standalone electronic systems due to their perceived simplicity and the absence of recurring subscription fees.
Strategic Opportunities
- Smart Building Integration:Combining ACaaS with building automation systems offers new value by linking access events to HVAC, lighting, and energy management, creating more efficient and responsive environments.
- Service Unbundling:Providers can target specific market niches by offering unbundled services, such as mobile credentialing or visitor management, as standalone apps that integrate with existing access control hardware.
- Emerging Geographies:Commercial real estate and industrial development in markets like Brazil, India, and Southeast Asia present significant greenfield opportunities for cloud-based security deployments.
Industry Challenges
- System Integration Complexity:Connecting ACaaS platforms with disparate enterprise systems, such as HR Information Systems for user provisioning or ERP software for billing, remains a significant technical and operational hurdle.
- Specialized Talent Scarcity:A shortage of technicians with dual expertise in both traditional low-voltage security installation and modern IT networking principles constrains the capacity of system integrators.
- Data Residency Compliance:Service providers face complexity in managing customer data across multiple jurisdictions with conflicting data localization laws, such as those in China and the European Union.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Access Control As a Service Market |
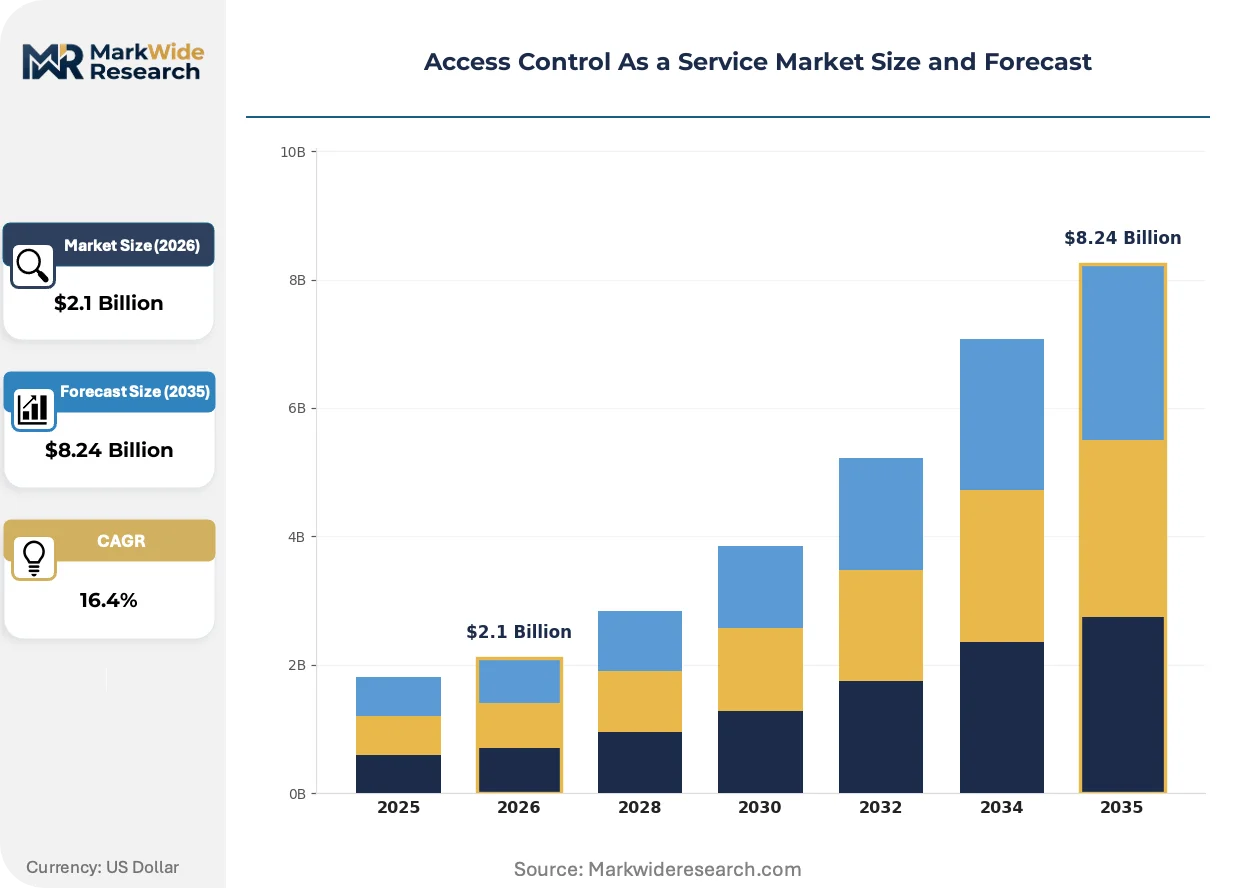
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.24 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Model: Cloud-Based, Hybrid, Dedicated Hosted, Multi-Tenant Authentication Technology: Biometric Recognition, RFID, Mobile Credentials, Smart Cards, PIN Code Deployment Environment: Corporate Campuses, Educational Institutes, Government Facilities, Data Centers, Hospitality Establishments Customer Segment: System Integrators, Managed Security Providers, Facility Managers, IT Administrators |
| Companies Covered | Microsoft Corporation, Brivo Inc., Johnson Controls, Honeywell International Inc., Assa Abloy, Thales, Kisi Inc., Cloudastructure Inc., Kastle Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Access Control As a Service Market Strategic Shifts & Innovations
A fundamental shift toward frictionless user experiences and unified security intelligence defines the current innovation cycle. This evolution moves beyond simple entry management to encompass broader operational and compliance functions within the enterprise, driven by software and data analytics.
Wireless locksets with integrated Bluetooth and NFC readers provide real-time, networked access control without the need for extensive door-to-panel wiring. Corporate offices and multi-family residential buildings are the primary adopters, using them to secure interior doors and common areas. This trend is miniaturizing the physical footprint of access control, embedding intelligence directly into the door assembly and simplifying installation.
Directives from bodies like the US Cybersecurity and Infrastructure Security Agency (CISA) are mandating stricter physical security for critical national infrastructure. These requirements compel operators in sectors such as energy and finance to upgrade from isolated systems to auditable, centrally managed solutions. The data center segment is most affected, now treating physical access logs with the same rigor as logical access data.
Enterprise buyers are moving away from large, one-time capital investments in hardware toward subscription-based service models. This disrupts the traditional business of security integrators who relied on hardware sales, favoring providers offering bundled software, support, and hardware as a recurring fee. This OpEx preference is most prominent among technology companies and co-working spaces in North America and Europe.
Access Control As a Service Market Segmentation
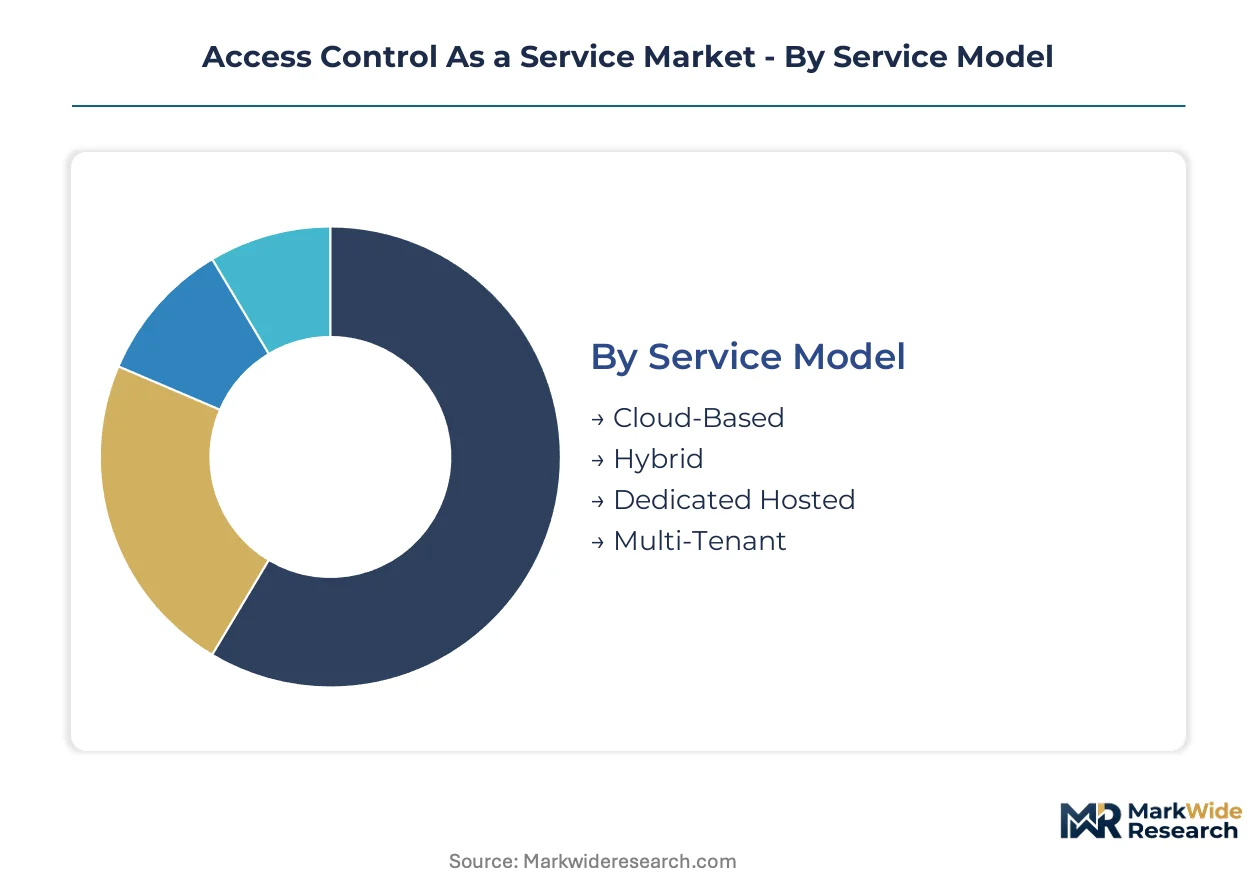
Understanding the varied segments within the Access Control as a Service market is crucial for identifying distinct customer requirements and operational preferences. This segmentation highlights how different delivery models, authentication methods, deployment settings, and customer types shape demand for physical security solutions.
Service Model:
The Access Control as a Service market delivers physical security solutions through varied deployment channels, each offering distinct operational and management profiles.
- Cloud-Based:This model involves a third-party provider hosting and managing the entire ACaaS software and infrastructure in the cloud, offering remote access and scalability for data centers and corporate offices. Demand concentrates here due to reduced on-premise IT burden and seamless updates.
- Hybrid:Combining on-premise hardware with cloud-based software management, this model allows organizations to maintain control over sensitive data locally while leveraging cloud benefits for scalability and remote administration. This approach addresses data sovereignty concerns, particularly in European government facilities.
- Dedicated Hosted:A single-tenant cloud environment where the ACaaS solution is hosted on a dedicated server for one client, providing enhanced security and customization.
- Multi-Tenant:Multiple clients share a single cloud infrastructure, where resources are partitioned virtually, offering cost efficiency and rapid deployment for small to medium-sized enterprises.
Cloud-Based solutions dominate the installed base. Hybrid models are where expansion concentrates.
Authentication Technology:
Authentication technologies within ACaaS span a spectrum of maturity, impacting both user experience and security assurance levels for various access points.
- Mobile Credentials:This technology uses smartphones or wearable devices for access authentication, leveraging Bluetooth or NFC to replace traditional cards. Adoption velocity is highest in corporate campuses, driven by user convenience and reduced credential management costs.
- Biometric Recognition:Utilizing unique physical characteristics like fingerprints, facial scans, or iris patterns for identity verification, this method offers high security and auditability. Strict regulatory mandates in data centers and government facilities drive its implementation.
- RFID:Radio-Frequency Identification cards or fobs communicate wirelessly with readers, providing a widely adopted and cost-effective access solution for commercial buildings.
- Smart Cards:Encrypted cards with embedded microchips store credential data, offering enhanced security over traditional proximity cards for corporate environments.
- PIN Code:Personal Identification Numbers entered on keypads provide a basic, cost-effective authentication method, often used as a secondary factor or for low-security areas.
Mobile Credentials are gaining share fastest. Traditional Smart Cards still hold significant market presence.
Deployment Environment:
ACaaS platforms find application across diverse environments, each presenting unique security challenges and operational demands for physical access control.
- Data Centers:These facilities require stringent physical access controls for sensitive IT infrastructure, necessitating scalable and auditable ACaaS platforms that integrate with logical security systems. Proliferation of hyper-scale data centers in the United States creates sustained demand.
- Corporate Campuses:Large office complexes utilize ACaaS for managing employee and visitor access across multiple buildings, often integrating with HR systems for streamlined provisioning. User experience design and open API platforms drive adoption here.
- Educational Institutes:Universities and schools deploy ACaaS for securing dormitories, classrooms, and administrative buildings, managing diverse user groups including students, staff, and visitors.
- Government Facilities:High-security government sites demand robust, compliant access control systems with comprehensive auditing capabilities, often driven by national security directives.
- Hospitality Establishments:Hotels and resorts use ACaaS for guest room access, staff areas, and common amenities, seeking solutions that enhance guest experience and operational efficiency.
Data Centers represent the largest volume of new installations. Corporate Campuses are driving significant upgrades.
Customer Segment:
The ACaaS market serves distinct customer types, each with specific procurement processes and integration needs for physical security solutions.
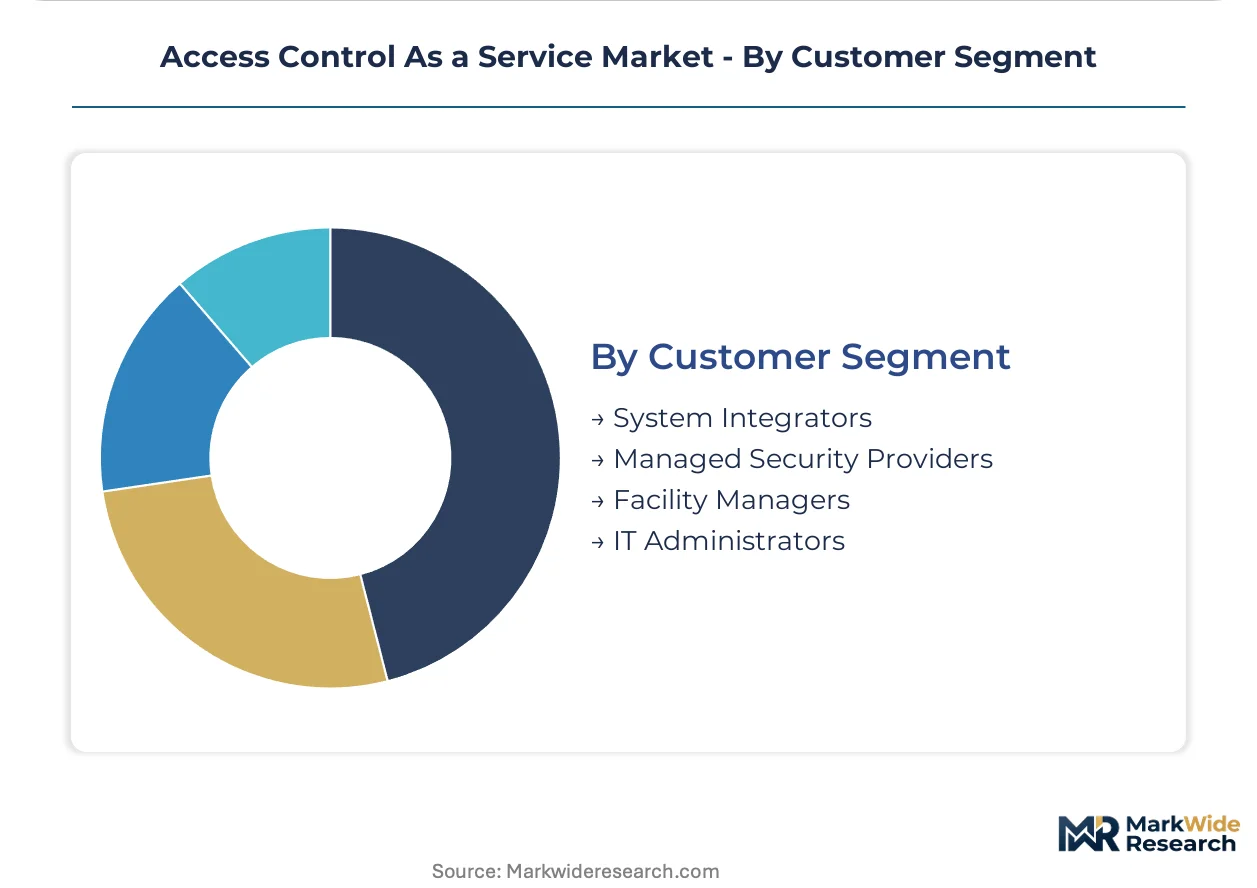
- System Integrators:These entities specialize in designing, installing, and maintaining physical security systems, often bundling ACaaS with other building management services for end-users. Their vast installation networks leverage established client relationships.
- Managed Security Providers:Offering ACaaS as part of a broader security service portfolio, these providers manage and monitor access control systems remotely, delivering recurring revenue streams. They cater to businesses seeking outsourced security operations.
- Facility Managers:Responsible for the day-to-day operations of buildings, facility managers procure ACaaS to enhance physical security, improve operational efficiency, and ensure compliance.
- IT Administrators:Overseeing an organization's IT infrastructure, these professionals are increasingly involved in ACaaS procurement due to the convergence of physical and logical security systems, and data privacy regulations.
System Integrators are central to solution deployment. Managed Security Providers are expanding their service portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Access Control as a Service varies significantly across regions. Highly regulated sectors and critical infrastructure facilities exhibit lower price sensitivity, prioritizing compliance and robust security features. Conversely, small to medium-sized enterprises and older commercial buildings often display higher price elasticity, weighing initial investment against recurring costs.
United States
The United States drives significant ACaaS demand, fueled by its extensive hyper-scale data center expansion and numerous corporate campuses. HIPAA regulations compel healthcare and related facilities to adopt auditable access control solutions. Northern Virginia's data center corridor sees continuous ACaaS deployment for critical infrastructure security.
Germany
Germany's demand for ACaaS stems from its expanding data center footprint and strict data privacy requirements. The EU's GDPR necessitates rigorous physical access controls for facilities handling sensitive information. Frankfurt's financial hub and colocation data centers actively implement hybrid ACaaS models.
United Kingdom
The United Kingdom exhibits strong ACaaS adoption, driven by corporate office upgrades and the financial sector's security needs. UK GDPR mandates influence procurement decisions, requiring comprehensive access logging and auditing capabilities. London's financial district and tech hubs frequently upgrade to mobile credentialing systems.
India
India represents a significant greenfield opportunity for ACaaS, propelled by rapid commercial real estate development and IT/BPO sector growth. The upcoming Digital Personal Data Protection Act (DPDPA) will likely increase demand for auditable physical security systems. Bengaluru's IT parks and new commercial developments actively deploy cloud-based access control solutions.
Brazil
Brazil's ACaaS market expands with industrial development and the modernization of commercial infrastructure. The Lei Geral de Proteção de Dados (LGPD) drives demand for compliant, auditable access control systems in various sectors. São Paulo's business districts and industrial zones are adopting advanced physical security platforms.
Access Control As a Service Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the Access Control as a Service market. The market structure involves established security hardware manufacturers alongside agile cloud-native providers, creating a dynamic competitive landscape. Strategic archetypes include traditional building management conglomerates, pure-play ACaaS specialists, and IT-centric security firms. Dominant competitive moves involve strategic partnerships for ecosystem expansion and continuous software development for enhanced user experience and platform capabilities.
Among established players, Johnson Controls exemplifies a diversified approach, leveraging its vast installation networks to bundle ACaaS with broader building management services. This strategy represents a significant segment of the market, where physical security integrates with wider building automation. Conversely, specialists such as Brivo Inc. and Kisi Inc. sit within the cloud-native provider segment. These companies differentiate through open API platforms and user experience design, anchoring innovation in frictionless authentication and seamless integration capabilities. Their focus often centers on rapid deployment and scalability for modern corporate environments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Brivo Inc. |
| Johnson Controls |
| Honeywell International Inc. |
| Assa Abloy |
| Thales |
| Kisi Inc. |
| Cloudastructure Inc. |
| Kastle Systems |
Cost & Logistics Intelligence
Operational efficiencies from cloud infrastructure capacity utilization shape supply concentration and influence price floors for Access Control as a Service. This dynamic favors providers with extensive cloud footprints and established service delivery networks, enabling them to offer competitive subscription models.
Pricing Analysis
Subscription-based service models generate recurring revenue, driving lifetime value for ACaaS providers. Price differentiation stems from enhanced user experience features and open API platforms, allowing seamless integration with other enterprise systems. Pricing pressure emerges from the commoditization of IP-based controllers, making basic ACaaS offerings more accessible. Highly regulated sectors like data centers exhibit lower price sensitivity, prioritizing compliance and robust security features, while small to medium-sized businesses show higher price elasticity.
Supply Chain Analysis
Hardware lead times for specialized components like wireless locksets and biometric readers influence deployment schedules across the ACaaS market. Supply concentration for core ACaaS hardware, such as IP-based controllers and readers, primarily resides in East Asia. Key component dependencies include specialized semiconductors for readers and secure microcontrollers for credentials. A structural risk involves single-source vulnerability for proprietary hardware from certain manufacturers. Distribution runs through a network of system integrators and managed security providers who handle installation and ongoing support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Access Control as a Service market is in an early-cycle expansion phase, propelled by increasing regulatory mandates for auditable physical security and the proliferation of hyper-scale data centers.
For Market Incumbents: Shield existing market share by integrating ACaaS offerings with broader building management systems, leveraging established installation networks. Invest in R&D to develop open API platforms that facilitate integration with diverse enterprise IT ecosystems, countering cloud-native specialists. Control distribution channels through enhanced partner programs, ensuring consistent service delivery and customer retention against emerging threats.
For New Entrants and Emerging Players: Anchor in specific market niches by offering unbundled services like mobile credentialing or visitor management as standalone applications. Target greenfield opportunities in emerging geographies, such as Brazil and India, where commercial real estate development is accelerating. Focus on user experience design and rapid deployment capabilities to attract small to medium-sized businesses seeking cost-effective, cloud-based solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play ACaaS specialists with strong software and API platforms. Long-term viability is strong due to the convergence of physical and logical security and a growing preference for OpEx models. Identify acquisition targets that possess deep expertise in mobile credentialing or have strong regional presence in expanding data center corridors. Integration with HR systems for automated user provisioning signals an inflection point for enterprise adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with IT Systems | Seamlessly connects physical access with logical identity management, meeting enterprise compliance needs. |
| Geographic Expansion into Emerging Markets | Captures greenfield opportunities in rapidly developing commercial and industrial sectors. |
| Development of Open API Ecosystems | Fosters third-party innovation and broadens integration possibilities for ACaaS platforms. |
| Acquisition of Mobile Credentialing Specialists | Strengthens offerings in high-adoption authentication technologies for corporate campuses. |
| Bundling with Building Management Services | Leverages existing infrastructure and client relationships for comprehensive facility solutions. |
Research Approach
A standing panel of facility managers, IT administrators, system integrators, and managed security providers provided ongoing calibration for market dynamics. This primary research was rigorously validated against secondary data from SEC filings, regulatory body publications like CISA directives, and industry association reports. A multi-pronged approach ensured both bottom-up and top-down triangulation of market figures.
The analytical framework ensured consistency by validating outputs against external benchmarks across the analysis window. Segmentation dimensions modeled included service model, authentication technology, deployment environment, customer segment, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market drivers, with data center expansion rates and regulatory compliance spend serving as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of a stable regulatory environment and consistent technology adoption rates; material deviation would warrant model refresh. Forecasts reflect these base assumptions regarding market evolution and competitive intensity. Revision becomes warranted when significant shifts in data privacy legislation or cybersecurity threats cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
France Access Control Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Car Security System Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Border Security System Market
Access Control Systems
Residential Smart Lock Market