
 Europe Cylinder Lock Market | 2026-2036
Europe Cylinder Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cylinder Lock Market Foresight
A shortage of precision machinists trained in brass-forging techniques is unwinding production capacity across Central European lock foundries. ASSA ABLOY AB leverages its Nordic manufacturing footprint to sustain volume output for institutional buyers. DOM Security SAS anchors its position through deep specialization in high-security master key systems for French government facilities. iLOQ Oy differentiates by eliminating battery dependency in electronic cylinders, a feature that resonates with sustainability-focused Scandinavian procurement.
Europe cylinder locks are mechanical or electromechanical fastening devices installed within door hardware to control access through rotating plug-and-housing assemblies, typically manufactured from brass bar stock with nickel-plated surfaces and tolerances measured in hundredths of a millimeter. Their primary purpose is to secure entry points across buildings and vehicles while enabling key-based or credential-based rekeying flexibility. Single cylinder configurations still dominate residential replacement cycles, though keyless segments are capturing margin pools in commercial new-build specifications. Stainless steel material grades are gaining specification share in coastal Nordic markets where salt corrosion degrades standard brass alloys faster.
CE marking under the EU Construction Products Regulation and ECHA REACH compliance for nickel and lead content in metal alloys jointly determine which products access continental distribution channels. Germany's KBA and France's ANSM-equivalent building security certifiers enforce divergent testing protocols that fragment pan-European product homologation. Stakeholders must monitor whether the EU AI Act extends conformity obligations to biometric-enabled smart cylinders before committing R&D budgets.
Market Dynamics
The EU's Cybersecurity Act is forcing a recalibration of certification pathways for electronic locking components, compressing product development timelines while elevating compliance costs for manufacturers serving pan-European distribution.
Growth Catalysts
- CE marking under the Construction Products Regulation:Harmonized access protocols enable manufacturers to scale across Germany, France, and Nordic markets without redundant national testing regimes.
- Scandinavian residential retrofit programs:Municipal building efficiency mandates in Sweden and Norway are accelerating replacement cycles for outdated mechanical cylinders with connected access systems.
- Brass-nickel surface treatment advances:Improved electroplating tolerances measured in hundredths of a millimeter are extending product lifespans in high-cycle institutional environments.
Market Restraints
- Precision machinist shortage:Central European foundries face unwinding production capacity as skilled brass-forging labor retires without sufficient apprenticeship pipeline replacement.
- Divergent national testing protocols:Germany's KBA and French building security certifiers enforce non-aligned validation requirements that fragment product homologation and inflate R&D duplication.
- Salt corrosion in coastal Nordic zones:Standard brass alloys degrade faster than stainless steel alternatives, forcing material specification upgrades that compress margin pools on replacement contracts.
Strategic Opportunities
- Battery-independent electronic cylinders:Energy-harvesting credential readers eliminate maintenance cycles in remote Scandinavian facilities where technician dispatch costs exceed hardware value.
- Master key system specialization:French government facility security upgrades create procurement windows for vendors with deep credential hierarchy engineering capabilities.
- ECHA REACH compliance services:Nickel and lead content verification consulting represents adjacent revenue streams as alloy composition rules tighten for continental distribution access.
Industry Challenges
- EU AI Act conformity uncertainty:Stakeholders face frozen R&D commitments until biometric-enabled smart cylinder classification clarifies under pending artificial intelligence liability frameworks.
- Legacy mechanical-electronic integration:Hybrid retrofit installations demand field technicians trained in both hundredths-of-a-millimeter mechanical tolerance and firmware credential provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cylinder Lock Market |
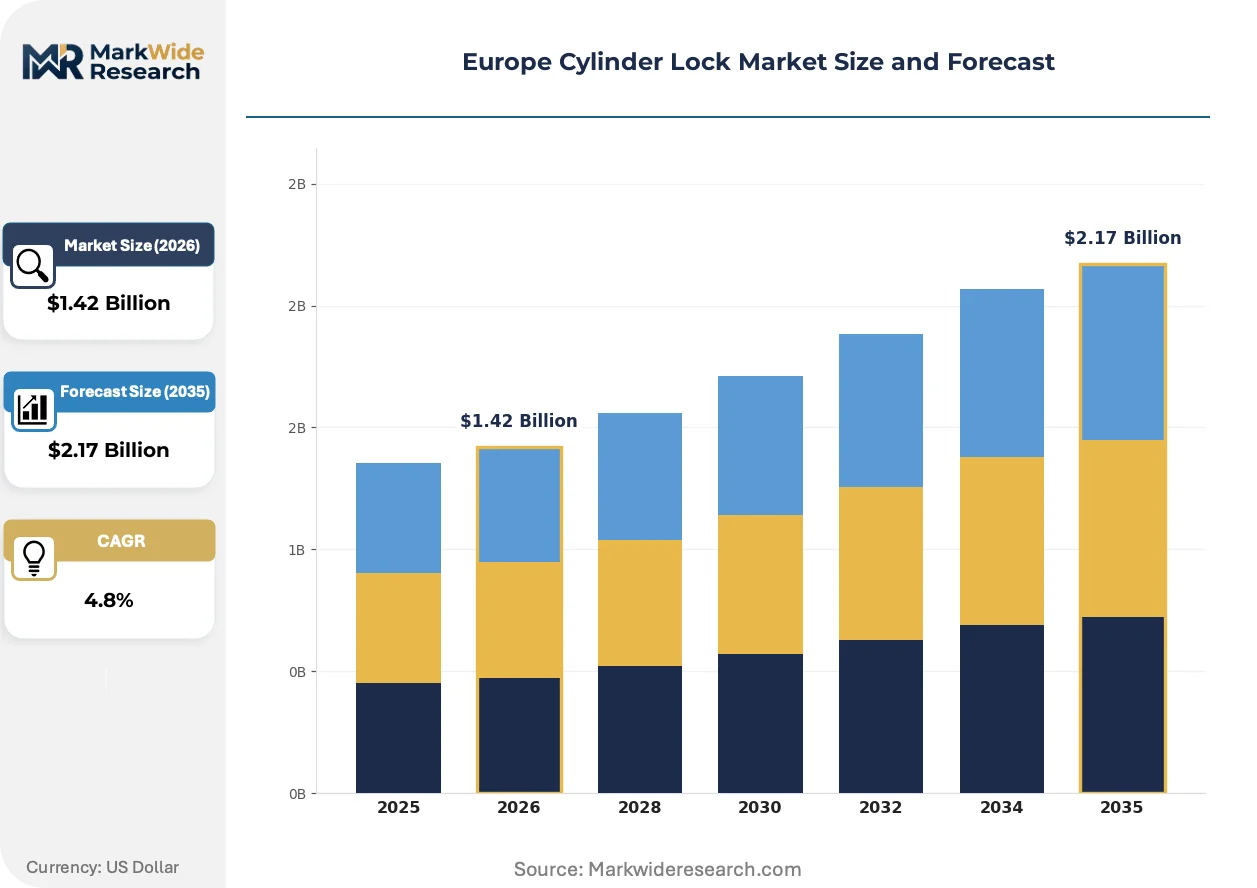
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cylinder, Double Cylinder, Keyless, Interconnected Material: Brass, Stainless Steel, Zinc Alloy, Plastic Application: Residential, Commercial, Industrial, Automotive Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets |
| Companies Covered | EVVA Sicherheitstechnologie GmbH, Winkhaus Deutschland GmbH & Co. KG, ASSA ABLOY AB, ISEO Serrature S.p.A., DOM Security SAS, Allegion plc, ABUS August Bremicker Söhne KG, iLOQ Oy, Dormakaba Holding AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cylinder Lock Market Shifts & Advancements
Electronic credential modules are compressing the physical footprint of access control hardware while sustainability mandates and procurement centralization reshape how institutional buyers evaluate total cost of ownership across replacement cycles.
Energy-harvesting piezoelectric generators embedded in cylinder housings is miniaturizing power infrastructure requirements for electronic locks. German industrial cluster facilities are specifying these units for high-traffic doors where battery replacement logistics consume 40% of maintenance budgets. The technology is compressing lifecycle cost calculations and displacing wired power alternatives in retrofit specifications.
ECHA REACH substance restrictions on nickel and lead content in metal alloys are tightening material sourcing requirements for brass bar stock suppliers. Manufacturers must now maintain dual alloy certification streams to serve continental versus export markets. French and German industrial buyers are prioritizing pre-certified component suppliers to compress their own product registration timelines.
Centralized procurement consortia among Nordic municipal housing authorities are consolidating specification power into fewer decision nodes. Traditional locksmith distribution channels face disintermediation as direct manufacturer relationships secure multi-year framework agreements. Sweden's Stockholm and Norway's Oslo metropolitan retrofit programs exemplify this concentration, with technical compliance teams now embedded within buyer organizations rather than intermediary distributors.
Europe Cylinder Lock Market Segmentation
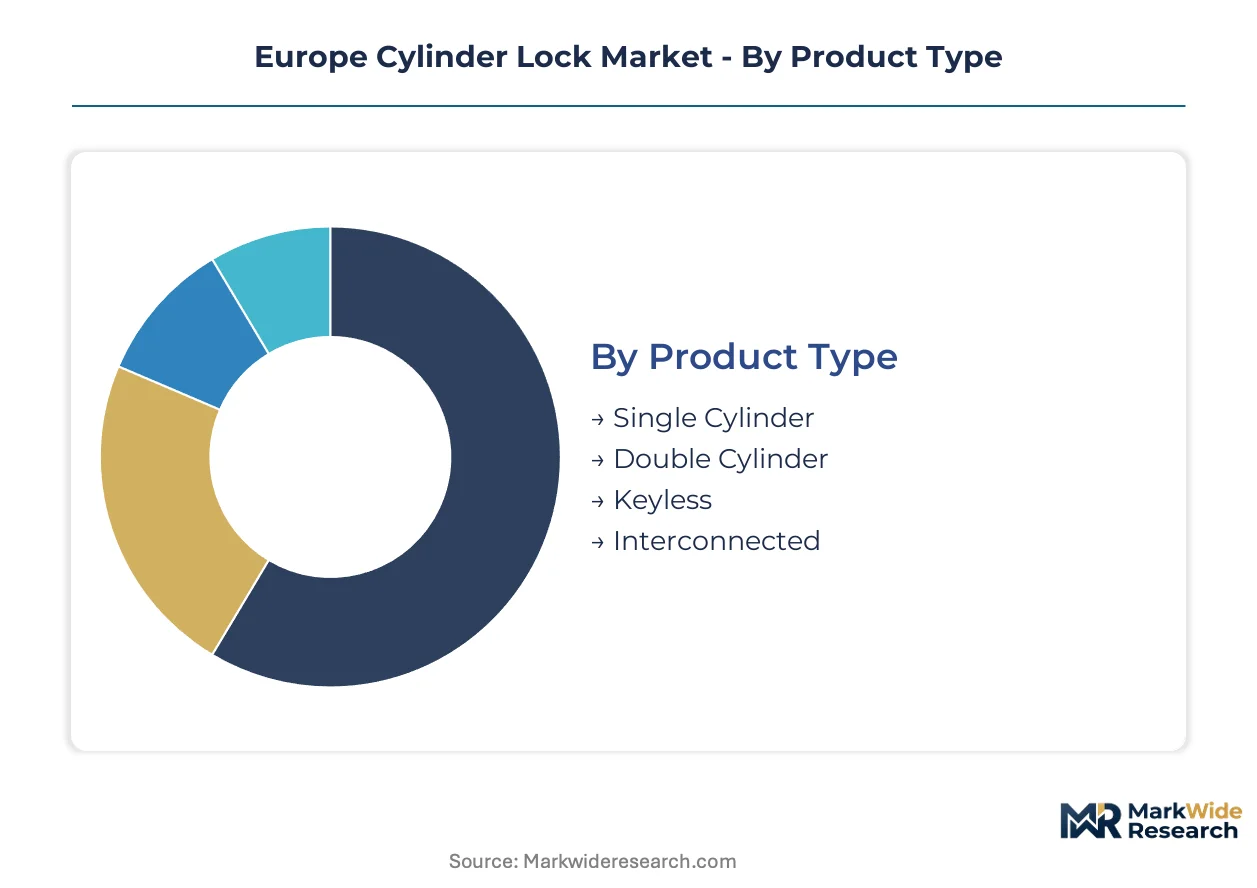
Cylinder lock procurement patterns diverge sharply across European national markets, with specification requirements in Germany, France, and Nordic clusters driving distinct product-mix priorities. Understanding segment-level demand concentration enables manufacturers to align alloy certification streams and credential technology investments with buyer procurement calendars.
Product Type:
Domestic replacement cycles in Germany and France sustain volume demand for mechanical configurations, while Nordic export channels absorb disproportionate shares of electronic variants for institutional retrofit programs.
- Single Cylinder:Brass-housing assemblies with rotating plug mechanisms dominate residential replacement cycles across German and French markets. Specification concentration sits with homeowner insurance-mandated security upgrades in suburban Paris and Munich metropolitan zones.
- Keyless:Electronic credential modules eliminate physical key management in Swedish municipal housing authority frameworks. Battery-independent harvesting technology from Finnish suppliers is capturing specification share in remote Norwegian facilities where technician dispatch costs exceed hardware value.
- Double Cylinder:Dual-access configurations serve commercial entry points requiring keyed operation from both sides.
- Interconnected:Handle-and-lock integrated units simplify installation for French commercial new-build specifications.
Single cylinder configurations hold the largest share; momentum sits with keyless electronic variants.
Material:
Cost tiers separate premium stainless specifications from standard brass offerings, with coastal corrosion resistance commanding 40% material cost premiums in Nordic procurement frameworks.
- Brass:Nickel-plated bar stock with hundredths-of-a-millimeter tolerances remains the baseline for continental distribution under ECHA REACH compliance. German industrial cluster buyers prioritize pre-certified brass suppliers to compress registration timelines.
- Stainless Steel:Marine-grade alloys withstand salt corrosion in Stockholm and Oslo coastal retrofit programs. Specification penetration climbs fastest where building insurance mandates 15-year replacement cycles.
- Zinc Alloy:Lower-cost die-cast alternatives serve price-sensitive French residential distribution channels.
- Plastic:Polymer housings address temporary access and low-security utility applications.
Brass dominates volume; stainless steel is climbing the fastest on coastal specification upgrades.
Application:
Customer type determines credential complexity, with government facility security upgrades in France requiring master key hierarchy engineering unavailable in standard residential offerings.
- Commercial:Smart access installations expand across German and French commercial real estate developments. CE marking harmonization enables pan-European scaling without redundant national testing regimes.
- Residential:Single-cylinder replacement cycles concentrate in Swedish and Norwegian municipal retrofit mandates. Building efficiency regulations accelerate connected access system adoption.
- Industrial:High-cycle institutional environments in German manufacturing clusters demand extended lifespan surface treatments.
- Automotive:Aftermarket ignition and door lock cylinders serve vehicle parc maintenance.
Commercial applications command premium pricing; residential retrofits are expanding most quickly on Nordic municipal procurement consolidation.
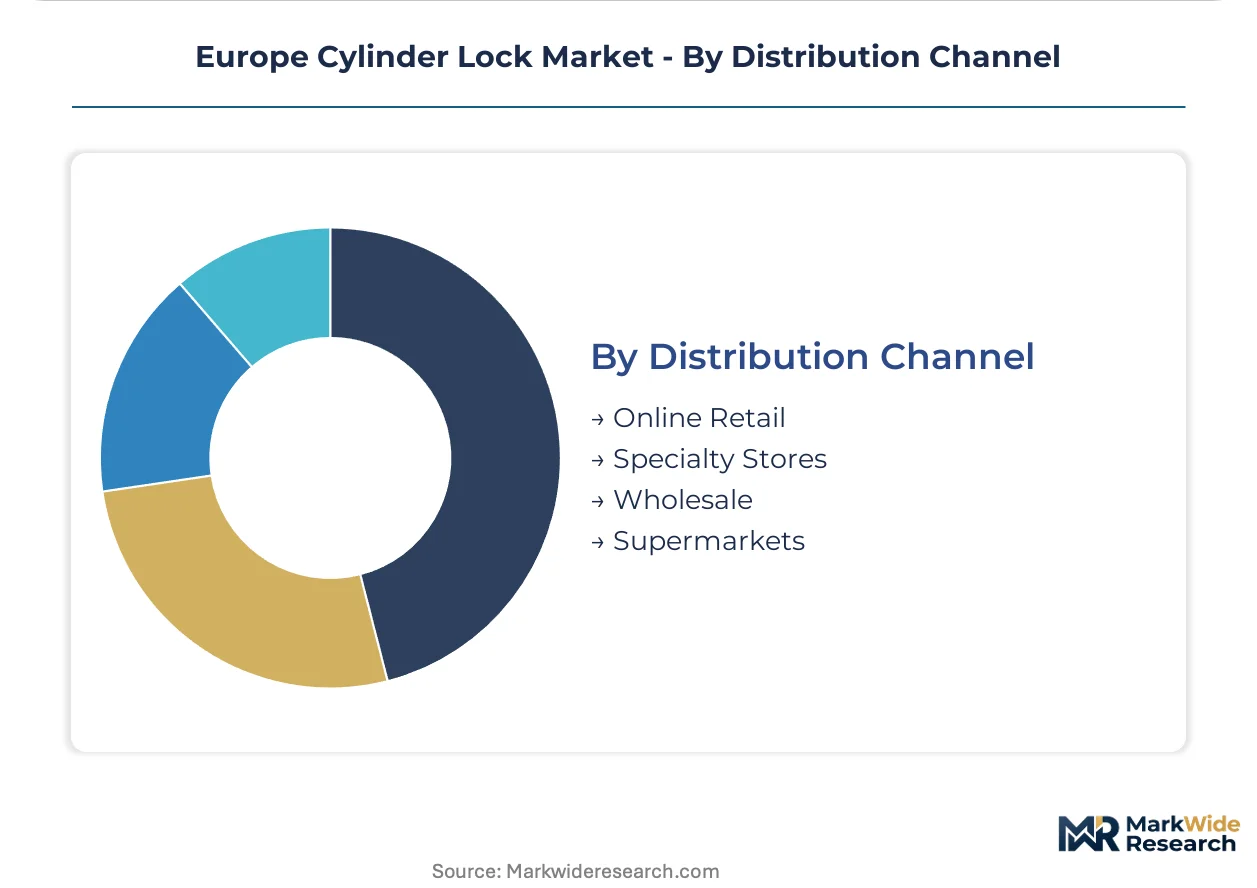
Distribution Channel:
Supply concentration is shifting from fragmented locksmith networks toward direct manufacturer relationships with centralized Nordic housing authority procurement consortia.
- Specialty Stores:Traditional locksmith channels retain specification influence in French government facility security upgrades. Technical compliance teams embedded within buyer organizations are displacing intermediary technical advisory roles.
- Wholesale:Bulk procurement frameworks dominate German industrial cluster supply agreements. Volume commitments secure alloy certification documentation required for CE marking compliance.
- Online Retail:Direct-to-installer platforms capture standard residential replacement demand.
- Supermarkets:Mass-market retail serves emergency replacement and basic security needs.
Wholesale channels hold the largest share; momentum sits with specialty stores on high-security master key system complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA anchors certification requirements for the dominant geography, with national testing protocols fragmenting product homologation across continental distribution channels. Divergent building security standards between Paris and Berlin procurement offices compress margin pools on pan-European scaling efforts.
Germany
Industrial cluster facilities in Bavaria and North Rhine-Westphalia specify high-cycle brass-nickel surface treatments for institutional door hardware. KBA testing protocols enforce hundredths-of-a-millimeter tolerance validation that delays product registration timelines. Munich metropolitan developers are expanding smart access installations across commercial real estate portfolios.
France
ANSM-equivalent building security certifiers mandate divergent validation requirements from German counterparts, forcing redundant R&D expenditure. Government facility security upgrades in suburban Paris create procurement windows for master key system specialists. Île-de-France commercial new-build specifications favor interconnected handle-and-lock integrated units.
Sweden
Stockholm municipal housing authorities consolidate specification power through centralized procurement consortia that disintermediate traditional locksmith channels. Building efficiency regulations accelerate connected access system adoption in residential retrofit programs. Coastal corrosion resistance commands 40% material cost premiums for marine-grade stainless specifications.
Norway
Oslo metropolitan retrofit programs exemplify procurement concentration with technical compliance teams embedded within buyer organizations. Battery-independent energy-harvesting cylinders capture specification share in remote facilities where technician dispatch costs exceed hardware value. Salt degradation of standard brass alloys forces specification upgrades in coastal zones.
Italy
ISEO Serrature S.p.A. anchors domestic manufacturing capacity for precision brass-forging output serving institutional buyers. CE marking harmonization enables Italian suppliers to scale across adjacent continental markets without redundant national testing. Northern industrial clusters sustain volume production for export channels into German and French distribution networks.
Europe Cylinder Lock Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the vendor base organizing around capability depth rather than scale alone. The structure rewards backward integration into brass bar stock sourcing and captive electroplating capacity. Three archetypes dominate: Nordic sustainability-focused electronics specialists, Alpine precision-forging houses, and pan-European full-line access control conglomerates. Competitive moves concentrate on M&A to secure master key engineering talent and strategic partnerships to bypass divergent national certification bottlenecks.
Among Nordic-based fabricators, ASSA ABLOY AB and iLOQ Oy exemplify divergent positioning strategies within the electronic cylinder segment. ASSA ABLOY AB occupies a position as a scale-driven conglomerate with manufacturing footprint leverage across institutional procurement frameworks. iLOQ Oy represents the sustainability-specialist archetype through battery-elimination technology that resonates with Scandinavian municipal procurement mandates. DOM Security SAS anchors the French specialist tier with deep credential hierarchy engineering capabilities for government facility security upgrades. These three companies illustrate how geographic origin and technical specialization combine to determine competitive positioning within fragmented national certification environments.
| Leading Market Players |
|---|
| EVVA Sicherheitstechnologie GmbH |
| Winkhaus Deutschland GmbH & Co. KG |
| ASSA ABLOY AB |
| ISEO Serrature S.p.A. |
| DOM Security SAS |
| Allegion plc |
| ABUS August Bremicker Söhne KG |
| iLOQ Oy |
| Dormakaba Holding AG |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day brass bar stock lead times concentrate pricing power with German and Italian foundries that maintain captive electroplating capacity, while Nordic buyers absorb forty-percent material cost premiums for marine-grade stainless specifications in coastal retrofit programs.
Pricing Analysis
German industrial cluster buyers pay fifteen-to-twenty-percent premiums over French residential distributors for identical brass-nickel specifications due to KBA tolerance validation requirements and embedded compliance documentation costs. Three-tier pricing structure across premium certified, standard CE-marked, and economy zinc-alloy levels separates institutional procurement frameworks from mass-market replacement channels. Cost compression in standard brass configurations is intensifying as Central European foundries unwind production capacity amid precision machinist shortages. Municipal housing authorities in Sweden and Norway exhibit lowest price sensitivity due to centralized procurement consolidation and fifteen-year replacement cycle mandates.
Supply Chain Analysis
Strategic stockpiling of nickel-plated bar stock dominates German and Italian foundry procurement to buffer against ECHA REACH certification delays, while just-in-time component flows characterize French commercial new-build supply chains. Manufacturing gravity centers on Germany, Italy, and Finland for precision-forging output and Nordic electronics assembly. Brass bar stock, nickel electroplating chemicals, and piezoelectric energy-harvesting modules constitute critical input dependencies. Single-source vulnerability concentrates in Finnish battery-independent credential technology suppliers serving remote Norwegian facilities. Distribution runs through wholesale bulk frameworks for German industrial clusters and disintermediated direct manufacturer relationships with Stockholm and Oslo municipal procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Nordic municipal housing authority procurement consolidation and centralized framework agreements that disintermediate traditional locksmith distribution channels.
For Market Incumbents: Fortify backward integration into captive brass bar stock sourcing and electroplating capacity to defend margin position against ECHA REACH compliance cost inflation and precision machinist shortages unwinding Central European foundry output. Deepen certification engineering teams to navigate divergent KBA and French building security validator protocols without redundant R&D expenditure.
For New Entrants and Emerging Players: Lead with battery-independent energy-harvesting credential modules for remote Scandinavian facilities where technician dispatch costs exceed hardware value, penetrating the municipal retrofit segment where centralized procurement consortia seek maintenance-elimination specifications. Target French government facility security upgrades through master key hierarchy engineering partnerships with embedded technical compliance teams.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because divergent national certification protocols and pending EU AI Act biometric-enabled smart cylinder classification create durable moats for specialists with compliance infrastructure already deployed. Acquisition targets should display captive precision-forging capacity and pre-certified alloy documentation streams. The signal to watch is clarification of EU AI Act conformity obligations for biometric-enabled smart cylinders, which would unlock frozen R&D commitments across the vendor base.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Bar Stock Sourcing | Captive supply of ECHA REACH pre-certified alloys compresses registration timelines for German industrial cluster buyers. |
| Master Key Hierarchy Engineering Acquisition | French government facility security upgrades demand credential complexity unavailable from standard residential suppliers. |
| Battery-Independent Technology Partnership | Finnish energy-harvesting modules eliminate maintenance cycles in remote Norwegian facilities where dispatch costs dominate. |
| CE Marking Harmonization Investment | Unified compliance documentation enables pan-European scaling without redundant KBA and French validator testing. |
| Direct Procurement Consortium Relationship | Stockholm and Oslo municipal housing authorities consolidate specification power through disintermediated manufacturer frameworks. |
Research Methodology
Initial hypotheses were tested against primary input from precision-forging plant managers, institutional procurement officers at German industrial clusters, French government facility security directors, Nordic municipal housing authority technical compliance teams, and traditional locksmith distribution channel owners, then refined against secondary validation from EU Construction Products Regulation documentation, ECHA REACH substance restriction filings, KBA testing protocol publications, French building security certification registers, and customs trade data for brass bar stock flows across the analysis window. Bottom-up volume triangulation from national replacement cycle data and top-down value estimation from procurement framework disclosures were cross-referenced for convergence.
Variance decomposition across product type, material grade, application sector, and national regulatory cluster drove segmentation-level modeling throughout the projection horizon. CAGRs were derived from fitted growth curves anchored to observable replacement cycle acceleration in Nordic municipal retrofit programs and smart access penetration in German commercial real estate developments. Industry-specific forecast inputs included precision machinist retirement rates affecting Central European foundry capacity and ECHA REACH substance restriction implementation timelines affecting alloy certification streams.
The analysis sits within stated boundaries; outcomes outside sustained Nordic municipal procurement consolidation or clarified EU AI Act biometric-enabled smart cylinder classification would require recalibration. Forecasts reflect documented assumptions regarding CE marking harmonization progress and precision-forging labor pipeline development. Revision becomes warranted when divergent national testing protocol fragmentation exceeds current KBA-French validator misalignment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Canada Access Control Market