
 Car Security System Market | 2026-2036
Car Security System Market Size, Share, and Industry Trends Forecast 2026-2036
Car Security System Market Intelligence
The upgrade to multi-factor authentication systems, incorporating biometrics and smartphone integration, is rotating the market away from standalone alarms. This shift emphasizes software and connectivity over simple hardware deterrents. Continental AG leverages its deep electronics expertise to provide integrated security suites for OEMs. Robert Bosch GmbH specializes in combining advanced sensor technology with software analytics for sophisticated threat detection and response.
A car security system is an ecosystem of electronic devices designed to prevent theft, unauthorized entry, and damage to a vehicle. These systems function using technologies like RFID for keyless authentication or ultrasonic sensors to detect interior cabin breaches. While Immobilizer systems are a mature, standard-fit component in the OEM channel, GPS Tracking Systems are expanding rapidly, especially for fleet management applications. Biometric Recognition technology is also establishing a foothold within the premium personal vehicles segment.
Regulatory frameworks such as the EU's UNECE regulations on vehicle anti-theft devices and standards from the US NHTSA mandate minimum security features. These rules ensure a baseline level of protection in new vehicles sold in these key markets. The critical decision for automakers is whether to develop proprietary security platforms in-house or partner with specialized technology firms to counter evolving cybersecurity threats.
Market Dynamics
The central force shaping the car security system market is the transition of vehicles into software-defined platforms. This shift elevates cybersecurity from a niche concern to a core design requirement, as connectivity exposes vehicles to remote threats.
Growth Catalysts
- Regulatory Mandates:The EU's UNECE regulations on vehicle cybersecurity (WP.29) are creating a global benchmark, compelling automakers to integrate certified security management systems and advanced threat detection technologies into new vehicle architectures.
- Biometric Integration:Fleet management operators are rapidly adopting biometric recognition for driver authentication. This technology enhances security, prevents unauthorized vehicle use, and provides reliable data for operational management and insurance purposes.
- Demand in China:China’s vast automotive production scale and its focus on New Energy Vehicles (NEVs) create a concentrated demand source. These electronically complex vehicles require sophisticated security suites, driving adoption of advanced systems.
Market Restraints
- Cost Pressures in Volume Segments:The high initial cost of integrating multi-factor authentication systems, including biometrics and advanced sensors, acts as a significant barrier for adoption in high-volume, price-sensitive economy and mid-range vehicle models.
- Legacy System Integration:Ensuring backward compatibility and seamless integration of new software-based security solutions with older, established vehicle electronic control unit (ECU) architectures presents a major technical and financial hurdle for OEMs.
- Aftermarket App Competition:The proliferation of third-party smartphone applications offering vehicle tracking and remote control functions creates a fragmented user experience and presents a substitution threat to OEM-embedded security packages, particularly in the used car market.
Strategic Opportunities
- V2X Cybersecurity:Securing vehicle-to-everything (V2X) communication channels represents a significant opportunity. Developing solutions to protect data exchanged between vehicles, infrastructure, and pedestrians can create new revenue streams for security specialists.
- In-Cabin Monitoring Convergence:Combining security functions with driver and occupant monitoring systems offers a path for product differentiation. Using interior sensors for both intrusion detection and driver alertness monitoring adds value for OEMs and consumers.
- Aftermarket in Emerging Economies:The large installed base of older vehicles in markets like Brazil and India presents an opportunity for aftermarket security products. Demand is strong for retrofittable GPS trackers, immobilizers, and basic alarm systems.
Industry Challenges
- Automotive Cybersecurity Talent Gap:A pronounced shortage of professionals with dual expertise in both automotive engineering and advanced cybersecurity protocols constrains the ability of OEMs and suppliers to develop and deploy secure vehicle systems at scale.
- Supplier Ecosystem Harmonization:Integrating security components from a diverse range of suppliers into a single, cohesive, and failsafe platform is a complex challenge. Mismatched software or hardware can create unforeseen vulnerabilities in the vehicle's security architecture.
- Over-the-Air (OTA) Update Standardization:The absence of universal standards for deploying secure OTA software updates creates significant logistical and security challenges. This lack of standardization complicates fleet management and lifetime vehicle security maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Security System Market |
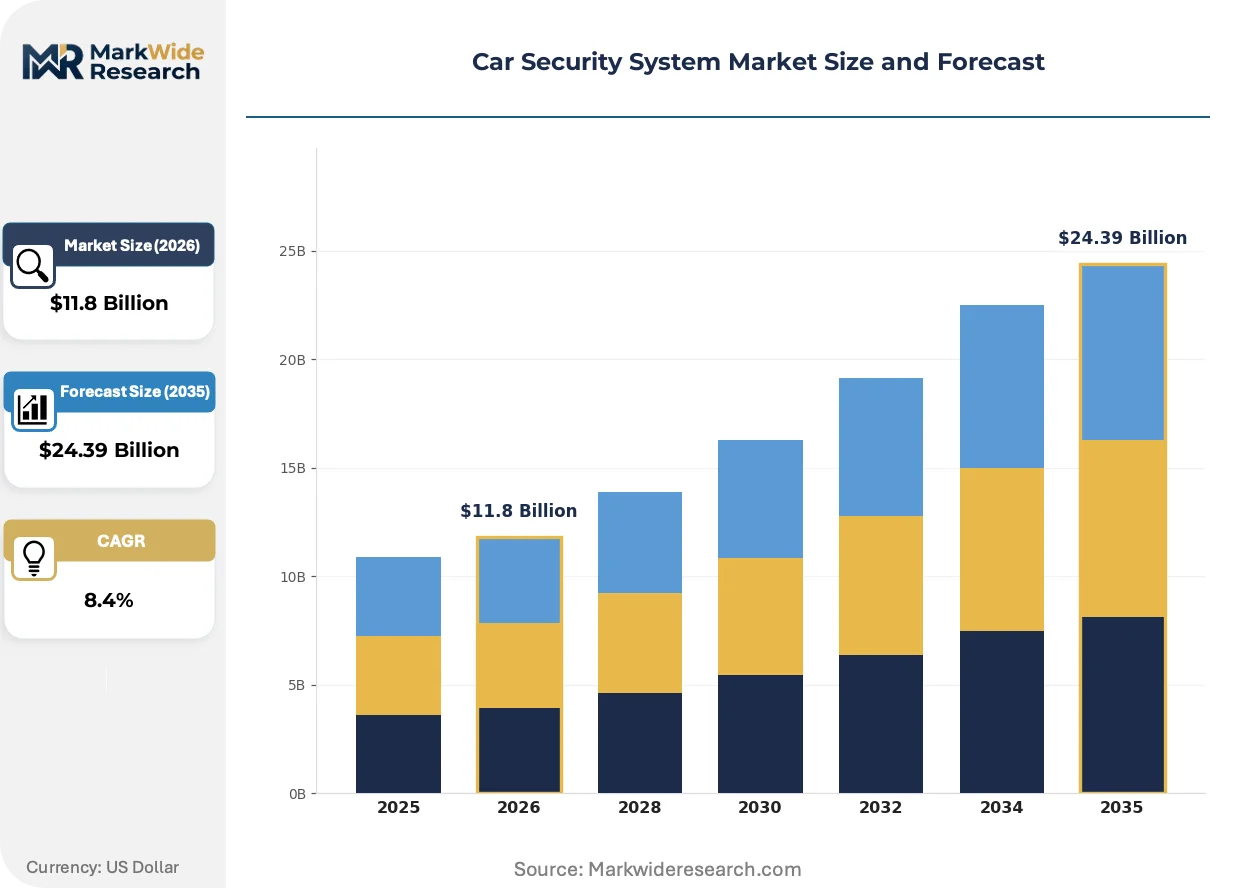
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alarm System, Immobilizer, GPS Tracking System, Keyless Entry System, Dashcam, Remote Start System Technology: RFID, Ultrasonic, Infrared, Bluetooth, Biometric Recognition, Voice Control Application: Fleet Management, Personal Vehicles, Commercial Delivery, Vehicle Leasing, Rental Cars, Taxi Services End User: OEMs, Aftermarket Dealers, Vehicle Assemblers, Auto Repair Shops, Security Installers, Insurance Companies |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, HELLA GmbH & Co. KGaA, Aptiv PLC, Valeo S.A., ZF Friedrichshafen AG, Alps Alpine Co. Ltd, Lear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Security System Market Strategic Shifts & Innovations
Software-defined security is fundamentally altering the market's value proposition. The focus is moving from passive hardware deterrents toward proactive, network-aware threat detection and response systems integrated directly into the vehicle's core electronic architecture and lifecycle management.
Ultrasonic and microwave sensors are providing a more sophisticated method for interior cabin breach detection. These technologies are being adopted primarily within the premium and luxury vehicle segments due to their higher accuracy and lower rate of false alarms. This advanced sensor fusion approach is supplanting traditional passive infrared sensors and simple contact switches, significantly improving the reliability of alarm systems.
Regulatory frameworks, particularly the UNECE's WP.29 regulations on cybersecurity (R155) and software updates (R156), are mandating new design principles. These rules require automakers to implement a certified Cybersecurity Management System (CSMS) covering the entire vehicle lifecycle, from development to post-production. The OEM segment is most affected, compelling partnerships with security firms to ensure compliance for vehicles sold in key markets like Europe and Japan.
Subscription-based models for advanced security features are altering consumer purchasing patterns. This approach unbundles premium services like real-time vehicle tracking, remote immobilization, or accident alerts from the initial vehicle sale, converting them into a recurring revenue stream. This trend is most prominent in the North American and European markets for connected car services offered directly by vehicle manufacturers.
Car Security System Market Segmentation
Understanding the varied segments within the car security system market reveals how different product types and technologies address distinct end-user needs. This granular view helps identify specific demand pockets and the competitive dynamics shaping adoption across diverse applications. Regulatory compliance and evolving vehicle architectures significantly influence segment growth trajectories.
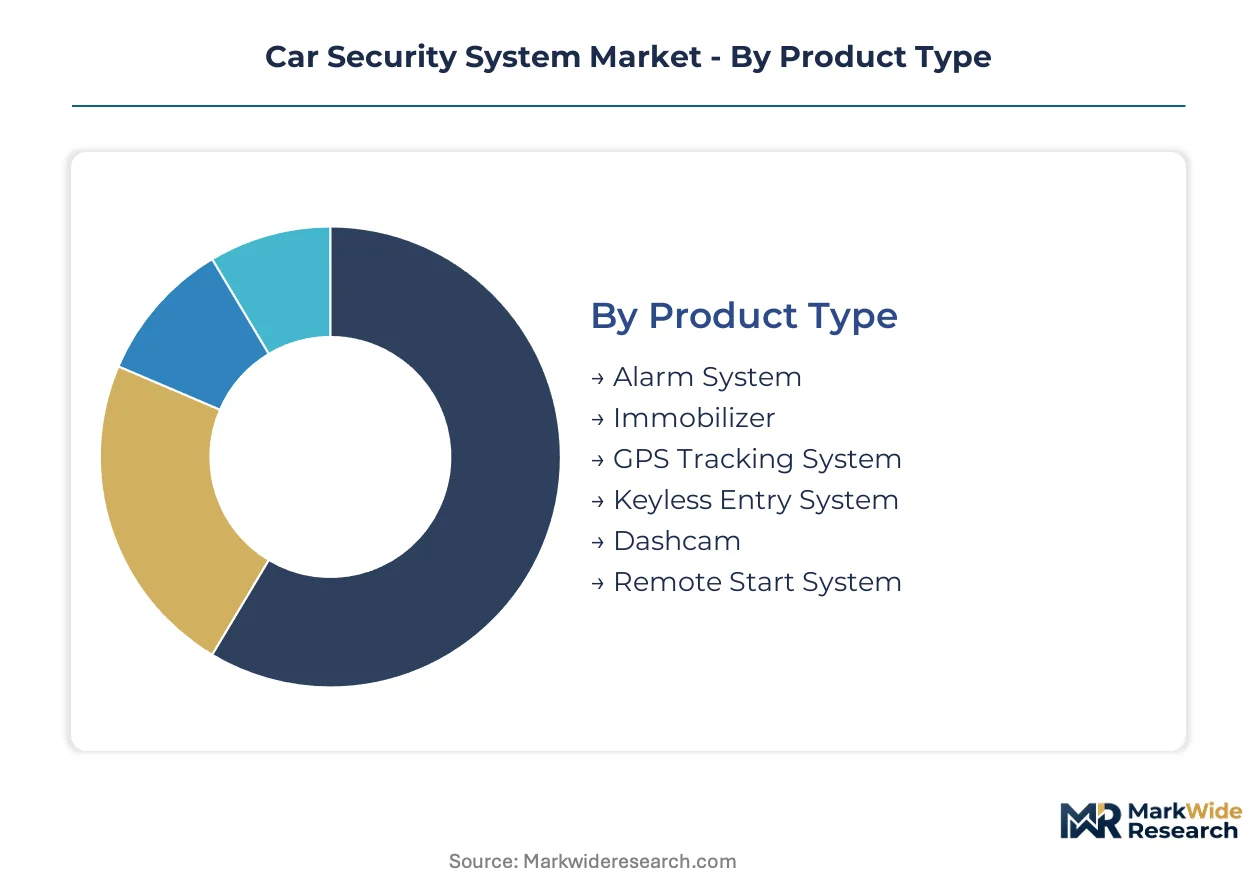
Product Type:
The product type segment faces substitution pressure from integrated software solutions that bundle multiple security functions into a single platform. Standalone hardware components are increasingly being replaced by comprehensive vehicle security suites.
- GPS Tracking System:These systems monitor vehicle location and movement in real-time, often integrating with telematics platforms. Strong demand emerges from fleet management applications in China for operational efficiency.
- Immobilizer:An electronic device preventing engine start without the correct key, a standard anti-theft feature. These mature systems are a baseline security requirement in new vehicles in Europe, mandated by UNECE regulations.
- Alarm System:Traditional systems deter theft through audible and visual signals upon unauthorized entry.
- Keyless Entry System:Allows drivers to unlock vehicles without a physical key, using rolling code technology.
- Dashcam:Onboard cameras record video footage, providing evidence for accidents or vandalism.
- Remote Start System:Enables remote engine starting for convenience, like pre-heating the cabin.
Immobilizer retains volume leadership; GPS Tracking System holds the steepest expansion curve.
Technology:
Technology adoption within car security systems is driven by specific application requirements, balancing advanced threat detection with user convenience. Sophisticated sensors and authentication methods define next-generation vehicle protection.
- Biometric Recognition:Uses unique biological characteristics like fingerprints for secure driver authentication. Gains traction in Chinese fleet management for enhanced security.
- Ultrasonic:Sensors emit high-frequency sound waves to detect interior movement, providing accurate intrusion detection. Premium vehicles in Europe increasingly use this technology.
- RFID:Radio-frequency identification systems enable keyless authentication via wireless communication with a transponder.
- Infrared:Infrared sensors detect heat signature changes, used for basic interior motion detection.
- Bluetooth:Short-range wireless technology facilitating secure smartphone-vehicle communication for remote control.
- Voice Control:Allows operating security features or authentication using spoken commands, enhancing convenience.
Biometric Recognition technology is experiencing rapid adoption, while RFID remains foundational for keyless access.
Application:
This segment delineates distinct demand sources for car security systems, driven by specific operational needs, regulatory compliance, or consumer preferences. Solutions are tailored to address unique risk profiles of various vehicle uses.
- Fleet Management:Deploys security systems across vehicle groups for tracking, monitoring, and driver authentication. North America's sector grows due to biometric integration for efficiency.
- Personal Vehicles:Systems for individual owners focus on theft prevention and convenience. Demand for advanced security suites in premium vehicles is notable across European markets.
- Commercial Delivery:Prioritizes cargo protection, route monitoring, and driver safety, often integrating with telematics.
- Vehicle Leasing:Leasing companies use security systems for asset protection and mileage tracking.
- Rental Cars:Operators use systems for vehicle tracking, geo-fencing, and managing unauthorized usage.
- Taxi Services:Focus on driver safety, panic buttons, incident recording, and vehicle tracking.
Fleet Management demonstrates strong growth potential, while Personal Vehicles continue to represent the largest volume segment.
End User:
The end-user landscape exhibits varying levels of maturity and influence over technology adoption, from direct manufacturing integration to post-sale service. Each end user plays a distinct role in the system's lifecycle.
- OEMs:Integrate security systems directly into new vehicles, often developing proprietary platforms. US NHTSA mandates compel OEMs to include minimum security features.
- Aftermarket Dealers:Provide security system upgrades, retrofits, and specialized solutions post-purchase. Demand for aftermarket GPS trackers is strong in emerging economies like India.
- Vehicle Assemblers:Assemble vehicles from components, relying on OEM-provided or third-party security modules.
- Auto Repair Shops:Handle maintenance, repair, and sometimes installation of security system components.
- Security Installers:Specialized businesses focused on professional installation and customization of advanced car security systems.
- Insurance Companies:Influence adoption by offering reduced premiums for vehicles with certified anti-theft devices.
OEMs remain critical for initial vehicle integration, while Aftermarket Dealers cater to customization and older vehicle needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side dynamics for car security systems are heavily influenced by major automotive manufacturing hubs. These regions drive innovation and adoption of advanced security technologies due to their large production volumes and consumer bases. Regulatory pressures also shape market development across key global economies.
China
China's vast automotive production and New Energy Vehicle (NEV) focus drive substantial demand for sophisticated security suites. The MIIT's push for advanced vehicle technologies compels integration of secure systems. Automotive manufacturing clusters in the Yangtze River Delta actively develop and deploy these complex security solutions.
Germany
Germany's premium vehicle segment demands advanced security systems, integrating sophisticated sensors and software analytics. The EU's UNECE regulations on vehicle cybersecurity compel automakers to implement certified security management systems. Bavaria's automotive R&D centers lead development of integrated security suites for global markets.
United States
The United States sees strong demand for GPS tracking systems in fleet management and subscription-based connected car services. US NHTSA mandates compel OEMs to include minimum security features in new vehicles. Detroit's automotive industry continues to integrate advanced security platforms into vehicle architectures.
Japan
Japan's automotive sector prioritizes advanced security features, driven by ADAS integration and the need for sophisticated threat detection. METI initiatives encourage the development of secure vehicle systems and compliance with international standards. Aichi Prefecture's automotive manufacturing base actively implements these cutting-edge security technologies.
India
India presents a significant opportunity for aftermarket security products, particularly retrofittable GPS trackers and basic alarm systems for its large installed base of older vehicles. The BIS works to establish standards for vehicle safety and anti-theft devices. Chennai's automotive hub sees increasing adoption of these aftermarket solutions.
Car Security System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the car security system market. The competitive landscape exhibits a tiered structure, with established automotive electronics suppliers and specialized software firms vying for market share. Strategic archetypes include integrated suite providers, advanced sensor technology specialists, and aftermarket solution vendors. Companies increasingly pursue strategic partnerships and portfolio diversification to enhance their market presence and address evolving cybersecurity threats.
Among the established automotive electronics suppliers, Germany-based Robert Bosch GmbH exemplifies a company specializing in combining advanced sensor technology with software analytics for sophisticated threat detection and response. Germany-based Continental AG represents another major player, leveraging its deep electronics expertise to provide integrated security suites for OEMs across various vehicle platforms. Japan-based Denso Corporation also occupies a position as a significant provider of advanced vehicle security components and systems, contributing to the baseline security requirements and evolving connectivity needs of new vehicles. These firms collectively anchor the premium and integrated solutions segment, leveraging extensive R&D capabilities for next-generation offerings.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| HELLA GmbH & Co. KGaA |
| Aptiv PLC |
| Valeo S.A. |
| ZF Friedrichshafen AG |
| Alps Alpine Co. Ltd |
| Lear Corporation |
| Others |
Cost & Logistics Intelligence
Subscription-based models for advanced security features lock in both supply access and price visibility for vehicle manufacturers. This structure converts premium services into a recurring revenue stream, influencing component procurement strategies.
Pricing Analysis
The EU's UNECE regulations dictate the pricing tier structure for baseline security features, making immobilizers and basic alarms standard-fit components. Pricing stratifies across premium, standard, and economy tiers, driven by advanced sensor technology and software integration complexity. Pricing softness reflects intense competition in the aftermarket segment for basic GPS trackers. Fleet management operators, seeking operational efficiency, exhibit lower price sensitivity for comprehensive biometric authentication systems.
Supply Chain Analysis
Short lead times for critical electronic components are essential for automotive production schedules. Supply concentration for advanced sensor technologies and microcontrollers centers in countries like China, Germany, and Japan. Raw material dependencies include rare earth elements for advanced sensors and specialized semiconductors for control units. Single-source vulnerability for specific proprietary software modules presents a structural supply chain risk. Distribution runs through a dual channel, with OEMs integrating systems directly and aftermarket dealers providing retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car security system market represents a platform-economics inflection, driven by the increasing interoperability of in-vehicle systems with external networks.
For Market Incumbents:Fortify existing OEM relationships by offering comprehensive, software-defined security suites that comply with UNECE WP.29 regulations. Invest in advanced cybersecurity R&D to counter evolving remote threats, protecting against competitive pressure from specialized software firms. Leverage deep electronics expertise to integrate V2X cybersecurity solutions, securing communication channels for future vehicle architectures.
For New Entrants and Emerging Players:Differentiate on specialized biometric recognition technologies tailored for fleet management applications in China. Target the aftermarket segment in emerging economies like India with cost-effective, retrofittable GPS tracking systems. Focus on developing niche software analytics for in-cabin monitoring convergence, offering enhanced driver and occupant safety features as a unique selling proposition.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among providers offering subscription-based advanced security features for connected car services. Identify acquisition targets with strong intellectual property in automotive cybersecurity or advanced sensor fusion technologies. The signal to watch is the adoption rate of certified Cybersecurity Management Systems across major OEMs, indicating long-term market viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Security Platform Development | Enhances vehicle resilience against evolving cyber threats and enables over-the-air updates. |
| Biometric Authentication Portfolio Expansion | Secures driver access and enhances operational efficiency for fleet management in key markets. |
| V2X Cybersecurity Solution Integration | Protects data exchange between vehicles and infrastructure, creating new revenue streams. |
| Strategic Partnerships with Cybersecurity Firms | Ensures compliance with stringent global regulations like UNECE WP.29 for OEMs. |
| Aftermarket Product Line Diversification | Captures demand from older vehicles and emerging economies for essential security upgrades. |
Research Approach
The analysis maps vehicle security hardware and software sub-sectors, each validated through extensive interviews with OEM procurement leads, Tier 1 component suppliers, and fleet managers. Secondary validation involved reviewing automotive industry reports, regulatory filings from US NHTSA and EU UNECE, and technology whitepapers. The approach integrated bottom-up market sizing with top-down validation.
Outputs were consistently checked against external benchmarks and industry association data across the analysis window. The forecast framework modeled market growth across technology types, product applications, and end-user segments, including an industry-specific dimension for vehicle electrification levels. Compound Annual Growth Rates were derived from historical data and projected market dynamics, with key inputs including regulatory compliance timelines and biometric technology adoption curves.
Material uncertainties — including unforeseen geopolitical shifts or rapid technological obsolescence — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement and market acceptance of new security features. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Port Security Systems Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Network Access Control Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
US Access Control Market