
 Australia Industrial Barrier Systems Market | 2026-2036
Australia Industrial Barrier Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Industrial Barrier Systems Market Insights
Market Context
Australian steel fabricators is expanding output of modular crash-rated barrier systems to serve resource-sector procurement cycles. A-Safe leverages polymer engineering expertise to compete in chemical-resistant flexible barrier niches. Barrier Group anchors its position through permanent installation capabilities across Pilbara mine sites. Verge Safety Barriers differentiates via rapid-deployment temporary systems for construction staging areas.
Technical Definition and Segment Structure
Industrial barrier systems encompass engineered physical separations—typically fabricated from steel, polymer composites, or reinforced concrete—that absorb kinetic impact, demarcate hazard zones, and channel pedestrian or vehicular traffic within operational facilities. These installations incorporate deflection ratings measured in kilonewtons, surface visibility treatments, and substrate anchoring configurations calibrated to AS/NZS 3845.1 loading protocols. Steel barriers dominate capital-intensive permanent installations across mining and manufacturing footprints, while flexible polymer systems represent the fastest-growing product category as operators prioritize post-impact reusability and reduced maintenance downtime. Modular installation formats command premium positioning where reconfiguration frequency justifies higher first-cost outlays against lifecycle replacement savings.
Regulatory Environment and Outlook
TGA workplace safety directives intersect with AS/NZS standards and state-based WorkSafe regulations to mandate certified impact resistance ratings and documented inspection intervals across industrial sites. These compliance layers elevate barriers from discretionary capital to mandated infrastructure, tightening market access for uncertified suppliers. Stakeholders must monitor evolving harmonization between federal model codes and state enforcement intensity as procurement specifications harden.
Market Dynamics
Mining sector procurement cycles in Western Australia and Queensland are compressing installation timelines, forcing suppliers to pre-certify modular systems against AS/NZS 3845.1 protocols before contract tendering begins.
Growth Catalysts
- AS/NZS 3845.1 Compliance Mandates:TGA workplace safety directives and state-based WorkSafe regulations now require documented impact resistance ratings, converting barrier systems from discretionary purchases to mandated infrastructure across Pilbara mine sites.
- Polymer Engineering Advances:Flexible composite materials offering post-impact reusability are penetrating chemical handling facilities where steel corrosion previously drove replacement cycles.
- Queensland Coal Infrastructure:Bulk materials handling expansions at Gladstone and Hay Point ports are generating concentrated demand for heavy-duty vehicle restraint systems.
Market Restraints
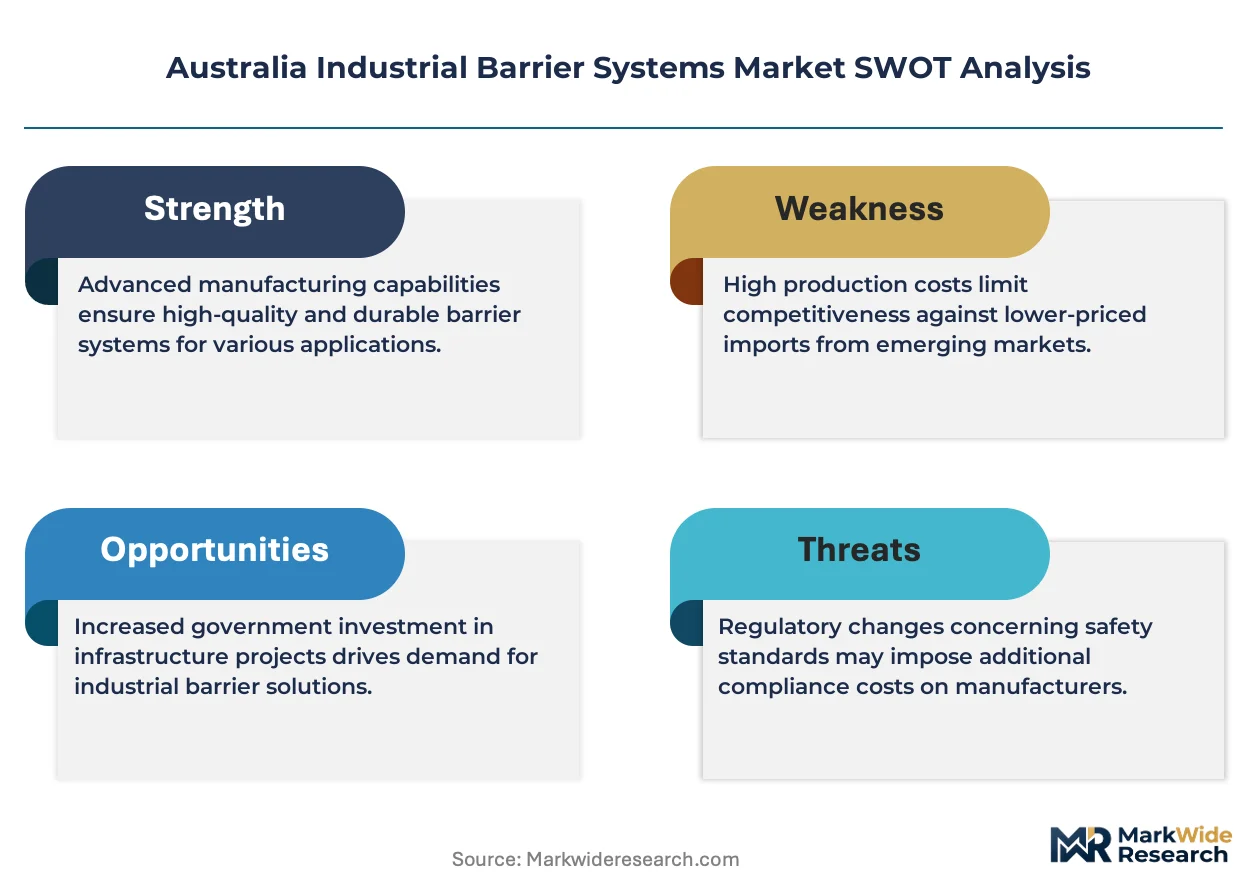
- Steel Input Volatility:Domestic fabrication costs fluctuate with imported hot-rolled coil pricing, squeezing margins on permanent installation contracts.
- Specialized Installer Scarcity:Certified anchoring technicians capable of substrate-specific installations remain concentrated in Perth and Brisbane metropolitan zones.
- Concrete Barrier Substitution:Cast-in-place concrete systems retain cost advantages in static, long-tenure applications such as perimeter security.
Strategic Opportunities
- New South Wales Infrastructure Corridors:WestConnex stage completions and Western Sydney Airport construction are creating demand for rapid-deployment temporary barrier systems.
- Smart Sensor Integration:Convergence of polymer barriers with IoT-enabled impact detection is opening predictive maintenance service revenue streams.
- WorkSafe Victoria Harmonization:Pending alignment of state enforcement intensity with federal model codes will expand addressable market for certified suppliers.
Industry Challenges
- Geotechnical Assessment Bottlenecks:Site-specific substrate analysis for Pilbara iron ore facilities extends pre-installation timelines by 4-8 weeks.
- Third-Party Certification Queues:NATA laboratory testing backlogs for new polymer formulations delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Industrial Barrier Systems Market |
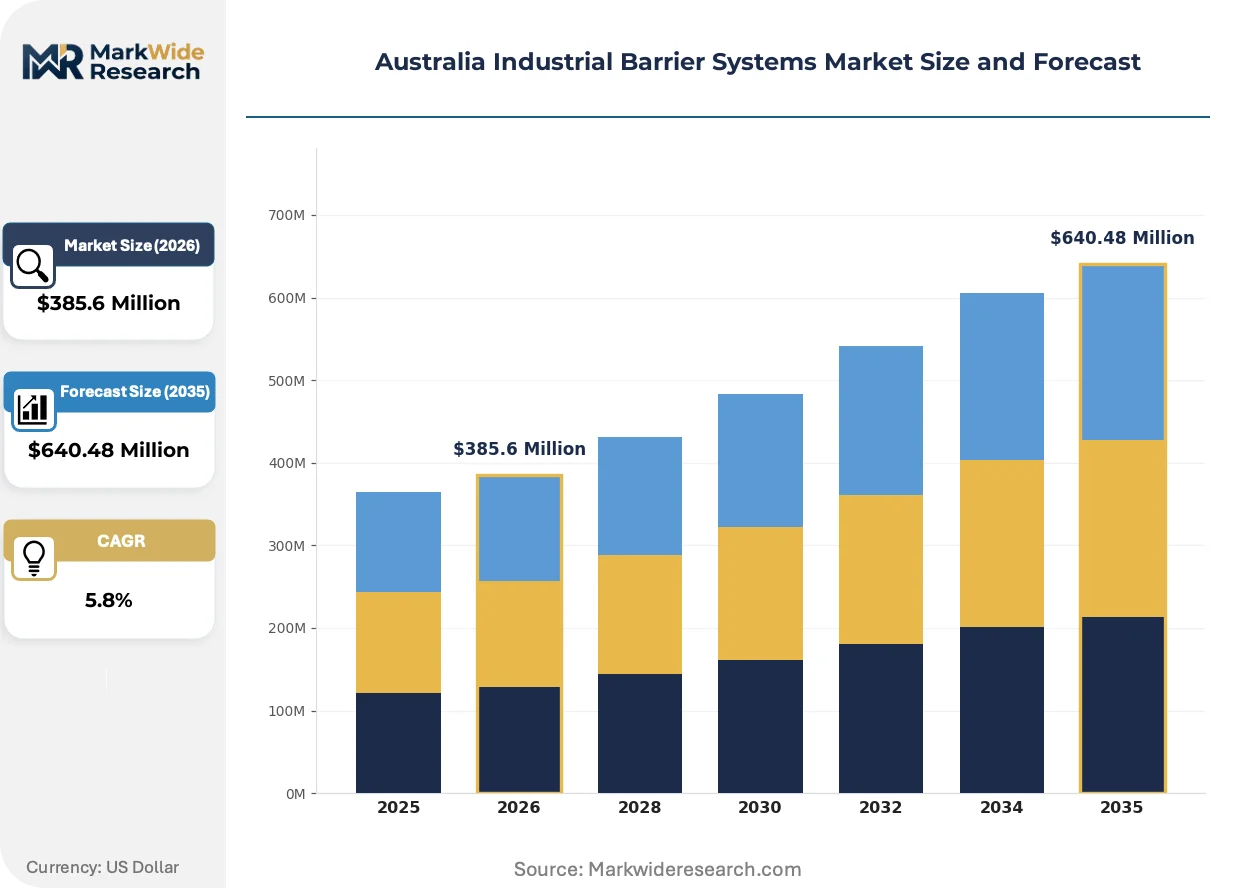
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Barriers, Plastic Barriers, Concrete Barriers, Flexible Barriers End User: Manufacturing, Construction, Mining, Transportation Installation Type: Permanent Installations, Temporary Installations, Modular Installations, Removable Installations Safety Feature: Impact Resistance, Visibility Enhancement, Noise Reduction, Weather Resistance |
| Companies Covered | A-Safe, Barrier Group, Verge Safety Barriers, Arbon Equipment Corporation, Sitecraft, Safe Direction, Premier Workplace Solutions, Area Safe, Australian Bollards, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Industrial Barrier Systems Market Trends and Innovations
Product architecture in Australian industrial barrier systems is pivoting from permanent steel fabrication toward reconfigurable polymer platforms that reduce lifecycle ownership costs. This shift redefines supplier value propositions around downtime minimization rather than initial capital outlay.
Polymer composite barriers incorporating elastomeric recovery layers is overtaking rigid steel guardrails in high-frequency impact zones. Rio Tinto and BHP maintenance divisions are specifying these systems for haul road intersections where vehicle contact rates exceed twelve incidents annually. The technology is compressing replacement parts revenue for traditional fabricators while expanding recurring service contracts for polymer system providers.
WorkSafe Queensland's 2024 amendments to the Mining and Quarrying Safety and Health Regulation now mandate documented deflection testing for all mobile equipment protection barriers. Surface operations across the Bowen Basin are retrofitting existing installations to meet the new documentation requirements. Underground coal operators in central Queensland are accelerating procurement of pre-certified modular systems to avoid production stoppages during compliance audits.
Asset owner procurement teams are unbundling installation from supply contracts, creating direct relationships with certified installation contractors. Mining maintenance departments in Western Australia are now separately tendering barrier supply, geotechnical assessment, and anchoring execution. This fragmentation is most visible in the Pilbara where Rio Tinto's Gudai-Darri and Western Range projects have adopted multi-vendor procurement structures.
Australia Industrial Barrier Systems Market Segmentation
Segmentation in Australian industrial barrier systems reveals how certification requirements and installation constraints reshape procurement patterns across resource-sector and infrastructure applications. Understanding these divisions exposes where AS/NZS compliance burdens concentrate and where flexible technologies displace traditional materials.
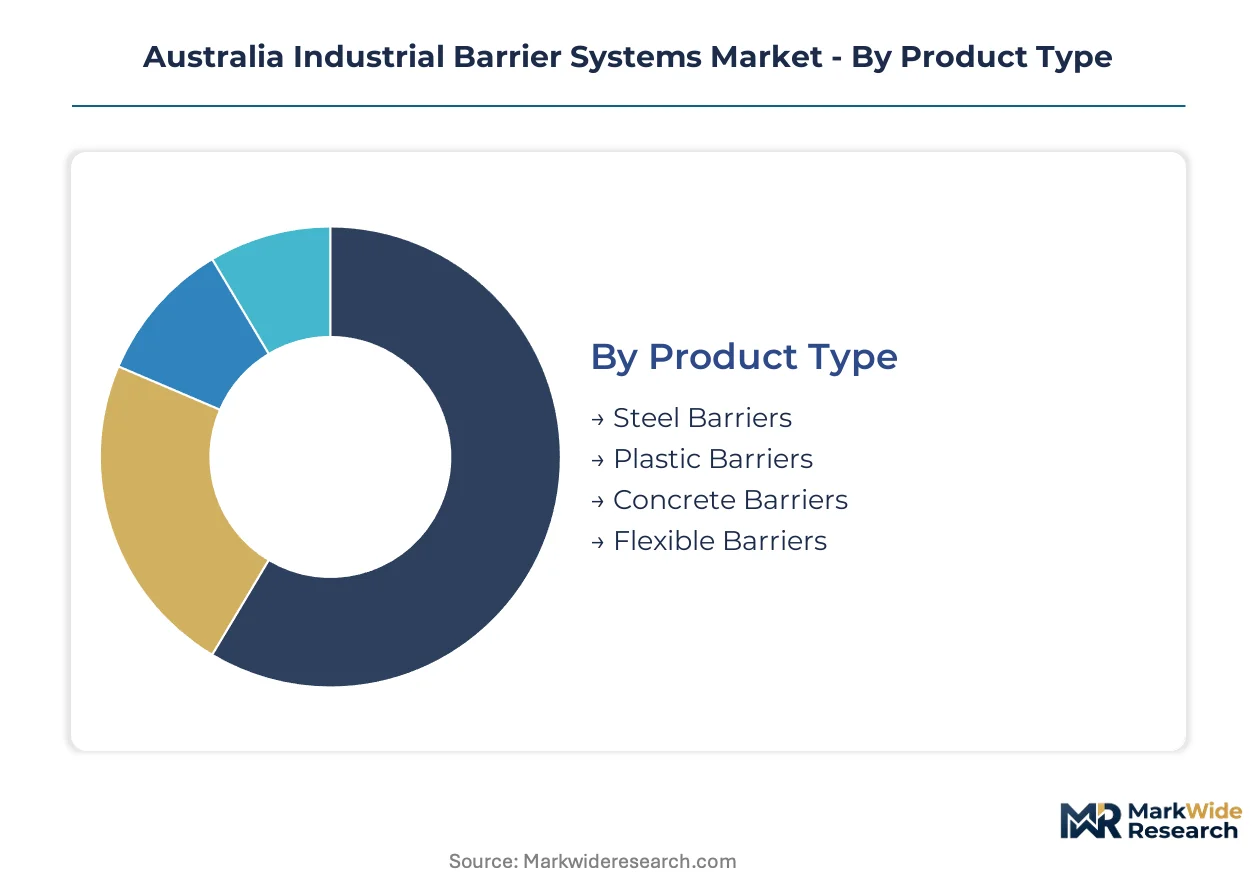
Product Type:
AS/NZS 3845.1 certification mandates apply differentially across material categories, with steel and concrete systems facing permanent-installation testing protocols while polymer barriers navigate chemical-resistance validation pathways.
- Steel Barriers:Fabricated from hot-rolled structural sections with welded post-and-rail configurations rated to 400kN impact loads. Western Australia mining corridors anchor demand as Pilbara iron ore operators specify crash-rated systems for haul road intersections.
- Flexible Barriers:Polymer composite platforms incorporating elastomeric recovery layers that rebound post-impact without component replacement. Queensland coal handling facilities are specifying these for high-frequency contact zones where traditional steel corrosion previously drove maintenance cycles.
- Plastic Barriers:Lightweight HDPE or PVC systems for pedestrian channeling and low-speed vehicle demarcation. Construction staging areas in New South Wales deploy these for rapid reconfiguration between project phases.
- Concrete Barriers:Cast-in-place or precast reinforced systems for static perimeter security and heavy-vehicle restraint. Long-tenure mining lease boundaries and port infrastructure favor these for lifecycle cost advantages.
Steel Barriers sits at the top of the volume ranking, with Flexible Barriers climbing the fastest.
End User:
Customer procurement sophistication varies sharply, with mining operators demanding bundled certification documentation while construction contractors prioritize rental-flexibility over ownership.
- Mining:Western Australia and Queensland resource giants specify impact-rated systems with documented deflection testing for mobile equipment protection. WorkSafe Queensland's amended Mining and Quarrying Safety and Health Regulation now mandates compliance documentation for all surface operations.
- Construction:Rapid-deployment temporary barriers dominate as WestConnex stage completions and Western Sydney Airport projects compress installation timelines. Procurement teams unbundle supply from installation contracts to accelerate site mobilization.
- Manufacturing:Chemical-resistant polymer systems penetrate food processing and pharmaceutical facilities where washdown protocols corrode traditional steel. TGA workplace safety directives intersect with state WorkSafe regulations to mandate certified installations.
- Transportation:Heavy-duty vehicle restraint systems for bulk materials handling expansions at Gladstone and Hay Point ports. These installations require substrate-specific anchoring configurations calibrated to geotechnical conditions.
Mining commands the largest addressable base, with Construction expanding most quickly on infrastructure pipeline momentum.
Installation Type:
Cost-tier stratification separates capital-intensive permanent systems from operational-expense rental models, with modular formats commanding premium positioning where reconfiguration frequency justifies higher first-cost outlays.
- Permanent Installations:Steel or concrete systems with embedded anchoring for decade-long service life. Pilbara mine sites specify these for haul road infrastructure where vehicle traffic density exceeds twelve incidents annually.
- Modular Installations:Pre-certified component systems allowing field reconfiguration without engineering redesign. Bowen Basin surface operators are accelerating procurement to avoid production stoppages during compliance audits.
- Temporary Installations:Rapid-deployment barriers for construction staging and event-based traffic management. Verge Safety Barriers has built positioning here through deployment speed rather than capital ownership.
- Removable Installations:Surface-mounted or weighted systems avoiding substrate penetration for leased facilities or heritage-sensitive sites. These trade impact resistance for installation flexibility in restricted geologies.
Permanent Installations retain volume leadership, with Modular Installations gaining share fastest on reconfiguration demand.
Safety Feature:
Performance-tier differentiation increasingly centers on integrated sensor capabilities and predictive maintenance service models rather than passive material specifications alone.
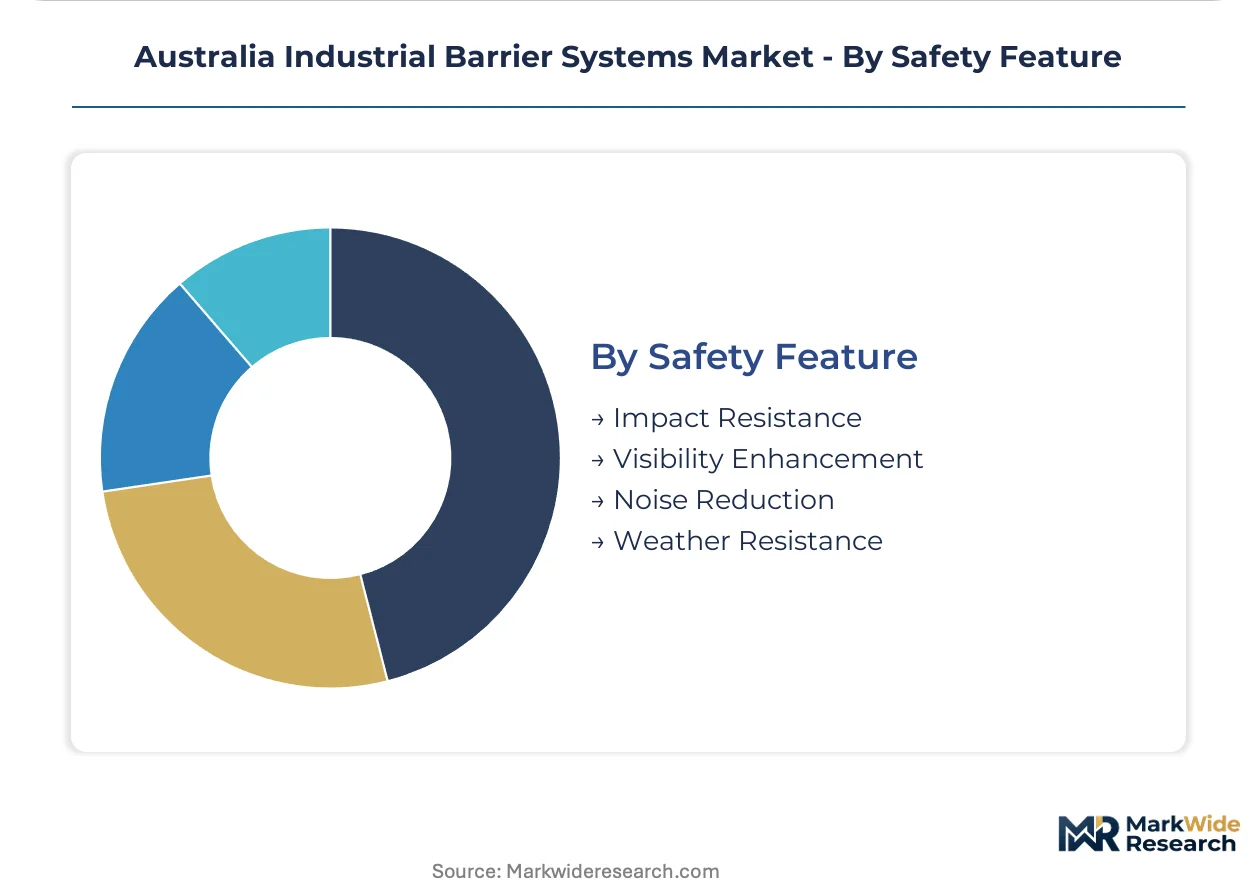
- Impact Resistance:Kilonewton-rated deflection performance certified to AS/NZS 3845.1 protocols. All Pilbara and Bowen Basin procurement now requires documented ratings, converting this from optional specification to mandated baseline.
- Visibility Enhancement:High-visibility surface treatments, LED integration, and reflective elements for low-light operational environments. Underground coal operators in central Queensland specify these for confined-space mobile equipment zones.
- Weather Resistance:UV-stabilized polymers and corrosion-protected steel for coastal and desert exposure conditions. Gladstone port infrastructure demands salt-spray validated systems.
- Noise Reduction:Acoustic dampening barriers for manufacturing facilities and urban construction sites facing community proximity constraints. These systems incorporate absorptive facing materials behind structural cores.
Impact Resistance dominates specification requirements, with Visibility Enhancement expanding most quickly on underground safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Australian states creates compliance-cost gaps that concentrate barrier system procurement in jurisdictions with harmonized enforcement. Western Australia and Queensland maintain stricter WorkSafe mandates than Victoria or South Australia, shifting supplier registration efforts toward high-intensity markets.
Western Australia
Pilbara iron ore operations drive demand for 400kN-rated steel barriers at haul road intersections. WorkSafe WA enforces AS/NZS 3845.1 documentation for all mobile equipment protection zones. Perth-based fabricators pre-certify modular systems before Rio Tinto and BHP tender cycles commence.
Queensland
Bowen Basin surface coal operators retrofit existing barriers to meet amended Mining and Quarrying Safety and Health Regulation requirements. WorkSafe Queensland mandates documented deflection testing for all mobile equipment protection barriers. Gladstone port bulk materials handling expansions specify salt-spray validated heavy-duty vehicle restraint systems.
New South Wales
WestConnex stage completions and Western Sydney Airport construction compress installation timelines for rapid-deployment temporary barriers. SafeWork NSW aligns with federal model codes while maintaining state-specific substrate assessment protocols. Sydney procurement teams unbundle supply from installation contracts to accelerate site mobilization.
Victoria
Manufacturing facilities in Melbourne's western industrial corridor specify chemical-resistant polymer systems for washdown-intensive environments. WorkSafe Victoria's pending harmonization with federal model codes will expand certified supplier addressable market. Geelong region food processing plants drive TGA workplace safety directive compliance for barrier installations.
South Australia
Olympic Dam and other remote mining operations face extended geotechnical assessment timelines that delay barrier deployment. SafeWork SA maintains lighter enforcement intensity than Western Australia or Queensland, reducing supplier pre-registration urgency. Adelaide metropolitan construction projects favor rental-flexible temporary systems over permanent installations.
Australia Industrial Barrier Systems Market Competitive Landscape
Western Australia producers anchor the permanent-installation tier; Queensland specialists hold temporary-deployment positioning. The vendor base separates into steel fabricators serving decade-long mining contracts and polymer engineers targeting reusable system niches. Three archetypes dominate: crash-rated steel fabricators, elastomeric recovery barrier engineers, and rapid-deployment rental operators. Capacity expansion and pre-certification against AS/NZS protocols constitute the dominant competitive moves.
Within the polymer engineering tier, A-Safe represents chemical-resistant flexible barrier specialization. Barrier Group anchors permanent installation capabilities across Pilbara mine sites. Verge Safety Barriers exemplifies rapid-deployment temporary systems for construction staging areas.
| Leading Market Players |
|---|
| A-Safe |
| Barrier Group |
| Verge Safety Barriers |
| Arbon Equipment Corporation |
| Sitecraft |
| Safe Direction |
| Premier Workplace Solutions |
| Area Safe |
| Australian Bollards |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between AS/NZS 3845.1 pre-certified systems and uncertified alternatives manifests in both pricing power and supply chain configuration. Premium-tier polymer barriers command 40-60% markups over commodity steel equivalents, with that premium reflecting NATA laboratory validation costs and Perth-based installer scarcity rather than material input differentials alone.
Pricing Analysis
Distributor margins concentrate in the 15-25% range for permanent steel installations, while direct-to-mine-site polymer supply contracts bypass traditional channel layers entirely. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates Rio Tinto procurement teams from smaller construction contractors. Cost compression in the steel fabrication tier is intensifying because imported hot-rolled coil pricing volatility squeezes domestic fabricator margins. Construction contractors exhibit highest price sensitivity, prioritizing rental-flexible temporary systems over capital ownership, while Pilbara mining operators accept premium first-cost outlays for documented deflection ratings.
Supply Chain Analysis
Refurbishment flows for elastomeric recovery barriers create reverse-logistics value pools that steel fabricators cannot replicate, with post-impact reusability driving recurring service contract revenue. Manufacturing concentration centers on Australia for fabricated steel systems, China for polymer composite feedstocks, and South Korea for specialized elastomeric formulations. Raw material dependencies rest on hot-rolled structural steel sections, UV-stabilized polymer resins, and geotechnical anchoring hardware. Single-source vulnerability runs through NATA-certified testing capacity, where laboratory backlogs delay product launch windows. Distribution runs through certified installation contractors who unbundle from supply contracts, fragmenting traditional vendor-buyer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Industrial Barrier Systems Market operates as a stable compounder anchored by TGA workplace safety mandates that convert discretionary capital to mandated infrastructure across mining and manufacturing footprints.
For Market Incumbents: Deepen vertical integration into NATA-certified testing capacity to compress product launch timelines and defend against polymer engineering specialists encroaching on chemical-resistant niches. Anchor Perth and Brisbane installer certification programs to lock in scarce anchoring technician capacity before WorkSafe Victoria harmonization expands addressable demand. For New Entrants and Emerging Players: Launch via rapid-deployment rental models targeting New South Wales infrastructure corridors where WestConnex and Western Sydney Airport projects compress mobilization timelines. White-space concentrates in smart sensor-integrated barriers for predictive maintenance service revenue, with IoT-enabled impact detection representing the most penetrable technology layer. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented installation contractor bases face unbundling demands from mining procurement teams seeking direct relationships. Long-term viability favors polymer engineering specialists with elastomeric recovery IP over commodity steel fabricators exposed to input cost volatility. Monitor WorkSafe Queensland audit intensity as inflection indicator for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NATA Pre-Certification Investment | Compresses tender eligibility timelines before Rio Tinto and BHP procurement cycles commence. |
| Polymer Engineering R&D Partnership | Accelerates chemical-resistant formulations for Queensland coal handling washdown environments. |
| Installer Certification Expansion | Captures scarce Perth and Brisbane anchoring technician capacity ahead of demand inflection. |
| Smart Sensor Integration Development | Opens predictive maintenance service revenue streams converging with IoT-enabled impact detection. |
| Geotechnical Assessment Capability Buildout | Resolves 4-8 week Pilbara substrate analysis bottlenecks delaying barrier deployment. |
Research Methodology
Direct dialogue with mining maintenance directors, construction procurement managers, polymer engineering R&D leads, and certified installation contractors anchored qualitative grounding, combined with secondary validation from AS/NZS standards documentation, WorkSafe enforcement bulletins, TGA workplace safety directives, and customs trade data for steel and polymer imports. Bottom-up project pipeline analysis across Pilbara mine sites, Bowen Basin surface operations, and New South Wales infrastructure corridors triangulated with top-down market sizing.
Segment-level projections across product type, end user, installation format, and safety feature dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from weighted average of historical procurement cycle analysis and forward pipeline visibility. Forecast inputs incorporated mining capital expenditure intentions, infrastructure project staging timelines, and regulatory amendment implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geotechnical assessment delays or NATA laboratory capacity constraints. Forecasts reflect documented assumptions regarding WorkSafe harmonization timing and polymer formulation certification queues. Practitioners should monitor TGA directive amendments and Queensland audit enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
US Access Control Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Border Security System Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Vehicle Security System Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Card-Based Electronic Access Control Systems Market