
 Global Commercial Security System Market | 2026-2036
Global Commercial Security System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Security System Market Foresight
Cloud-based management is broadening what commercial security providers sell beyond hardware to recurring subscription revenue. Honeywell International Inc. leverages its building automation heritage to bundle climate, fire, and access control into unified platforms. Bosch Security Systems GmbH anchors its European installed base with predictive maintenance contracts that reduce downtime for corporate offices. Hangzhou Hikvision Digital Technology Co., Ltd. dominates video analytics R&D spending, sustaining price competitiveness across emerging markets.
A commercial security system integrates sensors, controllers, and communication networks to detect unauthorized access, environmental hazards, and perimeter breaches with response latencies under 500 milliseconds. Surveillance cameras incorporating edge-based video analytics now process footage locally, reducing bandwidth costs for data centers and government buildings. Biometric authentication is capturing margin pools in banking facilities where fingerprint and iris recognition replace card-based access. Wireless sensors are expanding fastest in warehouse applications where retrofitting legacy structures with minimal cabling cuts installation costs by half.
The EU AI Act, GDPR, and NIST Cybersecurity Framework are mandating algorithmic transparency and data minimization for facial recognition deployments, forcing vendors to re-engineer analytics pipelines. The FCC in the United States enforces spectrum allocation for wireless sensor networks, shaping product certification timelines for RFID and motion detection hardware. Facility management companies and large corporations must evaluate vendor compliance portfolios against multi-jurisdiction requirements before standardizing on single platforms.
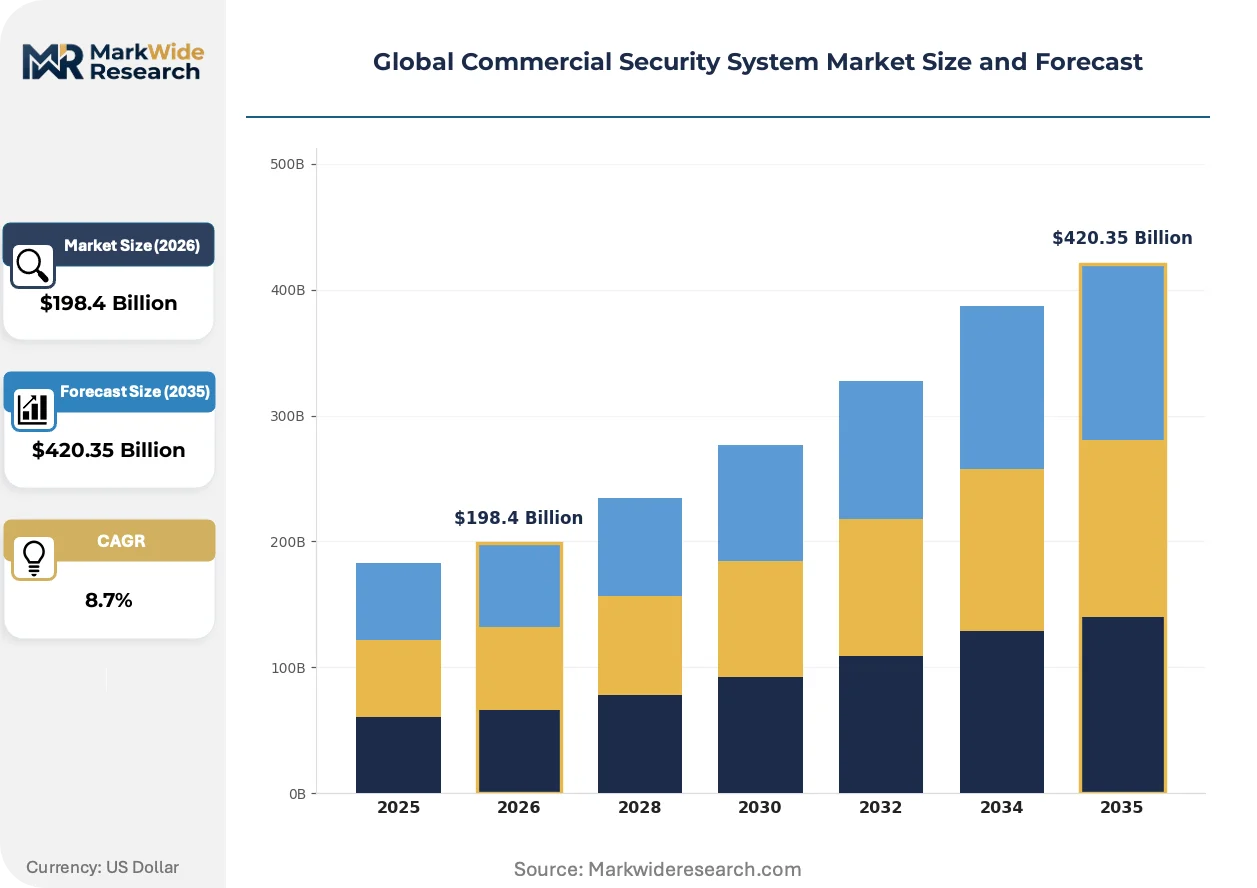
Market Dynamics
Cloud-native architectures are compressing hardware margins while expanding recurring revenue pools for commercial security providers, forcing incumbents to restructure sales organizations around subscription metrics rather than unit shipments.
Growth Catalysts
- Biometric authentication mandates:Banking regulators in Germany and Singapore require multi-factor authentication for high-value transactions, accelerating fingerprint and iris recognition deployments across financial institutions.
- Critical infrastructure protection budgets:United States federal spending on power grid and transportation security is expanding fastest among OECD nations, concentrating demand for perimeter intrusion detection systems.
- Edge computing architectures:Video analytics processing at the camera level reduces bandwidth costs for data center operators and eliminates cloud latency for real-time threat response.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends on Taiwan and South Korean foundry capacity, exposing security hardware vendors to geopolitical supply disruptions.
- GDPR algorithmic transparency requirements:Facial recognition deployments in European corporate campuses face mandatory explainability audits, extending sales cycles by 6-12 months.
- Wireless spectrum scarcity:FCC allocation constraints for RFID and motion detection frequencies in the United States limit sensor density in dense urban installations.
Strategic Opportunities
- India smart city infrastructure:Municipal surveillance tenders in Mumbai, Delhi, and Bangalore specify AI-enabled video analytics, creating white space for privacy-certified platform vendors.
- EU AI Act compliance services:Algorithmic risk classification mandates for biometric systems create adjacent revenue streams for audit and certification providers.
- Convergence of physical and cybersecurity:Unified threat management platforms that correlate access control logs with network intrusion data command premium pricing from multinational headquarters.
Industry Challenges
- Embedded systems cybersecurity expertise:Shortage of firmware engineers with NIST Cybersecurity Framework implementation experience delays product certification timelines.
- Legacy access control retrofit complexity:Wiegand protocol migration to OSDP encrypted communications requires phased hardware replacement that strains facility management budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Security System Market |
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $420.35 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Surveillance Cameras, Intrusion Detection, Fire Alarm Systems, Perimeter Security Technology: Biometric Authentication, Video Analytics, Wireless Sensors, Cloud-based Management, Motion Detection, RFID Application: Banking Facilities, Corporate Offices, Educational Institutes, Warehouses, Government Buildings, Data Centers Customer Type: Small and Medium Enterprises, Large Corporations, Facility Management Companies, Retail Chains, Hospitality Companies |
| Companies Covered | Honeywell International Inc., Johnson Controls International plc, Bosch Security Systems GmbH, Hangzhou Hikvision Digital Technology Co., Ltd., Axis Communications AB, Zhejiang Dahua Technology Co., Ltd., ADT, Inc., ASSA ABLOY AB, Carrier Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Security System Market Shifts & Advancements
Artificial intelligence inference at the network edge is redistributing computational load away from centralized servers, while privacy regulations force architectural redesigns of biometric data pipelines.
Edge-based video analytics is consolidating standalone server appliances into camera-embedded processing units. Data center operators in Northern Virginia and Frankfurt are deploying these systems to eliminate bandwidth charges for 24/7 recording. This compression of hardware tiers is consolidating mid-range NVR vendors into software licensing models.
The EU AI Act risk classification framework is mandating human oversight interfaces for biometric identification systems deployed in public spaces. Security integrators must now document algorithmic decision trails for law enforcement and transport authority clients. French and German facility managers are prioritizing vendors with pre-certified conformity assessment procedures to accelerate deployment timelines.
Subscription-based managed security services are displacing capital-intensive ownership models among mid-market retail and logistics chains. Channel partners in the United States are unbundling installation from monitoring to capture recurring revenue streams. This shift is most visible among national pharmacy and grocery chains standardizing on cloud-managed access control across hundreds of locations.
Global Commercial Security System Market Segmentation
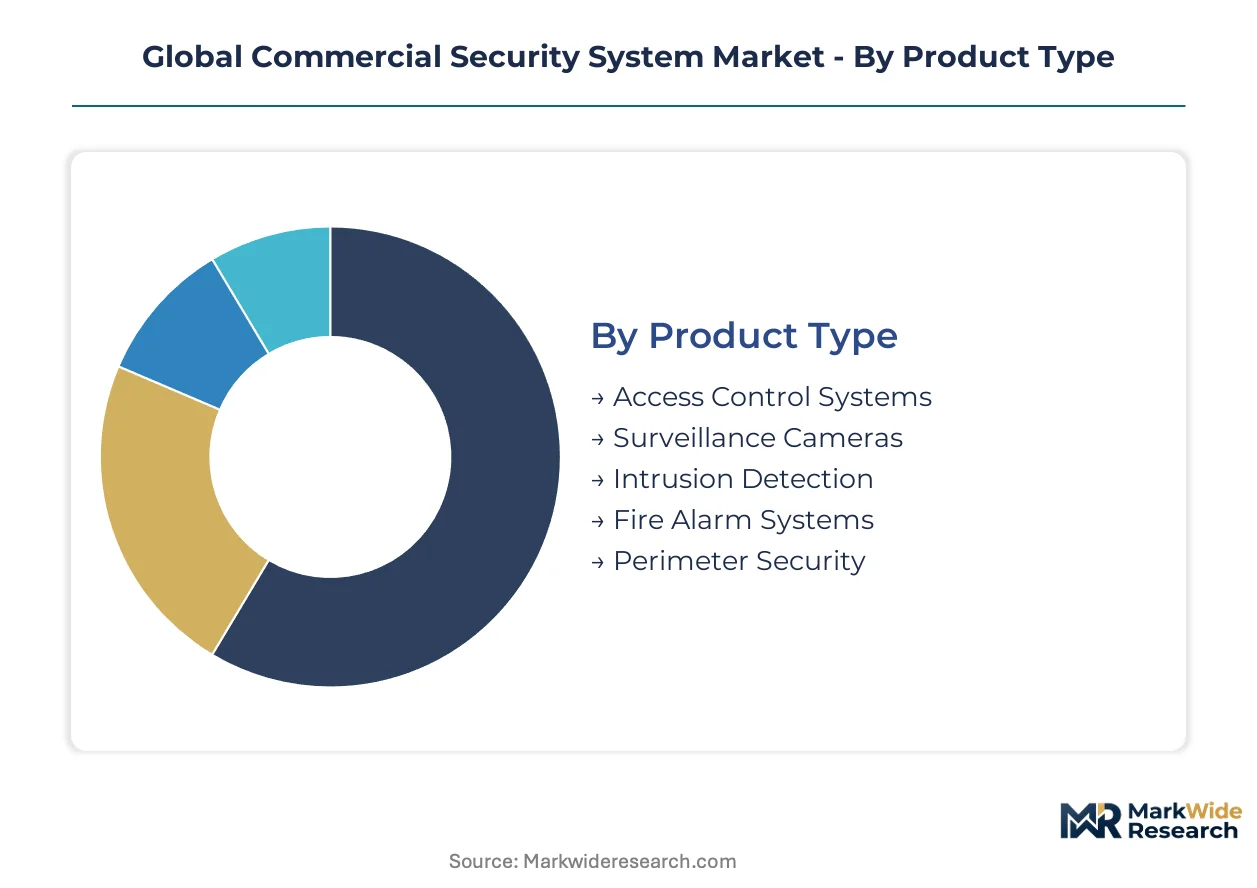
Commercial security procurement splits sharply between capital-intensive hardware ownership and recurring service subscriptions, with technology choices determining margin structures across banking, logistics, and critical infrastructure verticals.
Product Type:
Volume shipments concentrate in perimeter hardware, while premium pricing attaches to integrated platforms that unify multiple detection modalities under single management consoles.
- Access Control Systems:Credential readers, electronic locks, and centralized management software govern entry points through card, biometric, or mobile token verification. Banking facilities in Germany and Singapore are mandating multi-factor authentication for high-value transaction zones, accelerating fingerprint and iris recognition module procurement.
- Surveillance Cameras:Fixed, PTZ, and panoramic camera housings incorporate edge-based video analytics processors that eliminate centralized server dependencies. Data center operators in Northern Virginia and Frankfurt deploy these to avoid bandwidth charges for continuous recording while maintaining sub-500-millisecond threat response latencies.
- Intrusion Detection:Glass-break sensors, magnetic contacts, and volumetric detectors trigger alerts through hardwired or wireless signaling paths.
- Fire Alarm Systems:Smoke, heat, and multi-criteria detectors integrate with suppression release panels and mass notification networks.
- Perimeter Security:Buried cable sensors, fence-mounted accelerometers, and thermal imaging towers protect critical infrastructure boundaries.
Mature deployment sits with Surveillance Cameras. Newer deployment is concentrated in Access Control Systems.
Technology:
Cloud-native architectures are compressing hardware margins while expanding recurring revenue pools, forcing vendors to restructure sales organizations around subscription metrics rather than unit shipments.
- Biometric Authentication:Fingerprint, facial, iris, and vein pattern recognition modules provide non-transferable identity verification resistant to credential sharing. EU AI Act risk classification mandates are forcing re-engineering of algorithmic pipelines to achieve conformity assessment certification before deployment in French and German public spaces.
- Video Analytics:Object classification, behavior recognition, and anomaly detection algorithms process footage at the edge or in centralized servers. Warehouse operators are expanding fastest here, using occupancy analytics and safety compliance monitoring to reduce insurance premiums across distribution networks.
- Wireless Sensors:Battery-powered motion, door contact, and environmental monitors eliminate cabling costs in retrofit applications.
- Cloud-based Management:Browser-accessible configuration, monitoring, and firmware update platforms replace on-premise server installations.
- Motion Detection:PIR, microwave, and dual-technology sensors trigger illumination or recording activation.
- RFID:Passive and active radio-frequency identification tags enable asset tracking and long-range access credentialing.
Established infrastructure relies on Motion Detection. Steepest expansion trajectory belongs to Video Analytics.
Application:
Critical infrastructure protection budgets are expanding fastest in the United States, China, and Germany, concentrating demand for perimeter intrusion detection and cyber-physical convergence platforms.
- Banking Facilities:Vaults, teller lines, and ATM vestibules require layered authentication and covert surveillance resistant to tampering. Regulatory mandates from Germany's BaFin and Singapore's MAS are accelerating biometric deployment across financial institution branches.
- Corporate Offices:Multi-tenant lobbies, executive floors, and parking structures integrate access control with visitor management and elevator destination dispatch. Large multinational headquarters command premium pricing for unified threat management platforms that correlate physical access logs with network intrusion data.
- Educational Institutes:Campus perimeters, dormitory entrances, and emergency notification systems address active threat response protocols.
- Warehouses:Loading docks, inventory aisles, and cold storage zones prioritize wireless retrofit solutions that cut installation costs by half in legacy concrete structures.
- Government Buildings:Classified spaces and public service counters mandate NIST Cybersecurity Framework compliance for firmware and communications encryption.
- Data Centers:Mantrap entries, cabinet-level access logging, and environmental monitoring protect hyperscale and colocation facilities.
Traditional investment centers on Corporate Offices. Fastest-growing deployment concentrates in Data Centers.
Customer Type:
Procurement authority is shifting from facilities departments to chief security officers and chief information officers as cyber-physical convergence demands unified governance frameworks.
- Small and Medium Enterprises:Limited IT staffing drives preference for cloud-managed systems with remote dealer support and predictable monthly expenditures.
- Large Corporations:Centralized security operations centers demand enterprise-grade platforms with API integration into identity management and building automation systems. These buyers command volume discounts while insisting on dedicated account engineering support and custom analytics development.
- Facility Management Companies:Multi-site service contracts prioritize standardized platforms that reduce technician training costs and spare parts inventory.
- Retail Chains:Loss prevention departments balance shrinkage reduction against customer experience friction at store entrances.
- Hospitality Companies:Guest safety and liability mitigation drive investment in elevator emergency communications and pool monitoring systems.
Consolidated procurement dominates among Facility Management Companies. Fragmented purchasing persists with Small and Medium Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor commands the densest concentration of perimeter intrusion detection deployments, with hyperscale operators mandating sub-500-millisecond threat response latencies across multi-facility campuses.
United States
Critical infrastructure protection budgets are expanding fastest among OECD nations, with federal spending concentrating on power grid and transportation security. The FCC enforces spectrum allocation constraints for wireless sensor networks, shaping RFID and motion detection hardware certification timelines. Security integrators in Northern Virginia and Dallas-Fort Worth are deploying edge-based video analytics to eliminate bandwidth charges for 24/7 recording.
Germany
BaFin mandates multi-factor biometric authentication for high-value banking transactions, accelerating fingerprint and iris recognition module procurement across financial institution branches. The EU AI Act and GDPR compliance requirements are forcing algorithmic transparency audits for facial recognition deployments, extending sales cycles by 6-12 months. Frankfurt's data center operators are prioritizing privacy-certified video analytics platforms to satisfy regulatory scrutiny.
China
Municipal surveillance tenders in smart city infrastructure specify AI-enabled video analytics, creating procurement volume in Shanghai, Beijing, and Shenzhen. MIIT and GB standards govern encryption and data localization for security hardware deployed in government facilities. Hangzhou's technology corridor anchors domestic R&D spending on edge-based processing units, sustaining price competitiveness across emerging markets.
Singapore
MAS regulations require biometric authentication for high-value transaction zones in banking facilities, driving fingerprint and iris recognition deployments. The city-state's position as a regional headquarters hub concentrates demand for unified threat management platforms correlating physical access with network intrusion data. Marina Bay and Changi Business Park clusters are standardizing on cloud-managed access control across multi-tenant developments.
India
Municipal surveillance tenders in Mumbai, Delhi, and Bangalore specify AI-enabled video analytics, creating white space for privacy-certified platform vendors. BIS certification requirements and the PLI scheme for electronics manufacturing are reshaping procurement criteria for security hardware. Hyderabad's technology corridor is emerging as a deployment hub for wireless retrofit solutions in legacy warehouse structures.
Global Commercial Security System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the commercial security system market, with integrated platform vendors commanding premium pricing against point-solution specialists. The vendor base stratifies into three tiers: multinational conglomerates with building automation heritage, pure-play security specialists with regional installed bases, and emerging cloud-native entrants restructuring around subscription metrics. Dominant competitive moves include portfolio diversification into adjacent building systems and geographic expansion through channel partner networks rather than direct sales force investment.
Among diversified technology conglomerates, Honeywell International Inc. and Johnson Controls International plc exemplify the integrated platform archetype, leveraging building automation heritage to bundle climate, fire, and access control into unified management consoles. Bosch Security Systems GmbH anchors the European specialist tier with predictive maintenance contract structures, while Hangzhou Hikvision Digital Technology Co., Ltd. occupies a position at the scale-driven end of video analytics R&D investment. These three entities collectively represent the competitive tension between hardware margin compression and recurring revenue expansion that is restructuring sales organizations across the industry.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International plc |
| Bosch Security Systems GmbH |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Axis Communications AB |
| Zhejiang Dahua Technology Co., Ltd. |
| ADT, Inc. |
| ASSA ABLOY AB |
| Carrier Global Corporation |
| Others |
Supply & Pricing Matrix
Image sensor fabrication costs in Taiwan and South Korean foundries cascade through three distinct pricing tiers for security hardware vendors, with EU AI Act compliance certification emerging as the decisive margin separator between premium platform providers and commodity equipment suppliers.
Pricing Analysis
Uptime guarantees and threat response latency commitments anchor value-based pricing for integrated security platforms. Three-tier pricing structure across premium, standard, and economy levels separates vendors with pre-certified GDPR algorithmic transparency from those requiring 6-12 month audit extensions. Cost compression in mid-range NVR hardware is intensifying because edge-based video analytics eliminate centralized server dependencies. Small and medium enterprises exhibit highest price sensitivity due to limited IT staffing, while data center operators in Northern Virginia and Frankfurt accept premium positioning for sub-500-millisecond response commitments.
Supply Chain Analysis
CMOS image sensor supply rests on Taiwanese and South Korean foundry capacity, with Bosch and Honeywell sourcing from these concentrated production nodes. Specialized edge-processing chipsets, encrypted OSDP communication modules, and thermal imaging cores feed from semiconductor fabrication networks in China, Japan, and Germany. Single-source vulnerability in Taiwan Strait logistics exposes security hardware vendors to geopolitical disruption. Distribution runs through authorized security integrators and facility management service contracts rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Commercial Security System Market operates as a cost-of-compliance story where EU AI Act algorithmic risk classification mandates create barrier-to-entry moats for vendors with pre-certified conformity assessment procedures.
For Market Incumbents: Lock in recurring revenue conversion by restructuring sales organizations around subscription metrics rather than unit shipments, countering cloud-native entrants compressing hardware margins. Prioritize predictive maintenance contract structures that reduce downtime for corporate offices, defending against pure-play specialists with regional installed bases. Invest in NIST Cybersecurity Framework firmware certification to maintain procurement eligibility for United States government buildings. For New Entrants and Emerging Players: Launch via cloud-managed access control platforms targeting mid-market retail and pharmacy chains standardizing across hundreds of locations. Municipal surveillance tenders in Mumbai, Delhi, and Bangalore represent the most penetrable white space, specifying AI-enabled video analytics without legacy vendor lock-in. Position around privacy-certified platform architectures to satisfy EU AI Act and GDPR requirements extending sales cycles for incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light designers with cloud-native architectures in United States and German markets where capital-heavy producers face margin compression. Long-term viability hinges on recurring revenue mix exceeding hardware dependency. Watch for FCC spectrum allocation decisions affecting wireless sensor network density as inflection indicator for RFID and motion detection hardware certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certified conformity assessment procedures accelerate deployment timelines in French and German public spaces. |
| Edge Computing Architecture Migration | Camera-embedded processing units eliminate bandwidth charges for data center operators in Northern Virginia and Frankfurt. |
| Predictive Maintenance Contract Expansion | Bosch Security Systems GmbH structures reduce downtime for corporate offices across European installed bases. |
| Cloud-Native Platform Development | Browser-accessible management consoles displace capital-intensive ownership models among mid-market retail chains. |
| Biometric Authentication Module Procurement | BaFin and MAS regulatory mandates accelerate fingerprint and iris recognition deployment across banking facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across security integrators, facility management procurement directors, chief security officers, and cloud platform engineers. Bottom-up shipment data from access control, surveillance camera, and intrusion detection manufacturers triangulated against top-down critical infrastructure protection budget disclosures from United States, German, and Chinese government sources.
Segment-level modeling tracked product type, technology architecture, application vertical, and customer procurement authority across the analysis window. CAGRs derived from regression analysis of historical deployment trajectories in banking facilities, data centers, and warehouse retrofit applications, incorporating edge computing adoption curves and biometric authentication mandate implementation timelines.
Semiconductor supply disruptions, EU AI Act enforcement variance across member states, and FCC spectrum allocation decisions are the dominant revision risks. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
US Access Control Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
North America Home Security System Market