
 Automated Smart Locker System Market | 2026-2036
Automated Smart Locker System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Smart Locker System Market Intelligence
Logistics companies is shifting from centralized distribution hubs toward micro-fulfillment nodes with embedded smart lockers. Cuboid Industries leverages its manufacturing scale to dominate parcel locker deployments across dense urban corridors. Velocity Smart Technology competes through IoT-based platform specialization, while Gantner anchors European market access with RFID-native hardware architectures.
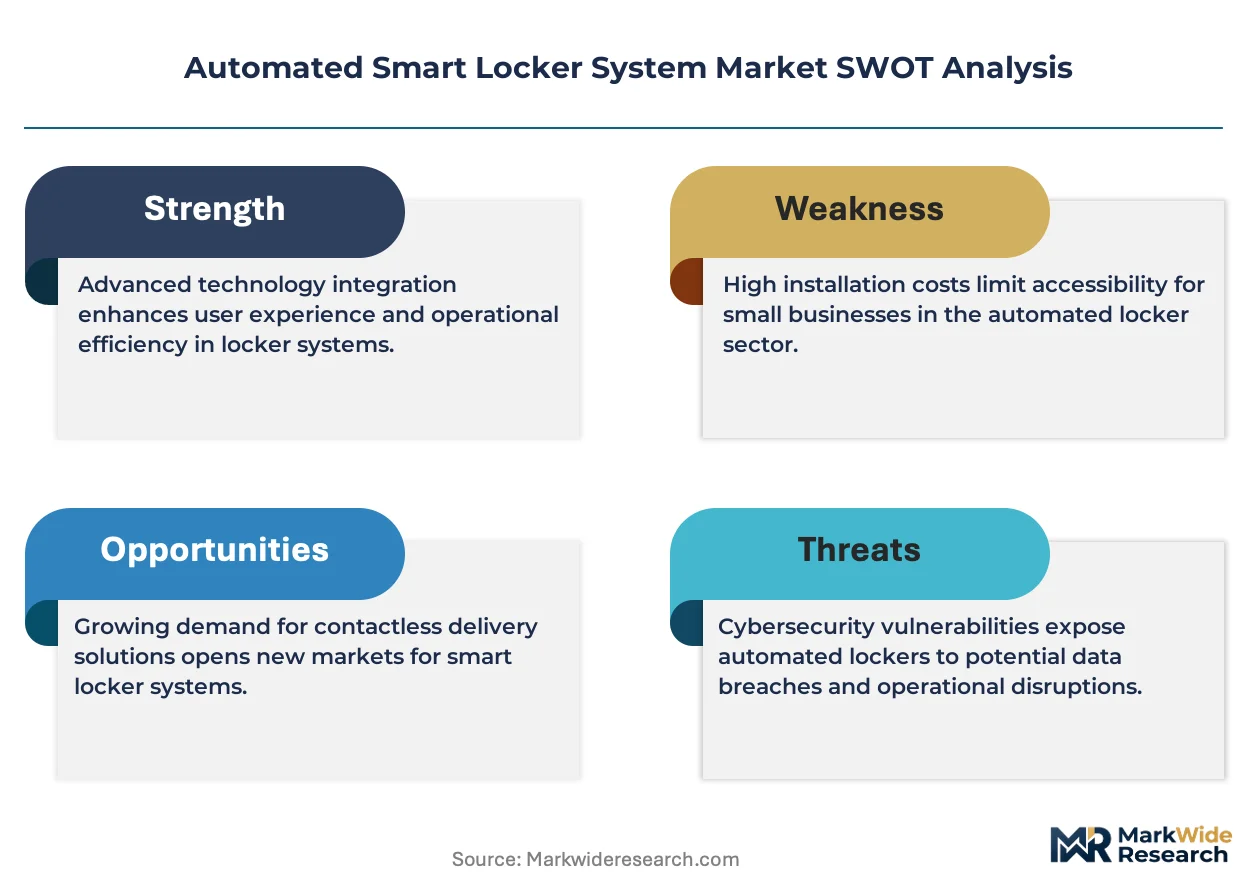
An automated smart locker system comprises modular, electronically controlled storage compartments with integrated authentication mechanisms, typically supporting 50-500 individual cells per installation unit, designed for secure, self-service exchange of goods, documents, or equipment without human attendant oversight. Parcel lockers lead product type demand due to e-commerce fulfillment saturation, while cloud-connected integration level captures the fastest growth trajectory as operators prioritize remote monitoring and API-driven fleet management over standalone units. Biometric technology segments remain niche but occupy premium margin pools in corporate security and high-value asset custody applications.
FCC certification governs wireless communication modules in US-deployed systems, while CE marking and GDPR compliance shape European product design and data handling protocols. Japan's METI promotes smart logistics infrastructure through standardization initiatives that directly influence locker interoperability requirements. Stakeholders must evaluate regulatory divergence across authentication data storage mandates when selecting technology architecture and geographic rollout sequencing.
Market Dynamics
Logistics operators are consolidating last-mile infrastructure around cloud-native locker networks that compress delivery dwell times and reduce failed-attempt costs. This architectural shift toward distributed micro-fulfillment nodes is restructuring capital deployment across parcel, grocery, and pharmaceutical distribution chains.
Growth Catalysts
- Japan METI Standardization:The ministry's smart logistics infrastructure initiatives mandate interoperability protocols that reduce deployment friction for multi-operator locker networks in dense urban corridors.
- E-commerce fulfillment saturation:Parcel volumes exceeding residential concierge capacity are forcing property managers across Germany and the United States to install automated handoff infrastructure as standard amenity.
- RFID-native hardware architectures:Contactless authentication is reducing per-transaction processing time to under 10 seconds, enabling high-throughput deployments in transit hubs and corporate campuses.
Market Restraints
- Steel and aluminum input volatility:Modular locker chassis fabrication depends on sheet metal prices that fluctuate with construction sector demand cycles, compressing gross margins on fixed-price municipal contracts.
- GDPR authentication data mandates:European biometric storage requirements impose encryption infrastructure costs that deter small-format deployments in rural postal networks.
- Curbside pickup substitution:Retailers operating dedicated drive-through lanes in suburban United States markets are diverting capital from locker installations where land costs permit surface parking expansion.
Strategic Opportunities
- Pharmaceutical cold-chain custody:Temperature-controlled locker cells with continuous IoT monitoring are opening prescription fulfillment contracts with hospital outpatient networks and specialty pharmacy distributors.
- India BIS certification pathway:The bureau's electronics safety standards for public access equipment are creating a regulatory on-ramp for imported locker systems targeting tier-1 metro residential complexes.
- API-driven fleet orchestration:Converging locker management platforms with route optimization software is enabling dynamic capacity allocation across carrier networks during peak demand windows.
Industry Challenges
- FCC modular certification timelines:Wireless communication module approvals for US deployments average 14-18 weeks, delaying pilot-to-scale transitions for logistics operators with seasonal volume commitments.
- Legacy WMS integration complexity:Warehouse management systems at third-party logistics providers require custom middleware development to synchronize locker inventory states with upstream order management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Smart Locker System Market |
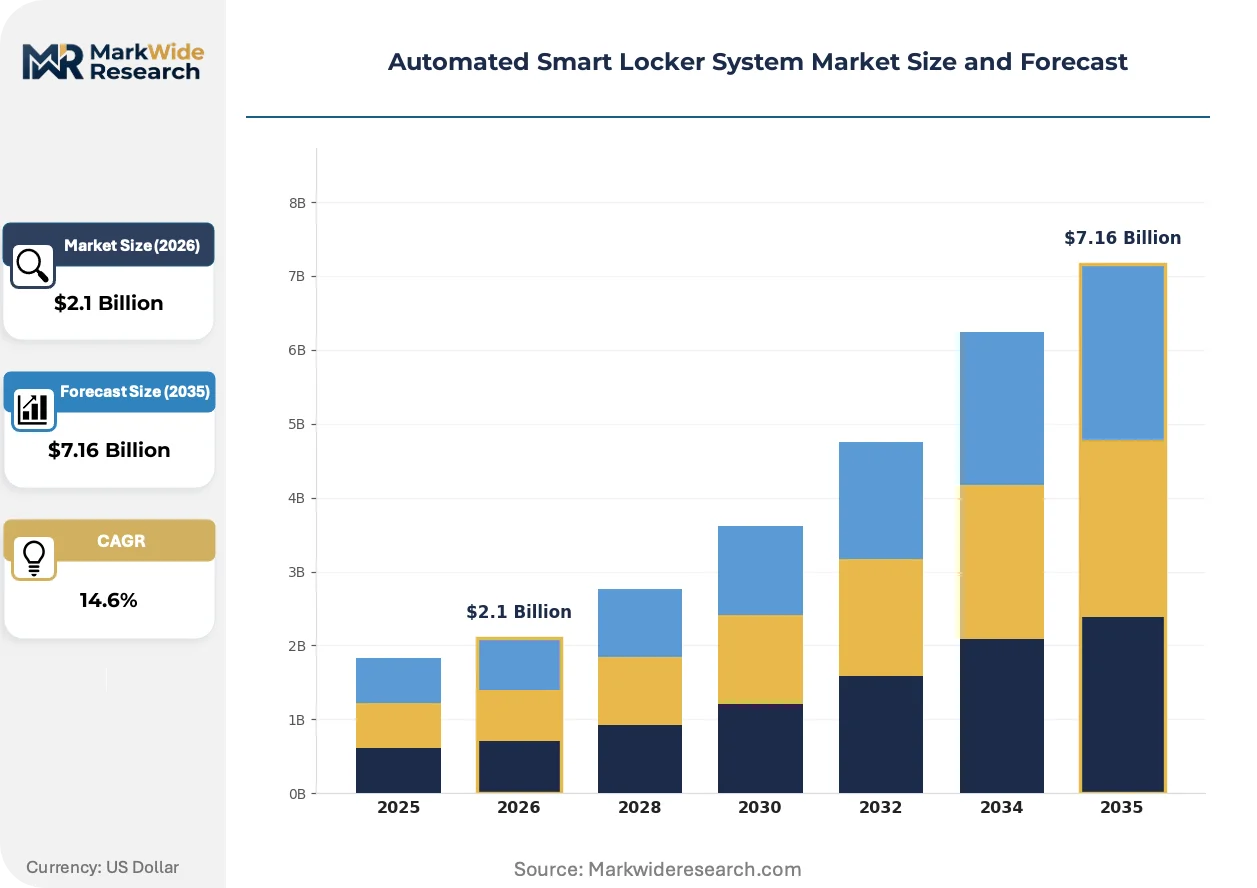
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parcel Lockers, Food Lockers, Laundry Lockers, Gym Lockers End User: Retail Stores, Educational Institutions, Logistics Companies, Corporate Offices Technology: IoT-Based, RFID, QR Code, Biometric Integration Level: Standalone, Cloud-Connected, Fully Automated, Hybrid |
| Companies Covered | Cuboid Industries, Parzelo, Velocity Smart Technology, Omnic, Sfinx Inside, uPOD Lockers, trakc, Gantner, BACE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Smart Locker System Market Strategic Shifts & Innovations
Three forces are compressing deployment cycles and reshaping buyer specifications across the automated locker value chain. Hardware commoditization is pushing differentiation toward software-layer services, while regulatory pressure on data sovereignty is fragmenting platform architectures.
Computer vision-based parcel dimensioning is electrifying inbound processing workflows at consolidation hubs. Automated cell allocation algorithms now size items against available compartment geometry in real time, eliminating manual pre-sorting. European postal operators are deploying these systems at Amsterdam and Frankfurt airport cargo terminals, compressing hub-to-locker transfer windows from 4 hours to 90 minutes.
CE marking requirements under the EU AI Act are forcing authentication algorithm disclosures for biometric-enabled lockers deployed in France and Germany. Hardware vendors must document facial recognition training data provenance and retention protocols to maintain market access. This transparency mandate is favoring European-headquartered platform providers with established data governance frameworks over Asian competitors.
Carrier-neutral locker access is displacing single-operator exclusivity in municipal procurement specifications. Berlin and Tokyo transit authorities now require open-network APIs that allow any logistics provider to reserve cells through standardized protocols. This specification shift is fragmenting deployment contracts across multiple hardware vendors rather than consolidating around integrated carrier-locker combinations.
Automated Smart Locker System Market Segmentation
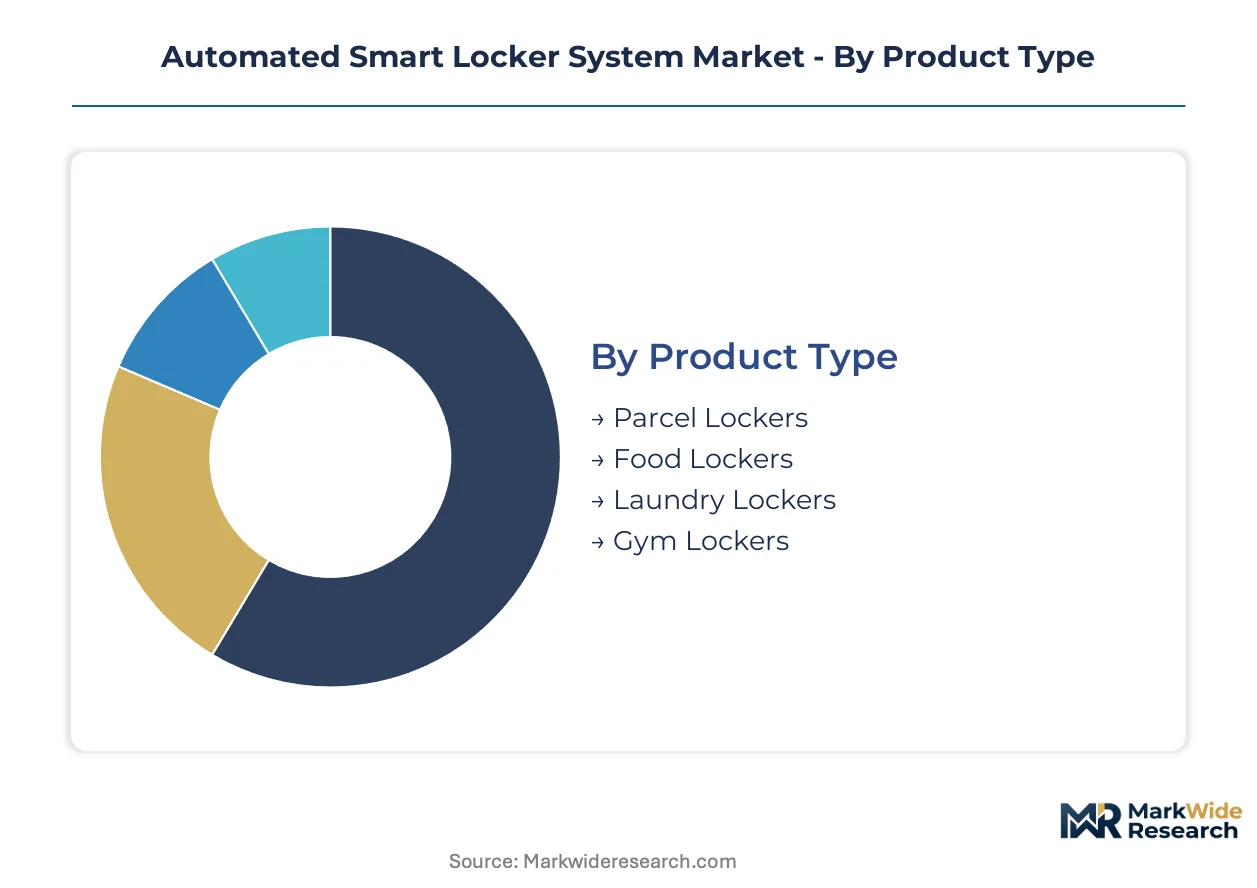
Segmentation in automated smart locker systems reveals how deployment architecture varies by payload sensitivity, authentication requirements, and backend connectivity depth. Buyers select configurations based on throughput demands, regulatory constraints, and existing IT infrastructure rather than hardware specifications alone.
Product Type:
Standalone parcel lockers operate independently with localized control systems, while food and pharmaceutical lockers embed temperature monitoring and compliance logging into unified platforms.
- Parcel Lockers:Modular chassis with 50-500 electronically controlled cells support package exchange across residential concierges, transit hubs, and retail storefronts. Logistics operators in Germany and the United States deploy these as micro-fulfillment nodes to compress last-mile dwell times. E-commerce volume saturation is forcing property managers to install parcel lockers as standard amenities in multi-tenant buildings.
- Food Lockers:Insulated compartments with heating or cooling elements maintain safe temperature bands for prepared meals and grocery fulfillment. Cloud-connected integration enables real-time thermal monitoring and automated customer notifications. Dark kitchen operators and grocery chains in Japan leverage these for contactless handoff in dense urban corridors where delivery labor costs constrain margins.
- Laundry Lockers:Ventilated compartments with moisture sensors accommodate garment exchange in residential complexes and hospitality settings.
- Gym Lockers:RFID-native access control supports member credential verification without staff oversight in fitness and corporate wellness facilities.
Parcel lockers lead volumes today; food lockers are gaining share fastest.
End User:
Cost tier differentiation separates high-volume logistics networks from single-site deployments with limited transaction frequency and simpler authentication requirements.
- Logistics Companies:Carrier-neutral locker networks with API-driven fleet orchestration compress failed-attempt costs and enable dynamic capacity allocation during peak demand windows. These deployments require FCC-certified wireless modules and GDPR-compliant data handling for multi-country operations.
- Retail Stores:Buy-online-pickup-in-locker configurations integrate with existing POS and inventory management systems. Curbside pickup substitution in suburban United States markets is diverting capital from locker installations where land costs permit surface parking expansion.
- Educational Institutions:Campus-wide networks support package receipt, equipment lending, and document exchange across distributed buildings.
- Corporate Offices:Biometric-enabled systems secure high-value asset custody and confidential document handoff in financial and legal services environments.
Logistics companies anchor procurement volumes; retail stores show steepest expansion trajectory as fulfillment models converge.
Technology:
Maturity curves separate established contactless methods from biometric segments facing regulatory fragmentation across authentication data storage mandates.
- IoT-Based:Continuous sensor telemetry and remote firmware management enable predictive maintenance and real-time occupancy optimization. Cloud-native platforms prioritize these modules for fleet-wide visibility across distributed installations.
- RFID:Contactless authentication reduces per-transaction processing time to under 10 seconds, enabling high-throughput deployments in transit hubs and corporate campuses. European postal operators favor RFID-native hardware architectures for interoperability with existing credential systems.
- QR Code:Smartphone-driven access eliminates credential issuance costs for low-security, high-volume use cases.
- Biometric:Facial recognition and fingerprint modules occupy premium margin pools in corporate security applications. GDPR biometric storage requirements impose encryption infrastructure costs that deter small-format deployments in rural postal networks.
RFID dominates transaction volumes today; biometric segments climb the fastest despite regulatory headwinds.
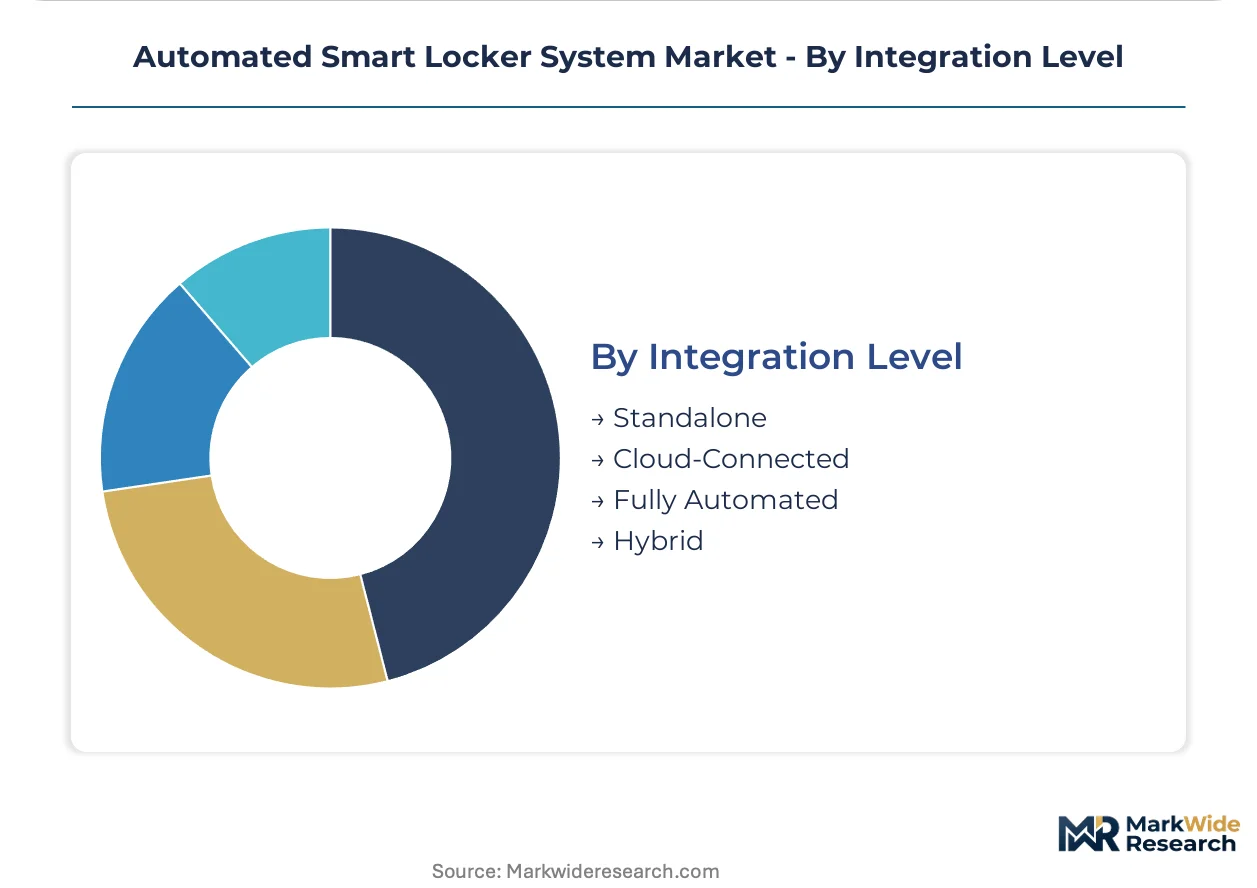
Integration Level:
Application depth varies from isolated units requiring manual inventory reconciliation to fully automated systems synchronizing with upstream warehouse management platforms.
- Cloud-Connected:API-accessible locker management enables remote monitoring, dynamic pricing, and third-party carrier reservations through standardized protocols. Municipal procurement specifications in Berlin and Tokyo now mandate open-network APIs that displace single-operator exclusivity.
- Fully Automated:Direct WMS integration with automated cell allocation algorithms sizes items against available compartment geometry in real time, eliminating manual pre-sorting at consolidation hubs.
- Standalone:Localized control without network dependency suits deployments with limited IT infrastructure or intermittent connectivity.
- Hybrid:Mixed architectures combine cloud oversight with offline transaction capability for redundancy in critical infrastructure settings.
Cloud-connected systems lead new deployments today; fully automated configurations are gaining share fastest as logistics operators consolidate platform architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's logistics corridor density is driving automated locker deployment across residential and transit infrastructure. Parcel volume saturation in Berlin, Munich, and Hamburg is forcing property managers to install carrier-neutral networks as standard amenities.
Germany
Last-mile consolidation centers in Berlin and Frankfurt require automated handoff infrastructure to manage e-commerce fulfillment density. CE marking and GDPR compliance shape hardware authentication and data retention protocols for biometric-enabled deployments. Bavaria's industrial corridor anchors manufacturing scale for modular locker chassis supplying European postal operators.
United States
Multi-tenant residential complexes in New York, Los Angeles, and Chicago are installing parcel lockers to replace overwhelmed concierge services. FCC certification governs wireless communication modules with 14-18 week approval timelines delaying pilot-to-scale transitions. The Pacific Northwest corridor concentrates cloud-native platform development for API-driven fleet orchestration.
Japan
Dark kitchen operators and grocery chains in Tokyo and Osaka deploy temperature-controlled food lockers for contactless urban handoff. METI standardization initiatives mandate interoperability protocols reducing friction for multi-operator networks. The Kansai industrial belt supplies RFID-native hardware architectures optimized for sub-10-second transaction processing.
India
Tier-1 metro residential complexes in Mumbai, Bangalore, and Delhi-NCR are importing locker systems through BIS electronics safety certification pathways. The national electronics regulator's public access equipment standards create regulatory on-ramps for foreign hardware vendors. Maharashtra's logistics parks anchor pilot deployments for pharmaceutical cold-chain custody applications.
United Kingdom
Transit authorities in London and Manchester now require open-network APIs in municipal procurement specifications displacing single-operator exclusivity. The EU AI Act's transparency mandates for biometric algorithm disclosures favor established data governance frameworks. The Southeast corridor concentrates corporate campus deployments for high-value asset custody applications.
Automated Smart Locker System Market Key Industry Players
Strategic partnerships dominate the current landscape as hardware vendors align with cloud platform specialists to compress deployment cycles. The vendor base fragments across manufacturing scale, IoT platform specialization, and RFID-native hardware architectures. Three archetypes define positioning: chassis fabricators with logistics relationships, software-layer specialists with API ecosystems, and European-access providers with compliance-native frameworks. Consolidation pressure is accelerating through carrier-neutral network mandates and municipal procurement specification shifts.
Among manufacturing-scale fabricators, Cuboid Industries occupies a position representing chassis production depth for dense urban corridor deployment. Velocity Smart Technology exemplifies the IoT platform specialization archetype with cloud-native fleet management capabilities. Gantner anchors the European-access tier with RFID-native hardware architectures aligned to postal operator interoperability requirements.
| Leading Market Players |
|---|
| Cuboid Industries |
| Parzelo |
| Velocity Smart Technology |
| Omnic |
| Sfinx Inside |
| uPOD Lockers |
| trakc |
| Gantner |
| BACE |
| Others |
Cost & Logistics Intelligence
Sheet metal input costs for modular locker chassis fabrication fluctuate with construction sector demand cycles, compressing gross margins on fixed-price municipal contracts and forcing tier separation between high-volume logistics operators and small-format rural deployments.
Pricing Analysis
Distributor margins on cloud-connected locker systems stratify across premium, standard, and economy tiers based on authentication complexity and API integration depth. Price differentiation hinges on FCC certification grade for US wireless modules and GDPR-compliant encryption infrastructure for European biometric deployments. Pricing pressure stems from curbside pickup substitution diverting capital in suburban US markets where land costs permit surface parking expansion. Logistics companies exhibit lowest price sensitivity due to failed-attempt cost savings, while rural postal networks face acute budget constraints.
Supply Chain Analysis
Steel and aluminum sheet supply rests on German, Chinese, and Japanese metal fabrication clusters serving modular chassis production. Electronic control modules draw from Taiwanese semiconductor foundries and South Korean memory suppliers. Single-source vulnerability concentrates in FCC-certified wireless communication chipsets with 14-18 week approval timelines. Distribution runs through logistics operator direct procurement for carrier-neutral networks and property developer bulk purchasing for residential amenity installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automated smart locker systems depends on software-layer service attach rates rising above hardware commoditization pressure, with pharmaceutical cold-chain custody and API-driven fleet orchestration commanding premium pricing.
For Market Incumbents: Lock in carrier-neutral network contracts through open-API platform investments before municipal procurement specifications in Berlin and Tokyo fragment deployments across multiple hardware vendors. Prioritize backward integration into RFID-native hardware architectures to defend against IoT platform specialists eroding authentication module margins. Accelerate GDPR-compliant data governance frameworks to maintain European market access against Asian competitors facing EU AI Act transparency mandates. For New Entrants and Emerging Players: Municipal transit authorities represent the most penetrable channel partner type for carrier-neutral locker networks with standardized reservation protocols. Target pharmaceutical cold-chain custody applications in India through BIS electronics safety certification pathways, where tier-1 metro hospital outpatient networks lack temperature-controlled infrastructure. Lead with API-driven fleet orchestration software to bypass capital-intensive chassis fabrication scale disadvantages. For Investors and Strategic Acquirers: Consolidation pressure builds where carrier-neutral network mandates fragment deployment contracts and compress standalone hardware vendor margins. Long-term viability favors software-layer specialists with established logistics operator relationships over chassis fabricators facing input cost volatility. Watch METI standardization initiative adoption rates across Japanese urban corridors as inflection indicator for multi-operator network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | API-driven fleet orchestration enables dynamic capacity allocation across carrier networks during peak demand windows. |
| RFID-Native Hardware Specialization | Sub-10-second transaction processing secures high-throughput deployments in European postal operator networks. |
| Pharmaceutical Cold-Chain Certification | Temperature-controlled locker cells with continuous IoT monitoring open prescription fulfillment contracts with hospital networks. |
| Regulatory Compliance Investment | GDPR biometric storage encryption and FCC modular certification reduce deployment friction in multi-country operations. |
| Carrier-Neutral Network Partnership | Open-API municipal procurement specifications in Berlin and Tokyo displace single-operator exclusivity arrangements. |
Research Approach
Direct dialogue with logistics operators, property developers, municipal transit authorities, and cloud platform engineers combined with secondary validation from FCC certification databases, METI standardization documents, GDPR implementation guidelines, and BIS electronics safety circulars. Bottom-up and top-down triangulation cross-referenced hardware shipment data against logistics operator capital expenditure disclosures and municipal procurement records.
Bottom-up modeling aggregated unit economics across product type, integration level, and authentication technology segments, while top-down analysis calibrated aggregate market size against e-commerce fulfillment volume growth and last-mile infrastructure investment trends across the analysis window. Segmentation dimensions included payload sensitivity, connectivity depth, and geographic regulatory cluster. CAGRs derived from logistic operator deployment pipeline visibility and property manager amenity installation surveys.
Revisions become necessary when steel and aluminum input volatility exceeds historical construction sector correlation patterns, or when curbside pickup substitution accelerates beyond current suburban US market penetration assumptions. A small set of named triggers warrants ongoing watch: FCC certification timeline extensions, EU AI Act biometric algorithm disclosure enforcement severity, and India BIS certification pathway processing efficiency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Canada Access Control Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Smart Entry System Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Access Control Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Electronic Cylinder Lock Credentials Market