
 North America Proximity Access Control Market | 2026-2036
North America Proximity Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
North America Proximity Access Control Market Insights
FIPS 201-compliant PIV credentialing is redrawing procurement standards across federal and enterprise buyers. HID Global Corporation leverages its embedded position in government credentialing infrastructure to sustain long-term contract visibility. Allegion plc anchors commercial real estate channels through specialized hardware distribution. Johnson Controls International plc competes by integrating access control into broader building management platforms.
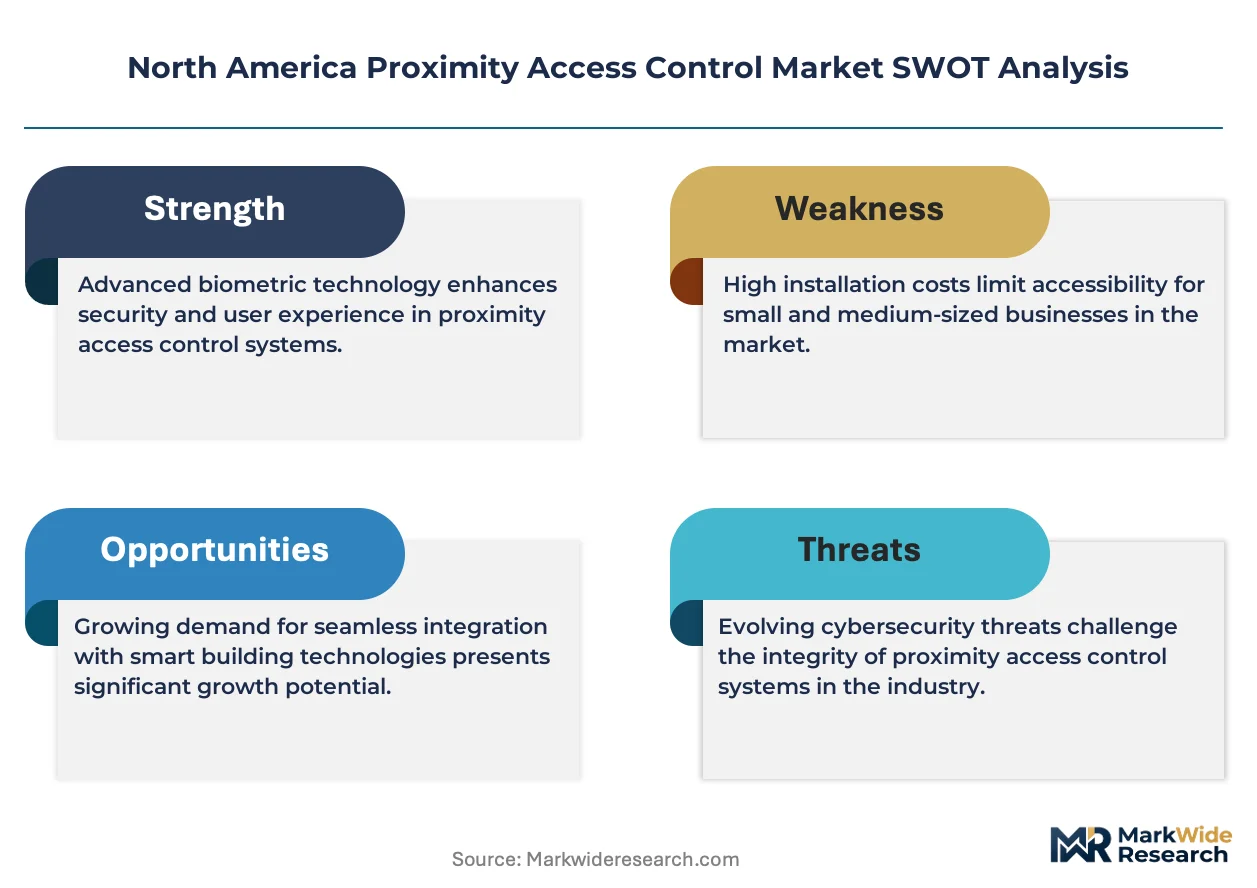
North America proximity access control encompasses credential readers, biometric capture devices, and authentication software operating on radio-frequency or contactless protocols, typically within 10-centimeter read ranges, designed to verify identity and manage physical entry permissions. The primary commercial purpose centers on replacing mechanical key systems with auditable, revocable electronic credentials that integrate with workforce and visitor management databases. Biometric sensors command premium positioning as organizations replace card-only systems with multi-factor authentication at high-security entry points. Cloud-based installation types are expanding fastest among mid-market commercial adopters seeking centralized credential administration across distributed sites.
NIST guidelines, FICAM standards, and state-level biometric privacy laws in Illinois and Texas shape product certification requirements and deployment protocols for vendors serving government and regulated industries. The Federal Risk and Authorization Management Program creates compliance gatekeeping that favors pre-authorized platform providers. Stakeholders must monitor evolving state biometric consent statutes and federal zero-trust architecture mandates to anticipate credential technology refresh cycles.
Market Dynamics
Federal zero-trust architecture mandates and FICAM credentialing standards are compressing procurement cycles across government and enterprise buyers, forcing hardware refresh decisions toward multi-factor biometric systems.
Growth Catalysts
- FICAM-compliant credentialing:Federal agencies across the United States face mandatory PIV card deployment deadlines, creating sustained demand for compatible reader infrastructure and authentication middleware.
- Smart building retrofits:Commercial real estate developers in California and Texas are bundling proximity access with HVAC and lighting controls to capture utility incentives and tenant premium pricing.
- Biometric sensor maturation:Fingerprint and facial recognition modules have reached cost parity with high-frequency card readers, enabling multi-factor deployments at mid-market price points.
Market Restraints
- Semiconductor supply concentration:RFID chip fabrication concentrates in East Asian foundries, exposing reader manufacturers to lead time volatility and tariff exposure.
- Biometric privacy litigation risk:Illinois BIPA and Texas biometric consent statutes impose per-violation damages that deter deployment in retail and hospitality settings.
- Legacy credential lock-in:Enterprises with embedded 125 kHz proximity card infrastructure face high switching costs to migrate encrypted credential formats.
Strategic Opportunities
- Canadian federal modernization:Government of Canada facilities lag US FICAM adoption by several years, creating a trailing-edge replacement market for PIV-interoperable systems.
- Mobile credential convergence:Bluetooth Low Energy and NFC wallet integration enables smartphone-based access, bypassing physical card distribution costs for distributed workforces.
- State-level cybersecurity grants:US Infrastructure Investment and Jobs Act funding flows to municipal and educational institutions for physical security hardening against targeted intrusion.
Industry Challenges
- FIPS 140-2 certification timelines:Cryptographic module validation for federal deployments extends 12-18 months, compressing vendor revenue recognition windows.
- Interoperability testing burden:Multi-vendor credential ecosystems require continuous conformance verification against SP 800-116 guidelines, straining quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Proximity Access Control Market |
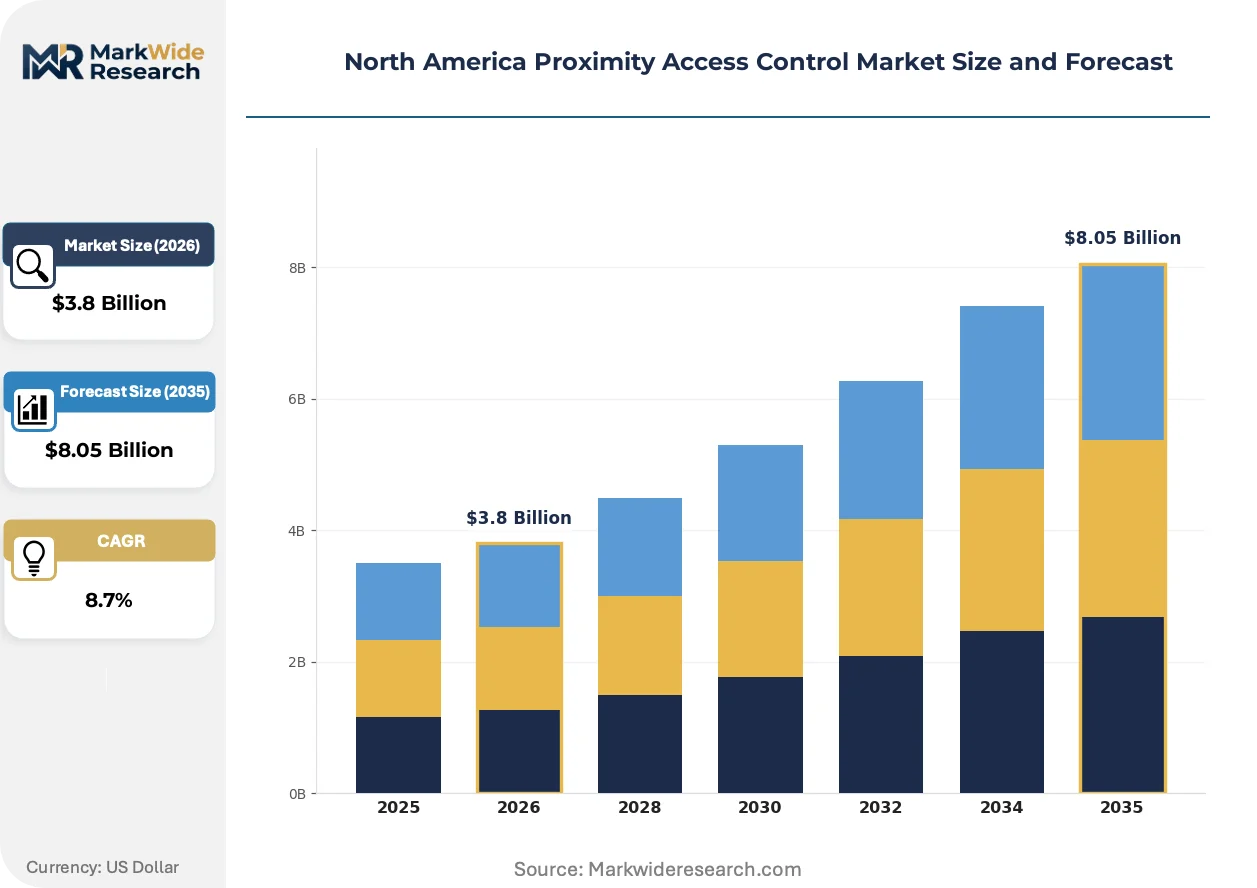
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card Readers, Biometric Sensors, Keypad Systems, Software Solutions Technology: RFID, NFC, Biometric Recognition, Bluetooth End User: Commercial Spaces, Educational Institutions, Government Facilities, Healthcare Installation Type: On-premises, Cloud-based, Hybrid, Mobile |
| Companies Covered | Johnson Controls International plc, Identiv Inc., HID Global Corporation, Suprema Inc., dormakaba Holding AG, ASSA ABLOY Group, Honeywell International Inc., Genetec, Allegion plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Proximity Access Control Market Trends and Innovations
Credential technology is bifurcating between high-assurance federal deployments and frictionless commercial experiences, with cloud-native architectures enabling centralized policy management across distributed estates.
Contactless fingerprint sensors with liveness detection are displacing card-only readers at high-security federal checkpoints and financial services data centers. Defense contractors and cleared facilities are accelerating adoption to meet CMMC 2.0 physical access control requirements. This displacement is compressing the installed base of legacy proximity-only hardware and redirecting maintenance contract value toward biometric-enabled platforms.
NIST SP 800-207 zero-trust architecture guidance now explicitly mandates continuous verification for physical entry points, binding credential validation to real-time identity risk scoring. Federal civilian agencies are re-specifying access control procurement to require PIV-derived credentials with backend attribute verification. The policy shift most affects enterprise vendors serving hybrid federal-commercial accounts, who must dual-track product roadmaps to maintain compliance eligibility.
Mid-market commercial buyers are consolidating vendor relationships around integrated building management platforms rather than standalone access control systems. Facility managers in Texas and California are selecting providers based on API depth and cloud dashboard functionality, not hardware specifications alone. This preference shift is most visible in multi-site healthcare and higher education verticals, where credential administration across dozens of buildings previously required on-premises server infrastructure.
North America Proximity Access Control Market Segmentation
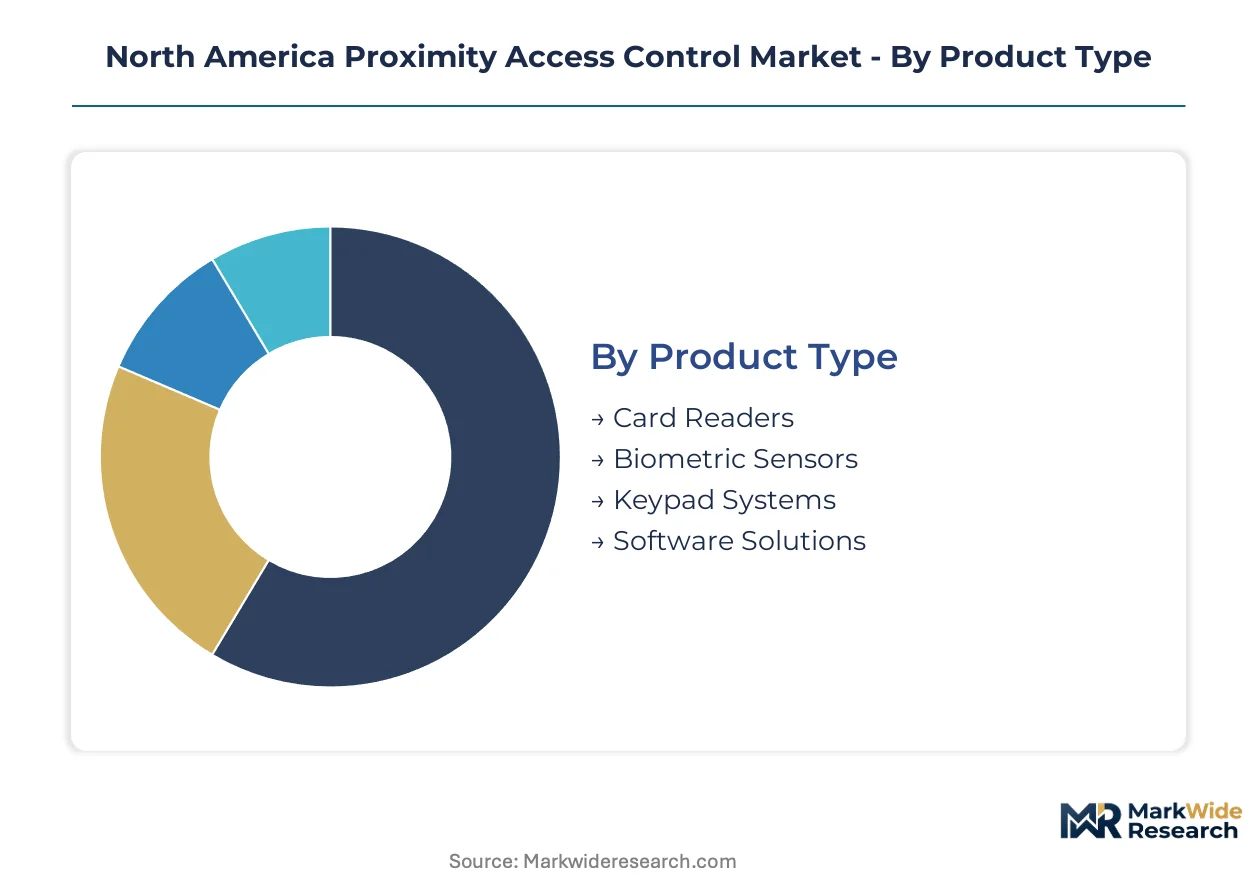
Segmentation in proximity access control reveals how procurement standards diverge between federal compliance mandates and commercial convenience priorities. Vendors must architect product lines that simultaneously satisfy FICAM credentialing for government buyers and frictionless mobile experiences for enterprise campuses.
Product Type:
FIPS 201 compliance requirements and biometric privacy statutes in Illinois and Texas create divergent certification burdens across hardware categories.
- Card Readers:Legacy 125 kHz and encrypted 13.56 MHz contactless readers remain the volume backbone for commercial real estate retrofits. Demand concentrates in Texas and California multi-tenant office buildings where property managers prioritize card reissuance efficiency over biometric enrollment complexity.
- Biometric Sensors:Contactless fingerprint modules with liveness detection and facial recognition terminals are displacing card-only systems at federal checkpoints and financial data centers. Procurement in cleared facilities accelerates under CMMC 2.0 physical access mandates, compressing deployment timelines for defense contractors.
- Keypad Systems:PIN-entry devices persist as backup authentication and standalone solutions for low-security utility rooms and secondary entrances.
- Software Solutions:Credential management platforms and visitor registration systems integrate with HR databases and physical security information management consoles.
Card readers handle the majority of throughput; biometric sensors are expanding most quickly on share.
Technology:
Cost tiers separate legacy radio-frequency implementations from emerging credential formats that bypass physical card distribution entirely.
- RFID:Passive 13.56 MHz ISO 14443 credentials dominate federal PIV deployments and enterprise high-frequency card systems. Manufacturing concentration in East Asian foundries exposes reader vendors to semiconductor lead time volatility.
- NFC:Near-field communication enables smartphone wallet integration and tap-to-access experiences for commercial adopters seeking to eliminate physical card logistics.
- Biometric Recognition:Template matching algorithms for fingerprint, facial, and iris modalities command premium positioning at high-assurance entry points.
- Bluetooth:Bluetooth Low Energy beacon technology supports hands-free mobile credentialing across extended read ranges for parking garages and campus perimeter gates.
RFID maintains the largest installed base; Bluetooth is climbing the fastest on adoption velocity.
End User:
Application context determines whether procurement prioritizes audit trails, visitor throughput, or infection-control contactless protocols.
- Commercial Spaces:Corporate campuses and multi-tenant office buildings drive cloud-based credential administration demand. Texas and California property developers bundle access control with smart building HVAC and lighting integrations to capture utility incentives.
- Government Facilities:Federal civilian agencies and military installations mandate PIV-compatible infrastructure under FICAM standards, compressing procurement toward pre-authorized vendor lists.
- Healthcare:Hospitals and clinic networks prioritize contactless biometric workflows to reduce surface transmission risks and integrate with patient management systems.
- Educational Institutions:Universities and K-12 districts seek centralized credential administration across distributed dormitory, classroom, and athletic facilities.
Commercial spaces generate the highest transaction volume; government facilities impose the strictest compliance thresholds.
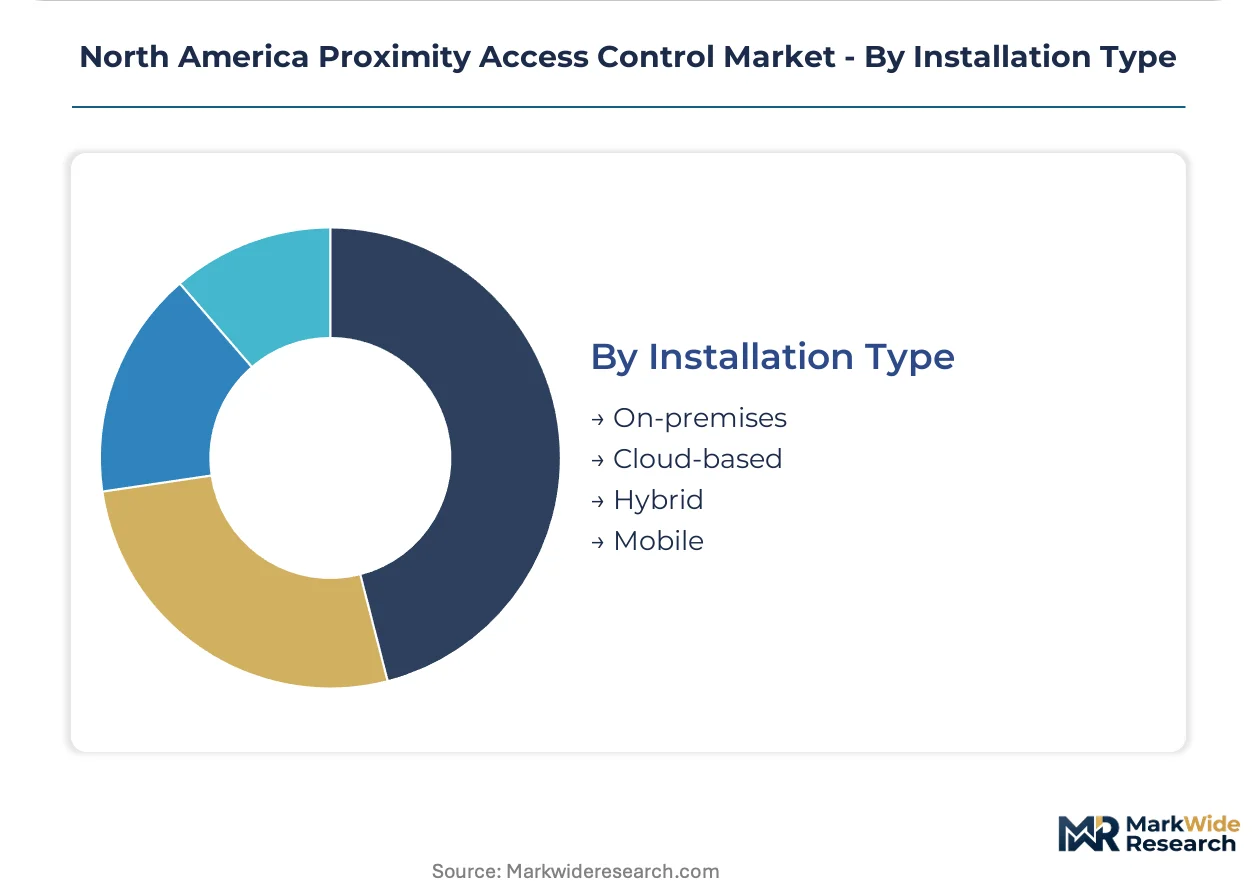
Installation Type:
Customer type and IT maturity dictate whether organizations retain on-premises control or delegate infrastructure to cloud-native platforms.
- Cloud-based:Mid-market commercial adopters across distributed retail and healthcare sites select browser-administered platforms to eliminate server maintenance overhead. API depth and dashboard functionality drive vendor selection more than hardware specifications.
- On-premises:Defense contractors and cleared facilities maintain air-gapped credential databases to satisfy CMMC 2.0 and NIST 800-171 boundary protection requirements.
- Hybrid:Large enterprises with mixed security zones deploy cloud-managed readers with local credential caching for continuity during network outages.
- Mobile:Smartphone-native credentialing via BLE and NFC wallet integration bypasses physical card distribution for remote and hybrid workforces.
On-premises architectures retain dominance in high-security verticals; cloud-based deployments are gaining share fastest among mid-market commercial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proximity access control hardware and software flows across North America reflect divergent federal procurement timelines and commercial real estate development cycles. Canada imports advanced biometric sensor modules from US defense contractors while exporting cloud-native credential management platforms to mid-market American buyers.
United States
Federal zero-trust mandates and FICAM credentialing deadlines drive PIV-compatible reader deployments across civilian agencies and military installations. NIST cybersecurity frameworks tighten authentication requirements for contractors serving cleared facilities. Demand clusters in California's smart building corridors and Texas federal facility upgrades, where property developers bundle access control with utility incentive programs.
Canada
Government of Canada facilities trail US FICAM adoption by several years, creating replacement demand for PIV-interoperable systems in Ottawa and Toronto federal complexes. Health Canada guidelines shape biometric privacy protocols for healthcare deployments. Ontario and Quebec commercial real estate developers are accelerating cloud-based credential administration across multi-site healthcare and educational portfolios.
Mexico
Manufacturing foreign direct investment in Nuevo León and Baja California generates demand for workforce access control at automotive and electronics assembly plants. Mexican federal security standards for critical infrastructure facilities are tightening credential authentication requirements. Guadalajara's technology corridor attracts cloud-native platform providers seeking nearshore service delivery for US mid-market accounts.
North America Proximity Access Control Market Competitive Landscape
Concentration sits with diversified building technology conglomerates and specialized physical security vendors competing across federal compliance and commercial convenience segments. The vendor base spans three tiers: integrated building management platforms, credential hardware specialists, and cloud-native software providers. Strategic moves center on API ecosystem expansion and biometric sensor portfolio diversification to capture zero-trust architecture refresh cycles.
Within the federal-credentialing tier, HID Global Corporation and Johnson Controls International plc exemplify divergent approaches to compliance-heavy procurement. HID Global occupies a position anchored in government credentialing infrastructure, while Johnson Controls exemplifies building management platform integration. Allegion plc represents the commercial real estate channel specialization, with hardware distribution networks serving multi-tenant property managers.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Identiv Inc. |
| HID Global Corporation |
| Suprema Inc. |
| dormakaba Holding AG |
| ASSA ABLOY Group |
| Honeywell International Inc. |
| Genetec |
| Allegion plc |
| Others |
Pricing and Supply Chain Analysis
Contactless biometric modules replacing legacy card-only readers are redrawing procurement economics across federal and commercial verticals, compressing hardware margins while concentrating premium pricing power with FIPS 201-certified vendors who control cryptographic validation pipelines.
Pricing Analysis
Federal buyers anchor pricing stratification across premium, standard, and economy tiers, with FIPS 140-2 certification commanding substantial premiums over commercial-grade alternatives. Price differentiation rests on NIST validation status and biometric liveness detection capability, not hardware specifications alone. Cost compression in mid-market card reader segments is intensifying because Bluetooth Low Energy and NFC wallet integration commoditize physical credential distribution. Municipal and educational institutions exhibit highest price sensitivity; cleared defense contractors demonstrate least sensitivity due to CMMC 2.0 compliance mandates.
Supply Chain Analysis
Strategic stockpiling of RFID chipsets has supplanted just-in-time procurement as lead time volatility from East Asian foundries forces reader manufacturers to carry 6-9 month component buffers. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with passive 13.56 MHz ISO 14443 modules drawing from concentrated wafer supply. Supply chains rest on silicon wafer, ferrite antenna substrate, and cryptographic secure element inputs. Single-source vulnerability around advanced biometric sensor ASICs exposes vendors to allocation constraints. Distribution runs through specialized physical security integrators and building automation OEM channels rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern vendor viability as API depth and cloud-native credential administration displace hardware specifications in procurement decisions, with FICAM interoperability emerging as the decisive ecosystem gate.
For Market Incumbents: Secure federal contract visibility by accelerating FIPS 201 middleware certification timelines against compressed NIST validation windows. Deepen backward integration into biometric sensor module production to offset East Asian semiconductor allocation risk. Consolidate channel position through exclusive distribution agreements with top-ten commercial real estate developers in Texas and California smart building corridors. For New Entrants and Emerging Players: Lead with mobile credential convergence targeting mid-market healthcare and higher education verticals where cloud-based administration eliminates on-premises server infrastructure requirements. Canadian federal modernization lags US FICAM adoption by several years, creating a trailing-edge replacement market with lower certification barriers. Pursue API-first go-to-market positioning that embeds access control data into broader building management dashboards. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed credential hardware specialists lacking cloud-native software platforms. Long-term viability hinges on recurring SaaS revenue attachment rates rather than transactional reader sales. Monitor state-level biometric consent statute evolution in Illinois and Texas as signal for litigation risk exposure that could redirect capital toward privacy-compliant facial recognition alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| FIPS 201 Middleware Certification | NIST validation unlocks federal procurement pipelines and enterprise hybrid deployments. |
| Biometric Sensor Portfolio Expansion | Contactless fingerprint modules with liveness detection capture CMMC 2.0 compliance demand. |
| Cloud-Native Platform Migration | Browser-administered credential management displaces on-premises server infrastructure in mid-market accounts. |
| API Ecosystem Development | Integration depth with HVAC and lighting controls drives smart building bundling decisions in California and Texas. |
| Mobile Credential Convergence | BLE and NFC wallet integration eliminates physical card logistics for distributed hybrid workforces. |
Research Methodology
Initial hypotheses were tested against primary input from federal security directors, commercial real estate technology officers, biometric sensor procurement leads, and physical security integrators and refined through secondary validation against NIST SP 800-116 conformance documentation, FICAM implementation guidelines, SEC 10-K filings from diversified building technology conglomerates, and state legislative databases tracking biometric privacy statute evolution. Bottom-up triangulation across installed base estimates and top-down cross-check against federal procurement disclosure records anchored volume and value assessments.
Variance decomposition across technology substitution curves, compliance deadline acceleration effects, and regional smart building incentive programs shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include credential format, authentication modality, deployment architecture, end-use vertical, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to federal mandate compliance schedules and commercial retrofit cycle data. Industry-specific forecast inputs incorporated FICAM credentialing deadline enforcement variance and semiconductor foundry capacity allocation announcements.
The analysis sits within stated boundaries; outcomes outside sustained federal zero-trust architecture funding or prolonged East Asian semiconductor supply disruption would require recalibration. Forecasts reflect assumptions around NIST guideline stability and state biometric consent statute enforcement intensity. Revision becomes warranted when FIPS 140-2 certification timeline delays cross 24-month thresholds or when mobile credential adoption rates in commercial verticals exceed modeled diffusion parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
US Access Control Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Locks Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Programmable Safety Systems Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Asia-Pacific Proximity Access Control Market