
 Europe Pin-Based Access Control Market | 2026-2036
Europe Pin-Based Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pin-Based Access Control Market Insights
Buyer concentration among commercial property portfolios is expanding across Northern Europe as real estate investment trusts consolidate office holdings. Johnson Controls leverages its building automation integration to capture bundled security contracts. Dormakaba Group anchors its position through specialized electronic lock manufacturing for high-traffic commercial environments. Bosch Security and Safety Systems differentiates via channel control across German-speaking markets.
Pin-based access control denotes credential verification systems where users authenticate through numeric codes entered on electromechanical keypads, typically operating on 12-24V DC power with IP65-rated enclosures for exterior mounting. These systems restrict entry to residential buildings, commercial offices, educational institutions, and healthcare facilities by validating codes against stored permissions in local or networked controllers. Standalone keypads retain dominance in cost-sensitive retrofits, while cloud-based solutions represent the fastest-expanding technology segment as facility operators seek centralized credential management. Smart card integration occupies the premium tier where multi-factor authentication commands higher margins.
CE marking under the EU's Radio Equipment Directive and EN 50133 alarm system standards govern product compliance across member states, with ECHA REACH regulations constraining hazardous substance use in keypad housings. Germany's KBA and France's ANSM do not directly regulate this sector, but national building codes in both countries mandate fire-safety integration for electronic access devices. Stakeholders must monitor evolving EU cybersecurity certification schemes that will soon require third-party assessment for networked access controllers.
Market Dynamics
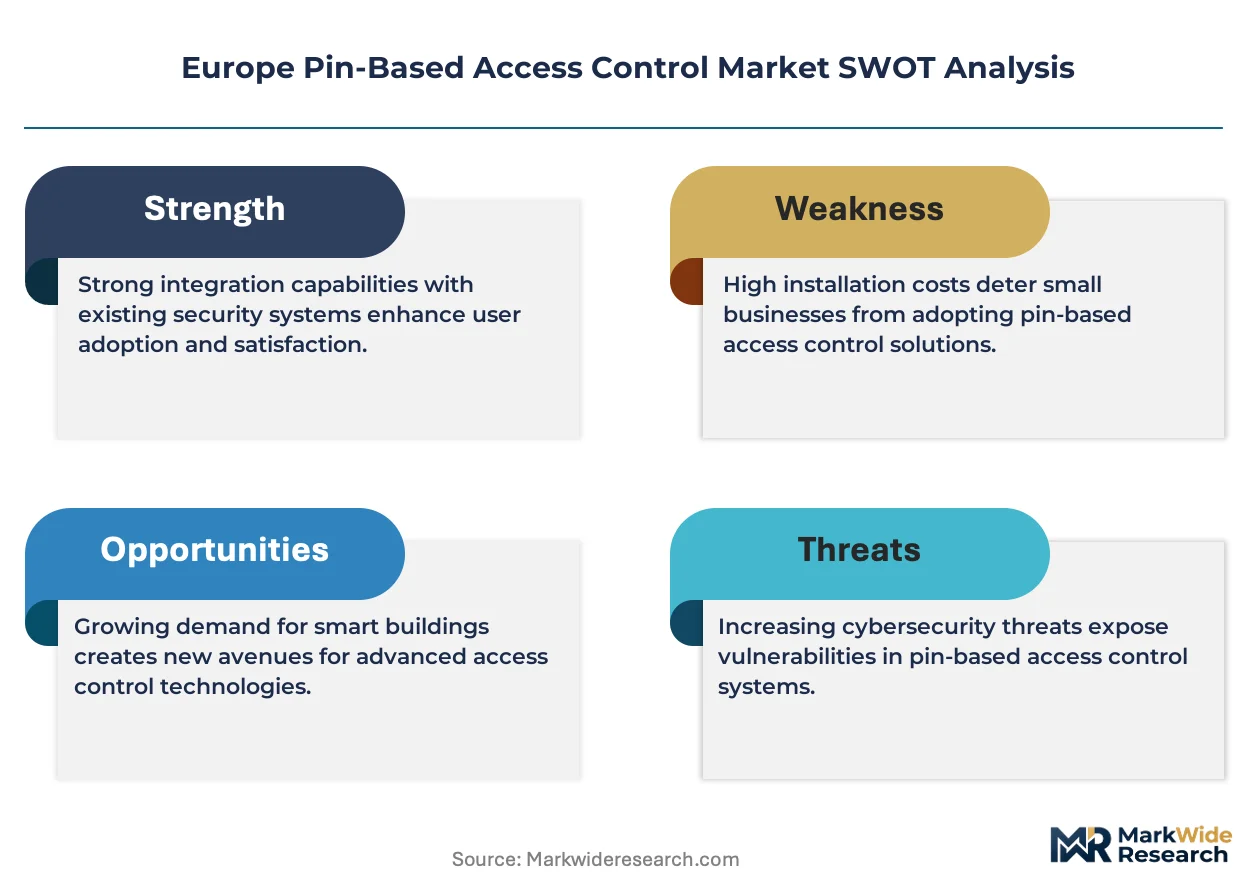
Commercial real estate consolidation across Northern Europe is compressing replacement cycles for legacy mechanical locks, while the EU's Cybersecurity Act mandates third-party assessment for networked controllers, elevating compliance costs for market participants.
Growth Catalysts
- EN 50133 Alarm System Standards:Mandatory fire-safety integration requirements under German and French building codes are forcing property managers to upgrade electromechanical systems with certified electronic alternatives.
- Cloud-Based Credential Management:Facility operators across the United Kingdom and Netherlands are adopting centralized platforms that reduce on-site IT infrastructure and enable remote permission updates.
- Commercial Office Retrofits:REIT portfolio consolidation in Germany and France is standardizing access infrastructure across multi-tenant buildings, creating bundled procurement opportunities for integrated platforms.
Market Restraints
- Semiconductor Supply Concentration:Microcontroller shortages from Asian foundries are extending lead times for keypad manufacturers serving Western European markets.
- Copper and Aluminum Price Volatility:Raw material swings in wiring and housing components are compressing margins for mid-tier electromechanical producers.
- Biometric Substitution:Fingerprint and facial recognition systems are capturing premium installations in high-security healthcare and financial services environments.
Strategic Opportunities
- Polish and Romanian Commercial Construction:Greenfield office development in these underpenetrated markets offers first-mover positioning before regulatory harmonization tightens.
- EU Cybersecurity Certification Schemes:Upcoming mandatory third-party assessment for networked controllers will create compliance service revenue streams for certified integrators.
- Smart Card Convergence:Multi-factor authentication combining PIN entry with contactless credentials commands premium pricing in Dutch and Belgian government facilities.
Industry Challenges
- Cybersecurity Engineering Talent:Shortages of embedded systems security specialists are delaying firmware development cycles for networked keypad manufacturers.
- CE Marking Timeline Compression:Evolving Radio Equipment Directive interpretations are extending product certification periods, delaying market entry for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pin-Based Access Control Market |
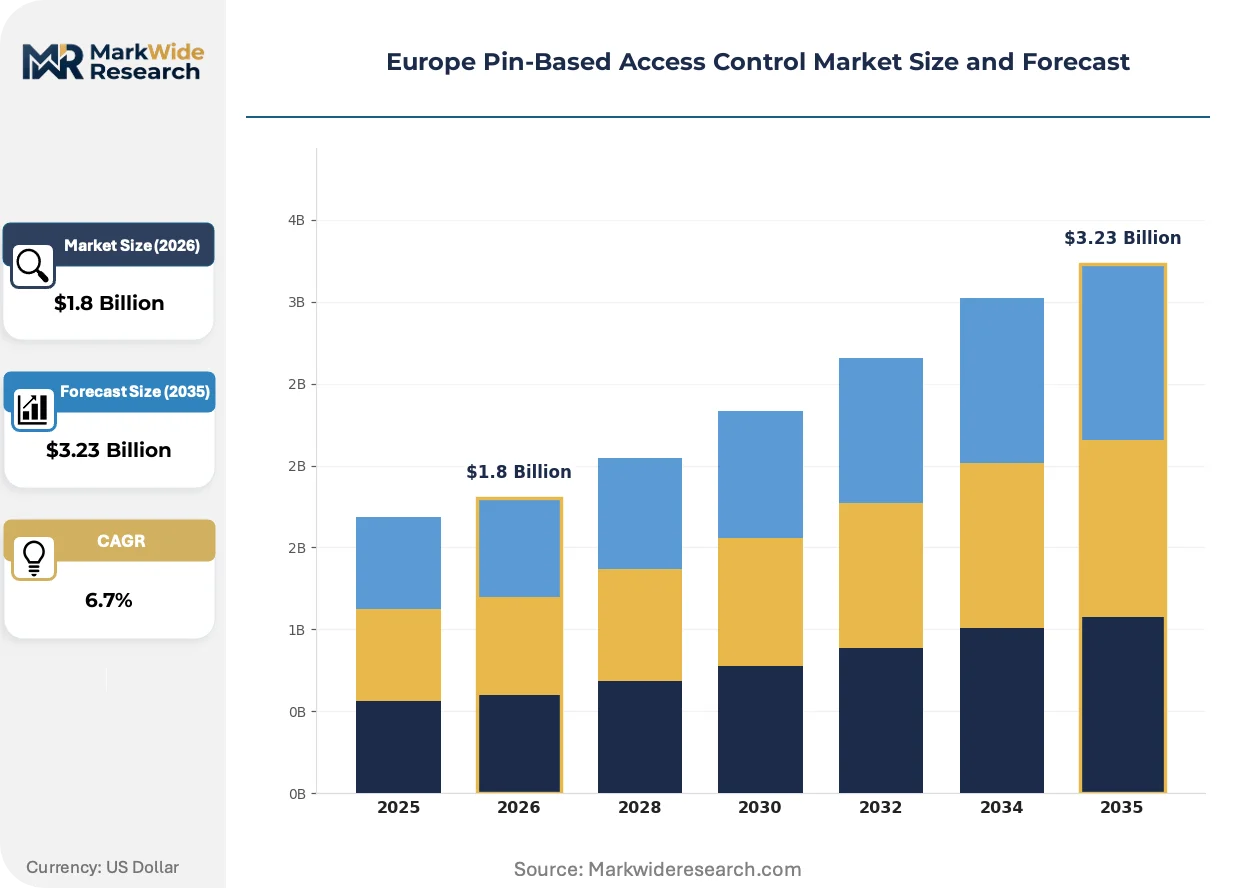
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Keypads, Mobile Unlocking Systems, Integrated Access Systems, Electronic Locks Application: Residential Buildings, Commercial Offices, Educational Institutions, Healthcare Facilities End User: Property Managers, Facility Operators, Educational Administrators, Security Personnel Technology: Wireless Technology, Fingerprint Recognition, Smart Card Integration, Cloud-Based Solutions |
| Companies Covered | Johnson Controls, HID Global Corporation, Bosch Security and Safety Systems, Honeywell International Inc, Dormakaba Group, ASSA ABLOY, Allegion, Axis Communications AB, Thales Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pin-Based Access Control Market Trends and Innovations
Three forces are actively restructuring this market: firmware-over-the-air updates are collapsing maintenance visit frequency, regulatory certification is becoming a competitive moat rather than a checkbox, and procurement centralization is shifting purchasing authority from facility managers to corporate security directors.
Bluetooth Low Energy credential handoff is rewriting how temporary access permissions are issued. Facility managers at UK logistics hubs and Dutch distribution centers are deploying smartphone-based PIN delivery to contractors and visitors, eliminating physical credential printing. This capability is compressing service revenue for traditional locksmith networks while expanding software subscription attach rates for platform vendors.
REACH regulations governing hazardous substances in keypad housings are tightening substance restrictions across EU member states. Manufacturers must reformulate polymer compounds to eliminate restricted phthalates and flame retardants, raising material costs but creating differentiation for early-compliant suppliers. German industrial buyers are now requiring full material disclosure documentation before contract award, shifting procurement criteria beyond unit price.
Corporate security directors are consolidating vendor relationships across multi-country portfolios. French and German multinational occupiers are standardizing on single-platform deployments with centralized audit logging, displacing the historical pattern of site-specific contractor selection. This concentration is visible most acutely in London and Frankfurt financial services, where compliance officers now mandate unified access event reporting for regulatory examination readiness.
Europe Pin-Based Access Control Market Segmentation
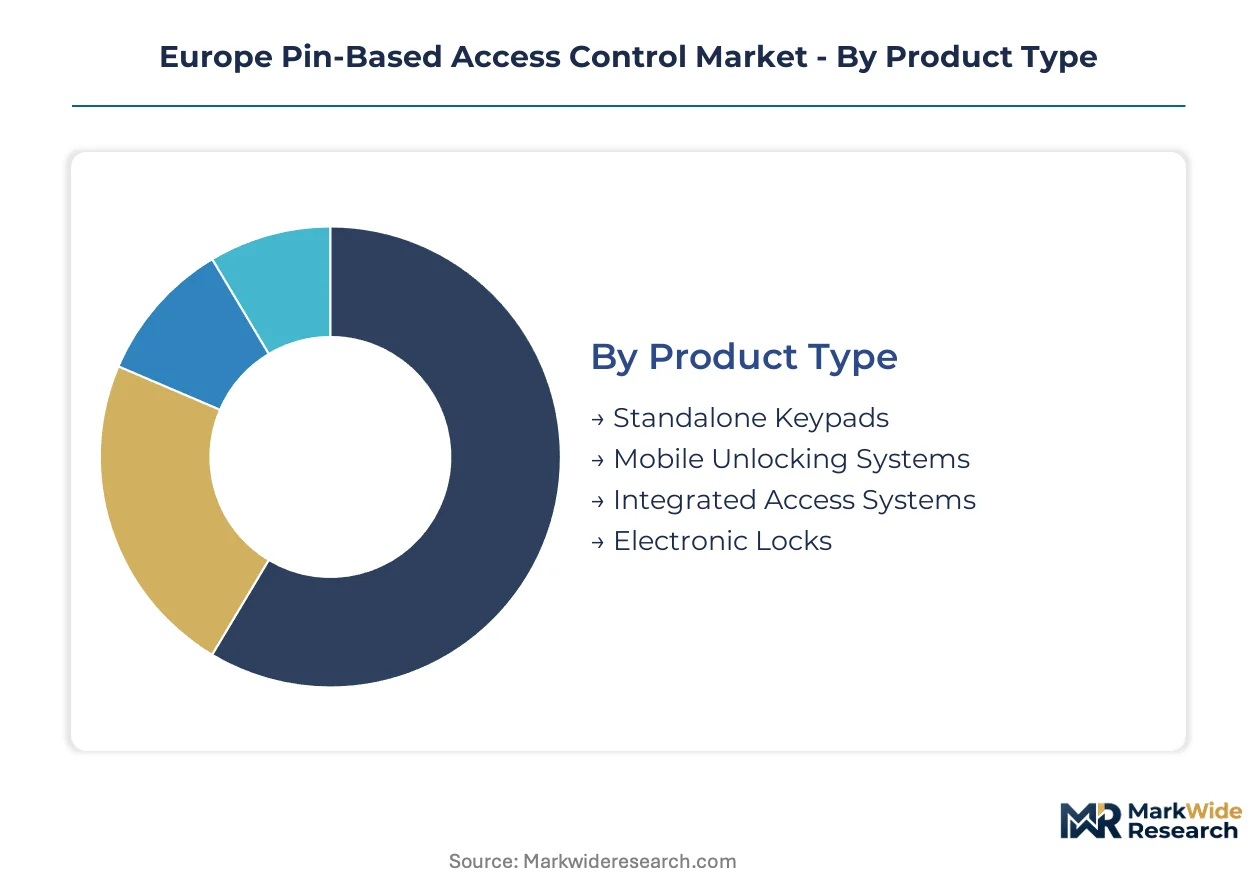
Segmentation reveals how upgrade pressures and compliance mandates distribute across product tiers, applications, and user types. Understanding these divisions helps identify where replacement cycles concentrate and which technology transitions command premium positioning.
Product Type:
Replacement cycles for legacy mechanical systems are compressing as German and French building codes mandate fire-safety integration, forcing property managers toward certified electronic alternatives.
- Standalone Keypads:Self-contained units with local credential storage and 12-24V DC power requirements dominate cost-sensitive retrofits across French residential portfolios. Electromechanical durability and IP65-rated enclosures satisfy exterior mounting demands in Northern European climates where maintenance access is limited.
- Cloud-Based Solutions:Networked controllers with centralized permission management are expanding fastest across UK and Netherlands commercial portfolios. Remote firmware updates and audit logging capabilities align with corporate security directors' demands for unified event reporting across multi-country deployments.
- Integrated Access Systems:Building automation convergence with HVAC and lighting controls commands bundled procurement contracts from consolidated REITs.
- Mobile Unlocking Systems:Bluetooth Low Energy credential handoff eliminates physical key distribution for contractor and visitor access at Dutch distribution centers.
- Electronic Locks:Motorized deadbolts with integrated PIN verification serve high-traffic commercial environments requiring rapid entry throughput.
Standalone keypads sit at the top of the volume ranking, with cloud-based solutions climbing the fastest.
Application:
Cost tier differentiation separates premium compliance-driven installations from economy retrofits where basic functionality suffices.
- Commercial Offices:Multi-tenant buildings across London and Frankfurt financial districts require audit-grade access logging for regulatory examination readiness. Johnson Controls and Dormakaba compete for standardized platform deployments across consolidated multinational portfolios.
- Healthcare Facilities:Patient safety protocols and pharmaceutical storage security drive biometric-PIN hybrid adoption in German university hospitals. Infection control requirements favor touchless credential options alongside numeric entry for staff access to restricted zones.
- Residential Buildings:French and German apartment blocks prioritize vandal-resistant keypads with weatherproofing for exterior entry points.
- Educational Institutions:Campus-wide standardization pressures in the Netherlands favor networked solutions with semester-based permission automation.
Commercial offices capture the largest installed base, while healthcare facilities gain share fastest on compliance tightening.
End User:
Procurement authority is shifting from site-level contractors to corporate security directors managing cross-border standardization.
- Property Managers:Consolidated REITs across Germany and France leverage portfolio scale for bundled security contracts with unified platform requirements. Standardized access infrastructure reduces vendor complexity across multi-tenant office holdings in Berlin and Paris business districts.
- Facility Operators:Dutch logistics hubs and UK distribution centers prioritize smartphone-based temporary credential issuance for contractor access. Operational efficiency demands drive adoption of centralized permission management with reduced on-site IT infrastructure.
- Security Personnel:Compliance officers in financial services mandate real-time event monitoring and forensic audit capabilities.
- Educational Administrators:Semester turnover automation and lost credential replacement costs favor cloud-managed solutions with remote deactivation.
Property managers dominate current procurement volume, with facility operators expanding most quickly on logistics sector growth.
Technology:
Margin structure stratifies between commodity wireless components and premium multi-factor authentication tiers.
- Smart Card Integration:Contactless credential pairing with PIN entry commands premium pricing in Belgian and Dutch government facilities. Dual-factor authentication satisfies classified area access requirements while maintaining audit trails for security clearance verification.
- Wireless Technology:WiFi and Bluetooth-enabled keypads reduce cabling costs in historic building retrofits across Italian and Spanish commercial properties. Battery-powered operation with low-power radio protocols extends deployment flexibility where electrical infrastructure modification is restricted.
- Fingerprint Recognition:Biometric-PIN hybrids capture high-security healthcare and financial installations despite higher per-unit costs.
- Cloud-Based Solutions:Subscription revenue models with firmware-over-the-air capabilities are displacing traditional hardware-only sales.
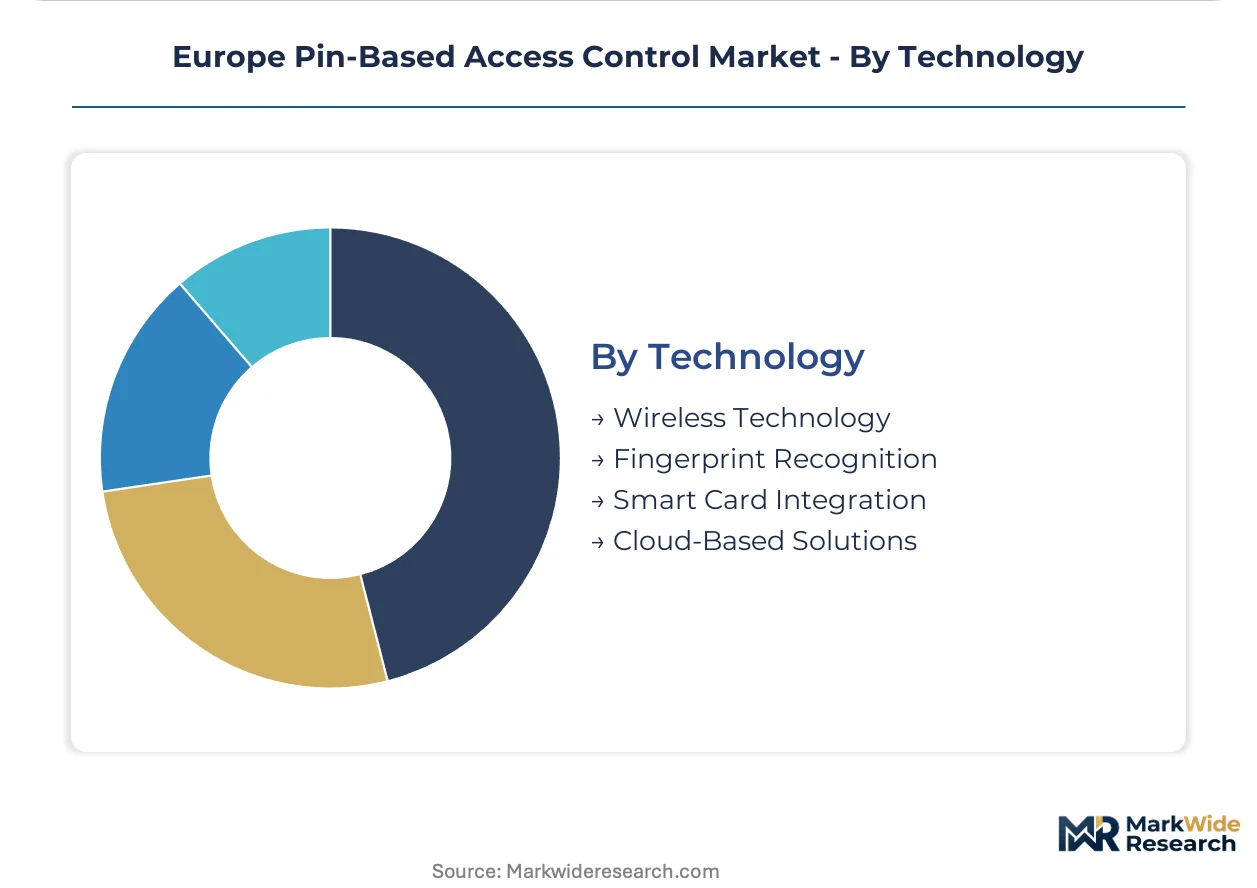
Wireless technology holds the broadest installed base, with smart card integration showing the steepest expansion trajectory on government security mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems security specialists cluster in southern Germany and the Netherlands, anchoring firmware development for networked access controllers across Western European markets.
Germany
Fire-safety integration mandates under national building codes are accelerating replacement cycles for legacy mechanical locks in Berlin and Frankfurt commercial portfolios. The KBA maintains indirect oversight through vehicle-related security standards that influence electronic locking device specifications. Bavaria's industrial corridor hosts concentrated manufacturing of IP65-rated keypad enclosures serving Northern European climate demands.
United Kingdom
Corporate security directors in London financial services mandate unified access event reporting for regulatory examination readiness. GDPR compliance requirements shape data handling protocols for cloud-based credential management platforms. The Midlands logistics hub drives smartphone-based temporary credential issuance for contractor access at distribution centers.
Netherlands
Campus-wide standardization pressures in Dutch educational institutions favor networked solutions with semester-based permission automation. REACH regulations governing hazardous substances in keypad housings tighten substance restrictions across polymer compounds. The Randstad metropolitan cluster concentrates demand for Bluetooth Low Energy credential handoff in logistics and commercial office developments.
France
ANSM oversight of healthcare facility security protocols drives biometric-PIN hybrid adoption in Paris and Lyon university hospitals. National building codes mandate certified electronic alternatives for electromechanical systems in multi-tenant residential blocks. Île-de-France anchors REIT portfolio consolidation creating bundled procurement opportunities for integrated access platforms.
Poland
Greenfield office development in Warsaw and Kraków offers first-mover positioning before EU regulatory harmonization tightens baseline requirements. CE marking under the Radio Equipment Directive governs product compliance for imported electronic locking devices. The country's construction sector expansion concentrates demand for cost-sensitive standalone keypad retrofits in emerging commercial zones.
Europe Pin-Based Access Control Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Building automation integrators leverage bundled security contracts against specialized electronic lock manufacturers. Three archetypes dominate: diversified industrial conglomerates with building systems portfolios, pure-play security specialists with channel depth, and component-scale manufacturers with cost-optimized production. Competitive moves center on strategic partnerships for technology convergence and geographic expansion into underpenetrated Central European markets.
Among diversified building systems providers, Johnson Controls exemplifies the integrated platform archetype through its automation convergence capabilities. Dormakaba Group occupies a specialist position anchored in high-traffic commercial environment expertise. Bosch Security and Safety Systems represents channel control differentiation across German-speaking markets. These three companies illustrate how competitive positioning stratifies between bundled procurement appeal and specialized application focus.
| Leading Market Players |
|---|
| Johnson Controls |
| HID Global Corporation |
| Bosch Security and Safety Systems |
| Honeywell International Inc |
| Dormakaba Group |
| ASSA ABLOY |
| Allegion |
| Axis Communications AB |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EN 50133-compliant networked controllers and basic standalone keypads manifests in divergent margin structures and supplier qualification requirements across European procurement channels. Premium-tier manufacturers command pricing power through third-party cybersecurity assessment capabilities, while commodity producers compete on unit economics constrained by raw material volatility and Asian microcontroller sourcing.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for standalone keypad retrofits as local assembly operations displace German and French incumbent premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with cloud-enabled platforms capturing subscription revenue against hardware-only transactional sales. Cost compression in the economy tier intensifies because copper and aluminum price volatility erodes mid-tier electromechanical margins. REIT portfolio managers exhibit lowest price sensitivity where bundled building automation integration reduces total procurement complexity.
Supply Chain Analysis
CE marking and REACH compliance documentation function as procurement gatekeepers, filtering non-qualified Asian component suppliers from Western European contract eligibility. Manufacturing concentration centers on Germany, the Netherlands, and China, with Bavarian facilities specializing in IP65-rated enclosures and Dutch operations anchoring firmware development. Supply chain risk rests on single-source vulnerability for microcontroller procurement from Taiwanese foundries. Distribution runs through specialized security integrators and building automation contractors rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Pin-Based Access Control Market operates as a stable compounder anchored by regulatory-mandated replacement cycles for legacy mechanical systems across commercial real estate portfolios.
For Market Incumbents: Anticipate margin compression from biometric substitution in healthcare and financial verticals by deepening firmware security differentiation and pre-emptive certification investment under evolving EU cybersecurity schemes. Channel control across German-speaking markets remains defensible against pure-play cloud entrants through bundled HVAC and lighting integration contracts. For New Entrants and Emerging Players: Begin with Polish and Romanian greenfield commercial construction where regulatory harmonization lags and incumbent presence remains thin. Campus-wide educational deployments in the Netherlands offer the most penetrable entry point through semester-automation software attach rates that established hardware vendors underemphasize. For Investors and Strategic Acquirers: Consolidation pressure builds where REIT portfolio standardization demands unified platform coverage across multi-country footprints. Five-to-ten year viability favors specialists with embedded systems security engineering depth over component-scale manufacturers exposed to commodity margin cycles. The signal to monitor is third-party cybersecurity certification mandate timing, which will abruptly disqualify non-compliant inventory and accelerate acquisition premiums for certified targets.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Centralized credential management aligns with corporate security director procurement authority consolidation. |
| Firmware Security Certification | EU Cybersecurity Act compliance creates competitive moats against uncertified Asian competitors. |
| Bluetooth Low Energy Credential Handoff | Smartphone-based temporary access eliminates physical credential costs for Dutch logistics operators. |
| Backward Integration into Enclosure Manufacturing | Captive IP65-rated housing production insulates against REACH-regulated polymer reformulation costs. |
| Geographic Expansion into Central Europe | Warsaw and Kraków greenfield positioning precedes regulatory tightening and incumbent saturation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facility operators, corporate security directors, building automation integrators, and regulatory compliance officers with secondary validation against CE marking databases, EN standard certification registries, and REIT portfolio disclosure filings. Bottom-up unit economics from component bill-of-materials analysis triangulated against top-down addressable market sizing from commercial construction permits and mechanical lock replacement cycle data.
Historical reference periods anchored the projection horizon to observed replacement cycle compression rates and cloud migration adoption curves across UK and Netherlands commercial portfolios. Segmentation modeling spanned product architecture, application vertical, end-user procurement authority, and technology tier dimensions. CAGRs derived from regression-weighted scenario analysis incorporating semiconductor supply lead time volatility and copper price trajectory assumptions.
Several conditions sit outside the modeled scope, including unannounced biometric technology breakthroughs, abrupt EU regulatory timeline accelerations, and geopolitical trade restrictions affecting Asian microcontroller supply. Forecasts reflect documented assumptions about REIT consolidation velocity and cybersecurity certification implementation pacing. A model refresh is warranted upon material change in semiconductor foundry capacity allocation or EN standard interpretation revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Mode Locking Device Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
US Access Control Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
Italy Access Control Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Access Control and Authentication Market