
 Global Fingerprint Access Control Systems Market | 2026-2036
Global Fingerprint Access Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fingerprint Access Control Systems Market Foresight
The gap between premium multispectral optical systems and entry-level capacitive modules is realigning procurement patterns across enterprise security budgets. IDEMIA leverages its government credentialing heritage to anchor high-assurance contracts in European critical infrastructure. ZKTeco Co. Ltd. competes aggressively on manufacturing scale, dominating price-sensitive installations across Asia-Pacific and Latin America. Honeywell International Inc extends its building automation ecosystem, integrating biometric terminals into broader facility management platforms.
A fingerprint access control system authenticates identity by capturing and matching friction ridge patterns against enrolled templates, typically operating with false acceptance rates below 0.001% and false rejection rates under 1% in enterprise-grade configurations. Its primary purpose is to replace credential-based entry with non-transferable biological verification across physically secured perimeters. Networked readers are capturing disproportionate investment as centralized audit trails become mandatory for financial services compliance. Capacitive sensors retain volume leadership in consumer-adjacent applications but ultrasonic and multispectral optical variants are expanding in data centers and government buildings where spoof resistance commands premium pricing. The application split reveals corporate facilities as the mature revenue base while transport terminals represent the fastest structural expansion corridor.
FDA guidelines on biometric data handling in healthcare-adjacent facilities, BIS certification mandates for electronic security products in India, and the EU AI Act's risk classification framework for biometric identification systems are collectively elevating compliance costs and technical barriers to market entry. China's GB standards for information security and SAMR quality enforcement add further layers of product validation complexity for vendors seeking multi-territory deployment. Stakeholders must monitor regulatory divergence between privacy-centric European frameworks and security-prioritized Asian regimes when allocating R&D and certification budgets.
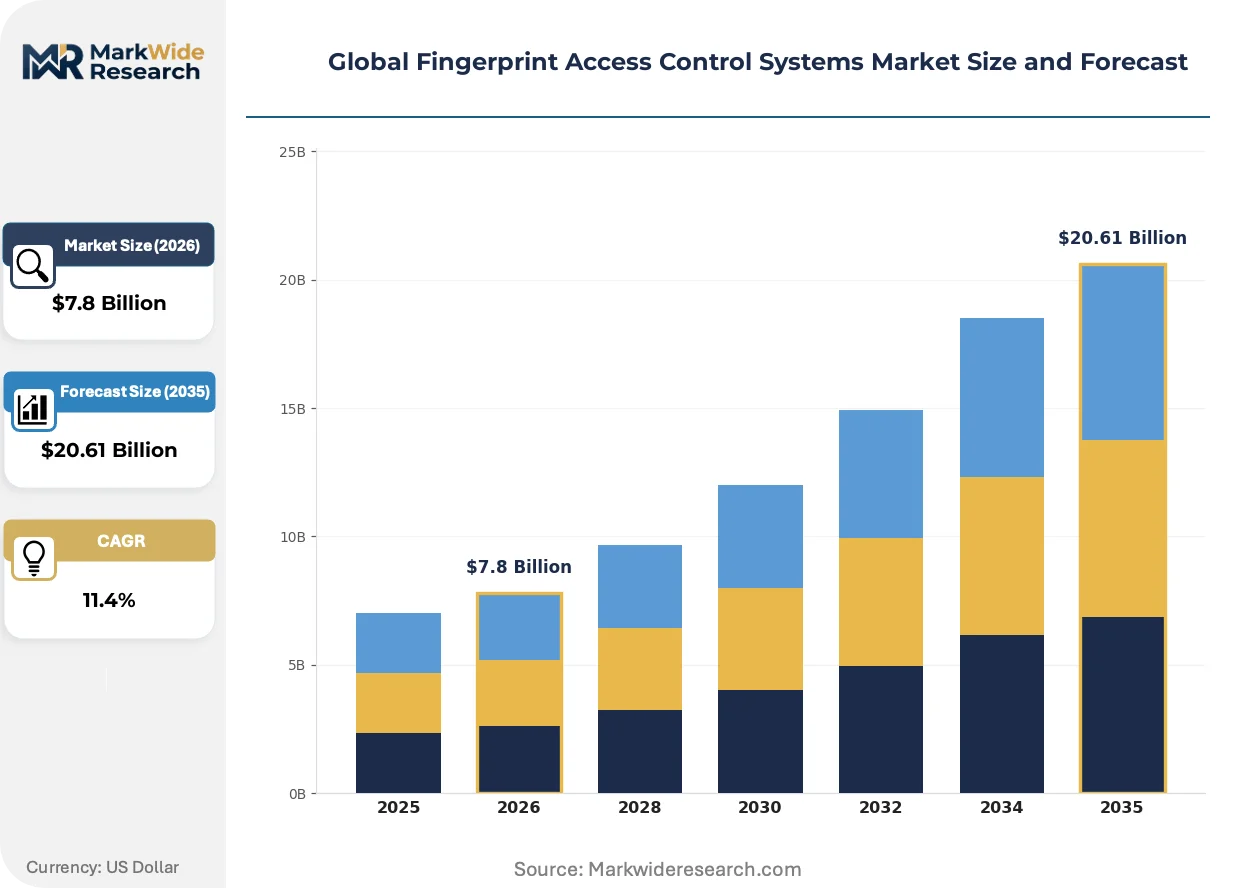
Market Dynamics
Networked biometric readers are consolidating facility security architectures as centralized audit mandates from financial regulators and data protection authorities eliminate siloed access systems. This infrastructure convergence is compressing procurement cycles and elevating technical certification requirements across enterprise, government, and critical infrastructure deployments.
Growth Catalysts
- EU AI Act risk classification:The European Union's tiered framework for biometric identification systems is mandating enhanced accuracy and transparency standards, accelerating replacement of legacy readers in Frankfurt and Paris financial districts.
- Data center construction:Hyperscale facility operators in Northern Virginia and Singapore are specifying multispectral optical sensors to meet SOC 2 and ISO 27001 physical access requirements.
- India's BIS certification mandate:Compulsory quality marks for electronic security products are formalizing supply chains and blocking uncertified imports, benefiting domestic manufacturers in Bangalore and Hyderabad.
Market Restraints
- Semiconductor input volatility:Capacitive sensor fabrication depends on specialized CMOS foundry capacity concentrated in Taiwan, creating procurement bottlenecks during supply shocks.
- Spoofing vulnerability in legacy capacitive modules:Basic fingerprint sensors without liveness detection face obsolescence pressure as presentation attack detection becomes a procurement prerequisite.
- GDPR biometric data processing restrictions:European data protection authorities require explicit consent frameworks and data retention limits that lengthen sales cycles and complicate cloud-based template storage.
Strategic Opportunities
- Transport terminal modernization:Airport authorities in Dubai and São Paulo are piloting contactless biometric corridors that integrate fingerprint verification with facial recognition for passenger flow optimization.
- Healthcare-adjacent deployment:FDA guidance on biometric data handling in clinical environments is creating compliant product categories for hospital pharmacy vaults and surgical suite access.
- Edge-to-cloud convergence:Hybrid architectures combining on-device template matching with centralized policy management are opening mid-market segments previously served by disconnected standalone readers.
Industry Challenges
- Embedded systems security engineering:Firmware vulnerability assessment and secure boot implementation require specialized talent scarce outside established cybersecurity hubs.
- Multi-territory certification sequencing:Simultaneous pursuit of BIS marks, CE conformity, and FCC authorization extends product launch timelines by 12-18 months.
- Legacy Wiegand protocol integration:Brownfield installations in industrial facilities demand bridging hardware that complicates zero-trust security architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fingerprint Access Control Systems Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Readers, Networked Readers, Biometric Terminals, Mobile Fingerprint Scanners Technology: Capacitive Sensors, Optical Sensors, Ultrasonic Sensors, Thermal Sensors, Piezoelectric Sensors Application: Residential Security, Corporate Facilities, Transport Terminals, Data Centers, Government Buildings End User: Small Offices, Large Enterprises, Educational Institutions, Financial Services, Hospitality Sector |
| Companies Covered | BOSCH Security, IDEMIA, HID Global Corporation, Honeywell International Inc, ZKTeco Co. Ltd., NEC Corporation, Suprema Inc., Hitachi Ltd., Johnson Controls International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fingerprint Access Control Systems Market Shifts & Advancements
Biometric access control is migrating from standalone authentication points toward integrated identity platforms that unify physical and logical security domains. This architectural shift is compressing vendor margins while elevating systems integration capabilities as a competitive differentiator.
Multispectral optical imaging is unifying spoof resistance and environmental reliability in a single sensor package. Data center operators in Ashburn and Frankfurt are specifying these modules for outdoor perimeter gates and climate-controlled server floors alike. The technology is unifying previously separate premium and standard product tiers, forcing capacitive specialists to defend position on cost or abandon enterprise segments entirely.
The EU AI Act's risk-based classification for biometric identification is mandating conformity assessment procedures that parallel medical device pathways. Manufacturers must now document algorithmic accuracy across demographic groups and maintain technical files for market surveillance authorities. European critical infrastructure operators are responding by pre-qualifying vendors with established notified body relationships, consolidating procurement around proven compliance track records.
Enterprise buyers are consolidating security technology spend under integrated facility management platforms rather than procuring access control as a standalone category. Building automation providers in Chicago and Singapore are capturing biometric terminal decisions through bundled service contracts that unbundle hardware from software licensing. This pattern is most pronounced in commercial real estate portfolios where standardization across multiple properties overrides best-of-breed technical preferences.
Global Fingerprint Access Control Systems Market Segmentation
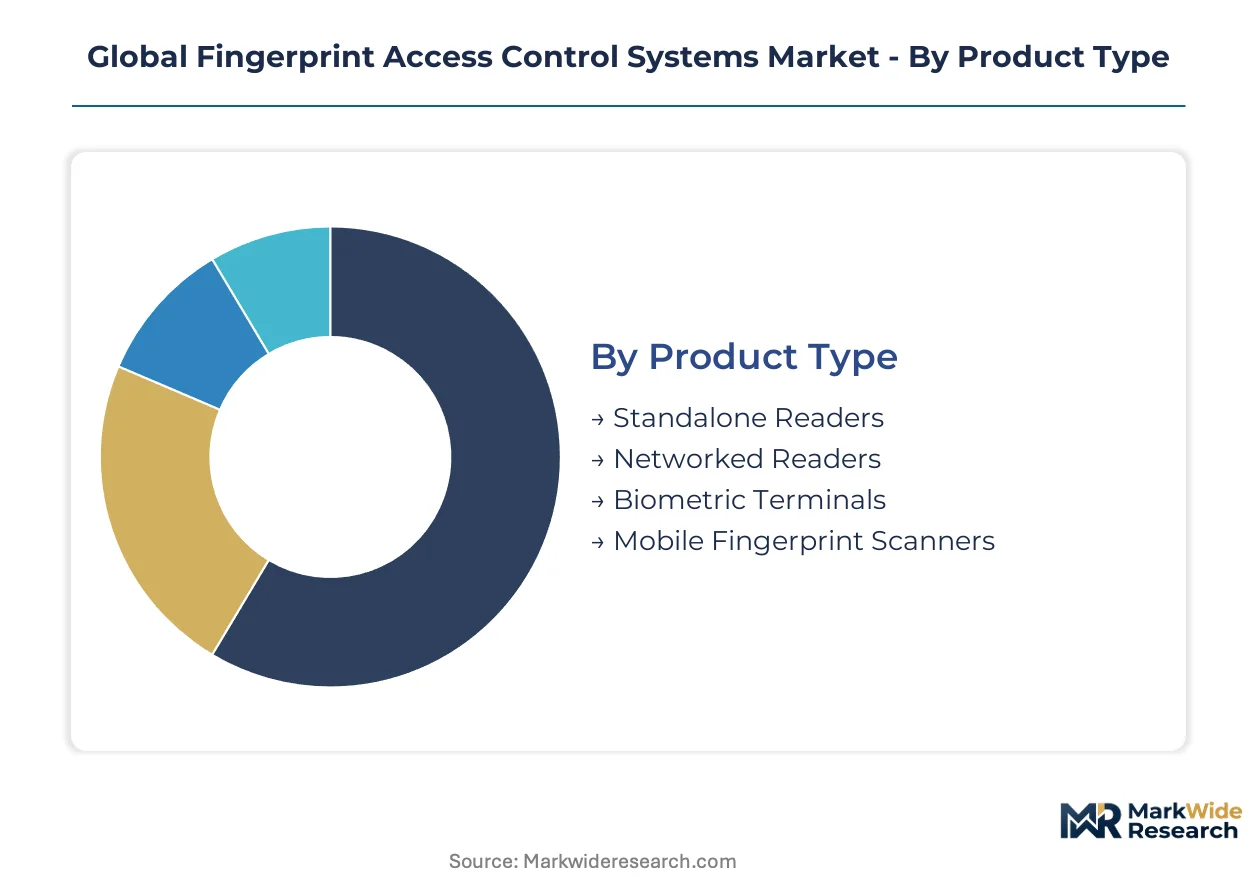
Procurement patterns across the fingerprint access control landscape diverge sharply by deployment scale, environmental conditions, and compliance burden. Upgrade cycles accelerate where regulatory mandates force replacement of legacy credential systems with biometric alternatives.
Product Type:
Replacement dynamics favor networked architectures as centralized audit requirements eliminate standalone installations in regulated industries.
- Standalone Readers:Single-device authentication units process template matching locally without network dependency. Demand persists in remote industrial outposts across Australia's mining belt and rural India where connectivity remains intermittent.
- Networked Readers:IP-connected terminals stream biometric events to centralized policy engines with real-time revocation capabilities. Financial services compliance in Frankfurt and Singapore drives disproportionate investment as SOC 2 and MAS TRM guidelines mandate immutable access logs.
- Biometric Terminals:Integrated hardware-software appliances combine fingerprint capture with display, processing, and relay control in weatherized enclosures.
- Mobile Fingerprint Scanners:Portable Bluetooth-connected peripherals extend biometric verification to temporary checkpoints and field service operations.
Volume placements concentrate in Standalone Readers; the faster expansion belongs to Networked Readers.
Technology:
Cost tiers separate commodity capacitive modules from premium multispectral optical and ultrasonic variants demanded by high-assurance environments.
- Capacitive Sensors:Silicon-based electrical field detection arrays dominate consumer-adjacent price points with compact form factors. India's commercial real estate sector in Bangalore and Mumbai absorbs volume shipments for standard office installations where environmental conditions remain controlled.
- Optical Sensors:Multispectral imaging variants capture sub-surface tissue patterns through prism-based illumination stacks resistant to spoofing. Data center operators in Northern Virginia and Frankfurt specify these for perimeter gates and server floor airlocks where presentation attack detection commands premium pricing.
- Ultrasonic Sensors:Piezoelectric transducers map three-dimensional ridge topology through acoustic impedance measurement.
- Thermal Sensors:Infrared detectors capture heat differential patterns between ridges and valleys.
- Piezoelectric Sensors:Pressure-sensitive polymer films convert mechanical ridge contact into electrical signals for low-power embedded applications.
Capacitive Sensors retain the largest installed base; Optical Sensors are climbing the fastest as spoofing resistance becomes non-negotiable in critical infrastructure.
Application:
Customer maturity varies dramatically across verticals, with transport and data center segments exhibiting compressed procurement cycles compared to legacy corporate deployments.
- Residential Security:Consumer-grade fingerprint locks and smart home entry systems prioritize convenience over forensic accuracy. China's tier-one cities of Shenzhen and Shanghai drive volume as property developers bundle biometric hardware into new construction specifications.
- Corporate Facilities:Enterprise campuses integrate fingerprint terminals with visitor management and time-attendance systems. Germany's Mittelstand manufacturing belt sustains steady replacement demand as ISO 27001 certification spreads through supply chains.
- Transport Terminals:Airport and seaport authorities deploy contactless biometric corridors for passenger flow optimization.
- Data Centers:Hyperscale and colocation operators enforce multi-factor physical access with biometric components.
- Government Buildings:Critical infrastructure and classified facilities mandate certified products under national security frameworks.
Corporate Facilities anchor current revenue; Transport Terminals show the steepest expansion trajectory as aviation authorities modernize passenger processing.
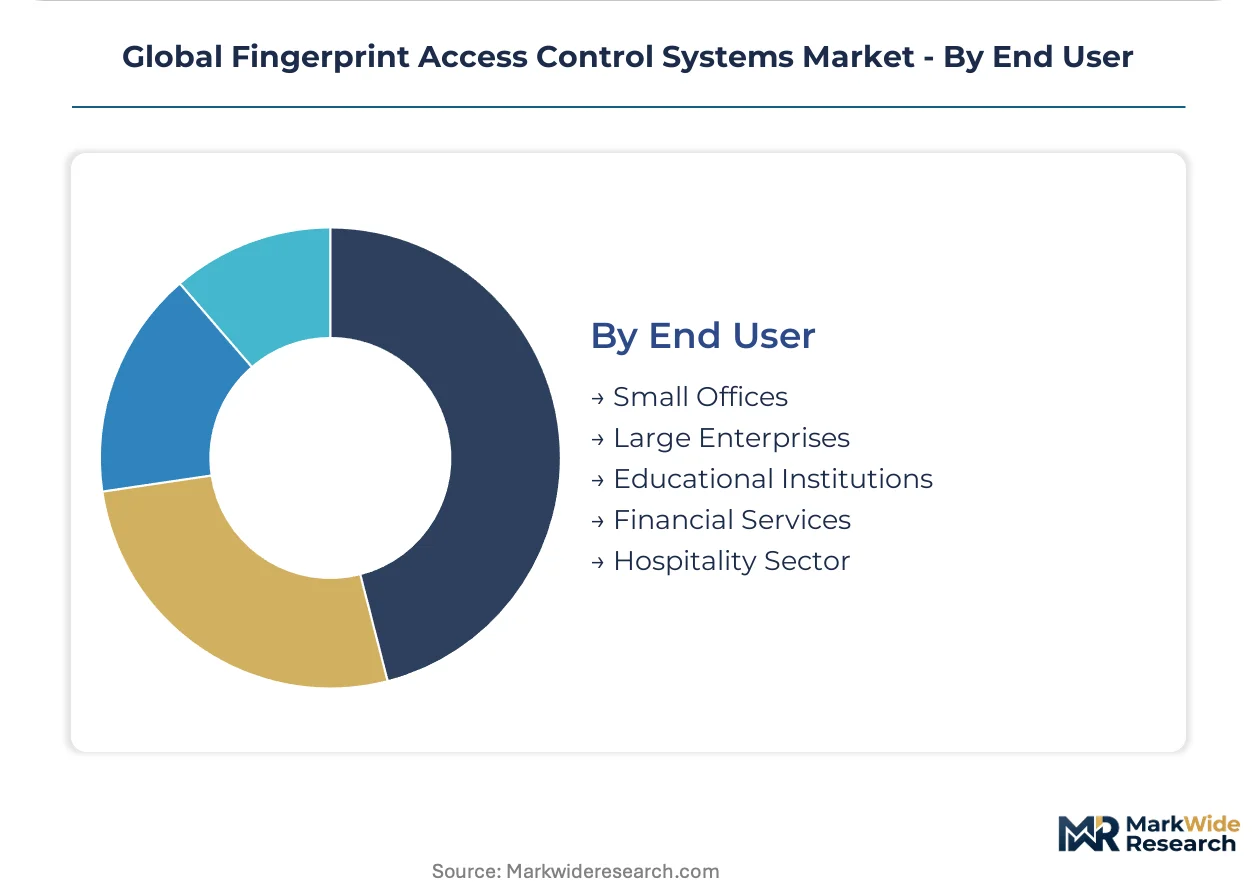
End User:
Scale economics favor large enterprise deployments where standardization across multiple sites justifies integration complexity and certification overhead.
- Small Offices:Single-location businesses prioritize plug-and-play devices with minimal IT infrastructure requirements.
- Large Enterprises:Multi-site organizations demand centralized identity platforms with API-driven policy orchestration. India's IT services corridor from Bangalore to Hyderabad generates concentrated demand as export-oriented firms pursue SOC 2 and ISO 27001 compliance for Western client contracts.
- Educational Institutions:University campuses and K-12 districts balance security imperatives with privacy concerns around student biometric data.
- Financial Services:Banks, insurers, and payment processors face stringent physical access controls under Basel operational risk guidelines and national banking regulations.
- Hospitality Sector:Hotels and resorts deploy biometric safes and staff access systems with guest-facing applications remaining limited by privacy sensitivities.
Large Enterprises dominate procurement value; Financial Services is gaining share fastest as regulatory pressure intensifies on operational resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ashburn's data center corridor drives North American biometric deployment as hyperscale operators harden physical perimeters against unauthorized access. Frankfurt and Singapore financial districts enforce centralized audit mandates that eliminate standalone reader installations.
United States
Northern Virginia's data center cluster and Chicago's building automation hub absorb premium multispectral optical sensors for SOC 2 compliance. FDA guidance on biometric data handling in healthcare-adjacent facilities shapes product categories for hospital pharmacy vaults. Financial services procurement in New York and Boston prioritizes networked architectures with immutable access logs under SEC operational resilience expectations.
Germany
Frankfurt's financial district replacement cycles accelerate under EU AI Act risk classification for biometric identification systems. The Mittelstand manufacturing belt sustains steady demand as ISO 27001 certification spreads through automotive and industrial supply chains. Munich and Stuttgart industrial parks specify certified products for critical infrastructure protection under national security frameworks.
China
Shenzhen and Shanghai property developers bundle consumer-grade fingerprint locks into new construction specifications across residential towers. GB standards for information security and SAMR quality enforcement add validation complexity for multi-territory deployment. Industrial corridor cities in the Yangtze River Delta deepen infrastructure digitization with networked biometric terminals.
India
Bangalore and Hyderabad's IT services corridor generates concentrated demand as export-oriented firms pursue SOC 2 and ISO 27001 compliance for Western client contracts. BIS certification mandates for electronic security products formalize supply chains and block uncertified imports. Mumbai's commercial real estate sector absorbs volume shipments of capacitive sensors for standard office installations.
Singapore
Hyperscale facility operators specify multispectral optical sensors to meet MAS TRM and SOC 2 physical access requirements. The city-state's position as Asia-Pacific data center hub concentrates procurement for regional financial services compliance. Building automation integrators capture biometric terminal decisions through bundled service contracts across commercial real estate portfolios.
Global Fingerprint Access Control Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across sensor fabrication and systems integration. The vendor base separates into three tiers: government credentialing specialists, manufacturing-scale commoditizers, and building automation ecosystem extenders. Strategic moves concentrate on M&A for compliance capabilities and capacity expansion in certified foundry relationships.
Within the government credentialing tier, IDEMIA anchors high-assurance contracts through established notified body relationships in European critical infrastructure. ZKTeco Co. Ltd. occupies the manufacturing-scale position, competing on production volume across price-sensitive Asia-Pacific and Latin American installations. Honeywell International Inc exemplifies the ecosystem extension archetype, integrating biometric terminals into broader facility management platforms through bundled service contracts.
| Leading Market Players |
|---|
| BOSCH Security |
| IDEMIA |
| HID Global Corporation |
| Honeywell International Inc |
| ZKTeco Co. Ltd. |
| NEC Corporation |
| Suprema Inc. |
| Hitachi Ltd. |
| Johnson Controls International plc |
| Others |
Supply & Pricing Matrix
Captive sensor fabrication in Taiwan and Shenzhen anchors supply positions for capacitive module specialists while multispectral optical producers defend margin through in-house prism-stack assembly. This integration choice concentrates pricing power with vendors controlling liveness-detection IP and certified foundry relationships, compressing margins for assembly-only competitors dependent on merchant CMOS supply.
Pricing Analysis
Uptime guarantees in data center contracts anchor value-based pricing for multispectral optical terminals, with premiums scaling to spoof-resistance certification tiers. Pricing stratifies across premium, standard, and economy tiers based on presentation-attack detection ratings and EU AI Act conformity assessment depth. Cost compression in entry-level capacitive modules intensifies as ZKTeco's manufacturing scale forces regional competitors toward bare-margin project bids. Small offices in India's tier-two cities exhibit highest price sensitivity, while Frankfurt financial services procurement prioritizes compliance documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore, Dubai, and Rotterdam handle hub-and-spoke fulfillment for networked reader deployments across Asia-Pacific, Middle East, and European financial districts. Specialized CMOS foundry capacity concentrates in Taiwan and South Korea, with prism illumination stacks sourcing from German and Japanese optical component specialists. Single-source vulnerability in Taiwan's 300mm CMOS fab capacity threatens capacitive sensor supply continuity during geopolitical stress. Distribution runs through building automation integrators in Chicago and Singapore who bundle biometric terminals into facility management contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
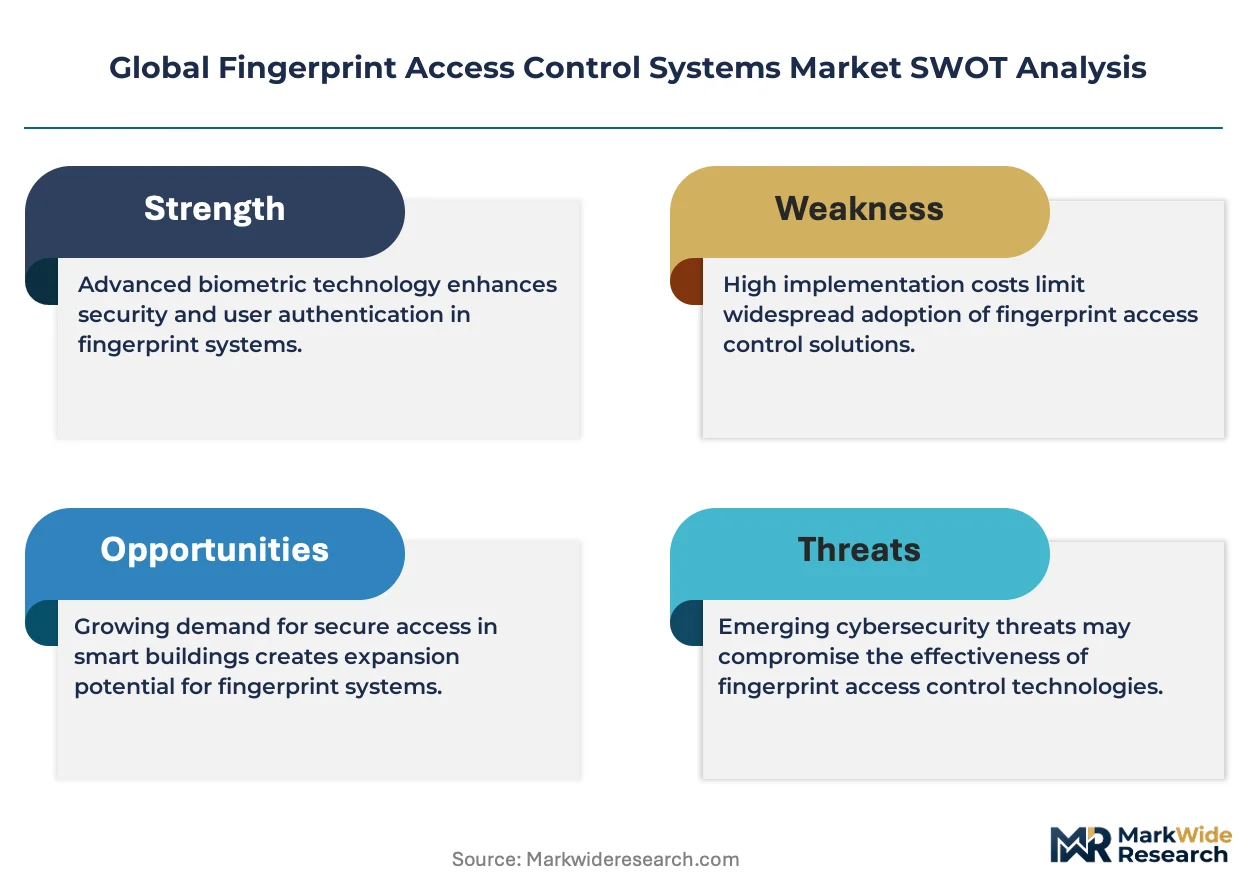
This market is a vertical-integration race into certified sensor fabrication and notified body relationships, with downstream control over building automation channels determining pricing power.
For Market Incumbents: Acquire EU AI Act technical file capabilities and notified body pre-qualification status to lock out commodity competitors from Frankfurt and Paris financial district replacement cycles. Defend position by embedding biometric terminals into Honeywell-style facility management platforms, neutralizing standalone reader vendors through bundled service contracts. Threat of ZKTeco's manufacturing scale requires backward integration into captive CMOS capacity or abandonment of price-sensitive Asia-Pacific volume segments. For New Entrants and Emerging Players: Begin with healthcare-adjacent deployments under FDA biometric data handling guidance, where compliance moats are shallower than EU critical infrastructure certification. Target hospital pharmacy vaults and surgical suite access in the US Southeast, where building automation incumbents lack specialized clinical workflow integration. Go-to-market angle: edge-to-cloud hybrid architectures serving mid-market enterprises previously served by disconnected standalone readers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by building automation conglomerates seeking biometric identity platform capabilities. Long-term viability favors vendors with demonstrated EU AI Act conformity assessment completion and established relationships with hyperscale data center operators. Signal to watch is BIS certification mandate enforcement depth in India, which could formalize supply chains around domestic manufacturers and strand uncertified import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Establishment | EU AI Act conformity assessment completion unlocks Frankfurt and Paris financial district procurement. |
| Captive CMOS Foundry Investment | Taiwan and South Korea fab capacity secures capacitive sensor supply continuity against geopolitical disruption. |
| Building Automation Platform Integration | Honeywell-style bundled service contracts capture biometric terminal decisions across commercial real estate portfolios. |
| Healthcare-Adjacent Product Certification | FDA biometric data handling guidance compliance opens hospital pharmacy vault and surgical suite access segments. |
| Edge-to-Cloud Hybrid Architecture Launch | On-device template matching with centralized policy management serves mid-market enterprises abandoning standalone readers. |
Research Methodology
Independent corroboration across facility security directors, biometric systems integrators, and data center operations managers underwrites the qualitative findings. Primary interviews with building automation procurement leads, CMOS foundry supply planners, and EU notified body technical assessors combined with secondary validation from SEC filings of listed security technology vendors, BIS certification registry data, and EU AI Act implementation guidance documents. Bottom-up unit shipment estimates triangulate against top-down security technology spend allocation data.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include product architecture, sensor technology tier, application vertical, end-user scale, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed hyperscale data center construction pipelines and financial services compliance mandate timelines. Industry-specific inputs encompass EU AI Act risk classification rollout schedules and India's BIS certification enforcement trajectory.
Underlying measurement precision varies by segment; networked reader and data center application estimates carry tighter precision than standalone reader and residential security projections. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hyperscale facility construction continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Border Security System Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
France Access Control Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market