
 Wearable Airbag Belt Market | 2026-2036
Wearable Airbag Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Airbag Belt Market Insights
High-tenacity nylon is consolidating its position as the dominant shell material across wearable airbag belt construction, displacing heavier woven polyester variants and reducing overall system weight by meaningful margins. Dainese leverages vertical integration across European textile sourcing to control quality and cost simultaneously. Helite anchors its competitive stance through specialized equestrian and motorcycling product lines with proven deployment records. Alpinestars competes aggressively in the premium motorcycling segment, where brand heritage commands channel positioning and pricing power.
A wearable airbag belt is a personal protective garment incorporating gas-inflatable bladder systems, typically triggered by accelerometer and gyroscope arrays detecting rapid deceleration or angular velocity shifts exceeding programmed thresholds, designed to deploy protective cushioning around the thorax, neck, and hips prior to ground contact. The smart belt segment leads absolute volume as connectivity features and smartphone integration attract tech-forward consumers, while the sport belt category registers the fastest expansion among cyclists seeking lightweight alternatives to rigid body armor. Motorcyclists dominate end-user demand due to established safety culture and insurance incentives, whereas industrial workers represent an emerging margin pool as warehouse and logistics operators evaluate fall-protection protocols.
The EU PPE Regulation mandates third-party conformity assessment for Category III protective equipment, directly shaping product certification timelines and market access costs for European entrants. The US Consumer Product Safety Commission and NHTSA maintain overlapping jurisdiction for motorcycling applications, creating a dual-track compliance environment that favors manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving e-bike classification standards, as jurisdictional ambiguity between bicycle and motorcycle safety frameworks threatens to fragment addressable market definitions and testing protocols.
Market Dynamics
CE marking requirements under the EU PPE Regulation are compressing certification timelines and elevating compliance costs, forcing smaller entrants to consolidate or exit while vertically integrated incumbents capture shelf space across German and French retail channels.
Growth Catalysts
- E-bike commuter expansion:Dense urban cycling infrastructure in Copenhagen and Amsterdam is normalizing powered two-wheeler commuting, expanding addressable user bases beyond traditional motorcyclists into daily transport segments.
- High-tenacity nylon adoption:Advanced polymer shells are displacing woven polyester variants, reducing system weight and improving wearer compliance during extended use periods across equestrian and industrial applications.
- Insurance premium incentives:German and Dutch insurers now offer documented rate reductions for certified wearable airbag users, converting safety equipment from discretionary purchase to cost-recovery investment.
Market Restraints
- CO2 cartridge supply concentration:European gas inflator manufacturing clusters in Austria and Czechia create single-source vulnerability for deployment mechanism components.
- Sensor calibration complexity:Accelerometer and gyroscope array tuning for false-positive avoidance demands specialized firmware expertise that concentrates among a handful of component suppliers.
- Reusable vest competition:Traditional motorcycle body armor with multi-impact capability retains price advantage in budget-conscious segments, constraining premium airbag pricing headroom.
Strategic Opportunities
- Warehouse logistics penetration:Fall-protection protocol evaluation by German and Dutch distribution center operators creates emerging demand pool outside established motorcycling verticals.
- Smartphone integration convergence:Bluetooth connectivity and crash-data telemetry are opening subscription service revenue streams alongside hardware sales.
- French equestrian mandate trajectory:Proposed competitive riding safety regulations would mandate airbag systems for sanctioned events, creating regulatory pull comparable to motorcycle helmet laws.
Industry Challenges
- Firmware validation timelines:Third-party conformity assessment for Category III PPE certification extends product development cycles by 8-14 months, straining working capital for pre-revenue ventures.
- Sensor fusion expertise scarcity:Embedded systems engineers capable of integrating IMU arrays with deployment algorithms command premium compensation, constraining R&D scaling for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Airbag Belt Market |
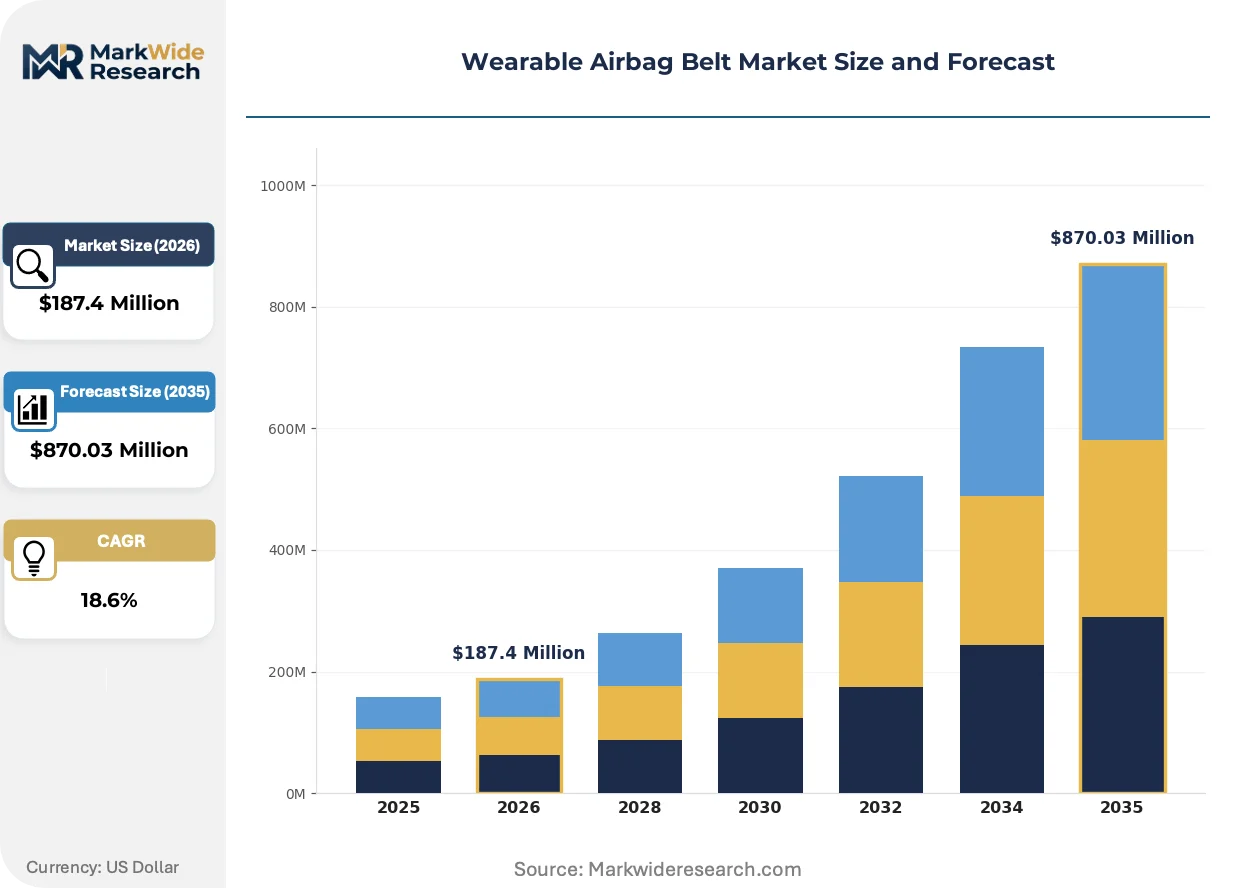
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Belt, Classic Belt, Sport Belt, Safety Belt End User: Motorcyclists, Pedestrians, Cyclists, Industrial Workers Technology: Inflatable, Non-Inflatable, Hybrid, Smart Sensors Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Dainese, Helite, Alpinestars, Hovding, In&motion, Point Two Air Vest, S-Airbag Technology, Wolk Airbag, Mugen Denko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Airbag Belt Market Trends and Innovations
Connected safety ecosystems and predictive deployment algorithms are compressing the gap between crash detection and bladder inflation, redefining performance benchmarks across motorcycling and equestrian applications.
Artificial intelligence inference at the edge is unifying sensor fusion and deployment decision-making within single-chip architectures. Premium motorcycling gear manufacturers are adopting these integrated SoC platforms for sub-80-millisecond inflation triggers. This convergence is unifying previously separate hardware modules into compact belt-integrated units that reduce manufacturing complexity and field failure rates.
REACH compliance deadlines for restricted substance screening in textile coatings are forcing reformulation of shell material treatments across European supply chains. Manufacturers with captive polymer finishing capabilities are absorbing testing costs internally while outsourcing-dependent competitors face margin compression. Motorcycling applications bear the heaviest burden due to abrasion-resistance requirements that conflict with candidate replacement chemistries.
Fleet procurement by commercial courier services is displacing individual consumer purchases as the dominant demand channel in urban European markets. Dutch and German last-mile delivery operators now specify certified airbag systems in rider equipment mandates, consolidating volume through direct manufacturer negotiations. This concentration is visible most acutely in Rotterdam and Berlin, where density economics favor centralized safety program administration over fragmented retail distribution.
Wearable Airbag Belt Market Segmentation
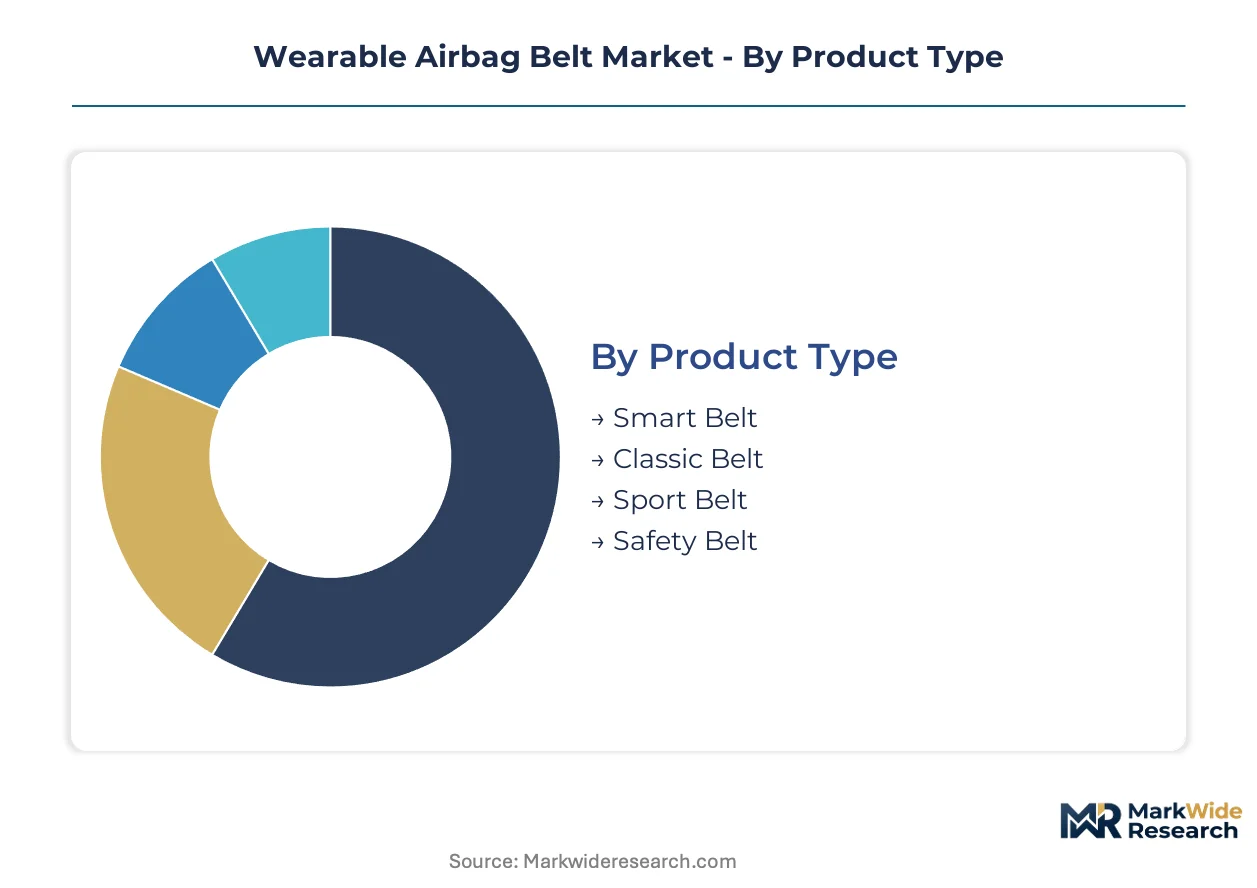
Wearable airbag belt manufacturers calibrate product portfolios across four distinct dimensions, each commanding different R&D investment cycles and margin structures. Upgrade trajectories vary sharply by user sophistication and regulatory exposure, creating tiered replacement demand patterns.
Product Type:
Replacement cycles accelerate where connectivity integration justifies periodic hardware refresh, while mechanical systems persist longer in price-sensitive verticals.
- Smart Belt:Bluetooth-enabled units with crash telemetry and smartphone pairing dominate absolute shipment volumes. German and Dutch fleet procurement programs specify these systems for last-mile delivery riders, converting equipment mandates into recurring connectivity subscription revenue.
- Sport Belt:Ultralight designs targeting competitive cyclists and amateur racers are climbing the fastest as e-bike commuting normalizes in Copenhagen and Amsterdam. Weight reduction below 800 grams drives adoption among riders rejecting rigid body armor.
- Classic Belt:Mechanical trigger systems without electronic components serve budget-conscious motorcyclists and developing market entry segments.
- Safety Belt:Industrial-rated variants with reinforced tethering points address warehouse fall-protection protocols under evaluation by German logistics operators.
Volume placements concentrate in Smart Belt configurations; the steepest expansion trajectory belongs to Sport Belt adoption among urban e-bike commuters.
End User:
Customer acquisition costs diverge sharply between established safety cultures and emerging protective equipment mandates.
- Motorcyclists:Established insurance incentive structures in Germany and the Netherlands convert certified airbag ownership into documented premium reductions. This segment anchors current revenue concentration through proven deployment records and dealer channel penetration.
- Industrial Workers:German distribution center operators pilot fall-protection programs specifying wearable airbag systems for elevated picking operations. Procurement runs through centralized safety departments rather than individual purchase decisions.
- Cyclists:Road and gravel riders seeking alternatives to foam back protectors represent emerging demand outside traditional motorcycling verticals.
- Pedestrians:Elderly mobility aid applications remain experimental, with limited reimbursement pathway clarity.
Motorcyclists retain the dominant share of current placements; industrial worker specifications are gaining share fastest as occupational safety protocols expand.
Technology:
Component sourcing strategies concentrate around gas inflator reliability and sensor fusion calibration expertise.
- Inflatable:CO2 cartridge-based systems with mechanical or electronic triggers constitute the installed base majority. Austrian and Czech manufacturing clusters create supply concentration for deployment mechanisms.
- Smart Sensors:IMU arrays with edge AI inference compressing detection-to-inflation intervals below 80 milliseconds command premium positioning. Firmware validation timelines for CE marking extend development cycles substantially.
- Hybrid:Combined mechanical-electronic trigger redundancy addresses false-positive sensitivity in equestrian applications.
- Non-Inflatable:Foam-based impact absorption without gas deployment serves budget segments and jurisdictions with cartridge shipping restrictions.
Smart Sensors capture the highest value per unit; Inflatable systems maintain the broadest volume footprint across price tiers.
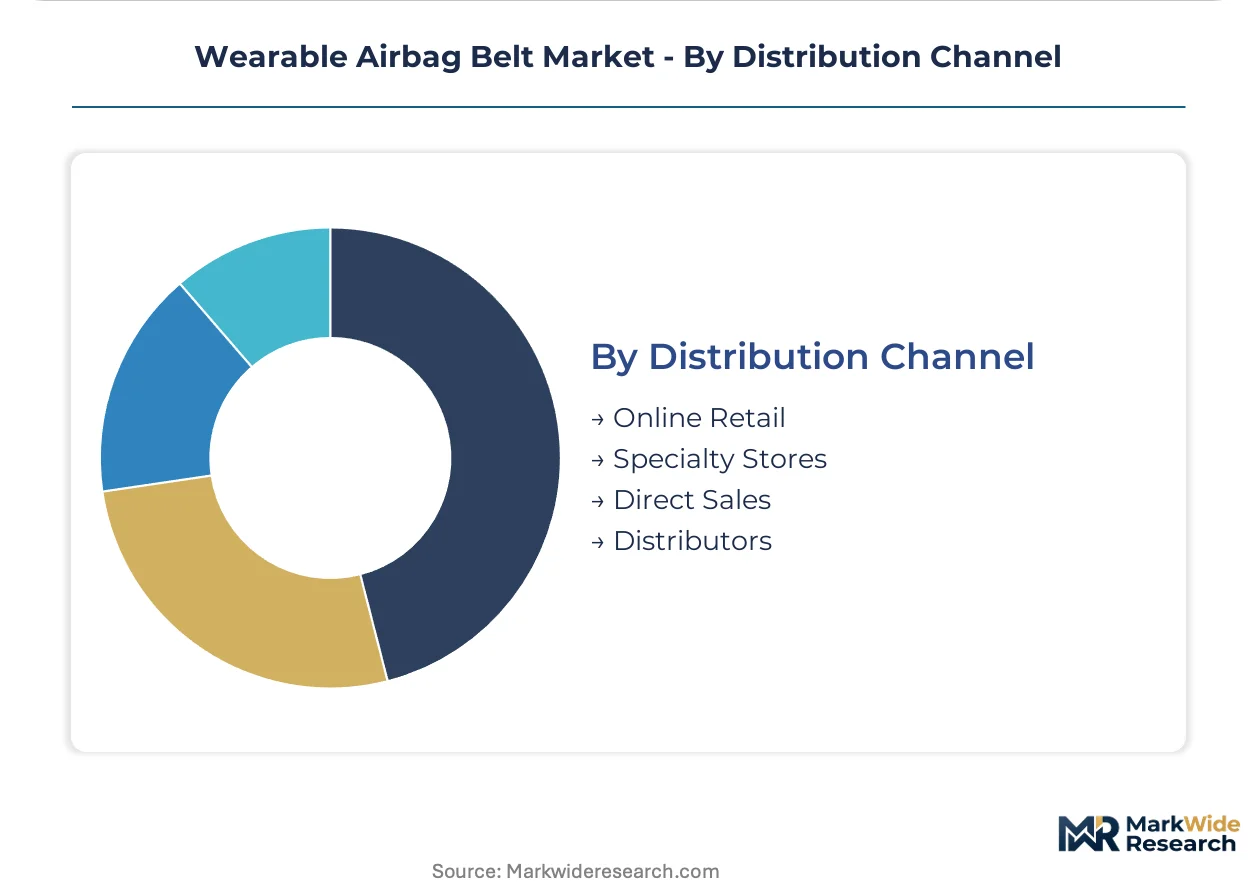
Distribution Channel:
Channel economics shift as fleet procurement displaces fragmented retail for urban commercial applications.
- Direct Sales:Manufacturer relationships with Dutch and German courier fleets consolidate volume through centralized safety program administration. Rotterdam and Berlin operators negotiate equipment mandates directly, bypassing retail markup.
- Specialty Stores:Motorcycling dealers with certified fitting services maintain pricing power in premium helmet-and-apparel bundling.
- Online Retail:Equestrian and cycling marketplaces expand geographic reach for replacement cartridges and accessory sales.
- Distributors:Industrial safety suppliers with existing warehouse and construction site relationships facilitate B2B penetration.
Direct Sales channels are expanding most quickly through fleet consolidation; Specialty Stores retain the highest margin structure per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motorcyclists and Dutch e-bike commuters concentrate current demand through insurance incentive structures and dense urban cycling infrastructure. Fleet procurement by last-mile delivery operators in Rotterdam and Berlin now displaces individual retail purchases as the dominant volume channel.
Germany
KBA registration data shows rising two-wheeler density in urban centers, while German insurers document premium reductions for certified airbag belt users. The EU PPE Regulation and CE marking requirements compress certification timelines for Category III protective equipment. Bavaria and North Rhine-Westphalia host the densest motorcycling populations, with Munich and Cologne dealers bundling airbag systems in premium helmet-and-apparel packages.
Netherlands
Amsterdam and Rotterdam normalize powered two-wheeler commuting through dedicated cycling infrastructure and municipal safety mandates. Dutch insurers replicate German premium reduction frameworks for certified wearable airbag ownership. Randstad logistics operators specify airbag systems in rider equipment mandates, consolidating procurement through direct manufacturer negotiations rather than retail channels.
France
Proposed equestrian safety regulations would mandate airbag systems for sanctioned competitive events, creating regulatory pull comparable to motorcycle helmet laws. ANSM oversees medical device adjacent classifications where airbag systems interface with health monitoring. The Île-de-France region concentrates equestrian activity around Parisian training centers, while Provence-Alpes-Côte d'Azur hosts competitive riding circuits evaluating protective equipment mandates.
United Kingdom
London's congestion charging scheme and low-emission zones accelerate two-wheeler adoption among commuters seeking parking and toll exemptions. The Health and Safety Executive evaluates wearable airbag applicability for courier and delivery worker protection protocols. Southeast England and the Midlands concentrate motorcycling populations, with Birmingham and Manchester dealers expanding fitting services for connected safety systems.
Japan
Tokyo's motorcycle parking scarcity and dense urban fabric create demand for compact protective equipment that stores efficiently. METI promotes advanced safety technology adoption through consumer awareness campaigns and standardization initiatives. The Kanto region around Tokyo and Osaka's Kansai hub host the primary dealer networks, with Nagoya's Chubu manufacturing corridor supplying sensor and gas inflator components to European assemblers.
Wearable Airbag Belt Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend from motorcycling into equestrian and industrial verticals. The vendor base concentrates among European specialists with proven deployment records and Asian component suppliers scaling sensor and inflator manufacturing. Three archetypes define positioning: heritage motorcycling brands with dealer channel control, equestrian specialists with event-sanctioned products, and industrial safety suppliers penetrating warehouse logistics. Competitive moves center on backward integration into textile sourcing and firmware development partnerships with semiconductor vendors.
Within the heritage motorcycling tier, Dainese and Alpinestars occupy positions where brand equity commands premium pricing and specialty store placement. Helite exemplifies the equestrian specialist archetype through event-proven product lines. Among Asian component suppliers, Mugen Denko represents the gas inflator manufacturing concentration that supplies European system assemblers. These named entities anchor industry-level commentary on geographic specialization and vertical scope without ascribing specific strategic actions or financial performance to individual firms.
| Leading Market Players |
|---|
| Dainese |
| Helite |
| Alpinestars |
| Hovding |
| In&motion |
| Point Two Air Vest |
| S-Airbag Technology |
| Wolk Airbag |
| Mugen Denko |
| Others |
Pricing and Supply Chain Analysis
CO2 cartridge manufacturing in Austria and Czechia feeds through three-tier pricing structures across premium, standard, and economy levels, with gas inflator reliability commanding premium positioning while mechanical trigger variants serve price-sensitive motorcyclists in Southern Europe.
Pricing Analysis
Volume concentrates in Smart Belt configurations with connectivity subscriptions, while margins peak in Sport Belt ultralight designs where weight reduction below 800 grams justifies premium positioning. Price differentiation hinges on CE marking tier and firmware validation depth, with Category III PPE certification extending development costs that compress economy-tier margins. Pricing pressure stems from reusable motorcycle body armor competition in budget segments. Fleet procurement by Dutch and German courier services demonstrates lowest price sensitivity; individual retail cyclists exhibit highest.
Supply Chain Analysis
Embedded systems engineering talent scarcity in Germany and France constrains R&D scaling for sensor fusion calibration, forcing manufacturers to concentrate firmware development in Munich and Paris metropolitan clusters. Component sourcing draws from Austrian gas inflator specialists, Czechia mechanical trigger producers, and Japanese IMU array suppliers. Single-source vulnerability in European gas inflator manufacturing creates supply chain risk. Distribution runs through direct manufacturer negotiations with fleet operators in Rotterdam and Berlin, bypassing traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable airbag belt competition is consolidating around captive control of textile finishing and firmware development, with REACH compliance deadlines forcing in-house polymer treatment capabilities that separate solvent from survivors.
For Market Incumbents: Acquire gas inflator manufacturing capacity to secure deployment mechanism supply against Austrian and Czechia concentration risk. Deepen CE marking expertise to compress certification timelines as EU PPE Regulation enforcement tightens, defending against mid-tier entrants lacking dedicated regulatory affairs capacity.
For New Entrants and Emerging Players: Capture warehouse logistics fall-protection specifications in German distribution centers before occupational safety protocols crystallize around incumbent products. Target industrial-rated Safety Belt variants with reinforced tethering points, leveraging distributor relationships with existing construction site safety suppliers.
For Investors and Strategic Acquirers: French equestrian mandate passage is the leading indicator that regulatory pull mechanics are replicating motorcycle helmet law dynamics in adjacent verticals. Five-to-ten-year viability favors specialists with proven deployment records across multiple use cases. Watch Dutch and German fleet procurement consolidation rates as volume concentration signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Textile Sourcing | Dainese's European polymer finishing absorbs REACH testing costs that compress outsourcing-dependent competitors. |
| Firmware Development Partnership | Semiconductor vendor alliances compress detection-to-inflation intervals below 80 milliseconds for premium motorcycling positioning. |
| CE Marking Pathway Investment | Third-party conformity assessment capacity reduces Category III PPE certification timelines by 8-14 months. |
| Fleet Procurement Direct Negotiation | Rotterdam and Berlin courier mandates consolidate volume through centralized safety program administration. |
| Equestrian Event Sanctioning Partnership | Proven deployment records in competitive riding create regulatory pull comparable to motorcycle helmet laws. |
Research Methodology
Document review covered EU PPE Regulation implementation guidance, KBA two-wheeler registration databases, and Dutch insurer premium reduction frameworks, complemented by interviews with motorcycling dealer network managers, industrial safety procurement leads at German logistics operators, equestrian event sanctioning body officials, and wearable airbag system firmware engineers. Secondary validation drew from CE marking conformity assessment body reports, REACH compliance documentation, and fleet procurement contract structures. Bottom-up shipment estimates triangulated against top-down addressable user base calculations.
Historical adoption curves in motorcycling safety equipment cross-referenced against panel input from component suppliers and end-user procurement committees across the analysis window. Segmentation modeling spanned product type, end user, technology architecture, and distribution channel dimensions. CAGRs derived from slope-consistent trajectory fitting against documented insurance incentive expansion and fleet mandate adoption curves. Forecast inputs incorporated e-bike commuter growth in Copenhagen and Amsterdam infrastructure development.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to French equestrian mandate timing, CO2 cartridge supply disruption, and e-bike classification standardization. Assumptions reflect current regulatory enforcement intensity and fleet procurement concentration patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market