
 Middle East and Africa Pin-Based Access Control Market | 2026-2036
Middle East and Africa Pin-Based Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pin-Based Access Control Market Insights
Biometric-grade keypad authentication is reorganizing procurement priorities across the Middle East and Africa. Johnson Controls International PLC leverages its building automation heritage to anchor integrated security platforms in Gulf commercial towers. Honeywell International Inc competes through in-house production of encryption modules that sustain compliance with evolving regional data protection standards. dormakaba Group specializes in wireless retrofit solutions that navigate the fragmented legacy infrastructure prevalent across older African metropolitan facilities.
Pin-based access control denotes entry management systems where users authenticate via numeric code input on electronic or electromechanical keypads, typically operating on 12-24V DC power with relay outputs for door strikes or magnetic locks. These systems serve primary commercial and institutional security functions across facilities requiring tiered authorization without credential media. Electronic keypads capture expanding share in new Saudi and UAE construction, while mechanical locks retain dominance in price-sensitive African residential markets. Networked systems command premium positioning in government facilities, whereas standalone solutions occupy the retrofit channel across mid-tier commercial buildings in North African urban centers.
Saudi Arabia's SFDA and South Africa's national communications regulator shape product certification pathways for data-handling access devices, with encryption standards tightening across Gulf Cooperation Council jurisdictions. The UAE's MOHAP and local civil defense authorities enforce fire-safety integration protocols that dictate keypad system wiring specifications in high-rise developments. Stakeholders must monitor divergence between Gulf cybersecurity mandates and sub-Saharan Africa's fragmented enforcement landscape when configuring regional product portfolios.
Market Dynamics
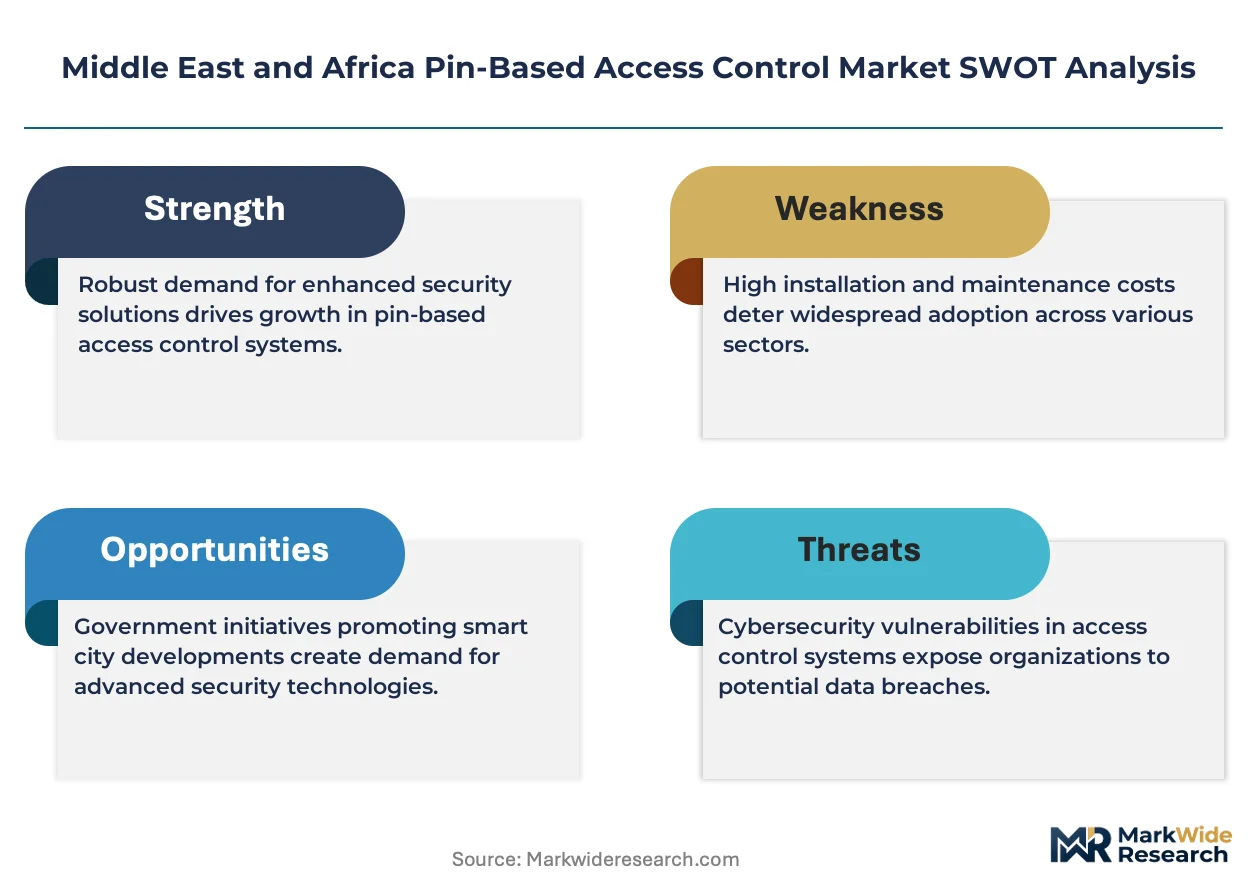
Smart city infrastructure investments across Gulf Cooperation Council states are accelerating adoption of integrated access systems, while cybersecurity mandates from South Africa's national regulator are compressing product certification timelines and reshaping vendor compliance strategies.
Growth Catalysts
- Saudi megaproject developments:Integrated access systems anchor security frameworks for new economic zones, creating sustained demand for keypad authentication infrastructure.
- SFDA encryption mandates:Saudi Arabia's pharmaceutical and data security regulator tightens standards for credential-handling devices, forcing upgrades across commercial installations.
- Wireless retrofit technology:Battery-powered keypad solutions eliminate wiring constraints in older African metropolitan facilities, expanding addressable market scope.
Market Restraints
- Semiconductor input volatility:Microcontroller shortages disrupt production schedules for electronic keypad manufacturers serving North African markets.
- Mechanical lock substitution:Electromechanical alternatives retain dominance in price-sensitive African residential segments, capping electronic system penetration.
- Fragmented enforcement landscape:Sub-Saharan Africa lacks unified certification pathways, forcing vendors to navigate multiple national approval processes.
Strategic Opportunities
- Egyptian commercial retrofit channel:Mid-tier buildings in Cairo and Alexandria present untapped demand for standalone keypad solutions replacing legacy mechanical systems.
- Biometric-keypad convergence:Multi-factor authentication combining PIN entry with fingerprint readers opens premium positioning in UAE government facilities.
- MOHAP fire-safety integration:UAE health authority mandates for emergency egress systems create bundled procurement opportunities for keypad vendors with certified integration capabilities.
Industry Challenges
- Cybersecurity skill scarcity:Local system integrators across the Gulf lack expertise in encryption module configuration, slowing deployment of networked access platforms.
- Legacy infrastructure incompatibility:Older African metropolitan facilities require extensive electrical upgrades to support 12-24V DC keypad installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pin-Based Access Control Market |
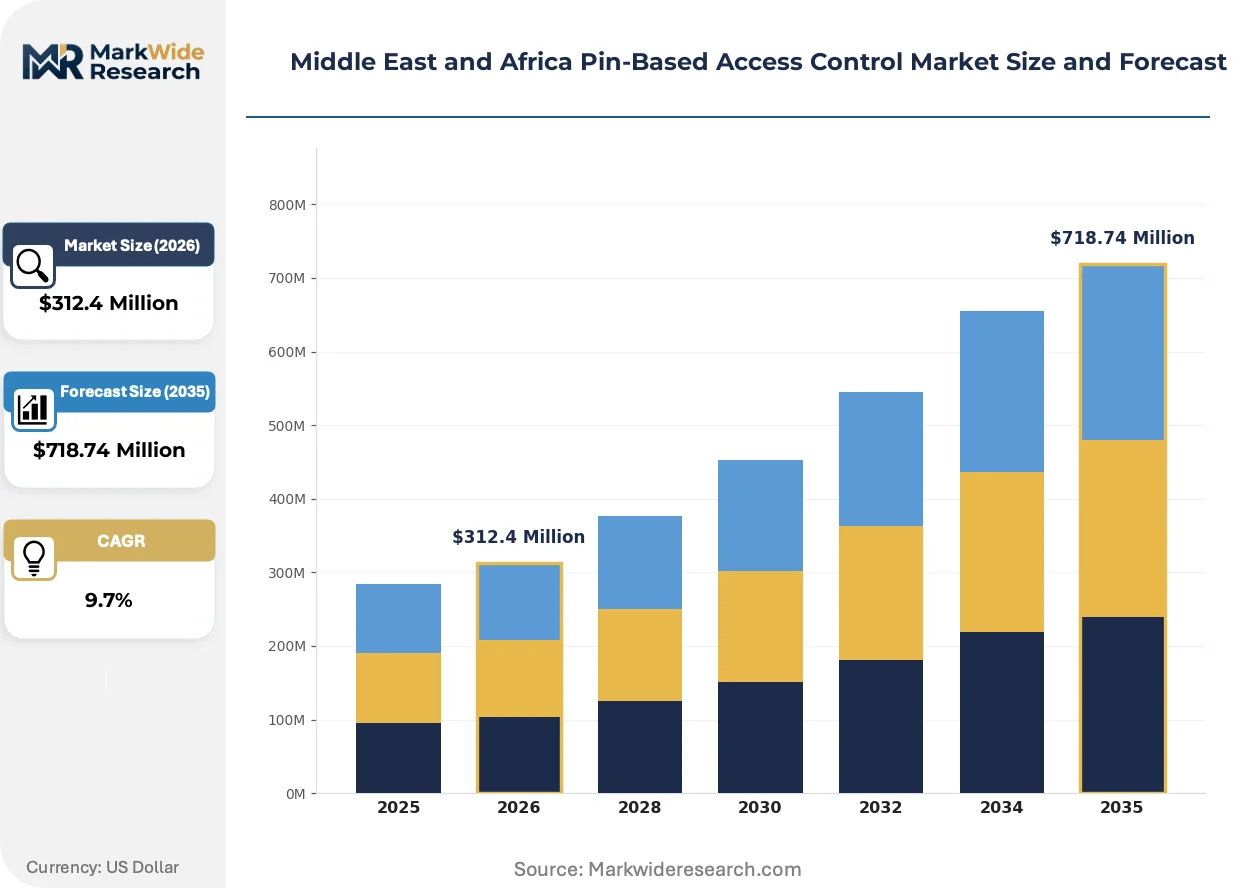
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Locks, Mechanical Locks, Electronic Keypads, Smart Card Readers End User: Commercial Buildings, Residential Properties, Government Facilities, Educational Institutions Technology: Fingerprint Recognition, RFID, Biometric Access, Keypad Entry Installation: Standalone Solutions, Networked Systems, Integrated Systems, Wireless Solutions |
| Companies Covered | Johnson Controls International PLC, Honeywell International Inc, Bosch Security and Safety Systems, Hangzhou Hikvision Digital Technology Co Ltd, Axis Communications AB, HID Global Corporation, Thales Group, dormakaba Group, Avigilon Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pin-Based Access Control Market Trends and Innovations
Authentication architecture across the Middle East and Africa is splitting between high-assurance biometric hybrids and cost-optimized standalone keypads, with regulatory pressure and construction economics driving divergent investment patterns.
Cloud-connected keypad controllers is bifurcating the installed base across Gulf commercial towers. Property managers in Dubai and Riyadh deploy these systems for centralized credential management across multi-tenant developments. This technology is compressing margins for standalone device vendors while enabling recurring revenue streams for platform providers.
South Africa's national communications regulator enforces encryption standards for data-handling access devices that exceed baseline ISO requirements. Manufacturers must re-engineer firmware architectures to achieve type approval. Government facilities and financial institutions represent the primary affected segments, with procurement specifications now mandating certified modules.
Facility managers increasingly unbundle after-sales service from initial hardware procurement, signing separate multi-year maintenance contracts with specialized integrators. This shift disrupts traditional distribution channels where distributors bundled installation support. The pattern is most visible in Saudi Arabia's megaproject developments, where owner-operators prioritize operational continuity over upfront cost minimization.
Middle East and Africa Pin-Based Access Control Market Segmentation
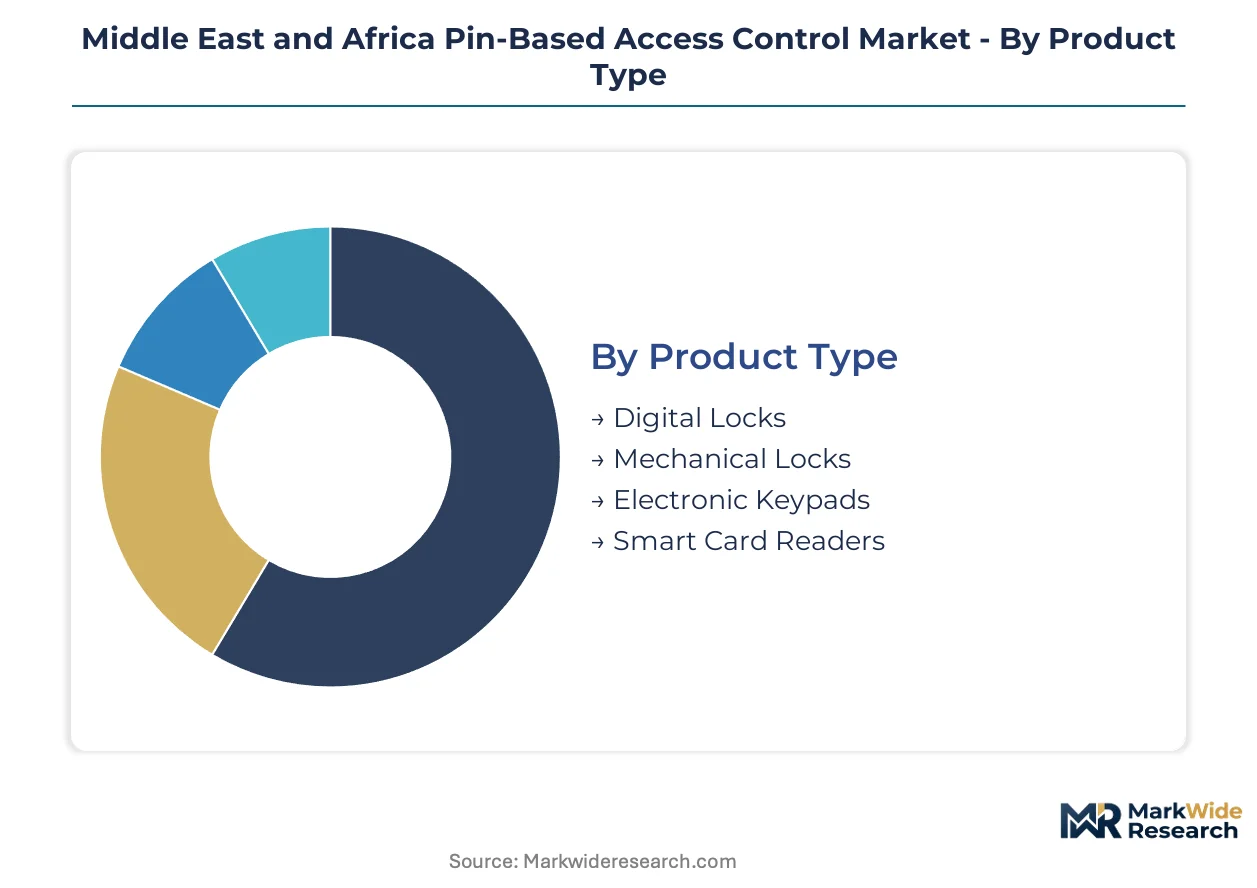
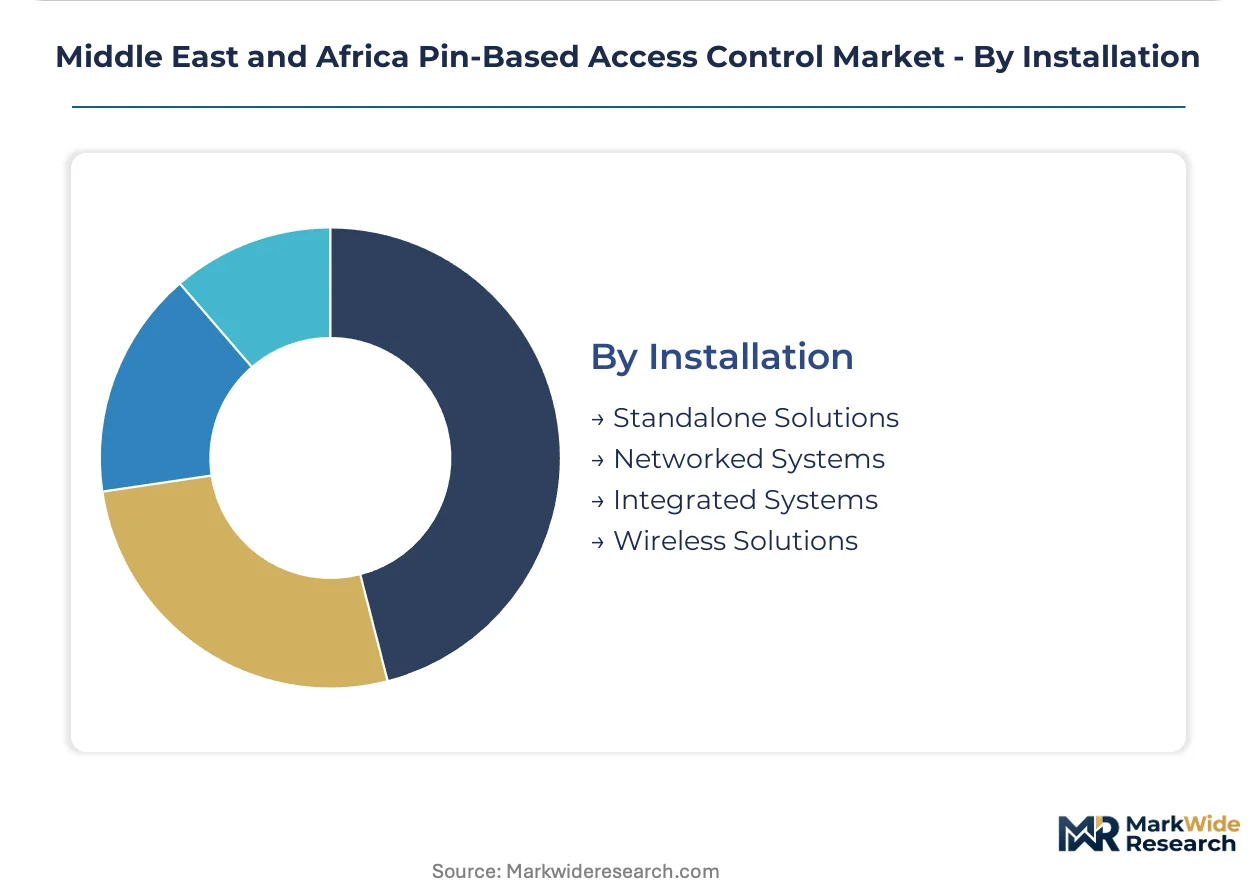
Segmentation in the Middle East and Africa pin-based access control market reveals divergent technology lifecycles and regulatory pressure points. Procurement patterns split between Gulf states demanding networked integration and African markets prioritizing cost-efficient standalone deployment.
Product Type:
Mechanical locks face the strongest substitution pressure as electronic alternatives capture commercial retrofit contracts across North African urban centers and Saudi megaproject developments.
- Digital Locks:These units integrate microcontroller-based credential validation with relay outputs for electromagnetic strikes. Demand concentrates in Dubai's multi-tenant commercial towers, where property managers prioritize centralized override capabilities during emergency egress scenarios.
- Electronic Keypads:12-24V DC powered devices with tactile or capacitive input interfaces dominate new construction specifications. Saudi Arabia's SFDA encryption mandates are accelerating replacements across pharmaceutical manufacturing facilities and data-handling installations.
- Mechanical Locks:Electromechanical and pure mechanical units retain dominance in price-sensitive residential segments across sub-Saharan African metropolitan areas.
- Smart Card Readers:Contact and contactless credential readers serve high-throughput environments requiring audit trails.
Mechanical locks retain volume leadership across the broader regional installed base; electronic keypads hold the steepest expansion curve in Gulf commercial construction.
End User:
Cost tier stratification separates premium-specification government procurement from economy-tier residential installations navigating fragmented African distribution channels.
- Commercial Buildings:Office complexes, retail centers, and hospitality properties deploy networked keypad systems with building automation integration. Cairo and Alexandria mid-tier buildings present untapped retrofit demand as legacy mechanical systems reach replacement cycles.
- Government Facilities:Ministries, defense installations, and critical infrastructure sites mandate biometric-grade authentication with certified encryption modules. South Africa's national communications regulator has tightened type-approval timelines for data-handling devices serving this segment.
- Residential Properties:Gated communities and multi-family housing across Gulf Cooperation Council states increasingly specify wireless keypad entry for amenity access.
- Educational Institutions:Universities and K-12 facilities balance security requirements against constrained capital budgets.
Commercial buildings command the largest addressable market; government facilities are climbing the fastest as cybersecurity mandates harden procurement specifications.
Technology:
Application requirements drive divergence between high-assurance biometric hybrids and cost-optimized credential-free keypad entry across facility security frameworks.
- Keypad Entry:Pure PIN-based authentication systems serve tiered authorization without credential media. These units anchor security frameworks in Saudi economic zones where integrated access platforms must interface with fire-safety and building management protocols.
- Biometric Access:Fingerprint, iris, and facial recognition modules combine with keypad input for multi-factor authentication. UAE government facilities specify these systems for zones requiring identity verification beyond possession of a code.
- Fingerprint Recognition:Standalone biometric readers serve high-security checkpoints with template storage on-device.
- RFID:Proximity and smart card technologies persist in legacy installations and mixed-credential environments.
Keypad entry maintains the broadest installed base; biometric access is gaining share fastest where MOHAP and SFDA data protection standards apply.
Installation:
Customer type segmentation separates owner-operators prioritizing operational continuity from facility managers seeking minimal upfront capital deployment.
- Networked Systems:IP-connected controllers enable centralized credential management, audit logging, and remote diagnostics. Property managers in Riyadh and Dubai deploy these across multi-tenant developments to compress operational overhead.
- Wireless Solutions:Battery-powered keypad units eliminate conduit requirements in older African metropolitan facilities lacking 12-24V DC infrastructure. dormakaba Group and similar specialists target this channel with retrofit-focused product architectures.
- Standalone Solutions:Self-contained keypad locks with local memory serve mid-tier commercial buildings and residential applications across North African urban centers.
- Integrated Systems:Hardwired platforms interfacing with fire alarms, CCTV, and building automation command premium positioning in Gulf high-rise developments.
Standalone solutions retain volume leadership in sub-Saharan price-sensitive markets; networked systems are expanding most quickly in Gulf smart city infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for electronic keypad systems clusters in the UAE and Saudi Arabia, where Gulf Cooperation Council investment flows concentrate assembly operations. Regional procurement splits between Gulf states demanding networked building automation integration and African markets prioritizing cost-efficient standalone deployment.
Saudi Arabia
NEOM and Red Sea Project developments generate concentrated demand for integrated access platforms with fire-safety interoperability. The Saudi Food and Drug Authority mandates encryption certification for credential-handling devices in pharmaceutical manufacturing zones. Riyadh's commercial tower construction anchors the largest addressable market for networked keypad controllers.
United Arab Emirates
Dubai's multi-tenant commercial properties deploy cloud-connected keypad systems for centralized credential management across portfolios. The Ministry of Health and Prevention enforces emergency egress integration protocols that dictate wiring specifications in high-rise healthcare facilities. Abu Dhabi's government district procurement specifies biometric-grade authentication for ministry installations.
South Africa
Financial institutions and critical infrastructure operators drive replacement cycles for encryption-certified access devices. The national communications regulator enforces type-approval standards exceeding baseline ISO requirements for data-handling systems. Johannesburg's commercial retrofit channel presents sustained demand as legacy mechanical systems reach end-of-life.
Egypt
Mid-tier commercial buildings in Cairo and Alexandria navigate replacement cycles for aging mechanical lock infrastructure. The country's national construction regulator issues fire-safety codes that increasingly reference electronic access integration in new high-rise specifications. New Administrative Capital development projects incorporate networked keypad systems in government facility clusters.
Nigeria
Lagos commercial property managers deploy standalone keypad solutions across banking and telecommunications facilities with constrained capital budgets. The national standards organization maintains fragmented enforcement of electronic security device certification. Port Harcourt's oil and gas sector procurement prioritizes ruggedized keypad hardware for harsh environment installations.
Middle East and Africa Pin-Based Access Control Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa pin-based access control market. Gulf commercial towers demand integrated platform providers with building automation heritage, while African price-sensitive segments favor specialists in wireless retrofit hardware. Three archetypes dominate: multinational conglomerates with encryption module production, European specialists in wireless battery-powered solutions, and Asian manufacturers scaling cost-optimized electronic keypads. Competitive moves center on strategic partnerships with regional system integrators and portfolio diversification into biometric-keypad convergence products.
Among conglomerate-tier providers, Johnson Controls International PLC and Honeywell International Inc occupy positions anchored by building automation integration capabilities. dormakaba Group represents the European specialist archetype focused on wireless retrofit architectures. These three companies exemplify the strategic segmentation between integrated platform provision and targeted hardware specialization.
| Leading Market Players |
|---|
| Johnson Controls International PLC |
| Honeywell International Inc |
| Bosch Security and Safety Systems |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Axis Communications AB |
| HID Global Corporation |
| Thales Group |
| dormakaba Group |
| Avigilon Corporation |
| Others |
Pricing and Supply Chain Analysis
Assembly scale economies in UAE and Saudi manufacturing clusters concentrate production capacity among Gulf-based fabricators, compressing unit economics for electronic keypad controllers while establishing price floors that tether African import markets to regional supply hubs. This geographic concentration amplifies pricing power for integrated platform providers serving megaproject developments, while fragmenting procurement leverage for standalone device vendors navigating sub-Saharan distribution channels.
Pricing Analysis
SFDA encryption mandates dictate the pricing tier structure across Saudi pharmaceutical and data-handling installations, separating biometric-grade certified modules from standard electronic keypads. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Asian manufacturers are scaling microcontroller production for price-sensitive African residential segments. Government facilities in the Gulf demonstrate the least price sensitivity due to cybersecurity compliance requirements, while mid-tier commercial buildings in North African urban centers exhibit acute procurement cost discipline.
Supply Chain Analysis
Container availability constraints on Asia-Gulf trade lanes elevate inbound logistics costs for microcontroller and relay component shipments, compressing margins for distributors serving Nigerian and Egyptian retrofit channels. Manufacturing concentrates in China, South Korea, and Taiwan for semiconductor inputs, while UAE and Saudi Arabia host final assembly operations for Gulf commercial tower deployments. The supply chain draws from Chinese PCB fabrication, German electromagnetic strike components, and South Korean capacitive touch sensors. Single-source vulnerability in encryption module sourcing poses structural risk for vendors seeking South African type approval. Distribution runs through regional system integrators in Riyadh and Dubai, with secondary channels reaching Lagos and Cairo via fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa pin-based access control market sits in early-cycle recovery as Gulf smart city infrastructure investments accelerate following pandemic-delayed project restarts. Megaproject construction timelines in Saudi Arabia and the UAE provide the cyclical anchor.
For Market Incumbents: Secure encryption module certification pathways ahead of SFDA and South African communications regulator deadline compressions. Defend installed base in Dubai multi-tenant towers through backward integration into cloud-connected controller platforms, neutralizing standalone vendor margin erosion from battery-powered retrofit alternatives. For New Entrants and Emerging Players: Differentiate on wireless retrofit architectures targeting Cairo and Alexandria mid-tier commercial buildings where legacy mechanical lock replacement cycles concentrate demand. Penetrate the Egyptian standalone keypad segment through specialized integrator partnerships, bypassing congested Gulf procurement channels dominated by incumbent building automation platforms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform providers with Gulf commercial tower maintenance contracts extending operational continuity guarantees. Five-to-ten year viability favors vendors with certified fire-safety integration capabilities serving MOHAP-regulated healthcare facilities. Monitor dormakaba Group's wireless retrofit penetration rates across African metropolitan facilities as inflection signal for standalone solution addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric-Keypad Convergence Product Launch | SFDA and MOHAP data protection standards mandate multi-factor authentication in government facilities. |
| Wireless Retrofit Channel Partnership | Cairo and Alexandria mid-tier buildings present replacement demand for aging mechanical infrastructure. |
| Encryption Module Certification Investment | South Africa's national communications regulator exceeds baseline ISO requirements for data-handling devices. |
| Cloud-Connected Platform Integration | Dubai property managers prioritize centralized credential management across multi-tenant portfolios. |
| Fire-Safety System Bundling | UAE health authority emergency egress protocols create procurement opportunities for certified integrators. |
Research Methodology
Desk research of customs trade databases, Gulf construction project registries, and national regulator certification filings preceded structured interviews with security system integrators, facility management executives, and building automation procurement officers across Riyadh, Dubai, Johannesburg, and Cairo. Primary fieldwork with dormakaba Group distribution partners and Honeywell International Inc regional technical directors validated secondary estimates. Bottom-up unit shipment modeling triangulated against top-down construction spend allocation across the analysis window.
Variance decomposition across product type, end user, technology, and installation architecture segments informed volume and value outputs over the projection horizon. CAGRs were derived from regression-based elasticity modeling against Gulf Cooperation Council infrastructure investment flows and African urbanization rates. Industry-specific inputs included SFDA encryption mandate compliance timelines and MOHAP fire-safety integration protocol adoption curves.
Material uncertainties — semiconductor input volatility, regulatory divergence between Gulf and sub-Saharan enforcement landscapes, megaproject construction delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding credential-handling device replacement cycles and wireless retrofit technology penetration trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
US Access Control Market
Access Control Systems
Italy Access Control Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market