

Residential Smart Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Smart Lock Market Insights
The EU Cyber Resilience Act is realigning product development priorities across the residential smart lock supply chain by mandating baseline cybersecurity certification for connected devices sold in member states. Assa Abloy leverages its architectural hardware heritage to dominate European commercial-to-residential channel crossover. Xiaomi competes on ecosystem integration, embedding smart locks within its broader home automation platform. Spectrum Brands anchors North American retail distribution through big-box home improvement chains.
A residential smart lock is an electromechanical locking device that replaces or augments traditional mechanical cylinders with motorized bolt actuation, typically operating on battery power with wireless communication protocols such as Bluetooth Low Energy or Z-Wave at sub-gigahertz frequencies, and designed to grant or restrict physical entry to dwellings through credential verification including PIN codes, biometric templates, or mobile token authentication. Deadbolt locks occupy the largest installed base due to straightforward retrofit compatibility with standard North American door preparations. Wi-Fi-enabled units represent the fastest-growing technology segment as cloud-based remote management becomes standard for vacation rental operators and distributed property managers. Multi-family units concentrate margin pools through bulk procurement contracts and ongoing software-as-a-service subscription attach.
The FCC governs radio frequency emissions for wireless smart lock protocols in the United States, while the EU Cyber Resilience Act and GDPR collectively shape product security architecture and data handling practices across European markets. California's SB-327 IoT security law imposes additional password and vulnerability disclosure requirements that manufacturers must address for access to that state. Stakeholders should monitor evolving insurance industry premium structures, as underwriters increasingly weigh connected device security certifications in residential policy pricing.
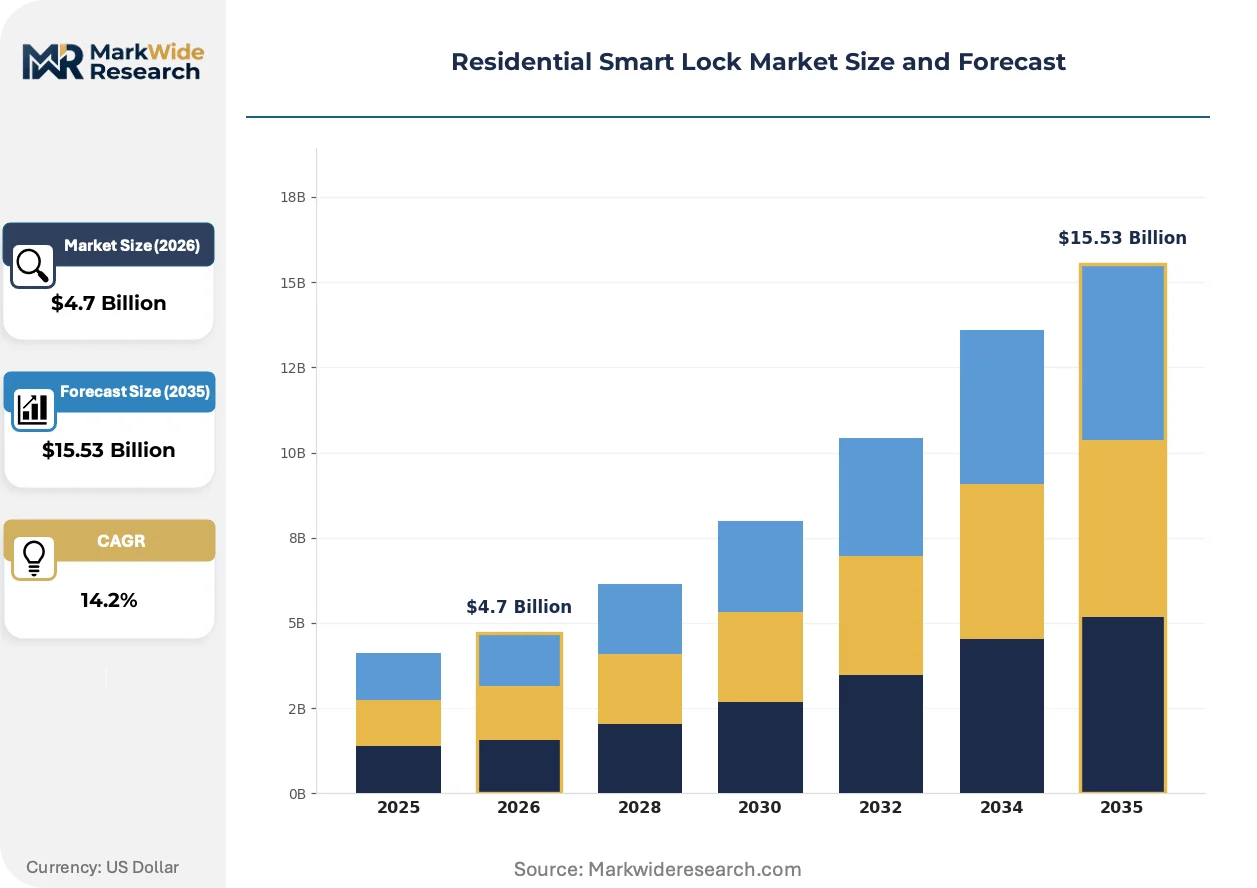
Market Dynamics
The EU Cyber Resilience Act is compressing product development timelines across the residential smart lock supply chain by mandating mandatory cybersecurity certification for all connected devices sold in member states. This regulatory pressure is forcing manufacturers to re-architect firmware security layers and vulnerability disclosure protocols before market entry.
Growth Catalysts
- GDPR data-handling mandates:European privacy requirements are accelerating demand for edge-computing lock architectures that process biometric templates locally rather than transmitting raw data to cloud servers.
- Vacation rental operators:Short-term rental platforms are driving Wi-Fi-enabled unit adoption as remote access provisioning becomes a standard guest amenity across the United States.
- Bluetooth Low Energy 5.3:Extended range and improved power efficiency in the latest protocol revision are enabling battery life extension without hardware cost increases.
Market Restraints
- Lithium battery supply concentration:Cell production clustering in East Asia creates input cost volatility and logistics risk for battery-powered lock manufacturers.
- California SB-327 compliance burden:The state's IoT security law imposes unique password complexity and vulnerability disclosure requirements that fragment firmware development for the US market.
- Mechanical key override:Consumer preference for physical backup access limits full-electronic adoption and preserves hybrid product cost structures.
Strategic Opportunities
- Multi-family housing software-as-a-service:Bulk procurement contracts with property management platforms create recurring revenue attach through access-log analytics and tenant onboarding tools.
- India smart city infrastructure:Government digitization initiatives for urban housing are opening municipal procurement channels for connected access control in affordable housing developments.
- Matter protocol convergence:Cross-platform interoperability between Apple HomeKit, Google Home, and Amazon Alexa is expanding into smart locks and reducing ecosystem lock-in friction.
Industry Challenges
- Firmware security engineering talent:Shortage of embedded systems developers with cryptographic implementation expertise is slowing certification timelines for EU Cyber Resilience Act compliance.
- Legacy access control integration:Property management software platforms require API development resources to synchronize smart lock credentials with existing tenant databases.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Smart Lock Market Trends and Innovations
Wireless protocol maturation and biometric sensor cost reduction are simultaneously expanding functional capabilities and compressing price bands across the residential smart lock category. These forces are reshaping competitive differentiation from hardware reliability toward software ecosystem depth.
Ultrasonic fingerprint sensing is expanding into mid-tier residential smart locks after proving durability advantages in commercial banking applications. Vacation rental operators are adopting these units fastest due to high turnover rates that accelerate capacitive sensor wear. The technology is expanding into price segments previously served by PIN-only entry, compressing the premium tier's addressable market.
The EU Cyber Resilience Act's mandatory vulnerability disclosure requirements are forcing manufacturers to establish formal security incident response teams and public bug bounty programs. European market access now depends on documented secure development lifecycle processes. Deadbolt retrofit products face the steepest compliance costs due to their higher installed base and longer firmware support obligations.
Property managers are consolidating vendor relationships around platforms that unify access control with rent collection and maintenance ticketing. Independent smart lock manufacturers without software integration capabilities are losing procurement decisions to ecosystem providers. This concentration is most visible in the United States, where institutional multifamily ownership creates volume purchasing power that extracts API customization and white-label app development from suppliers.
Residential Smart Lock Market Segmentation
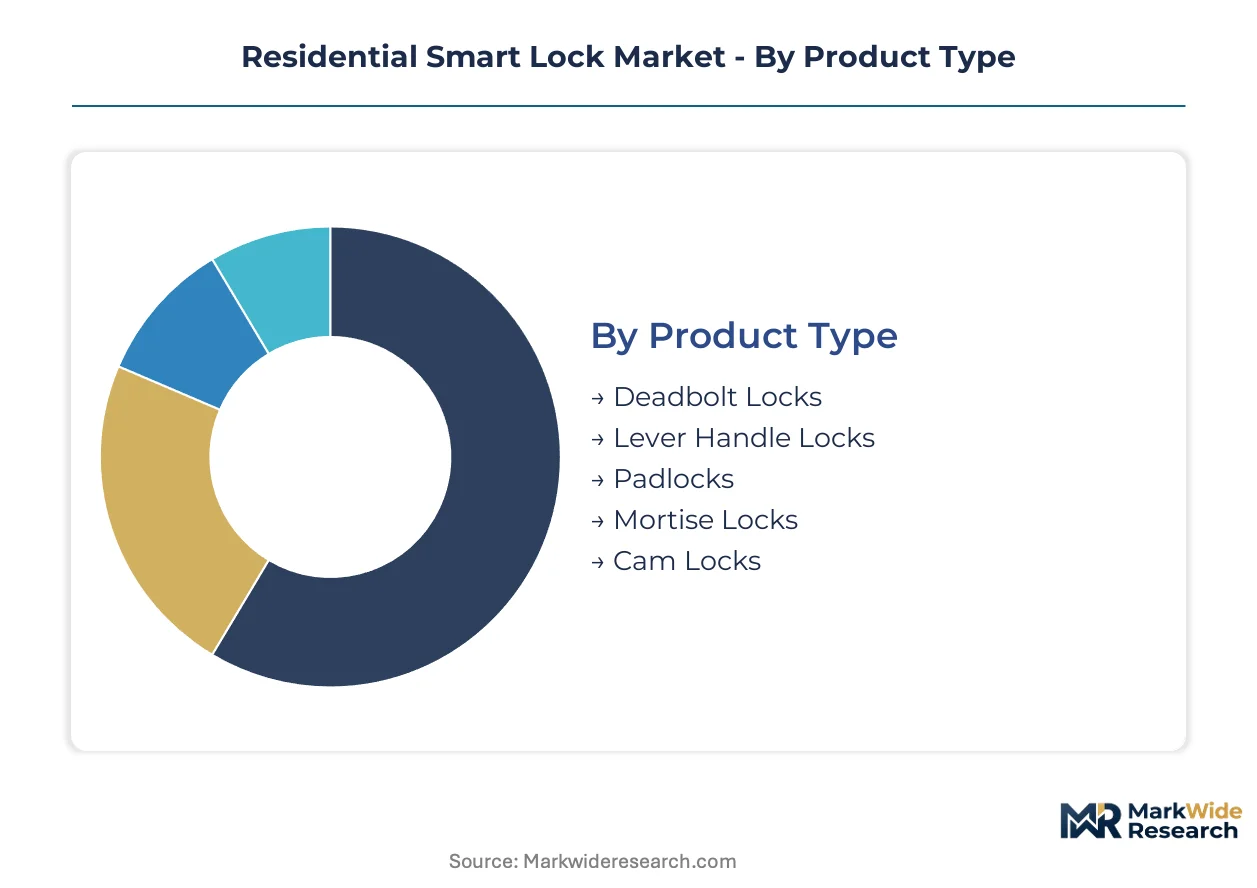
Smart lock purchasing decisions diverge sharply across installation contexts, with retrofit compatibility driving homeowner choices while remote management capabilities dominate commercial procurement. Technology selection follows application requirements rather than feature maximization, creating distinct competitive arenas within each segment.
Product Type:
Retrofit complexity shapes buyer preference more than aesthetic differentiation, with standard door preparation dictating viable options for each installation scenario.
- Deadbolt Locks:Electromechanical units replace existing single-cylinder deadbolts without door modification, utilizing standard bore holes and strike plates. North American single-family retrofits concentrate demand here, though consumer insistence on mechanical key override preserves hybrid cost structures.
- Lever Handle Locks:Integrated handle-and-lock assemblies require full door replacement or extensive modification, limiting adoption to new construction and major renovations. Multi-family developers in Germany and the Netherlands specify these for unified lobby-to-unit aesthetic standards.
- Padlocks:Battery-powered hasp-mounted units serve gates, storage units, and detached structures without wired power access.
- Mortise Locks:European commercial-to-residential conversions favor these for their superior security ratings and fire-door compatibility.
- Cam Locks:Compact cabinet and mailbox applications represent a niche segment with limited smart feature integration.
Volume sits with deadbolt configurations; growth tilts toward lever handle locks as multi-family construction accelerates.
Technology:
Power budget and connectivity range determine protocol selection, with battery life constraints eliminating Wi-Fi for certain deployment scenarios.
- Bluetooth:Low Energy 5.3 protocols enable smartphone proximity unlocking with minimal power draw, supporting 12-18 month battery cycles. Single-family homeowners in the United States and Canada default to this option for its simplicity and absence of subscription fees.
- Wi-Fi:Direct cloud connectivity enables real-time access logging and remote credential issuance without hub dependency. Vacation rental operators across Florida, Arizona, and California mandate this capability for guest self-check-in workflows.
- Z-Wave:Sub-gigahertz mesh networking penetrates building materials more effectively than 2.4 GHz protocols, suiting multi-family concrete construction.
- Zigbee:IEEE 802.15.4-based mesh integrates with broader home automation ecosystems including Philips Hue and Amazon Echo.
- NFC:Near-field credentialing supports hospitality-style keycard access for senior living and student housing applications.
- RFID:Passive tag systems persist in budget-conscious bulk deployments where smartphone penetration assumptions fail.
Bluetooth dominates installed base; Wi-Fi expands most quickly as property management platforms consolidate around cloud-native architectures.
Application:
Occupancy turnover frequency and access credential volume differentiate hardware and software requirements across residential contexts.
- Single-family Homes:Owner-occupied installations prioritize family member convenience over administrative features, with biometric and PIN entry gaining preference among households with children.
- Multi-family Units:Institutional ownership creates procurement concentration, with software-as-a-service subscription attach becoming standard in Class A apartment buildings across Texas and Georgia.
- Vacation Properties:Short-term rental platforms drive Wi-Fi-enabled adoption for automated guest code generation and cleaning crew scheduling.
- Student Housing:Semester-based turnover demands bulk credential reprogramming capabilities and integration with campus identity systems.
- Co-living Spaces:Flexible lease terms and communal area access requirements favor platform-integrated solutions with granular permission controls.
Single-family homes anchor volume; vacation properties generate the steepest technology upgrade cycles.
End User:
Technical sophistication and procurement scale separate consumer self-installation from enterprise-managed deployment patterns.
- Homeowners:Retail channel purchasers prioritize installation simplicity and brand recognition, with Amazon and home improvement chains capturing the majority of transactions.
- Property Managers:Multi-site operators extract volume discounts and API customization from vendors, consolidating vendor relationships around unified tenant portals.
- Real Estate Agents:Showing access convenience drives adoption for lockbox replacement, with Supra and SentriLock interoperability requirements influencing selection.
- Vacation Rental Operators:Platform integration with Airbnb and Vrbo becomes a hard requirement, with automated messaging and review solicitation features valued above hardware specifications.
- Facility Supervisors:Corporate housing and extended-stay properties require audit trails and liability documentation that consumer-grade products inadequately support.
Homeowners represent the largest addressable population; property managers concentrate margin through recurring software attach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors smart lock hardware manufacturing, hosting the densest cluster of Bluetooth module suppliers and biometric sensor integrators serving both domestic Chinese demand and export markets.
United States
Vacation rental operators in Florida and Arizona drive Wi-Fi-enabled adoption for automated guest check-in workflows. California's SB-327 imposes unique password complexity and vulnerability disclosure requirements that fragment firmware development. Austin and Atlanta concentrate property management platform headquarters where smart lock APIs integrate with unified tenant portals.
Germany
Multi-family developers in Berlin and Hamburg specify lever handle locks for unified lobby-to-unit aesthetic standards. The EU Cyber Resilience Act mandates baseline cybersecurity certification for all connected devices sold in member states. Munich hosts commercial-to-residential channel crossovers where architectural hardware heritage transfers to smart lock product lines.
China
Mass-market ecosystem integration propels Xiaomi's home automation platform penetration in tier-one cities. MIIT governs radio frequency emissions for wireless protocols under national GB standards. Shenzhen's Pearl River Delta corridor supplies Bluetooth Low Energy modules and fingerprint sensors to global lock manufacturers.
Netherlands
Smart city infrastructure pilots in Amsterdam test connected access control for social housing digitization. GDPR data-handling mandates accelerate demand for edge-computing architectures that process biometric templates locally. Eindhoven's technology corridor hosts Zigbee protocol development centers influencing multi-family mesh networking specifications.
India
Government smart city initiatives for urban housing open municipal procurement channels in affordable housing developments. BIS certification requirements shape product entry pathways for imported connected devices. Bangalore's technology cluster incubates property management software startups integrating access control with rent collection platforms.
Residential Smart Lock Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software ecosystem depth and certification compliance capabilities. Architectural heritage manufacturers leverage commercial-to-residential channel crossover against consumer electronics brands competing on platform integration. Three archetypes dominate: ecosystem platform owners, commercial hardware heritage players, and retail distribution anchors. Consolidation pressure intensifies through API customization demands from institutional property managers and mandatory cybersecurity certification timelines.
Within the commercial heritage tier, Assa Abloy and dormakaba occupy positions where architectural hardware expertise transfers to residential smart lock specifications. Xiaomi exemplifies the ecosystem platform archetype, embedding locks within broader home automation environments. Spectrum Brands anchors retail distribution concentration through big-box home improvement channel relationships. These three patterns illustrate how competitive positioning separates on software integration depth rather than mechanical reliability alone.
| Leading Market Players |
|---|
| Assa Abloy |
| Allegion |
| Spectrum Brands |
| dormakaba |
| Honeywell International |
| Samsung Electronics |
| Xiaomi |
| ZKTeco |
| Salto Systems |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EU Cyber Resilience Act-compliant units and legacy inventory creates divergent margin structures across the residential smart lock supply chain. Premium-tier vendors command sustained pricing power through mandatory cybersecurity documentation while commodity producers face margin compression from firmware re-engineering costs and extended support obligations.
Pricing Analysis
Outcome-based pricing anchored to tenant turnover efficiency dominates property management procurement decisions. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified ecosystem locks from Bluetooth-only units and unconnected mechanical-electronic hybrids. Price differentiation hinges on SaaS subscription attach rates and API customization depth. Cost compression in the economy tier is intensifying because Shenzhen-based module suppliers are absorbing Bluetooth 5.3 chipset cost declines. Vacation rental operators exhibit lowest price sensitivity due to labor savings from automated guest provisioning.
Supply Chain Analysis
Embedded systems engineering talent shortages in Shenzhen and Dongguan are constraining firmware development capacity for EU certification timelines. Hardware assembly concentrates in China's Pearl River Delta, with biometric sensor sourcing from South Korean fabs and lithium cell supply anchored in East Asian production networks. The supply chain rests on single-source vulnerability for ultrasonic fingerprint modules where commercial banking demand competes for constrained foundry slots. Distribution runs through big-box retail chains in North America and property management platform direct procurement in institutional multi-family segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential smart lock market sits in a protocol-transition phase where Matter interoperability is displacing ecosystem-locked legacy architectures. Wi-Fi-enabled cloud-native platforms are supplanting hub-dependent Z-Wave installations in commercial procurement.
For Market Incumbents: Cement firmware security engineering capabilities through acquisition of embedded cryptography specialists before EU Cyber Resilience Act enforcement windows tighten. Lock in multi-family SaaS subscription renewals by embedding access-log analytics into property management platform APIs. The threat of Matter protocol commoditization demands defensive ecosystem integration investments.
For New Entrants and Emerging Players: Begin with white-label manufacturing partnerships for Indian affordable housing smart city tenders where BIS certification barriers remain surmountable. Target student housing operators in Texas and Georgia with semester-credentialing software bundles. A direct-to-property-manager channel strategy bypasses retail slotting fee disadvantages against Spectrum Brands and Allegion.
For Investors and Strategic Acquirers: Re-rating potential sits with commercial-to-residential crossover specialists given EU regulatory tailwinds favoring architectural hardware heritage. Long-term viability over a multi-year horizon favors vendors with in-house secure development lifecycle documentation. The signal to watch is insurance premium differentiation for Cyber Resilience Act-certified installations.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Cyber Resilience Act Certification Investment | Mandatory cybersecurity documentation unlocks European member state market access for connected devices. |
| Matter Protocol Integration | Cross-platform interoperability with Apple HomeKit and Amazon Alexa reduces ecosystem switching costs. |
| Property Management Platform API Development | Unified tenant portal integration captures recurring SaaS revenue from institutional multi-family operators. |
| Ultrasonic Fingerprint Sensor Adoption | Durability advantages over capacitive alternatives address high-turnover vacation rental operator requirements. |
| Edge-Computing Biometric Architecture | Local template processing satisfies GDPR mandates without cloud transmission liability exposure. |
Research Methodology
Regulatory filings with the FCC and EU Cyber Resilience Act draft documentation, SEC 10-K disclosures from Allegion and Assa Abloy, and property management software platform technical specifications formed the secondary backbone. Primary interviews with smart lock product managers, firmware security engineers, institutional property management procurement directors, and vacation rental platform integration specialists combined with secondary validation. Bottom-up and top-down triangulation cross-checked unit shipment estimates against Bluetooth SIG certification databases and Z-Wave Alliance membership rolls.
Bottom-up modeling aggregated segment-level assumptions across product type, connectivity protocol, and application vertical throughout the forecast period. Segmentation dimensions included deadbolt versus lever handle configurations, Bluetooth versus Wi-Fi versus Z-Wave technology tiers, and single-family versus multi-family versus vacation rental end-use contexts. CAGRs were derived from logistic diffusion curves fitted to smart home penetration benchmarks. Forecast inputs incorporated EU Cyber Resilience Act implementation timelines and California SB-327 compliance cost estimates.
Underlying measurement precision varies by segment; Wi-Fi-enabled vacation rental applications carry tighter precision than emerging market affordable housing pilots due to data availability. Forecasts reflect documented assumptions about regulatory enforcement timing and protocol adoption curves. Material deviation in EU certification deadlines or Matter protocol uptake rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.