
 Crash Barrier Systems Market | 2026-2036
Crash Barrier Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Crash Barrier Systems Market Analysis
Steel mill capacity additions in India and Southeast Asia are rebalancing raw material availability for barrier manufacturers. Tata Steel leverages its integrated steel operations to supply high-tensile grades for w-beam systems. Hill & Smith Holdings PLC anchors European distribution through its permanent barrier fabrication network. Nucor Corporation competes on mini-mill flexibility, serving North American highway authorities with just-in-time coil deliveries.
Crash barrier systems are roadside safety structures engineered to contain or redirect errant vehicles through controlled deformation, typically fabricated from galvanized steel conforming to EN 1317 or MASH test levels for impact energy absorption. Their primary purpose is reducing fatalities on high-speed corridors by dissipating kinetic energy through rail deflection and post-breakaway mechanisms. Steel barriers dominate mature highway networks where lifecycle cost calculations favor durability over upfront expenditure, while wire rope barriers gain share on undivided rural routes where installation speed and worker safety matter. Concrete barriers retain margin concentration in airport perimeters and bridge parapet retrofits where deflection tolerance approaches zero.
The US Federal Highway Administration enforces MASH compliance for federal-aid projects, forcing state DOTs to retire pre-2002 barrier designs and restock inventories. India's IRC SP: 99 and BIS certification requirements for road safety hardware are tightening product approval timelines for imported systems. China's Ministry of Transport GB standards mandate vehicle crash-testing at specific speed classes for all national trunk highway installations. Stakeholders must monitor evolving test-speed thresholds and local-content rules as procurement shifts from specification compliance toward whole-life performance contracting.
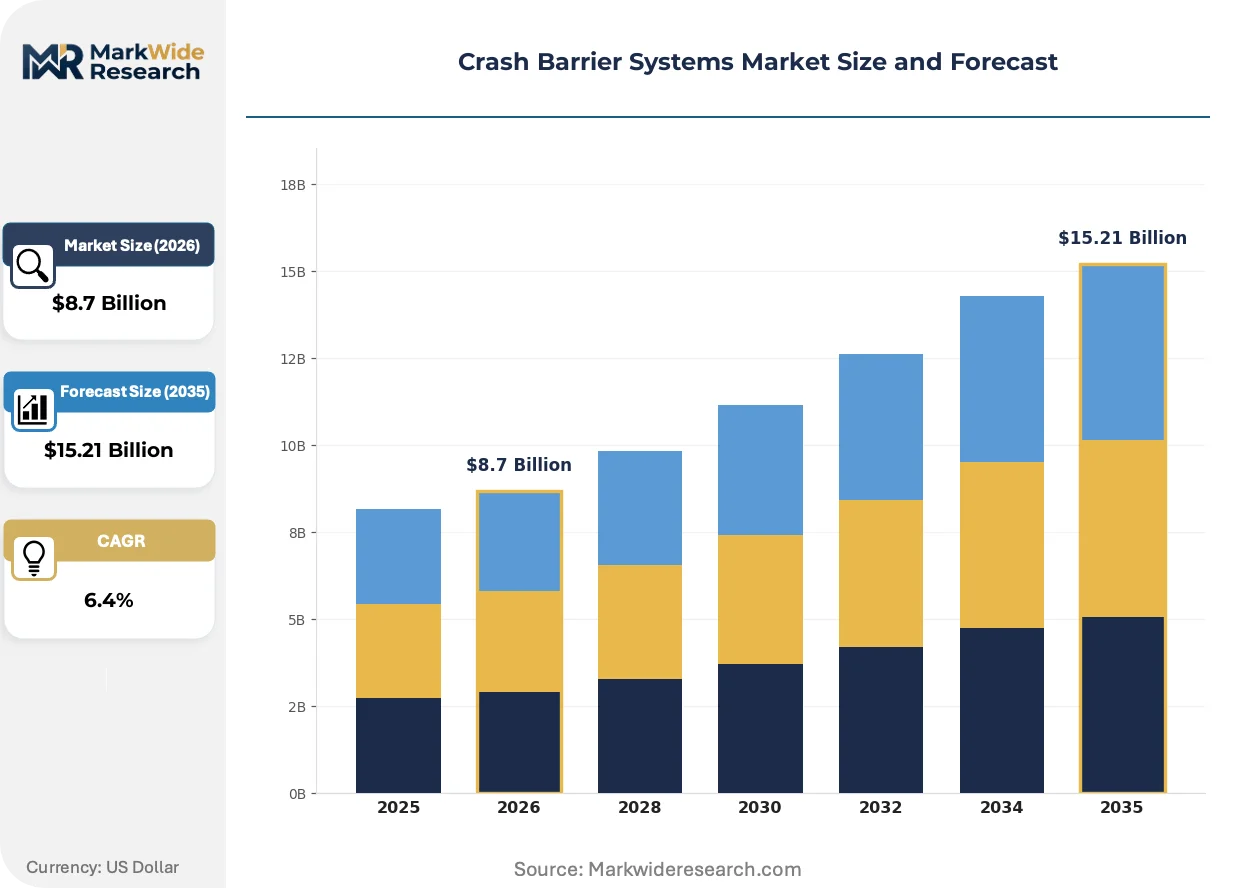
Market Dynamics
Highway authorities are retiring legacy barrier inventories faster than replacement supply chains can scale, creating procurement bottlenecks for MASH-compliant and EN 1317-certified systems while steel coil lead times stretch across fabricator networks.
Growth Catalysts
- IRC SP: 99 Mandates:India's Ministry of Road Transport and Highways enforces stricter crash-testing protocols, forcing state agencies to upgrade roadside hardware on national highways and expressway corridors.
- Wire Rope Technology:Tensioned cable barriers reduce installation labor by half on undivided rural routes, accelerating adoption among county road departments in high-incident corridors.
- China Expressway Expansion:Provincial transport bureaus in Sichuan and Yunnan are procuring energy-absorbing terminals for mountainous highway segments with severe run-off risks.
Market Restraints
- Zinc Price Volatility:Hot-dip galvanizing costs swing with London Metal Exchange zinc futures, compressing fabrication margins for barrier coaters dependent on spot metal purchases.
- Steel Mill Concentration:Integrated producers in India and Southeast Asia control high-tensile coil supply, leaving smaller barrier fabricators exposed to allocation priorities during capacity tightness.
- Concrete Substitution:Precast parapet systems retain bridge retrofit work where deflection tolerance is zero, limiting steel barrier penetration in structural rehabilitation projects.
Strategic Opportunities
- Urban Retrofitting Corridors:Municipal authorities in Guangzhou and Chengdu are replacing aging guardrails on elevated ring roads with compliant systems as traffic volumes surge.
- Smart Highway Integration:Sensor-embedded barriers that communicate impact data to traffic management centers are attracting pilot deployments from autonomous vehicle testing zones.
- Performance Contracting:Whole-life cost models are displacing lowest-bid procurement in Australia's state road agencies, favoring suppliers with predictive maintenance capabilities.
Industry Challenges
- Certification Timeline Compression:BIS approval processes for imported road safety hardware are extending product qualification cycles, delaying market entry for non-domestic manufacturers.
- Welding Automation Deficit:Skilled robotic welder operators remain scarce across Indian fabrication shops, constraining output scaling for w-beam production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crash Barrier Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Barriers, Steel Barriers, Plastic Barriers, Wire Rope Barriers Application: Highway, Bridge, Airport, Urban Installation Method: Permanent, Temporary, Mobile, Integrated End User: Government, Construction Companies, Highway Authorities, Private Developers |
| Companies Covered | Trinity Industries, Inc., Tata Steel, Hill & Smith Holdings PLC, Roadsafe Traffic Systems, Inc., Transpo Industries, Inc., Valmont Industries, Inc., Lindsay Corporation, Avon Barrier Corporation Ltd, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crash Barrier Systems Market Emerging Trajectories
Barrier engineering is pivoting from passive containment toward active energy management, with material science and digital monitoring converging to reshape roadside safety architecture.
Polymer-composite rail elements are integrating into median barrier designs for their superior corrosion resistance in coastal and de-icing salt environments. State DOTs in Florida and California are specifying these systems for bridge approaches where steel deterioration accelerates maintenance cycles. This shift is integrating non-metallic alternatives into procurement specifications previously dominated by galvanized steel.
The US Federal Highway Administration's MASH 2016 updates are forcing inventory obsolescence across state maintenance yards, compelling agencies to restock with tested configurations. State DOTs are consolidating supplier pools to vendors with certified testing records, compressing the vendor base. California and Texas are leading compliance transitions, with their combined procurement volumes setting national specification precedents.
Buyers are unbundling installation from hardware supply, creating separate contracting lanes for specialized erection crews. County road departments in the Midwest are sourcing barriers directly from mills while hiring regional installers, bypassing traditional full-service distributors. This pattern is most pronounced in Iowa and Wisconsin, where seasonal construction windows demand flexible labor sourcing separate from material procurement schedules.
Crash Barrier Systems Market Segmentation
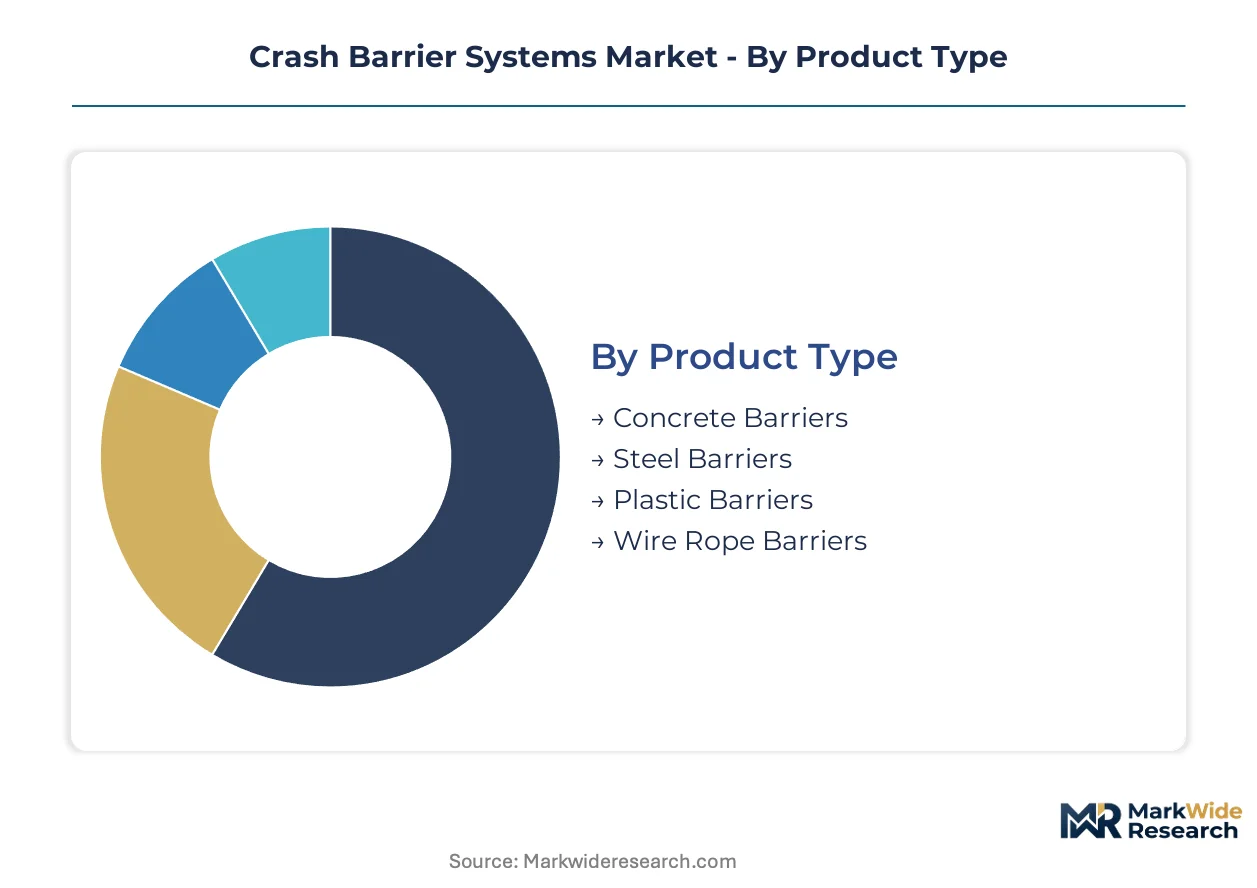
Crash barrier procurement splits across material specifications, deployment contexts, and contracting structures. Specification alignment with EN 1317 or MASH test levels determines vendor eligibility, while installation method shapes supply chain relationships and margin capture.
Product Type:
Material composition dictates energy absorption mechanics, lifecycle cost profiles, and corrosion resistance in coastal or de-icing environments.
- Concrete Barriers:Precast reinforced concrete systems deliver zero-deflection containment for bridge parapets and airport perimeters where vehicle penetration cannot occur. State DOTs in California and Texas specify these for median crossover elimination on high-volume corridors with severe run-off risks.
- Steel Barriers:Galvanized w-beam and thrie-beam configurations dominate federal-aid highway networks through controlled deformation and post-breakaway mechanisms. China's provincial expressway programs in Sichuan and Yunnan are procuring high-tensile grades for mountainous terrain where rail deflection must absorb heavy truck impact energy.
- Plastic Barriers:Water-ballasted polyethylene systems serve construction zone channelization with rapid deployment and repositioning capabilities.
- Wire Rope Barriers:Tensioned cable arrays reduce installation labor and material mass on undivided rural routes with limited setback corridors.
Mature deployment sits with steel barriers. Newer deployment is concentrated in wire rope systems.
Application:
Roadway geometry and speed environment determine containment level requirements and hardware specifications.
- Highway:High-speed divided corridors demand MASH TL-3 or EN 1317 H2W2 containment levels with energy-absorbing terminals. India's national highway upgrades under IRC SP: 99 mandates are accelerating procurement of tested configurations across Maharashtra and Gujarat state road agencies.
- Bridge:Structural rehabilitation projects favor rigid parapet systems where deflection tolerance approaches zero and foundation loading is constrained.
- Airport:FAA-compliant frangible systems protect runway approach zones with controlled collapse on aircraft impact.
- Urban:Municipal retrofitting in Guangzhou and Chengdu targets elevated ring roads with compliant systems as traffic volumes surge on aging infrastructure.
Highway applications command the steepest expansion trajectory. Bridge retrofits face substitution pressure from precast concrete alternatives.
Installation Method:
Contracting structure separates hardware supply from erection labor, reshaping distributor relationships.
- Permanent:Embedded post systems with soil plate foundations dominate interstate networks where 50-year design life justifies galvanized steel capital investment.
- Temporary:Surface-mounted or ballasted configurations serve work zone protection with seasonal redeployment across Midwest county road departments.
- Mobile:Vehicle-mounted attenuator trucks protect mobile maintenance crews on active traffic lanes.
- Integrated:Smart highway pilots embed sensor arrays for impact detection and autonomous vehicle corridor communication.
Permanent installation anchors volume. Mobile and integrated methods are gaining share in maintenance contracting and pilot deployments.
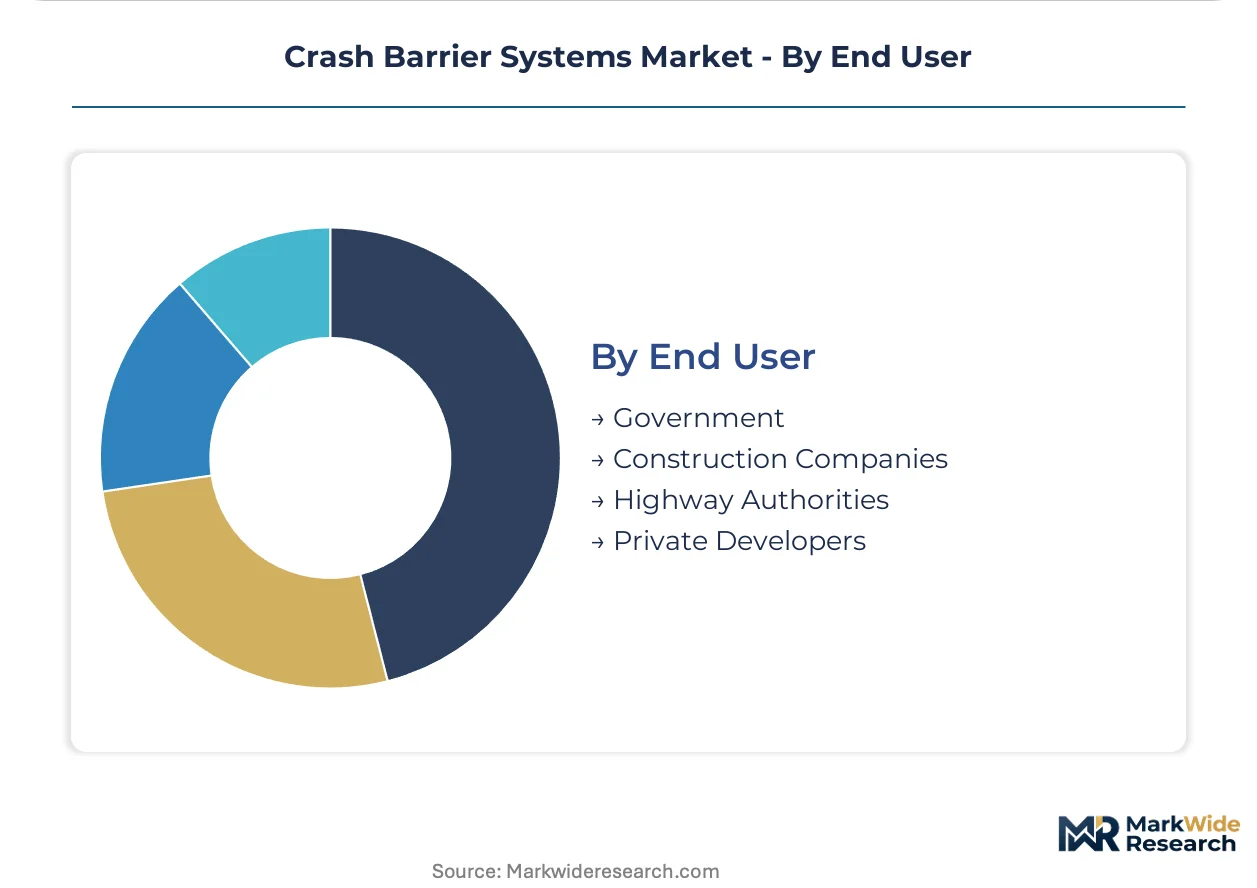
End User:
Procurement authority shapes specification stringency, vendor qualification requirements, and contract bundling preferences.
- Government:Federal and state transportation departments enforce MASH compliance with certified testing records, consolidating supplier pools to vendors with documented crash performance. The US Federal Highway Administration mandates inventory retirement of pre-2002 barrier designs.
- Highway Authorities:Australia's state road agencies are displacing lowest-bid procurement with whole-life performance contracting that favors predictive maintenance capabilities.
- Construction Companies:General contractors on design-build projects are unbundling hardware supply from installation, sourcing barriers directly from mills while hiring regional erection crews.
- Private Developers:Industrial park and logistics campus developers specify barriers for internal circulation roads with reduced test-level requirements compared to public networks.
Government procurement dominates specification-setting. Private developer volume is climbing fastest as industrial real estate expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-tensile steel coil availability from Indian and Southeast Asian mills anchors regional production capacity for barrier fabricators serving highway expansion programs across multiple continents.
United States
Federal-aid highway rehabilitation and state DOT inventory replacements drive procurement volumes. The Federal Highway Administration enforces MASH compliance, forcing retirement of pre-2002 barrier designs. Texas and California state transportation departments set national specification precedents through combined procurement volumes.
China
Provincial expressway expansion in mountainous western provinces accelerates demand for energy-absorbing systems. The Ministry of Transport GB standards mandate vehicle crash-testing at specific speed classes for national trunk highway installations. Sichuan and Yunnan transport bureaus concentrate procurement for high-incident corridor upgrades.
India
National highway upgrades under IRC SP: 99 mandates force state agencies to replace roadside hardware. The Ministry of Road Transport and Highways enforces stricter crash-testing protocols through BIS certification requirements. Maharashtra and Gujarat state road agencies anchor procurement volumes for tested barrier configurations.
Germany
Autobahn network maintenance and cross-border corridor standardization sustain demand for EN 1317-certified systems. The KBA and federal transport ministry coordinate test-level harmonization across EU member states. Industrial fabricators in the Ruhr region supply high-tensile grades for Central European highway authorities.
Australia
State road agencies displace lowest-bid procurement with whole-life performance contracting models. Transport departments in New South Wales and Victoria favor suppliers with predictive maintenance capabilities. Urban retrofitting corridors in Sydney and Melbourne target aging guardrail replacement on elevated roadways.
Crash Barrier Systems Market Vendor Landscape
Global majors compete with regional champions across fabrication capacity and certification depth, creating a tiered structure where scale advantages meet local regulatory intimacy. Steel-integrated players control upstream material flows while specialized barrier fabricators compete on testing records and installation speed. Two archetypes dominate: integrated steel producers with captive coil supply, and independent fabricators with certified MASH and EN 1317 portfolios. Competitive moves concentrate on backward integration into galvanizing operations and geographic expansion through distributor partnerships.
Among steel-integrated producers, Tata Steel and Nucor Corporation exemplify the upstream-control archetype, leveraging mill operations to secure high-tensile coil allocation. Hill & Smith Holdings PLC occupies a position within the specialized fabrication tier, anchoring European distribution networks through permanent barrier expertise. These three entities represent distinct strategic postures—captive raw material security versus testing-certification depth versus regional channel dominance.
| Leading Market Players |
|---|
| Trinity Industries, Inc. |
| Tata Steel |
| Hill & Smith Holdings PLC |
| Roadsafe Traffic Systems, Inc. |
| Transpo Industries, Inc. |
| Valmont Industries, Inc. |
| Lindsay Corporation |
| Avon Barrier Corporation Ltd |
| Nucor Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fabricators across India's western states anchor regional pricing discipline through captive galvanizing operations and long-term steel mill relationships, while private-equity-rolled-up specialists in North America unbundle installation labor to defend margin position against commodity zinc volatility.
Pricing Analysis
Warranty and crash-test certification bundling separates premium-tier suppliers from commodity fabricators competing on per-meter hardware quotes. Three-tier pricing structure across MASH-certified, EN 1317-compliant, and uncertified economy levels reflects testing investment amortization and after-sales service inclusion. Cost compression in economy-grade w-beam systems is intensifying because county road departments in the US Midwest source directly from mills. State DOT procurement offices show lowest price sensitivity due to whole-life performance mandates, while private developers of industrial parks exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
MASH and EN 1317 qualification gating restricts vendor pools to fabricators with documented crash-test records, concentrating compliant production in India, China, and Germany. High-tensile steel coil, zinc ingot for hot-dip galvanizing, and energy-absorbing terminal components constitute critical input dependencies. Single-source vulnerability runs through integrated steel mills in India and Southeast Asia that prioritize allocation to captive barrier operations during capacity tightness. Distribution runs through full-service distributors on federal-aid projects and direct mill relationships on unbundled county contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification depth and captive raw material security, with zinc price volatility and MASH compliance timelines forcing smaller fabricators into distressed exit or acquisition.
For Market Incumbents: Deploy backward integration into galvanizing operations to capture coating margin and insulate against London Metal Exchange zinc futures swings. State DOT supplier pool consolidation threatens independent fabricators without certified testing records; anchor channel control through exclusive distributor partnerships in Texas and California procurement corridors. Capacity addition in Indian high-tensile coil production secures allocation priority during mill tightness. For New Entrants and Emerging Players: Launch via unbundled hardware supply to Midwest county road departments bypassing traditional full-service distributors. Wire rope barrier technology in undivided rural routes offers the most penetrable white space, with installation labor reduction of half versus steel systems. Target Australia's state road agencies adopting whole-life performance contracting as the entry geography with lowest certification barrier and highest contract value potential. For Investors and Strategic Acquirers: Distressed-cycle entries favor EN 1317-certified mid-cap fabricators in Germany's Ruhr industrial region with underutilized testing capacity and established KBA relationships. Long-term viability rests on regulatory ratchet effects tightening crash-test protocols across multiple jurisdictions. Watch for BIS approval timeline compression in India as the inflection signal accelerating domestic consolidation and import substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing | Captures coating margin and hedges zinc price exposure for barrier fabricators serving federal-aid projects. |
| MASH Certification Investment | Unlocks state DOT supplier pool consolidation in Texas and California procurement corridors. |
| Wire Rope Technology Expansion | Reduces installation labor by half on undivided rural routes with limited setback corridors. |
| Smart Highway Pilot Deployment | Positions sensor-embedded barriers for autonomous vehicle testing zone infrastructure contracts. |
| Performance Contracting Capability Buildout | Aligns with Australia's state road agencies displacing lowest-bid procurement with whole-life models. |
Methodological Framework
Independent corroboration across barrier fabricator plant managers, state DOT procurement officers, steel mill sales directors, and highway authority engineering leads underwrites the qualitative findings. Primary interviews with galvanizing operation heads and aftermarket service managers combined with secondary validation from FHWA MASH compliance databases, IRC SP: 99 regulatory filings, EN 1317 test certification records, and customs trade data for high-tensile steel coil movements. Bottom-up fabrication capacity modeling and top-down highway expenditure forecasts triangulate volume estimates.
Rate-of-change decomposition across material type, application context, installation method, and end-user procurement authority structures the analytical framework. Segmentation dimensions modeled include steel grade tier, containment test level, contracting structure, and regional regulatory cluster. CAGRs derive from highway capital expenditure trajectories, inventory replacement cycles, and compliance deadline clustering. Zinc price volatility indices and steel mill capacity utilization feed raw material cost projections.
Regulatory test-speed threshold escalation, zinc futures volatility spikes, and BIS approval timeline extensions are the dominant revision risks to modeled forecasts. Forecasts reflect documented assumptions on compliance deadline adherence and highway authority budget execution rates. A model refresh is warranted upon material change in MASH update implementation schedules or IRC SP: 99 enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market