
 Global Digital Door Lock Systems Market | 2026-2036
Global Digital Door Lock Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Door Lock Systems Market Analysis
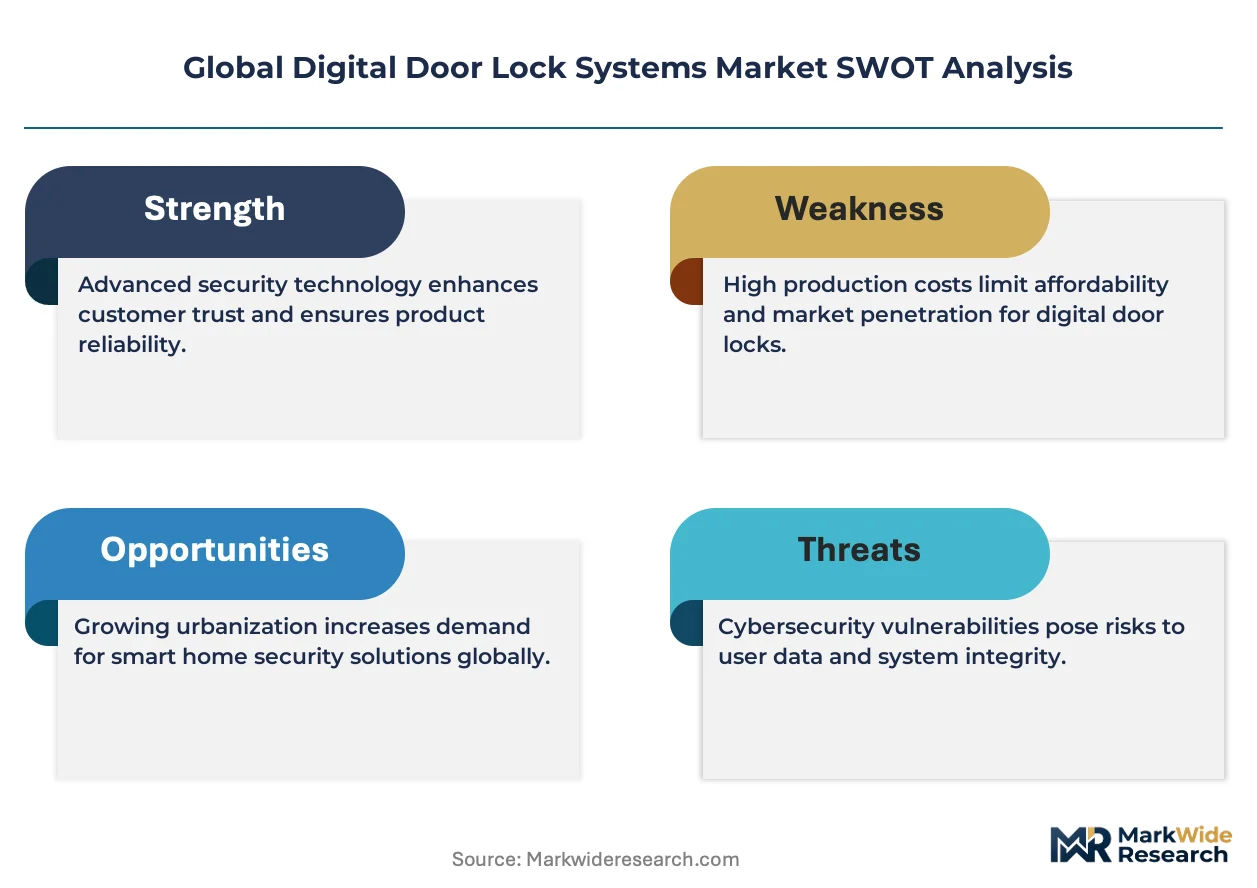
GDPR's data-protection mandates for biometric storage is realigning the cost-of-entry calculus for European vendors. ASSA ABLOY AB leverages its manufacturing scale across Nordic production facilities to sustain certification compliance. Allegion plc anchors its position through specialized commercial-grade encryption modules. Samsung SDS competes on semiconductor integration, controlling chip-to-lock design pipelines.
Digital door lock systems electromechanical entry devices that authenticate users through PIN codes, biometric sensors, or wireless credentials before actuating a motorized bolt mechanism with ANSI/BHMA Grade 1 or Grade 2 durability ratings. These systems primarily secure residential perimeters, commercial facilities, and institutional buildings while generating audit trails for access management. Biometric locks lead product-type margin pools due to fingerprint and facial recognition premiums, while smart locks represent the fastest-expanding category through Wi-Fi and Bluetooth connectivity integration. The hospitality end-user segment concentrates retrofit installations as hotels phase out magnetic-stripe systems.
The EU Cybersecurity Act and CE marking framework enforce baseline encryption standards for connected locks sold across member states, while the FDA regulates biometric data handling in healthcare-adjacent facilities. China's SAMR and GB standards mandate domestic cybersecurity certifications that foreign manufacturers must navigate for market access. Stakeholders must monitor evolving fragmentation between regional encryption protocols when allocating R&D budgets.
Market Dynamics
The hospitality sector's mandatory shift to contactless check-in protocols across Southeast Asian chains is compressing replacement cycles for legacy magnetic-stripe systems and redistributing procurement budgets toward biometric-capable entry devices.
Growth Catalysts
- EU Cybersecurity Act:The framework's baseline encryption standards for connected locks create compliance-driven replacement demand across member states as older devices lose CE marking eligibility.
- China's tier-one smart home clusters:Shanghai, Beijing, and Shenzhen exhibit residential penetration rates that outpace other metropolitan concentrations, concentrating volume demand for Wi-Fi integrated deadbolts.
- Biometric sensor miniaturization:Fingerprint and facial recognition modules achieve cost parity with PIN-pad alternatives in mid-range product tiers, expanding addressable market segments.
Market Restraints
- Semiconductor supply concentration:Discrete chip sourcing for motorized bolt actuators and wireless transceivers remains concentrated among East Asian foundries, exposing lead-time volatility.
- GDPR biometric storage mandates:The regulation's data-protection requirements for fingerprint and facial templates impose encryption infrastructure costs that compress margins for European vendors.
- ANSI/BHMA Grade 1 certification timelines:Extended durability testing protocols delay product launches by 8-14 months versus ungraded alternatives, constraining speed-to-market.
Strategic Opportunities
- India's residential retrofit wave:Urban gated community expansion in Bengaluru and Hyderabad creates first-mover positioning for Bluetooth-enabled locks compatible with existing smartphone penetration.
- Healthcare-adjacent facilities:FDA-regulated biometric data handling requirements in US hospital and clinic environments open specialized high-margin segments for audit-trail-capable systems.
- Matter protocol convergence:The interoperability standard's integration of Wi-Fi, Thread, and Zigbee protocols enables single-device compatibility across fragmented smart home ecosystems.
Industry Challenges
- Cybersecurity firmware talent scarcity:Embedded systems engineers with cryptographic implementation expertise command premium compensation, constraining R&D scaling for mid-tier manufacturers.
- Legacy mechanical infrastructure incompatibility:Pre-2000 door preparations in European commercial buildings lack standardized backset dimensions, requiring costly site-specific retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Door Lock Systems Market |
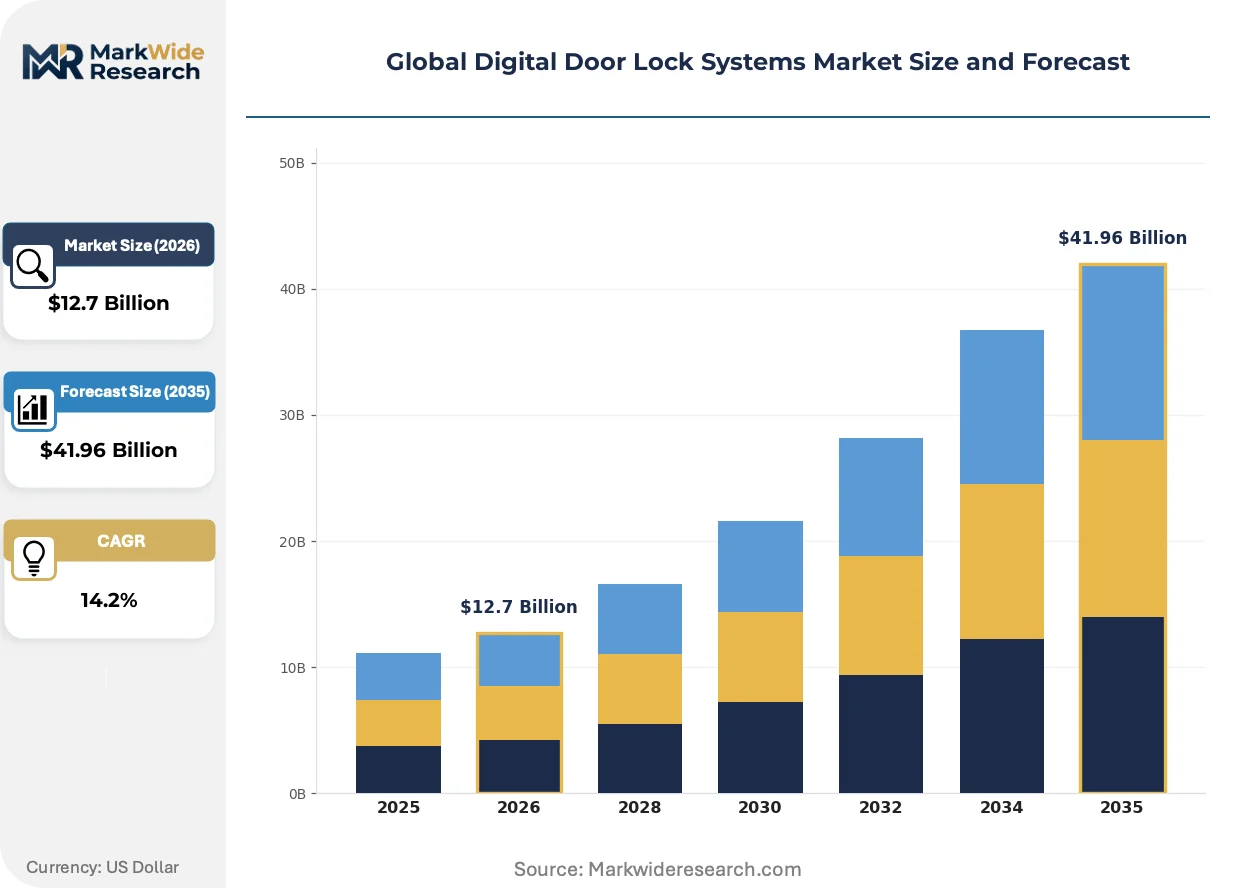
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keyless Entry, Biometric Locks, Remote Access, Smart Locks Technology: Z-Wave, Zigbee, Wi-Fi, Bluetooth End User: Residential, Commercial, Hospitality, Government Installation Type: New Installation, Retrofit, Integrated Systems, Standalone |
| Companies Covered | ASSA ABLOY AB, Allegion plc, Honeywell International Inc., Samsung SDS, dormakaba Group, Bosch Security Systems GmbH, Johnson Controls International plc, August Home, Inc., Kwikset Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Door Lock Systems Market Emerging Trajectories
Wireless credential authentication is displacing physical key management across enterprise facilities, while semiconductor integration and regulatory fragmentation reshape competitive differentiation. Three developments dominate the innovation landscape.
Facial recognition modules with 3D depth-sensing arrays are overtaking fingerprint sensors as the primary biometric modality in premium hospitality deployments. Marriott and Hilton properties across Singapore and Bangkok are standardizing touchless entry to meet post-pandemic hygiene expectations. This shift is compressing PIN-pad component demand and reallocating R&D budgets toward liveness-detection algorithms.
China's SAMR cybersecurity certification mandates for networked entry devices are fragmenting technical specifications between domestic and export-oriented product lines. Foreign manufacturers must maintain parallel firmware branches to satisfy GB standards that diverge from ISO/IEC 27001 baselines. The compliance burden falls heaviest on mid-volume suppliers lacking dedicated China regulatory teams.
Enterprise buyers are consolidating vendor relationships through master key system digitization, replacing fragmented mechanical keyway contracts with centralized cloud-based credential provisioning. Facility management firms in Germany's commercial real estate sector are unbundling hardware procurement from ongoing access-management subscriptions. This behavioral pivot concentrates purchasing authority among CIOs and away from traditional security contractors.
Global Digital Door Lock Systems Market Segmentation
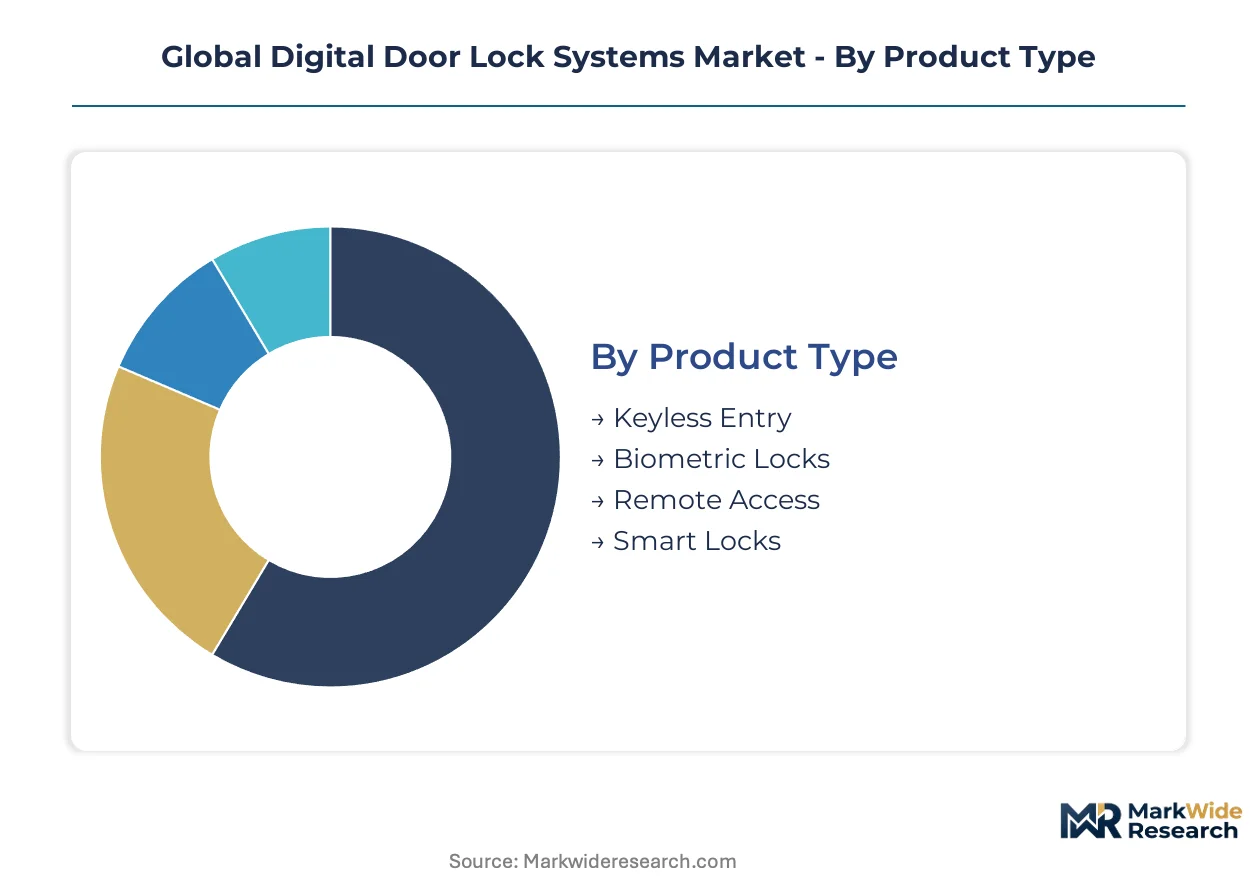
Segmentation in digital door lock systems reveals how component sourcing and assembly geography dictate competitive positioning across price tiers. Supply chain configuration directly shapes which technology combinations reach specific end-use verticals.
Product Type:
Electromechanical component sourcing concentrates among East Asian foundries, with motor and sensor procurement patterns determining which product categories achieve cost-effective scale.
- Biometric Locks:Fingerprint and facial recognition modules integrate 3D depth-sensing arrays with liveness-detection algorithms. Demand concentrates in Singapore and Bangkok hospitality properties where Marriott and Hilton properties mandate touchless entry protocols post-pandemic.
- Smart Locks:Wi-Fi and Bluetooth connectivity enables cloud-based credential provisioning and audit-trail generation. Shanghai, Beijing, and Shenzhen residential clusters drive volume as smart home penetration outpaces other metropolitan concentrations.
- Keyless Entry:PIN-pad authentication with motorized bolt actuation serves cost-sensitive commercial retrofits.
- Remote Access:Cellular and internet-connected locks enable centralized facility management across distributed real estate portfolios.
Today's leader: Biometric Locks. Tomorrow's challenger: Smart Locks.
Technology:
Wireless protocol adoption tracks directly against regional smart home ecosystem maturity and broadband infrastructure density.
- Wi-Fi:Direct router connectivity eliminates hub requirements for residential consumers. China's tier-one cities exhibit the densest deployment as fiber-to-home penetration enables reliable cloud connectivity for deadbolt systems.
- Bluetooth:Low-energy pairing with smartphones dominates India's Bengaluru and Hyderabad gated community retrofits where existing phone penetration exceeds dedicated smart home hub adoption.
- Zigbee:Mesh networking protocol integrates with Thread and Matter standards for cross-platform interoperability.
- Z-Wave:Sub-GHz frequency avoids Wi-Fi congestion in multi-dwelling commercial installations.
Current volume anchor: Wi-Fi. Fastest climb: Bluetooth.
End User:
Procurement authority varies sharply by vertical, with hospitality CIOs consolidating vendor relationships while residential purchasing remains fragmented.
- Hospitality:Enterprise buyers in Southeast Asian chains compress replacement cycles for magnetic-stripe systems through centralized cloud-based credential provisioning.
- Commercial:Germany's facility management firms unbundle hardware procurement from ongoing access-management subscriptions, shifting purchasing authority from security contractors to IT departments.
- Residential:Shanghai and Shenzhen smart home clusters concentrate demand for Wi-Fi integrated deadbolts among early-adopter households.
- Government:EU Cybersecurity Act compliance requirements drive CE-marked encryption standards for connected entry devices in institutional facilities.
Dominant spend pool: Hospitality. Steepest expansion trajectory: Commercial.
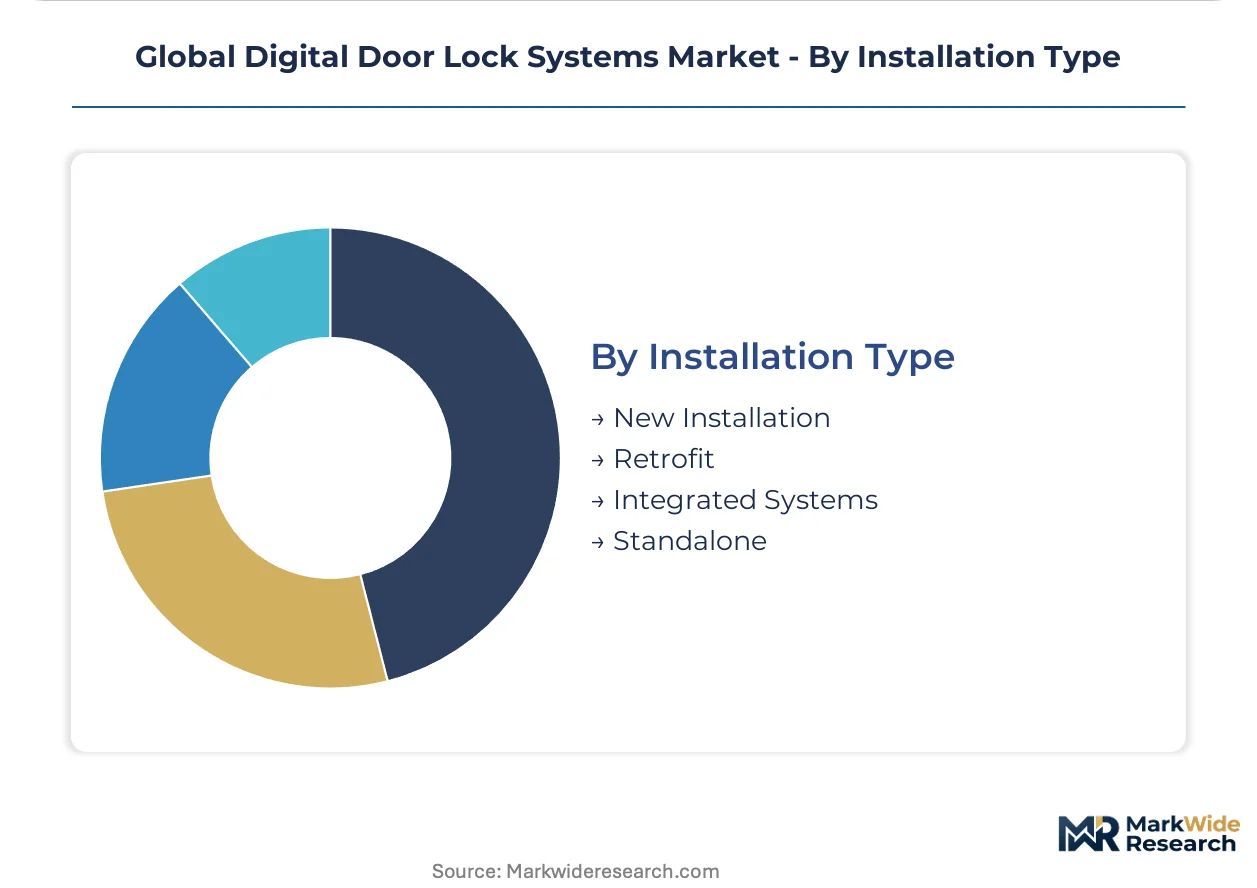
Installation Type:
Site preparation requirements and legacy infrastructure compatibility determine which installation modes achieve margin efficiency across regional building stocks.
- Retrofit:Adapters for non-standard backset dimensions in pre-2000 European commercial buildings require costly site-specific engineering but capture upgrade demand from mechanical keyway replacements.
- New Installation:Standardized door preparations in China's residential construction boom enable factory-optimized hardware with minimal field customization.
- Integrated Systems:Hardwired power and network connections serve enterprise facilities with centralized access control architecture.
- Standalone:Battery-powered units with local credential storage address connectivity-constrained deployments in emerging market perimeter security.
Margin concentration: Retrofit. Volume scaling: New Installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromechanical locking technology originated in Nordic and German industrial centers during the 1970s, with precision manufacturing clusters in Sweden and Bavaria establishing early design standards that persist in today's ANSI/BHMA certification frameworks. Contemporary demand patterns reflect this heritage while shifting toward Asia-Pacific production and consumption gravity.
United States
Enterprise facility managers and healthcare-adjacent institutions drive procurement of audit-trail-capable systems. FDA regulates biometric data handling in hospital and clinic environments, creating specialized compliance segments. Dallas and Atlanta commercial real estate corridors concentrate retrofit installations as property technology budgets expand.
Germany
Facility management firms unbundle hardware procurement from cloud-based access subscriptions, transferring purchasing authority to CIOs. CE marking and EU Cybersecurity Act encryption standards enforce baseline compliance for connected entry devices. Frankfurt and Munich commercial districts anchor enterprise-grade deployment volumes.
China
Shanghai, Beijing, and Shenzhen residential clusters exhibit smart home penetration rates that outpace other metropolitan concentrations. SAMR cybersecurity certification mandates for networked entry devices fragment technical specifications between domestic and export product lines. Pearl River Delta manufacturing bases supply motor and sensor components for global assembly.
India
Urban gated community expansion in Bengaluru and Hyderabad creates first-mover positioning for Bluetooth-enabled locks compatible with existing smartphone penetration. BIS standards govern electronic lock safety certifications for residential and commercial installations. Western India industrial corridors assemble cost-optimized units for domestic and export markets.
Singapore
Marriott and Hilton properties across Southeast Asian chains mandate touchless entry protocols, compressing replacement cycles for magnetic-stripe systems. Post-pandemic hygiene expectations accelerate facial recognition module adoption in premium hospitality deployments. The city-state's procurement standards influence specification requirements across ASEAN markets.
Global Digital Door Lock Systems Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive semiconductor or security system portfolios. Vendor concentration remains moderate, with tier-one players leveraging manufacturing scale for certification compliance and mid-tier specialists competing on regional customization. Two strategic archetypes dominate: Nordic-German precision manufacturers with integrated encryption module capabilities, and Asia-Pacific electronics conglomerates controlling chip-to-lock design pipelines. Dominant competitive moves include geographic expansion through localized certification acquisition and portfolio diversification into cloud-based access management subscriptions.
Among Nordic-based industrial groups, ASSA ABLOY AB anchors the precision manufacturing archetype through its manufacturing scale across regional production facilities. Allegion plc exemplifies the specialized commercial-grade encryption module approach. Samsung SDS occupies a position within the semiconductor-integrated design pipeline archetype, competing through chip-to-lock vertical control. These three representations illustrate how certification compliance, encryption specialization, and semiconductor integration constitute the primary vectors of differentiation.
| Leading Market Players |
|---|
| ASSA ABLOY AB |
| Allegion plc |
| Honeywell International Inc. |
| Samsung SDS |
| dormakaba Group |
| Bosch Security Systems GmbH |
| Johnson Controls International plc |
| August Home, Inc. |
| Kwikset Corporation |
| Others |
Supply Flow & Price Mechanics
Semiconductor integration into deadbolt actuation mechanisms is compressing component counts while concentrating procurement leverage among East Asian foundries with captive motor-controller fabrication. This consolidation simultaneously reduces per-unit material costs and amplifies exposure to single-source supply disruptions.
Pricing Analysis
The bundled-vs-unbundled service split between hardware-only transactions and cloud-based access subscriptions is fragmenting pricing architectures across vendor tiers. Three-tier pricing structure across premium, standard, and economy levels tracks ANSI/BHMA certification grades, with Grade 1 durability premiums widening against ungraded alternatives. Pricing pressure stems from biometric sensor commoditization in mid-range tiers. Hospitality procurement teams exhibit lowest price sensitivity due to compliance-driven replacement mandates, while Indian residential retrofits demand aggressive unit economics.
Supply Chain Analysis
Motorized bolt actuator sourcing rests on Taiwan, South Korea, and China for precision stepper motors, wireless transceivers, and 3D depth-sensing arrays. Discrete chip dependencies include BLE SoCs, capacitive fingerprint sensors, and liveness-detection ASICs. Single-source vulnerability concentrates in advanced biometric module fabrication. Distribution runs through OEM direct contracts for enterprise hospitality chains, regional security integrators for commercial retrofits, and e-commerce platforms for residential consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hospitality chains mandate biometric-capable entry devices with audit-trail functionality, compressing replacement cycles for legacy magnetic-stripe systems.
For Market Incumbents: Anchor certification compliance as the primary defensive moat by accelerating EU Cybersecurity Act CE marking acquisition ahead of eligibility deadlines for older devices. Deepen backward integration into semiconductor design pipelines to offset East Asian foundry concentration risk. Prioritize cloud-based access management subscription attach rates to capture recurring revenue streams unbundled from hardware procurement. For New Entrants and Emerging Players: India's BIS certification pathway for electronic lock safety opens a window for Bluetooth-enabled residential retrofits in Bengaluru and Hyderabad gated communities where smartphone penetration exceeds smart home hub adoption. Target healthcare-adjacent facilities with FDA-regulated biometric data handling requirements as the most penetrable high-margin segment. Pursue white-label manufacturing partnerships with Pearl River Delta assembly houses to bypass capital-intensive production infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialists with regional certification depth but limited semiconductor integration. Long-term viability favors vendors controlling chip-to-lock design pipelines or captive encryption module capabilities. Acquisition targets should demonstrate SAMR cybersecurity certification progress for China market access. Watch Matter protocol adoption rates as the inflection indicator for ecosystem consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acquisition | EU Cybersecurity Act CE marking preserves market access across member states as baseline encryption standards tighten. |
| Semiconductor Integration | Captive chip-to-lock design pipelines reduce exposure to East Asian foundry lead-time volatility for motorized actuators. |
| Cloud Subscription Unbundling | Separating hardware procurement from access-management subscriptions transfers purchasing authority to CIOs in German commercial real estate. |
| Biometric Module Miniaturization | 3D depth-sensing array cost parity with PIN-pad alternatives expands addressable market into mid-range hospitality retrofits. |
| Regional Regulatory Localization | Parallel firmware branches for China's SAMR GB standards versus ISO/IEC 27001 baselines enable domestic market penetration. |
Methodological Framework
Multiple input streams — facility management procurement directors, smart home platform engineers, hospitality CIOs, and semiconductor supply chain managers — were reconciled against regulatory filing databases and customs trade records. Primary interviews with ANSI/BHMA certification auditors and EU cybersecurity assessors complemented secondary validation through SAMR certification registries and FDA 510(k) device listings. Bottom-up unit demand estimates across installation types were triangulated with top-down spending analysis from enterprise real estate technology budgets.
Historical shipment data were cross-referenced against panel input from smart lock platform providers and electromechanical component distributors to construct the analytical framework. Segmentation dimensions modeled include product type, wireless protocol, end-user vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted replacement cycle analysis and smart home penetration rate trajectories. Forecast inputs incorporated Matter protocol adoption curves and biometric sensor cost decline trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or cybersecurity certification timeline extensions. A small set of named triggers warrants ongoing watch: EU Cybersecurity Act enforcement intensity, China's SAMR standard divergence from ISO baselines, and hospitality chain consolidation of vendor relationships.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Latin America Card-Based Access Control Market