
 Access Control and Authentication Market | 2026-2036
Access Control and Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Access Control and Authentication Market Intelligence
Silicon-based fingerprint sensors is repositioning product economics across entry-level biometric terminals. ASSA ABLOY leverages its lock-to-reader integration to dominate commercial real estate channels. Honeywell International anchors its position through building-automation bundling that ties access control into wider security ecosystems. Bosch Security Systems differentiates through video-analytics fusion that merges surveillance with credential verification.
Access control and authentication encompasses hardware and software systems that verify identity through credentials, biometrics, or behavioral patterns before granting physical or digital entry, typically operating at authentication speeds under one second with false acceptance rates below 0.001%. These systems secure facilities, networks, and data assets against unauthorized intrusion. Biometric systems capture the highest margin pools as iris and vein recognition command premium pricing in government and data center applications. Mobile credentials represent the fastest-expanding product type as Bluetooth Low Energy and Near Field Communication enable smartphone-based entry that eliminates card replacement costs. Card readers remain the volume backbone across enterprise security and educational institutions where legacy infrastructure upgrade cycles stretch replacement timelines.
The EU AI Act restricts biometric deployment in public spaces, pushing vendors toward on-device processing and encrypted template storage that satisfies GDPR data minimization principles. In the United States, NIST guidelines and state-level biometric privacy laws in Illinois and Texas shape product certification requirements for facial recognition vendors. Stakeholders must monitor regulatory fragmentation between privacy-first European frameworks and sector-specific U.S. federal standards as compliance architecture becomes a primary procurement criterion.
Market Dynamics
EU AI Act enforcement is compressing biometric deployment timelines while forcing vendors toward on-device processing architectures that satisfy GDPR data minimization mandates.
Growth Catalysts
- EU AI Act compliance mandates:Privacy-certified facial recognition systems face accelerated procurement across German industrial facilities and smart building portfolios.
- Bluetooth Low Energy credential proliferation:Mobile-based entry eliminates card replacement costs and drives adoption in enterprise security and educational institutions.
- Germany's smart building mandates:Industrial facility upgrades concentrate demand for card reader and mobile credential integration across commercial real estate channels.
Market Restraints
- Silicon sensor input cost volatility:Fingerprint sensor economics remain exposed to semiconductor foundry capacity constraints and wafer pricing cycles.
- Regulatory fragmentation friction:Divergent NIST guidelines and Illinois biometric privacy laws create certification complexity for facial recognition vendors serving US-EU dual markets.
- Legacy infrastructure substitution drag:Card reader replacement cycles stretch timelines in educational institutions where budget constraints favor incremental upgrades over system overhaul.
Strategic Opportunities
- Vein recognition technology convergence:Iris and vein biometric fusion commands premium positioning in government and data center security applications.
- Video-analytics integration white space:Surveillance-credential verification merger creates new product categories for facility operators seeking unified security stacks.
- On-device processing architectures:Encrypted template storage solutions satisfy GDPR principles while differentiating vendor offerings in privacy-sensitive European deployments.
Industry Challenges
- Biometric algorithm certification timelines:NIST testing protocols and state-level compliance requirements extend product launch cycles for facial recognition vendors.
- Legacy system integration complexity:Building-automation bundling demands specialized engineering capacity to tie access control into wider security ecosystems.
- Cross-border data governance skill scarcity:GDPR-EU AI Act dual compliance requires legal-technical hybrid expertise that vendors struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Access Control and Authentication Market |
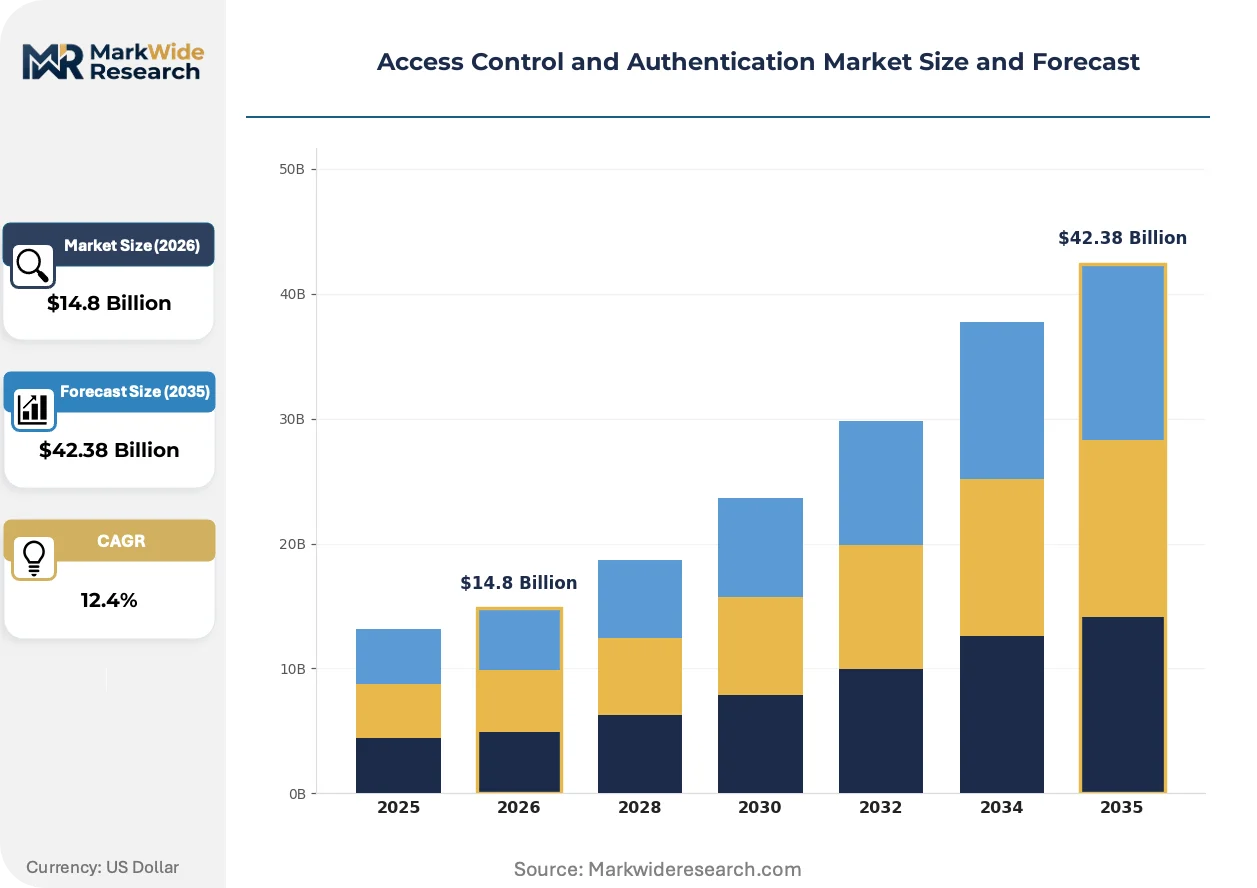
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $42.38 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Card Readers, Keypads, Mobile Credentials, Token Devices, Facial Recognition Technology: RFID, Bluetooth Low Energy, Near Field Communication, Multi-Factor Authentication, Behavioral Analytics, Voice Recognition Application: Enterprise Security, Government Facilities, Data Centers, Educational Institutions, Hospitality, Transportation End User: Corporations, Educational Establishments, Public Sector Agencies, Financial Institutions, Retail Chains, Event Management Companies |
| Companies Covered | Honeywell International, ASSA ABLOY, Johnson Controls International, Bosch Security Systems, Allegion, NEC Corporation, HID Global Corporation, Suprema, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Access Control and Authentication Market Strategic Shifts & Innovations
Architectural shifts toward edge processing and privacy-preserving biometrics are reconfiguring competitive advantage around compliance velocity rather than raw recognition accuracy.
Contactless fingerprint sensors using ultrasonic and capacitive arrays is electrifying entry-level biometric terminal economics. Financial institutions in Germany and the Netherlands are deploying these sensors at scale for branch access and vault authentication. The technology is electrifying margin structures by reducing silicon area requirements while maintaining sub-one-second authentication speeds.
GDPR Article 9 restrictions on special category data processing are forcing biometric vendors toward federated learning architectures that keep raw templates on local devices. Industrial facility operators in Germany now require encrypted template storage with zero-knowledge proof verification before procurement approval. Facial recognition deployments in public-facing commercial real estate face heightened scrutiny under CNIL guidance in France and BfDI interpretations in Germany.
Enterprise security teams are unbundling after-sales service contracts from hardware procurement, favoring subscription-based software maintenance that decouples upgrade cycles from capital budgets. System integrators in German smart building projects now compete on API interoperability rather than proprietary lock-in. This behavioral shift concentrates vendor selection power with facility management platforms that aggregate credential administration across multi-site portfolios.
Access Control and Authentication Market Segmentation
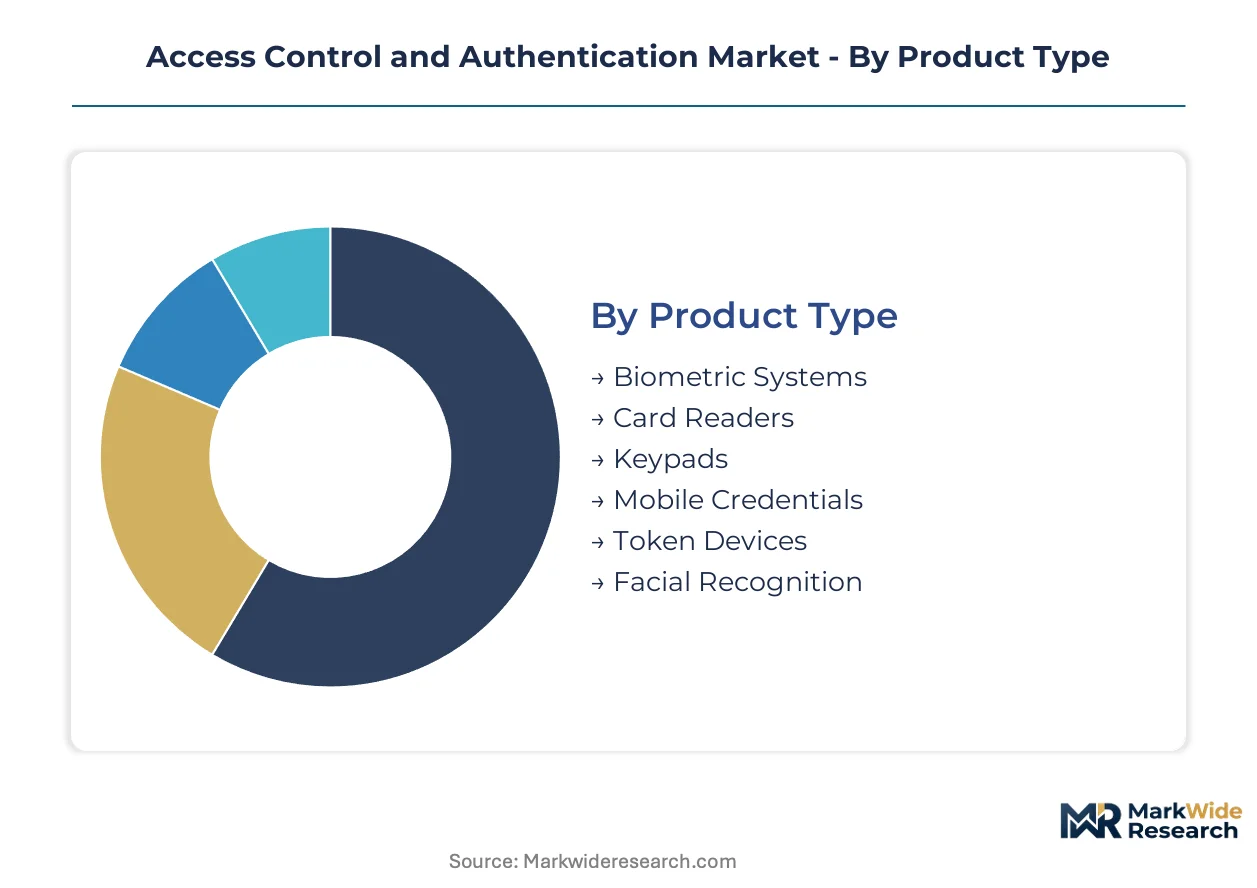
Segmentation in access control and authentication reveals how certification requirements, integration complexity, and end-user risk profiles reshape procurement patterns across hardware and software categories. Vendors must align product architectures with specific compliance burdens that vary sharply by deployment context.
Product Type:
Biometric systems carry the heaviest certification load, requiring NIST testing for facial recognition algorithms and GDPR Article 9 compliance for special category data processing across EU deployments.
- Biometric Systems:Fingerprint, iris, and vein recognition hardware operating at sub-one-second authentication speeds with false acceptance rates below 0.001%. German industrial facilities and data centers command premium pricing for multi-modal configurations that satisfy BfDI encryption mandates.
- Mobile Credentials:Bluetooth Low Energy and Near Field Communication enable smartphone-based entry that eliminates card replacement costs. Enterprise security teams in the Netherlands and Germany are unbundling these from hardware procurement in favor of subscription-based software maintenance.
- Card Readers:Volume backbone across educational institutions where legacy infrastructure upgrade cycles stretch replacement timelines.
- Keypads:Entry-level credential verification for cost-sensitive applications with minimal integration requirements.
- Token Devices:Hardware security keys serving high-assurance environments requiring offline authentication capabilities.
- Facial Recognition:Privacy-certified systems face accelerated procurement under EU AI Act enforcement, with on-device processing architectures satisfying GDPR data minimization principles.
Card readers sit at the top of the volume ranking, with mobile credentials climbing the fastest.
Technology:
Technology selection tracks directly to integration cost tiers, with multi-factor authentication commanding engineering premiums while single-protocol solutions compete on deployment speed.
- Multi-Factor Authentication:Combines credential types to satisfy high-assurance requirements in financial institutions and government facilities. German smart building mandates are driving convergence with building-automation systems that bundle access control into wider security ecosystems.
- Bluetooth Low Energy:Enables proximity-based credential transmission at reduced power consumption. Hospitality and transportation operators in France favor BLE for guest and passenger flow management under CNIL guidance restricting biometric alternatives.
- RFID:Mature contactless credential standard dominating educational institution deployments.
- Near Field Communication:Short-range credential exchange for mobile-first enterprise environments.
- Behavioral Analytics:Keystroke dynamics and gait analysis for continuous authentication in zero-trust architectures.
- Voice Recognition:Hands-free verification for logistics and manufacturing floor access.
RFID maintains the widest installed base, though multi-factor authentication is gaining share fastest among new deployments.
Application:
Application segmentation reflects divergent threat models, with data centers prioritizing biometric fusion while educational institutions optimize for credential lifecycle cost.
- Data Centers:Iris and vein recognition fusion commands premium positioning where physical perimeter breaches threaten catastrophic asset exposure. German facility operators require encrypted template storage with zero-knowledge proof verification.
- Enterprise Security:Mobile credential proliferation is eliminating card replacement costs as Bluetooth Low Energy and Near Field Communication enable smartphone-based entry across multi-site portfolios.
- Government Facilities:NIST guidelines and state-level biometric privacy laws in Illinois and Texas shape product certification requirements for facial recognition vendors.
- Educational Institutions:Budget constraints favor incremental card reader upgrades over system overhaul.
- Hospitality:Guest experience prioritization drives contactless mobile credential adoption.
- Transportation:High-throughput authentication requirements favor low-latency RFID and BLE configurations.
Enterprise security generates the largest addressable spend, with data center applications expanding most quickly.
End User:
End user segmentation maps to procurement sophistication, with financial institutions demanding API interoperability while retail chains prioritize volume pricing.
- Financial Institutions:Enterprise security teams are expanding biometric deployments for branch access and vault authentication. German banks are deploying contactless fingerprint sensors at scale, electrifying margin structures by reducing silicon area requirements.
- Public Sector Agencies:EU AI Act restrictions on biometric deployment in public spaces are pushing vendors toward on-device processing and encrypted template storage that satisfies GDPR data minimization principles.
- Corporations:Smart building mandates in Germany concentrate demand for card reader and mobile credential integration across commercial real estate channels.
- Educational Establishments:Legacy infrastructure substitution drag stretches replacement timelines where capital budgets favor incremental upgrades.
- Retail Chains:High-volume credential issuance requirements prioritize cost-per-unit economics.
- Event Management Companies:Temporary deployment models favor rental and subscription-based access control services.
Corporations represent the deepest installed base, with financial institutions driving the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters concentrate smart building retrofit demand as BfDI encryption mandates reshape procurement criteria across commercial real estate channels. Facility operators in Stuttgart and Munich now require zero-knowledge proof verification before approving biometric deployments.
United States
Financial institutions in New York and Chicago are expanding contactless fingerprint sensor deployments for branch security and vault authentication. NIST guidelines and Illinois Biometric Information Privacy Act shape facial recognition vendor certification requirements. Data center operators in Northern Virginia prioritize iris-vein fusion systems for perimeter hardening.
Germany
Industrial facility upgrades in North Rhine-Westphalia and Bavaria concentrate demand for card reader and mobile credential integration. EU AI Act enforcement compresses biometric deployment timelines while pushing vendors toward on-device processing architectures. Smart building mandates in Frankfurt and Hamburg accelerate Bluetooth Low Energy adoption across commercial portfolios.
France
Hospitality operators in Paris and Lyon favor Bluetooth Low Energy credentials for guest flow management under CNIL guidance restricting biometric alternatives. GDPR Article 9 compliance requirements force encrypted template storage with federated learning architectures. Transportation hubs in Île-de-France deploy low-latency RFID configurations for high-throughput authentication.
Netherlands
Enterprise security teams in Amsterdam and Rotterdam unbundle mobile credentials from hardware procurement in favor of subscription-based software maintenance. Privacy-certified facial recognition systems face accelerated procurement under EU AI Act alignment. Financial institutions deploy contactless fingerprint sensors at scale for branch access modernization.
United Kingdom
Data center operators in London and Slough command premium pricing for multi-modal biometric configurations satisfying post-Brexit data governance requirements. Building-automation bundling ties access control into wider security ecosystems across commercial real estate. Educational institutions in the Midlands stretch card reader replacement cycles due to capital budget constraints.
Access Control and Authentication Market Key Industry Players
Global majors compete with regional champions across compliance velocity and integration depth, creating a tiered structure where scale-driven bundlers face off against specialized biometric pure-plays. Market concentration clusters around building-automation ecosystems and privacy-certified facial recognition systems. Three archetypes dominate: diversified industrial conglomerates with security divisions, dedicated physical security specialists, and semiconductor-enabled biometric technology vendors. Competitive moves center on strategic partnerships with facility management platforms and geographic expansion through system integrator networks.
Within the diversified conglomerate tier, Honeywell International and Johnson Controls International exemplify building-automation bundling strategies that embed access control within wider security ecosystems. ASSA ABLOY occupies a position representing lock-to-reader integration specialists dominating commercial real estate channels through hardware convergence. Bosch Security Systems anchors the video-analytics fusion segment where surveillance-credential verification merger creates unified security stack offerings. These three entities represent distinct competitive vectors rather than direct substitutes, with each archetype commanding different procurement decision criteria across end-user segments.
| Leading Market Players |
|---|
| Honeywell International |
| ASSA ABLOY |
| Johnson Controls International |
| Bosch Security Systems |
| Allegion |
| NEC Corporation |
| HID Global Corporation |
| Suprema |
| Thales Group |
| Others |
Cost & Logistics Intelligence
EU AI Act compliance mandates gate qualified supply and premium-tier pricing access for biometric vendors serving German industrial and smart building portfolios. Facility operators in Stuttgart and Munich now require encrypted template storage with zero-knowledge proof verification before procurement approval, bifurcating vendor access between certified and non-certified tiers.
Pricing Analysis
Silicon sensor input cost pass-through electrifies margin structures across entry-level biometric terminals. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-certified multi-modal systems from legacy card reader configurations. Cost compression in standard-tier fingerprint sensors intensifies because semiconductor foundry capacity constraints expose vendors to wafer pricing cycles. Educational institutions exhibit highest price sensitivity due to capital budget constraints, while data center operators show lowest sensitivity given catastrophic breach exposure.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and France operate hub-and-spoke patterns for credential hardware fulfillment. Manufacturing draws from Taiwan and South Korea for silicon-based fingerprint sensors, with assembly concentrating in Poland and Hungary for EU market proximity. Single-source vulnerability persists for advanced iris recognition optics sourced from Japanese precision component suppliers. Distribution runs through system integrator networks that bundle installation with facility management platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU AI Act enforcement shifts procurement criteria toward privacy-certified architectures over raw recognition accuracy. Data center and financial institution buyers now demand encrypted template storage and on-device processing as baseline specifications.
For Market Incumbents: To counter regulatory fragmentation friction between NIST guidelines and GDPR Article 9 requirements, prioritize certification investment in dual-compliant facial recognition architectures. Channel control through API interoperability partnerships with facility management platforms protects against unbundling of hardware from software maintenance contracts. For New Entrants and Emerging Players: A price-point gap between premium GDPR-certified biometric systems and economy-tier legacy card readers opens white-space in mid-market mobile credential integration. Target educational institutions in the UK and France where budget constraints favor incremental BLE-enabled upgrades over system overhaul. Go-to-market through subscription-based software maintenance models decouples upgrade cycles from capital budgets. For Investors and Strategic Acquirers: Roll-up economics work for specialized biometric pure-plays because EU AI Act compliance velocity creates acquisition premiums for vendors with existing BfDI and CNIL certifications. Long-term viability centers on federated learning architecture capabilities across a five-to-ten-year horizon. Watch for inflection where on-device processing penetration in German industrial facilities crosses threshold for template storage standardization.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Certified Product Architecture | EU AI Act alignment unlocks procurement approval from BfDI-mandated German facility operators. |
| API Interoperability Partnership | Facility management platform integration prevents hardware-software unbundling by enterprise security teams. |
| On-Device Processing Investment | Encrypted template storage satisfies CNIL guidance restricting biometric data transmission in French deployments. |
| Mobile Credential Platform Launch | BLE-enabled smartphone entry eliminates card replacement costs for Dutch educational institutions. |
| Video-Analytics Fusion Development | Surveillance-credential verification merger addresses unified security stack demand from Frankfurt commercial real estate. |
Research Approach
Direct dialogue with enterprise security directors, facility management platform engineers, biometric system integrators, and regulatory compliance officers grounds qualitative findings in procurement decision dynamics. Secondary validation draws from EU AI Act implementation guidance, BfDI encryption mandate documentation, NIST biometric testing protocols, and SEC filings from diversified security conglomerates. Bottom-up and top-down triangulation cross-checks segment-level demand against aggregate market sizing.
Bottom-up demand modeling aggregates credential deployment volumes across German smart building mandates, US financial institution branch modernization cycles, and data center perimeter hardening projects. Segmentation dimensions include product type, authentication technology, application vertical, and end-user procurement sophistication. CAGRs derive from regression analysis against regulatory enforcement timelines and infrastructure replacement cycles. Industry-specific forecast inputs incorporate BLE credential adoption curves and silicon sensor cost trajectories.
Caveats apply where EU AI Act enforcement delays, semiconductor foundry capacity constraints, or state-level biometric privacy law expansion could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Programmable Safety Systems Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
South Korea Access Control Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Global Automatic Door Control Market