
 Border Security System Market | 2026-2036
Border Security System Market Size, Share, and Industry Trends Forecast 2026-2036
Border Security System Market Intelligence
MIL-STD-810H compliance tier is unwinding legacy procurement patterns across border security programs. Lockheed Martin leverages its integrated command-and-control heritage to anchor large-scale perimeter contracts. Elbit Systems specializes in multi-sensor fusion architectures for harsh-environment deployments. Thales competes through sovereign-data-pathway guarantees in European and Middle Eastern installations.
Border security systems encompass electro-optical, radar, biometric, and command-and-control subsystems engineered to detect, identify, and interdict unauthorized crossings across land, maritime, and aerial domains. These platforms integrate thermal imaging sensors with operational ranges exceeding 20 kilometers, synthetic aperture radar for all-weather coverage, and AI-enabled video analytics to reduce operator cognitive load in high-clutter environments. Surveillance cameras and intrusion detection technologies occupy the largest installed base, though biometrics is recording the fastest upgrade cycle as facial recognition and iris matching displace document-centric inspection at land ports of entry. Government agencies command the dominant share of capital expenditure, while airports represent a concentrated margin pool due to passenger-volume-linked refresh schedules and stringent regulatory certification requirements.
The US Department of Homeland Security and US Customs and Border Protection shape North American demand through operational requirements documents that mandate interoperability with legacy radar networks. The European Union's Schengen Borders Code and Frontex technical standards enforce common performance thresholds for biometric identification systems across member-state procurement. The EU AI Act introduces additional conformity obligations for automated threat-detection algorithms, redirecting vendor development resources toward explainable AI architectures. Stakeholders must monitor how sovereign-data-localization mandates fragment cloud-deployment roadmaps for cross-border intelligence sharing.
Market Dynamics
Sensor fusion architectures are compressing procurement cycles as US Customs and Border Protection mandates interoperability between legacy radar networks and AI-enabled detection platforms, forcing vendors to re-engineer integration layers rather than compete on standalone hardware specifications.
Growth Catalysts
- Biometric identification mandates:The EU AI Act's conformity obligations for automated threat-detection algorithms are redirecting vendor development resources toward explainable AI architectures, accelerating upgrade cycles at land ports of entry.
- Maritime domain awareness expansion:Coastal surveillance programs across the Mediterranean and Arabian Gulf are driving demand for synthetic aperture radar with all-weather coverage capabilities.
- Thermal imaging range extension:Operational requirements documents from US Department of Homeland Security now specify detection thresholds exceeding 20 kilometers, pulling investment into cooled infrared sensor arrays.
Market Restraints
- Semiconductor supply concentration:Specialized FPGA and GPU components for edge AI processing face single-source dependencies from Taiwanese foundries, creating vulnerability in sensor manufacturing pipelines.
- Sovereign data localization mandates:Fragmenting cloud-deployment roadmaps for cross-border intelligence sharing as EU member states enforce divergent data residency requirements under GDPR and national security frameworks.
- Legacy radar integration costs:MIL-STD-810H compliance tier requirements impose hardware redesign burdens that extend qualification timelines for new perimeter surveillance entrants.
Strategic Opportunities
- Unmanned aerial system countermeasures:Drone detection and defeat systems represent an emerging application segment as airports and critical infrastructure operators seek layered perimeter defense beyond ground-based sensors.
- Explainable AI architectures:Regulatory tailwinds from the EU AI Act create first-mover advantage for vendors delivering algorithmic transparency in automated threat classification systems.
- India land border modernization:The country's national security establishment is expanding procurement of integrated command-and-control platforms along Himalayan and desert frontiers, opening new geography for sensor fusion deployments.
Industry Challenges
- AI/ML engineering talent scarcity:Video analytics and sensor fusion algorithm development require specialized skill sets concentrated in defense contracting hubs, constraining vendor scaling capacity.
- Interoperability certification timelines:US Customs and Border Protection's operational requirements documents mandate extensive field testing against legacy networks, extending deployment schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Border Security System Market |
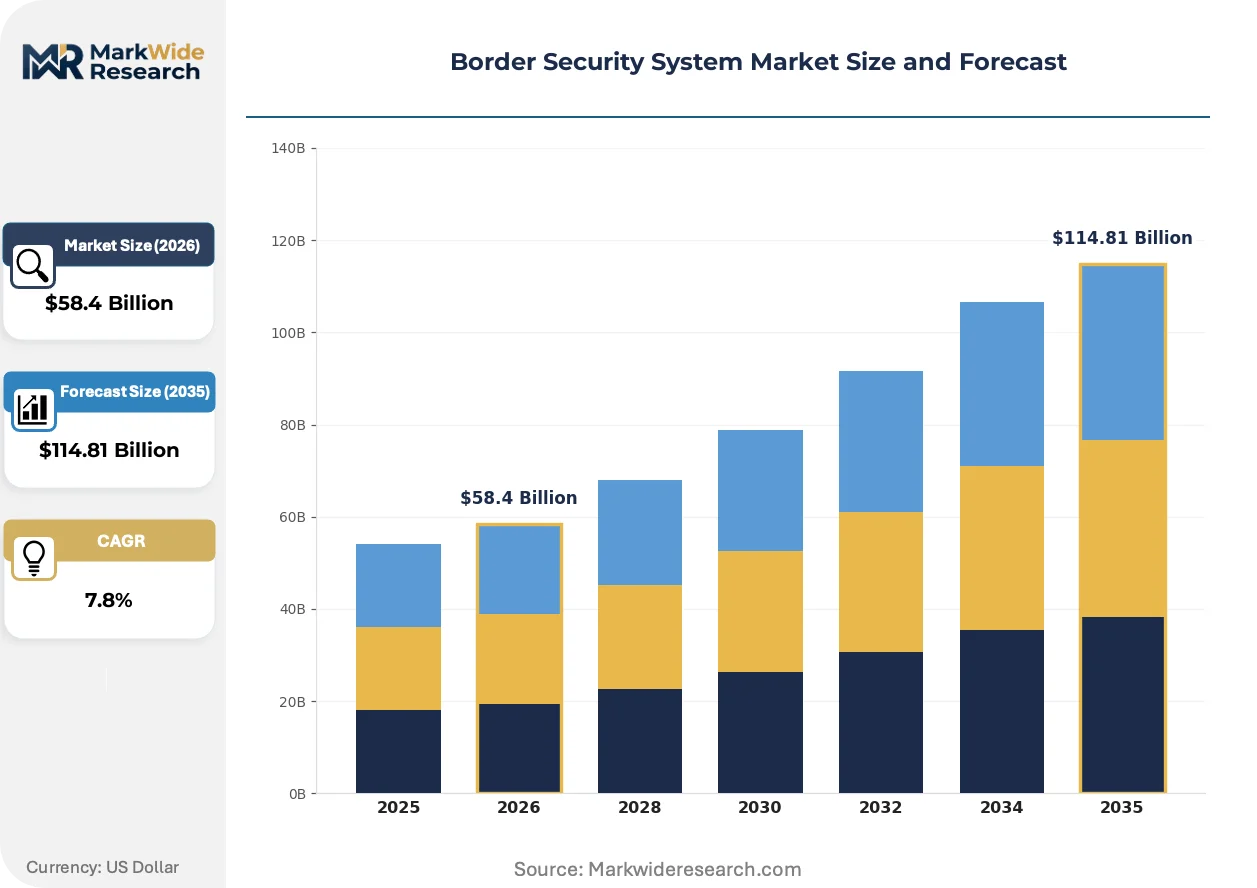
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $114.81 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Cameras, Intrusion Detection, Biometrics, Access Control End User: Government Agencies, Military, Airports, Private Security Firms Application: Perimeter Security, Border Control, Port Security, Customs Enforcement Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Units |
| Companies Covered | Lockheed Martin Corporation, General Dynamics Corporation, Northrop Grumman Corporation, BAE Systems, Thales, RTX Corporation, Elbit Systems Ltd., Leonardo S.p.A., Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Border Security System Market Strategic Shifts & Innovations
Edge computing architectures are redistributing processing loads from centralized command centers to field-deployed sensor nodes, enabling real-time threat classification without bandwidth-dependent cloud connectivity. This shift is compressing response latencies while complicating firmware update and cybersecurity management protocols.
Multi-sensor fusion platforms are bifurcating the competitive landscape between integrated system providers and specialized component suppliers. Large-scale perimeter contracts now favor vendors delivering unified command-and-control software layers, while standalone sensor manufacturers face margin pressure unless they embed sufficient onboard processing to participate in fusion architectures. Defense agencies in the United States and Israel are driving this consolidation through procurement vehicles that penalize fragmented subsystem integration.
The EU AI Act's risk-based classification framework for biometric identification systems is forcing algorithm vendors to document training data provenance and decision pathways. Industrial consequence includes redirected R&D spending toward audit-ready machine learning pipelines rather than pure performance optimization. European border management agencies are responding by extending procurement evaluation periods to accommodate conformity assessment procedures, delaying deployment schedules.
Performance-based service contracting is displacing traditional capital acquisition models for large-scale surveillance infrastructure. Government buyers in Australia and the United Arab Emirates now specify availability guarantees and detection-rate thresholds rather than hardware specifications, transferring operational risk to integrators. This reconfiguration favors vendors with captive maintenance networks and predictive analytics capabilities, compressing margins for equipment-only suppliers.
Border Security System Market Segmentation
Border security procurement channels diverge sharply by buyer sophistication and integration complexity. Government tenders favor bundled technology stacks, while private operators increasingly source standalone components through specialized distributors.
Technology:
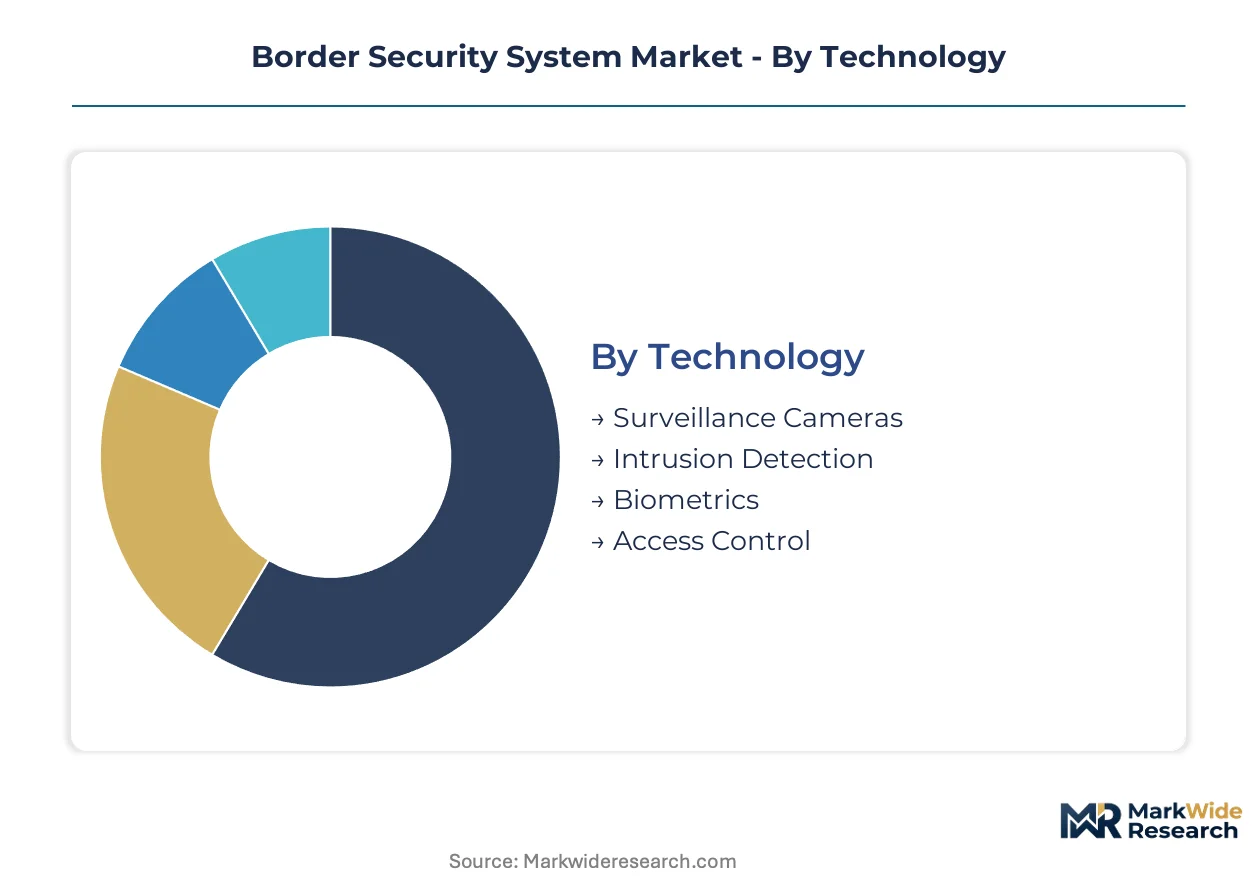
Channel mix varies by integration burden—surveillance cameras and intrusion detection flow through broad distribution, while biometrics and access control require certified systems integrators with sovereign-data clearances.
- Surveillance Cameras:Thermal imaging and electro-optical arrays with 20-kilometer detection ranges form the perimeter backbone. US Customs and Border Protection southwestern infrastructure programs are pulling cooled infrared sensor procurement through federal acquisition vehicles.
- Biometrics:Facial recognition and iris matching systems displace document-centric inspection at land ports. EU AI Act conformity obligations are redirecting vendor development toward explainable AI architectures, accelerating upgrade cycles at Schengen entry points.
- Intrusion Detection:Ground sensors and seismic monitors for unmanned perimeter segments.
- Access Control:Credential verification and gate management systems for manned checkpoints.
By volume, surveillance cameras lead. By growth pace, biometrics is climbing the fastest.
End User:
Cost tier stratification separates sovereign buyers with decade-long refresh cycles from commercial operators seeking subscription-based availability models.
- Government Agencies:US Department of Homeland Security and EU Frontex command dominant capital expenditure through operational requirements documents mandating legacy radar interoperability. These buyers specify MIL-STD-810H compliance tiers that extend qualification timelines.
- Airports:Passenger-volume-linked refresh schedules and stringent regulatory certification from FAA and EASA create concentrated margin pools. Detection-rate thresholds now dominate procurement over hardware specifications.
- Military:Harsh-environment deployments requiring multi-sensor fusion architectures.
- Private Security Firms:Performance-based service contracting with availability guarantees.
By installed base, government agencies dominate. By margin expansion, airports are gaining share fastest.
Application:
Geography drives specification divergence—maritime programs prioritize all-weather radar, while land borders emphasize biometric throughput.
- Border Control:Integrated command-and-control platforms for unauthorized crossing interdiction across land, maritime, and aerial domains. Mediterranean and Arabian Gulf coastal surveillance programs are driving synthetic aperture radar demand.
- Perimeter Security:Layered sensor networks for critical infrastructure protection.
- Port Security:Container inspection and vessel tracking systems.
- Customs Enforcement:Trade compliance and contraband detection platforms.
By deployment scale, border control leads. By technology refresh frequency, customs enforcement is expanding most quickly.
Deployment:
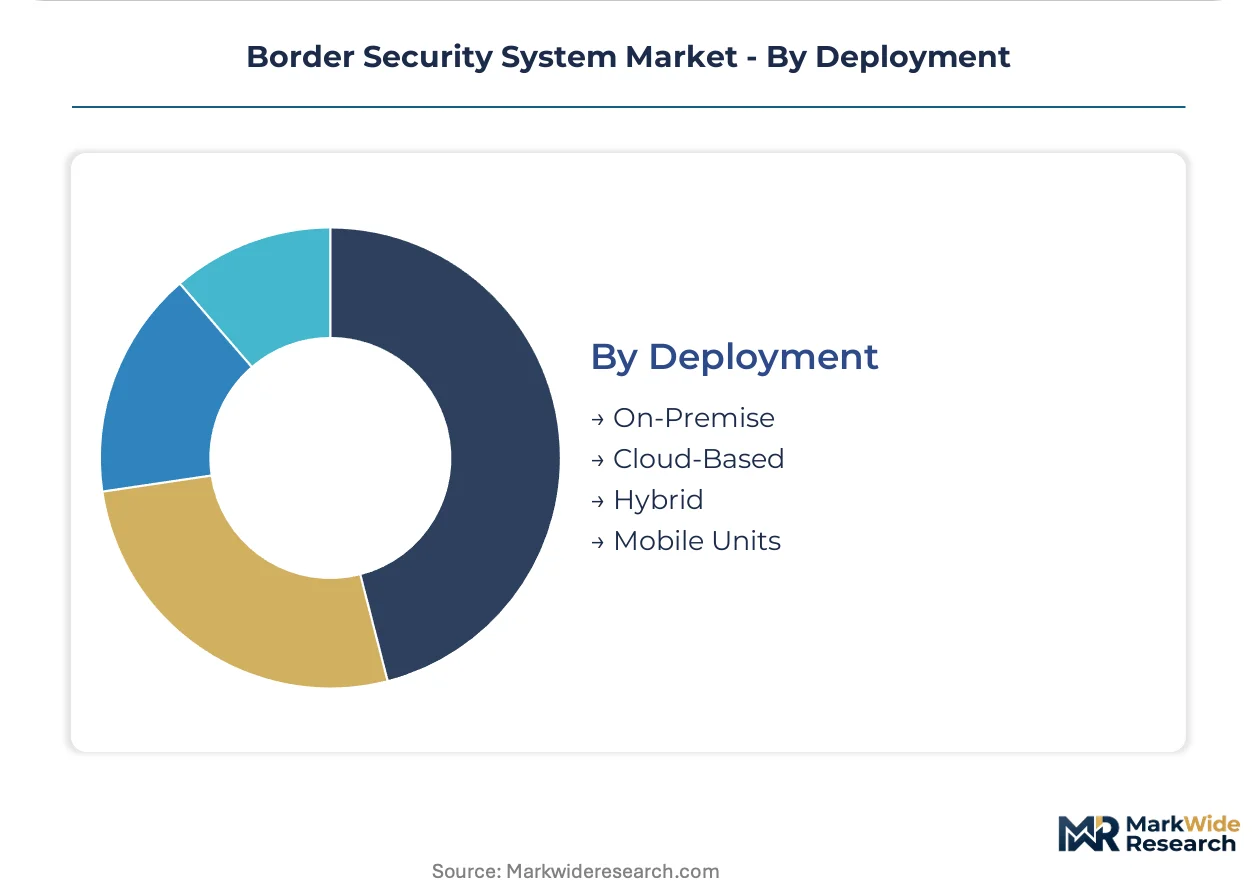
Customer type dictates architecture choice—sovereign operators with classified networks resist cloud migration, while commercial buyers embrace hybrid models.
- On-Premise:Air-gapped command centers for classified intelligence processing. GDPR and national security frameworks across EU member states are fragmenting cloud-deployment roadmaps, reinforcing on-premise preferences.
- Hybrid:Edge computing architectures redistributing processing loads to field-deployed sensor nodes.
- Cloud-Based:Predictive analytics and firmware management for non-classified operations.
- Mobile Units:Rapidly deployable surveillance for temporary perimeter establishment.
By current installed base, on-premise leads. By R&D investment trajectory, hybrid architectures show the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican exports of integrated surveillance platforms flow primarily to US federal procurement channels, while Israeli sensor fusion systems reach European and Asian defense ministries through technology transfer agreements.
United States
US Customs and Border Protection drives southwestern border infrastructure modernization through operational requirements documents mandating 20-kilometer thermal detection ranges. The Department of Homeland Security enforces MIL-STD-810H compliance tiers that extend vendor qualification timelines. El Paso and San Diego anchor concentrated deployment corridors where cooled infrared sensor arrays are being field-tested against legacy radar networks.
Germany
Federal Police procurement of biometric identification systems accelerates under Schengen Borders Code harmonization pressures. The EU AI Act's risk-based classification framework forces algorithm vendors toward explainable AI architectures. Munich and Stuttgart host competing development clusters where sovereign-data-pathway guarantees are being negotiated for cross-border intelligence sharing.
Israel
Defense Ministry requirements for harsh-environment multi-sensor fusion pull investment into edge computing architectures. National security frameworks enforce strict data residency for classified perimeter surveillance. Haifa and Beersheba concentrate specialist engineering talent for video analytics and sensor fusion algorithm development.
India
Land border modernization programs along Himalayan and desert frontiers expand procurement of integrated command-and-control platforms. The Ministry of Home Affairs specifies interoperability with legacy networks across diverse terrain conditions. Bengaluru and Hyderabad emerge as domestic integration hubs for thermal imaging and seismic monitoring subsystems.
United Arab Emirates
Critical infrastructure operators specify performance-based availability guarantees rather than hardware specifications for coastal surveillance programs. MOHAP frameworks influence procurement evaluation criteria for automated threat-detection systems. Abu Dhabi and Dubai concentrate integrator networks capable of delivering detection-rate thresholds for maritime domain awareness expansion.
Border Security System Market Key Industry Players
Listed leaders compete with private specialists across defense contracting hierarchies, creating a tiered structure where scale advantages in federal procurement coexist with niche expertise in harsh-environment deployments. Three archetypes dominate: integrated system providers delivering unified command-and-control software layers, specialized component suppliers embedding onboard processing for fusion architectures, and sovereign-data guarantors navigating EU and Middle Eastern localization mandates. Competitive moves concentrate on strategic partnerships for legacy radar interoperability and geographic expansion into India's land border modernization programs.
Within the integrated system tier, Lockheed Martin and Northrop Grumman occupy positions anchored by heritage command-and-control contracts, while Elbit Systems exemplifies the harsh-environment specialist archetype. Thales represents the sovereign-data guarantor model, with its positioning shaped by European regulatory compliance requirements. These three entities collectively illustrate how vendor strategy diverges across procurement channel sophistication and geographic regulatory intensity.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales |
| RTX Corporation |
| Elbit Systems Ltd. |
| Leonardo S.p.A. |
| Israel Aerospace Industries |
| Others |
Cost & Logistics Intelligence
MIL-STD-810H certification tiers gate both vendor qualification and price differentiation simultaneously, forcing entrants to absorb extended testing costs while incumbents extract premiums through heritage compliance. Government procurement vehicles reward pre-qualified suppliers with sole-source eligibility, compressing margins for non-compliant competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—MIL-STD-810H compliance commands 15-25% premiums over commercial-grade alternatives—and volume scale through federal acquisition vehicles. Cost compression in the standard tier is intensifying because Taiwanese FPGA foundries face capacity constraints. System integrators with sovereign-data clearances exhibit lowest price sensitivity, while private security firms operating on performance-based contracts show highest elasticity.
Supply Chain Analysis
Strategic stockpiling of cooled infrared sensor arrays dominates inventory strategy, with US Customs and Border Protection mandating 90-day buffer stocks for critical perimeter deployments. Geographic supply concentrates in Taiwan for FPGA edge-processing components, Israel for multi-sensor fusion software, and the United States for MIL-STD-qualified thermal imagers. Raw material dependencies include indium antimonide for cooled detectors, gallium arsenide for radar modules, and specialized aluminum alloys for harsh-environment enclosures. Single-source vulnerability from Taiwanese foundries creates procurement risk. Distribution runs through defense contracting hierarchies with certified systems integrators as gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Border security procurement is shifting toward platform-economics logic as sensor fusion architectures mandate unified command-and-control software layers over standalone hardware sales. Interoperability with legacy radar networks has become the gating ecosystem requirement.
For Market Incumbents: Shield heritage command-and-control contracts by accelerating backward integration into edge AI processing components, reducing exposure to Taiwanese foundry bottlenecks. Invest in explainable AI certification pipelines ahead of EU AI Act enforcement. Vertical integration into cooled infrared sensor manufacturing defends margin position against modular competitors. For New Entrants and Emerging Players: CE marking fast-tracks for biometric identification systems open Schengen procurement channels without decade-long US federal qualification timelines. Target India's land border modernization programs through domestic integration partnerships in Bengaluru and Hyderabad. White-space exists in unmanned aerial system countermeasures for airport perimeter defense. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid edge-cloud deployment architectures as sovereign data localization mandates fragment infrastructure requirements. Acquisition targets should display captive maintenance networks and predictive analytics capabilities. Watch for EU member state divergence in GDPR enforcement as signal for cloud-deployment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Lockheed Martin and Elbit Systems anchor large-scale perimeter contracts through unified command layers. |
| Explainable AI Certification Investment | EU AI Act conformity obligations redirect vendor R&D toward audit-ready machine learning pipelines. |
| Backward Integration into Edge Processing | Taiwanese FPGA concentration creates vulnerability that captive component supply mitigates. |
| Performance-Based Service Contracting | Australian and UAE government buyers now specify availability guarantees over hardware specifications. |
| Geographic Expansion into India | Himalayan and desert frontier modernization opens new procurement channels for integrated platforms. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with border security procurement officers at US Customs and Border Protection, EU Frontex technical directors, systems integration engineers at Israeli defense contractors, and airport security operations managers; and secondary validation through Department of Homeland Security operational requirements documents, EU AI Act regulatory filings, FAA certification databases, and customs/trade data for surveillance component flows. Bottom-up segment sizing triangulated against top-down federal budget appropriations for southwestern border infrastructure.
Across the projection horizon, the analytical framework modeled technology segments by integration burden, end-user categories by procurement sophistication, and deployment architectures by data classification requirements. CAGRs derived from weighted regression of historical federal acquisition cycles and regulatory mandate timelines. Forecast inputs included US Department of Homeland Security technology refresh schedules and EU Schengen Borders Code harmonization pressures.
The analysis sits within stated boundaries; outcomes outside sustained US federal infrastructure appropriations or EU regulatory enforcement intensity would require recalibration. Forecasts reflect assumptions regarding Taiwanese semiconductor supply continuity and legacy radar network interoperability standards. Revision becomes warranted when sovereign data localization mandates cross thresholds that fragment cross-border intelligence sharing architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
South Korea Access Control Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Digital Security Control Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
North America Home Security System Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Italy Access Control Market
Access Control Systems
Network Access Control Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Access Control Market