
 Spain Ransomware Protection Market | 2026-2036
Spain Ransomware Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Ransomware Protection Market Insights
The capability gap between capital-heavy integrated providers and leaner specialists is rotating competitive dynamics across Spain's cybersecurity landscape. Telefónica Tech leverages its national telecom infrastructure to anchor enterprise-grade managed detection services. S21sec Thales sustains differentiation through deep specialization in threat intelligence tailored to Iberian regulatory environments. Panda Security competes on channel density, extending its endpoint security footprint through Spain's mid-market reseller networks.
Ransomware protection encompasses layered defensive architectures combining endpoint agents, network segmentation protocols, and encrypted backup orchestration to neutralize cryptographic extortion attacks before data exfiltration or system lockout. Solutions deploy through on-premises appliances, cloud-native platforms, or hybrid configurations depending on organizational legacy infrastructure and data sovereignty requirements. Endpoint security dominates current procurement volumes among large corporations, while behavioral analysis represents the fastest-growing technology segment as Spanish enterprises shift from signature-based detection to anomaly-driven prevention. Cloud-based deployment is gaining share among small and medium enterprises seeking to bypass capital expenditure cycles.
Spain's national data protection authority enforces breach notification timelines under GDPR that compress incident response windows and elevate demand for automated containment platforms. The EU NIS2 Directive imposes stricter security governance obligations on critical infrastructure operators, directly expanding addressable demand within Spain's energy, transport, and healthcare sectors. Stakeholders must monitor how transposition of the EU Cyber Resilience Act into Spanish law reshapes product certification requirements for security software vendors operating in this market.
Market Dynamics
GDPR enforcement by Spain's national data protection authority is compressing incident response timelines and forcing financial services firms to accelerate procurement of automated containment platforms. This regulatory pressure is restructuring competitive positioning between capital-heavy integrated providers and leaner specialists.
Growth Catalysts
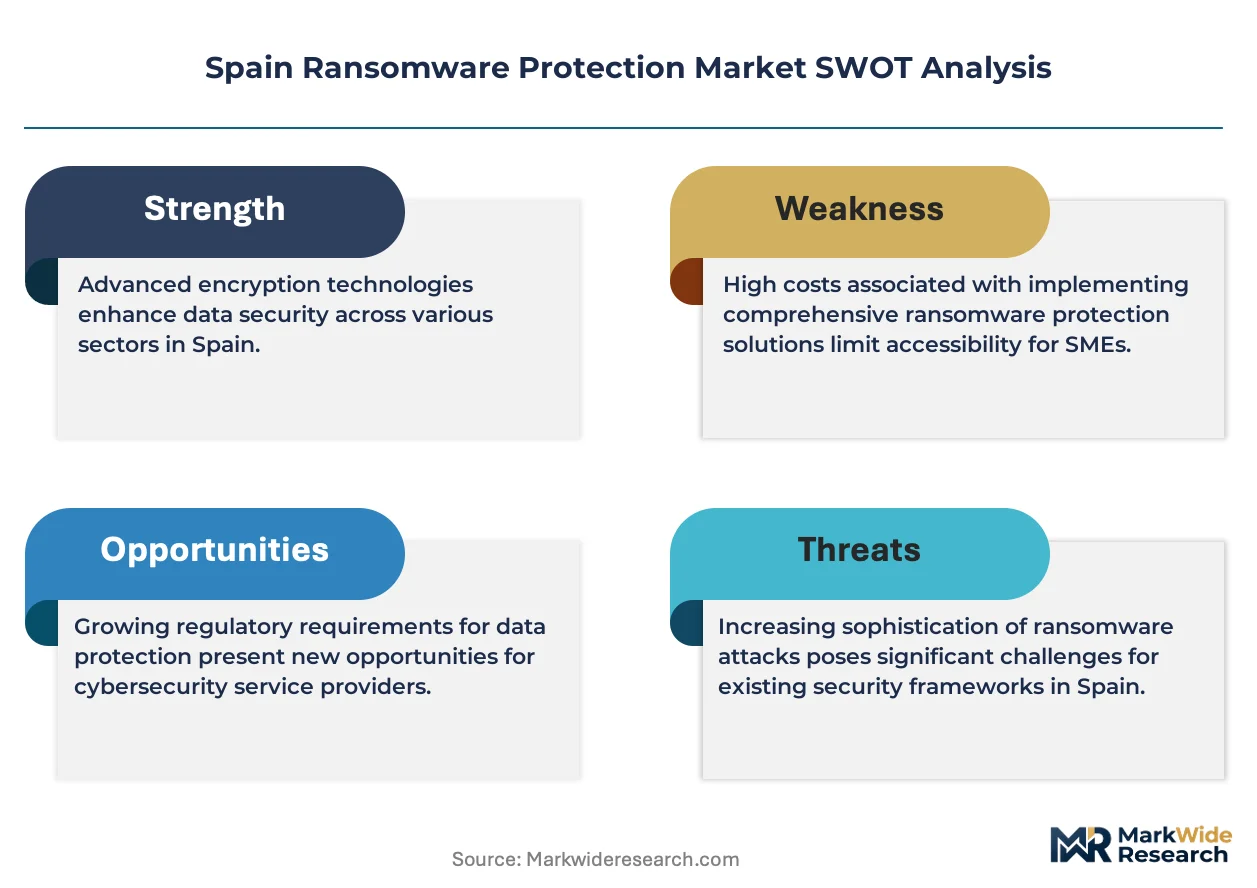
- EU NIS2 Directive transposition:Stricter security governance obligations on critical infrastructure operators in Spain's energy, transport, and healthcare sectors are expanding addressable demand for managed detection services.
- Behavioral analysis technology:Spanish enterprises are shifting from signature-based detection to anomaly-driven prevention, elevating procurement volumes for endpoint security with embedded machine learning.
- Madrid's technology clusters:Corporate and government concentration in the capital region creates dense demand nodes where critical infrastructure operators face elevated threat exposure.
Market Restraints
- Capital expenditure cycles:Small and medium enterprises lack budget for on-premises appliance deployment, constraining penetration outside Madrid and Barcelona corporate hubs.
- Technical limitation:Legacy infrastructure in Spain's industrial base creates integration friction with cloud-native protection platforms, delaying hybrid configuration adoption.
- Regulatory friction:Pending transposition of the EU Cyber Resilience Act into Spanish law is creating certification uncertainty for security software vendors, freezing procurement decisions.
Strategic Opportunities
- Andalusia and Valencia SME segments:Underpenetrated mid-market reseller networks outside Madrid present channel density expansion opportunities for cloud-based deployment models.
- Encrypted backup orchestration:Convergence of immutable storage with automated recovery workflows addresses GDPR's compressed breach notification windows.
- EU AI Act alignment:Proactive certification for AI-driven threat detection systems creates first-mover advantage as Spanish regulators develop supervisory frameworks.
Industry Challenges
- Cybersecurity talent scarcity:Incident response specialists and threat intelligence analysts command premium compensation in Madrid's competitive labor market, inflating managed service delivery costs.
- Legacy system integration complexity:Industrial control systems in Spain's energy and transport sectors require customized segmentation protocols that extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Ransomware Protection Market |
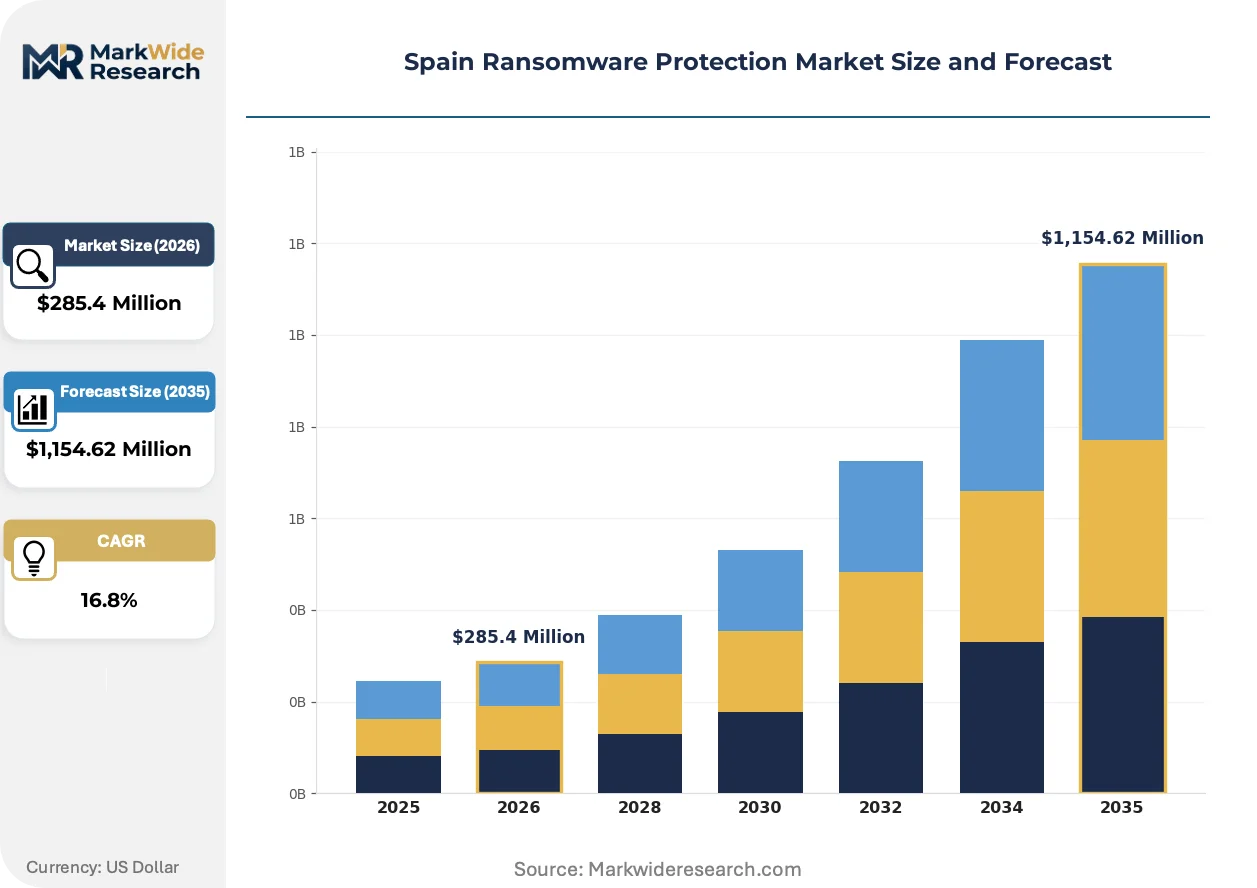
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Endpoint Security, Email Security, Network Security, Cloud Security Deployment: On-premises, Cloud-based, Hybrid, Managed Service End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Technology: AI-based Detection, Behavioral Analysis, Data Recovery, Threat Intelligence |
| Companies Covered | Telefónica Tech, S21sec Thales, Panda Security, DeepStrike, GMV Innovating Solutions, Indra Sistemas, Factosecure, Entelgy Innotec Security, Tarlogic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Ransomware Protection Market Trends and Innovations
Behavioral anomaly detection is supplanting signature-based methods as the dominant defensive architecture across Spanish enterprise security stacks. This technology rotation is compressing procurement cycles and elevating vendor differentiation requirements.
Extended detection and response platforms with native machine learning engines are supplanting traditional antivirus deployments in Spanish financial services. Large corporations in Madrid's banking district are adopting these systems within twelve-month refresh cycles. This shift is compressing margin structures for signature-dependent vendors while expanding recurring revenue pools for behavioral analytics providers.
Spain's national data protection authority is tightening GDPR breach notification enforcement, compressing the window between detection and regulatory disclosure to seventy-two hours. Industrial consequence includes mandatory investment in automated containment and forensic preservation tools. Critical infrastructure operators in energy and transport are responding by procuring integrated platforms that unify detection, containment, and documentation workflows.
Subscription-based managed detection services are displacing perpetual license purchases among Spanish mid-market enterprises. Reseller channels in Barcelona and Valencia are pivoting toward recurring revenue models that bundle monitoring with incident response retainers. This pattern is most visible in healthcare and professional services verticals where internal security team scale is constrained.
Spain Ransomware Protection Market Segmentation
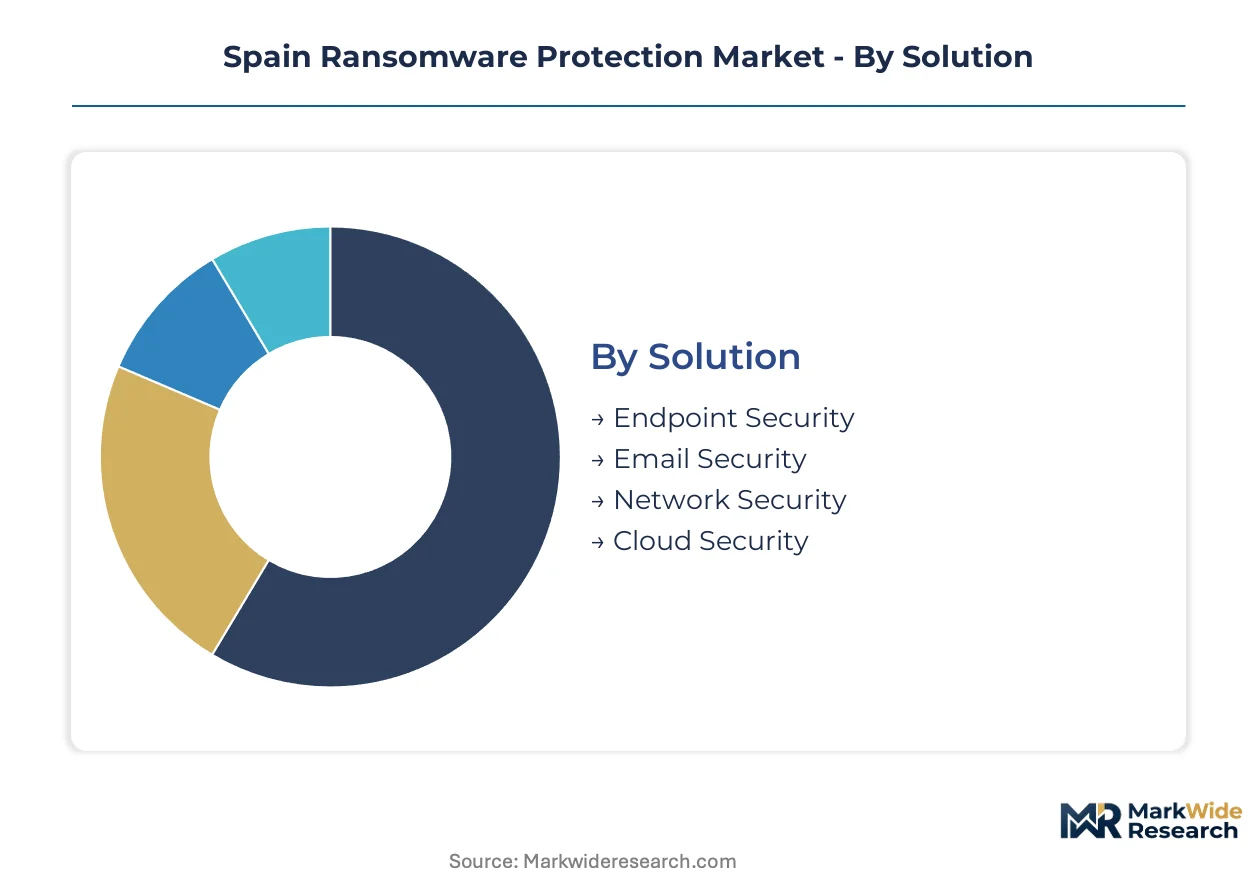
Ransomware protection procurement patterns in Spain diverge sharply across organizational scale and infrastructure maturity. Channel strategy, deployment complexity, and regulatory exposure create distinct segment trajectories that vendors must navigate through differentiated pricing and service architectures.
Solution:
Enterprise procurement flows through direct sales for integrated suites, while mid-market demand concentrates in value-added reseller channels bundling endpoint with email protection. Managed service providers capture cloud security through monthly subscription models.
- Endpoint Security:Deploys through lightweight agents on workstations and servers with real-time process monitoring and application whitelisting. Large corporations in Madrid's financial district dominate procurement volumes, driven by GDPR's seventy-two-hour breach notification mandate compressing response windows.
- Email Security:Intercepts phishing payloads and malicious attachments through gateway filtering and sandbox detonation. Medium enterprises across Barcelona and Valencia reseller networks show steepest expansion trajectory as remote work patterns elevate attack surface exposure.
- Network Security:Microsegmentation and east-west traffic inspection for lateral movement prevention. Industrial control operators in Spain's energy sector drive specialized demand requiring protocol-aware inspection.
- Cloud Security:Native protection for SaaS workloads and containerized environments. Small enterprises bypass capital expenditure through consumption-based licensing.
By volume, Endpoint Security leads. By growth pace, Cloud Security is ahead.
Deployment:
Cost tier stratification separates perpetual license on-premises from subscription cloud models, with hybrid configurations commanding premium pricing for orchestration complexity.
- On-premises:Appliance-based deployment within organizational data centers requiring dedicated infrastructure investment. Large corporations with legacy compliance frameworks sustain demand despite higher total cost of ownership.
- Cloud-based:Native SaaS delivery eliminating hardware procurement cycles. Small enterprises in Andalusia and Valencia mid-market show fastest adoption velocity as channel partners pivot to recurring revenue models.
- Hybrid:Orchestrated protection spanning on-premises and cloud workloads with unified policy management. Critical infrastructure operators in transport and healthcare sectors procure for data sovereignty compliance.
- Managed Service:Outsourced detection and response with guaranteed service level agreements. Government entities in Madrid technology clusters favor this model for talent scarcity mitigation.
By installed base, On-premises retains dominance. By new contract velocity, Managed Service is expanding most quickly.
End User:
Customer type determines solution complexity and sales cycle length, with government procurement requiring certification compliance that extends vendor onboarding timelines.
- Small Enterprises:Sub-fifty-employee organizations procuring through bundled security packages. Andalusia reseller networks show underpenetrated expansion potential for cloud-native deployment.
- Medium Enterprises:Fifty-to-five-hundred-employee firms with dedicated IT staff but constrained security specialization. Barcelona professional services vertical drives behavioral analytics adoption for anomaly-driven prevention.
- Large Corporations:Multi-site enterprises with security operations centers and formal governance frameworks. Madrid banking district concentrates procurement of integrated detection platforms with machine learning engines.
- Government:National and regional public sector entities with sovereign data requirements. EU NIS2 Directive transposition is expanding addressable demand across energy, transport, and healthcare agencies.
By revenue concentration, Large Corporations dominate. By policy tailwinds, Government is climbing the fastest.
Technology:
Maturity differentiation separates established signature methods from emerging AI-driven architectures, with implementation risk elevating pricing for unproven detection paradigms.
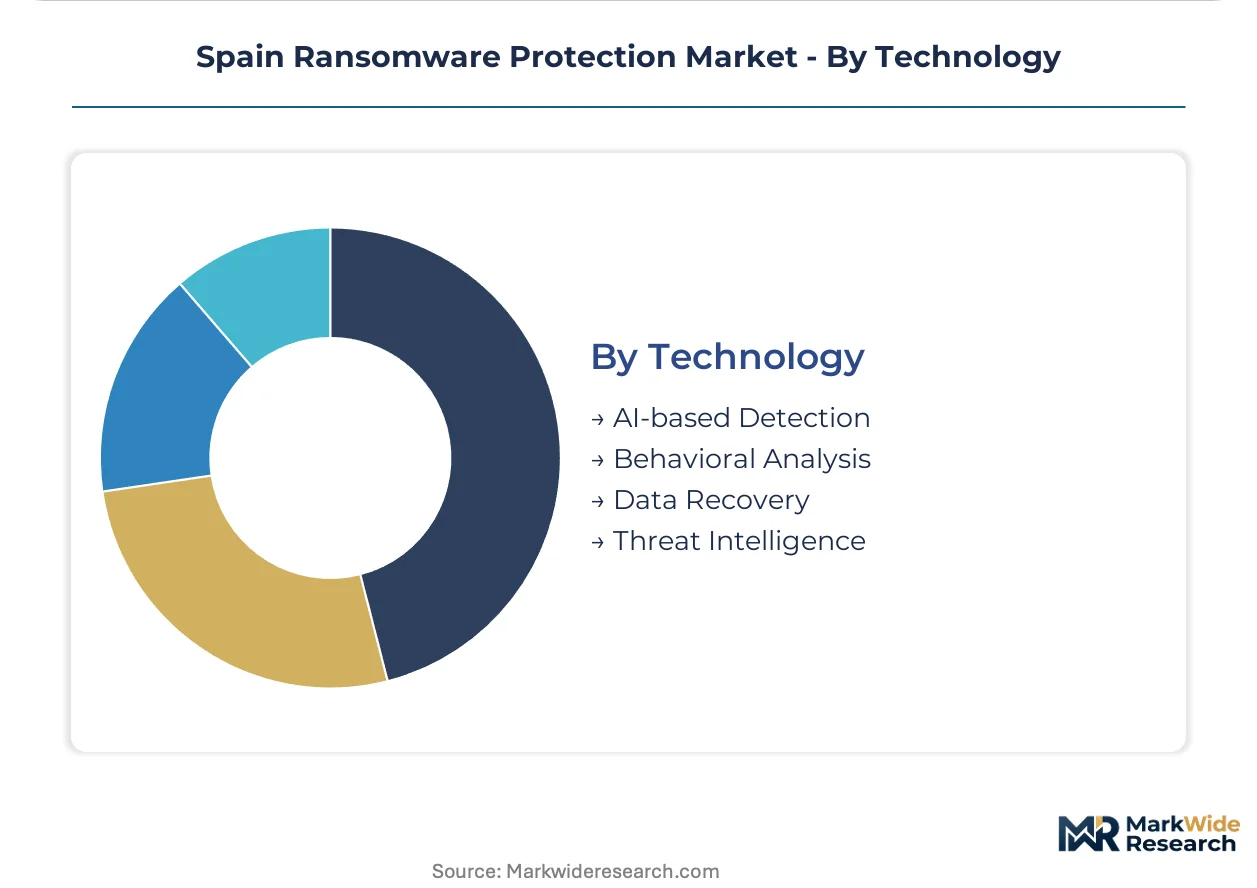
- AI-based Detection:Machine learning models trained on threat telemetry for zero-day identification. Financial services firms in Madrid pilot these systems within twelve-month refresh cycles.
- Behavioral Analysis:Baseline deviation monitoring for insider threat and compromised credential detection. Large corporations shifting from signature-based methods represent core demand concentration.
- Data Recovery:Immutable backup orchestration with automated restoration workflows. GDPR enforcement is elevating procurement for encrypted backup with forensic preservation capabilities.
- Threat Intelligence:Curated indicator feeds and adversary tracking tailored to Iberian threat landscapes. Specialized providers differentiate through regulatory context for Spanish enforcement patterns.
By current deployment share, Behavioral Analysis leads. By capability investment, AI-based Detection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Madrid's corporate technology clusters, while Andalusia and Valencia mid-markets trade at discount tiers due to channel fragmentation and lower procurement sophistication.
Madrid
Financial services firms and critical infrastructure operators drive concentrated demand for automated containment platforms. Spain's national data protection authority enforces GDPR breach notification timelines that compress incident response windows to seventy-two hours. The capital's banking district anchors procurement of integrated detection systems with embedded machine learning engines.
Catalonia
Barcelona's professional services vertical accelerates behavioral analytics adoption for anomaly-driven prevention. EU NIS2 Directive transposition imposes stricter security governance obligations on regional healthcare and transport operators. Mid-market reseller networks in the metropolitan area pivot toward recurring revenue models bundling monitoring with incident response retainers.
Basque Country
Industrial control operators in energy and manufacturing sectors generate specialized demand for protocol-aware network segmentation. The region's legacy infrastructure base creates integration friction with cloud-native protection platforms. Bilbao-based critical infrastructure procurement favors hybrid deployment configurations addressing data sovereignty requirements.
Andalusia
Small enterprises across underpenetrated mid-market reseller networks present channel density expansion opportunities for cloud-based deployment models. Capital expenditure constraints among sub-fifty-employee organizations sustain demand for subscription-based managed detection services. Seville and Málaga technology corridors show fastest adoption velocity as local partners eliminate hardware procurement cycles.
Valencia
Medium enterprises with dedicated IT staff but constrained security specialization drive email security procurement through gateway filtering and sandbox detonation. Remote work patterns elevate attack surface exposure across professional services and healthcare verticals. The metropolitan technology cluster trails Madrid and Barcelona in behavioral analytics penetration but leads in cloud-native endpoint security adoption.
Spain Ransomware Protection Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Spain's ransomware protection market. Capital-heavy integrated providers anchor enterprise-grade managed detection services through national infrastructure footprints, while leaner specialists sustain differentiation through regulatory-tailored threat intelligence. The competitive structure stratifies across three archetypes: telecom-anchored platforms, cybersecurity pure-plays, and channel-dense endpoint vendors. Dominant competitive moves include vertical integration into sovereign cloud infrastructure and strategic partnerships with critical infrastructure operators.
Among Spain-based cybersecurity providers, Telefónica Tech, S21sec Thales, and Panda Security occupy distinct positioning tiers. Telefónica Tech exemplifies the telecom-anchored platform archetype leveraging national infrastructure for enterprise service delivery. S21sec Thales represents the specialist tier with positioning around Iberian regulatory context. Panda Security anchors the channel-dense endpoint archetype extending reach through mid-market reseller networks. These three players collectively illustrate how scale, specialization, and distribution density map to divergent customer segments across Madrid's corporate clusters and regional SME markets.
| Leading Market Players |
|---|
| Telefónica Tech |
| S21sec Thales |
| Panda Security |
| DeepStrike |
| GMV Innovating Solutions |
| Indra Sistemas |
| Factosecure |
| Entelgy Innotec Security |
| Tarlogic |
| Others |
Pricing and Supply Chain Analysis
GDPR certification tiers enforced by Spain's national data protection authority gate vendor qualification while simultaneously stratifying price premiums across deployment models. Compliance with the seventy-two-hour breach notification mandate separates configured-to-order managed detection services from standard endpoint packages, compressing margins for non-compliant suppliers while elevating pricing power for certified platforms.
Pricing Analysis
Configured-to-order pricing for hybrid deployment configurations commands substantial premiums over standardized cloud-native subscriptions. Pricing stratifies across premium, standard, and economy tiers based on machine learning engine sophistication and data sovereignty compliance certification. Cost compression in the economy tier intensifies as channel partners consolidate procurement volumes for SME segments. Small enterprises in Andalusia exhibit highest price sensitivity, while critical infrastructure operators in Madrid's energy sector demonstrate lowest elasticity due to regulatory penalty exposure.
Supply Chain Analysis
Spain and Germany anchor security software development and threat intelligence curation for the European ransomware protection market. Component sourcing draws from Israeli behavioral analytics engines, American cloud infrastructure, and Taiwanese semiconductor fabrication for dedicated appliances. Single-source vulnerability in machine learning training data creates concentration risk for vendors dependent on narrow telemetry partnerships. Distribution runs through Madrid-based systems integrators for enterprise accounts and Barcelona-Valencia reseller networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's ransomware protection market functions as a service-attach opportunity where managed detection and response retainers expand faster than perpetual endpoint licenses. Recurring revenue from automated containment workflows and incident response SLAs outpaces hardware procurement cycles across Madrid's banking district and regional SME markets.
For Market Incumbents: Consolidate channel control through exclusive partnerships with Andalusia and Valencia reseller networks before cloud-native specialists establish density. Acquire threat intelligence boutiques with Iberian regulatory specialization to defend margin position against leaner competitors. Backward integration into sovereign cloud infrastructure addresses data sovereignty requirements under EU NIS2 Directive transposition. For New Entrants and Emerging Players: Lead with AI-driven behavioral analytics tailored to GDPR's compressed incident response windows as the primary wedge against signature-dependent incumbents. Target underpenetrated healthcare verticals in Valencia and Seville where internal security team scale constraints favor outsourced detection. Deploy through channel partners offering bundled email security and endpoint protection to minimize direct sales infrastructure investment. For Investors and Strategic Acquirers: EU Cyber Resilience Act transposition reshapes the acquisition landscape by elevating certification asset values for compliant vendors. Long-term viability favors platforms with recurring revenue concentration above sixty percent and embedded machine learning engines replacing legacy antivirus architectures. Monitor enforcement patterns from Spain's national data protection authority as the signal for accelerated procurement cycles in financial services and critical infrastructure verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying endpoint, network, and cloud detection layers addresses GDPR's seventy-two-hour containment mandate for Madrid banking clients. |
| Acquisition of Specialist Firm | Threat intelligence boutiques with Iberian regulatory context command premium valuations from Telefónica Tech and S21sec Thales. |
| Geographic Expansion | Channel density investments in Seville and Málaga corridors capture cloud-native adoption velocity among Andalusian SMEs. |
| Strategic Partnership | Alliances with Basque Country energy operators secure protocol-aware segmentation contracts for industrial control environments. |
| Product Launch | AI-driven anomaly detection platforms displace signature-based antivirus in Barcelona professional services refresh cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, channel partner disclosures, and hyperscaler capex reports across the European cybersecurity sector. Conversations with CISOs at Madrid financial institutions, procurement leads at Catalan healthcare systems, channel sales directors in Valencia, and incident response specialists at Basque energy operators informed demand-side validation. SEC filings from listed security vendors, Spain's national data protection authority enforcement bulletins, and EU NIS2 Directive implementation timelines provided secondary triangulation. Bottom-up segmentation modeling and top-down macroeconomic anchoring converged on volume and value estimates.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical industry, technology maturity, and regional technology cluster concentration. Growth trajectories across the analysis window derive from penetration rate assumptions by segment, replacement cycle compression in financial services, and regulatory enforcement intensity. Machine learning adoption curves, cloud migration velocity among SMEs, and critical infrastructure operator procurement patterns served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained GDPR enforcement pressure, stable hyperscaler infrastructure pricing, and functional EU Cyber Resilience Act transposition would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and channel partner consolidation velocity. Recalibration cycles align with material shifts in Spanish data protection authority enforcement patterns and NIS2 Directive implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Rescue Pole Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market