
 Electronic Security Systems Market | 2026-2036
Electronic Security Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Security Systems Market Analytics
Buyer concentration across the commercial real estate sector is rebalancing as property management groups consolidate portfolios and standardize security infrastructure across multi-site operations. Honeywell International Inc. leverages its building automation integration to capture bundled security contracts. Robert Bosch GmbH sustains engineering-intensive R&D programs for video analytics and edge computing cameras. Axis Communications AB specializes in open-platform IP camera architectures that appeal to enterprise buyers seeking vendor flexibility.
Electronic security systems encompass integrated hardware and software platforms designed to detect, deter, and document unauthorized access or activity through sensors, cameras, biometric readers, and centralized management consoles operating across analog, IP-based, or hybrid network architectures. These systems serve primary commercial and industrial purposes including asset protection, personnel safety, regulatory compliance documentation, and operational continuity assurance. CCTV cameras and video analytics together represent the largest product value pool, though access control systems command superior margins due to biometric integration complexity and recurring software licensing structures. The residential application segment remains fragmented with price-sensitive demand, while government and industrial verticals drive specification-grade procurement with longer replacement cycles and stricter certification requirements.
The EU AI Act and GDPR impose algorithmic transparency and data retention constraints on facial recognition and behavioral analytics deployments across European jurisdictions. The FCC in the United States governs wireless spectrum allocation for sensor networks and IoT-enabled security devices, while cybersecurity mandates from NIST affect product certification pathways. Stakeholders must monitor evolving cross-border data flow restrictions and harmonization gaps between regional AI governance frameworks as these will determine which video analytics features achieve scalable deployment.
Market Dynamics
AI-driven video analytics is compressing hardware margins while elevating software licensing revenue, forcing manufacturers to restructure product architectures around recurring subscription models rather than one-time equipment sales.
Growth Catalysts
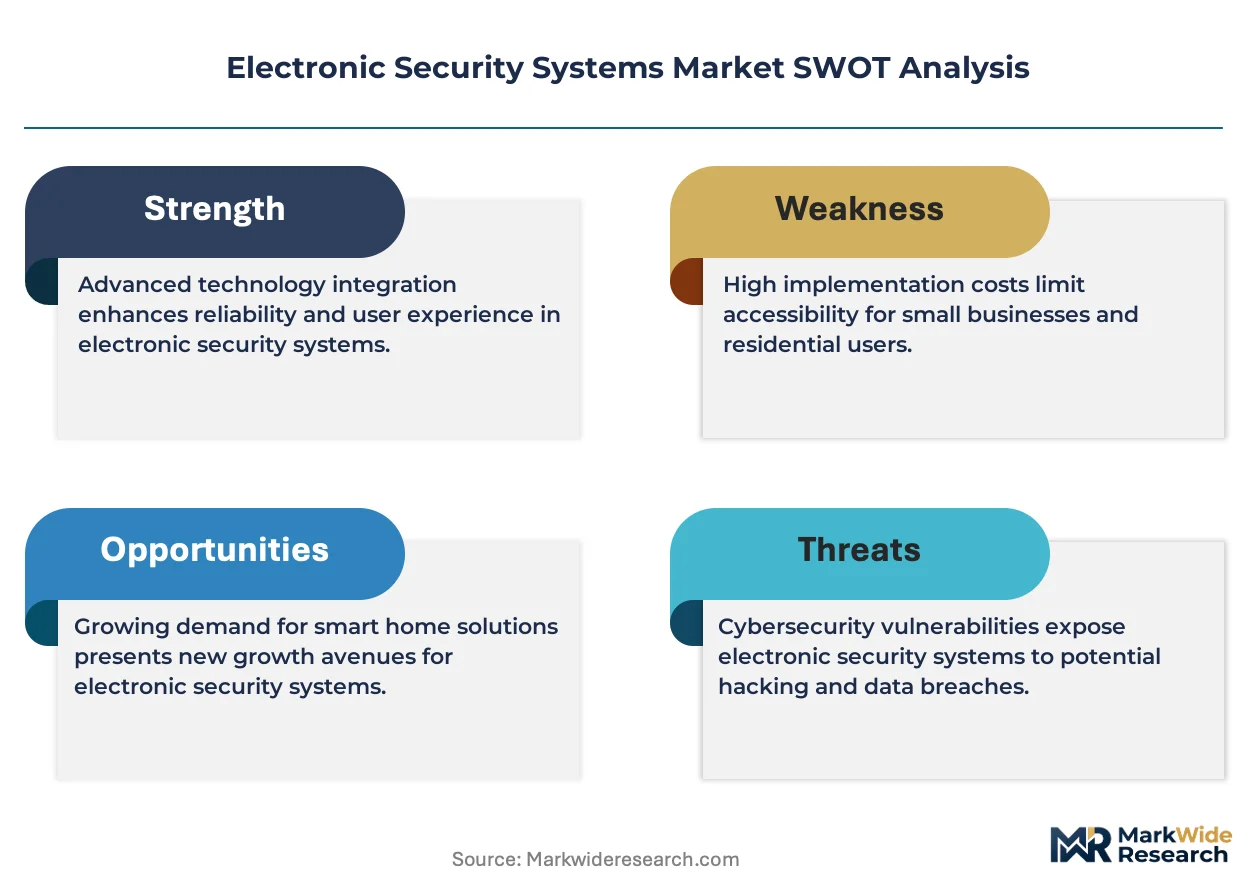
- EU AI Act compliance mandates:Healthcare facilities across Germany, France, and Italy are accelerating biometric access control deployments to meet algorithmic transparency requirements for patient data protection zones.
- Edge computing camera architectures:On-device processing is reducing bandwidth costs for industrial automation buyers operating multi-site manufacturing networks with limited connectivity.
- Smart city infrastructure budgets:Municipal governments in Spain and the Netherlands are consolidating surveillance tenders into framework agreements that favor integrated platform providers over point-product vendors.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends on TSMC and Samsung foundry capacity, creating 16-24 week lead time volatility for camera manufacturers.
- GDPR data retention constraints:Facial recognition deployments face 72-hour deletion mandates that limit behavioral analytics training datasets and model accuracy improvement cycles.
- Legacy analog infrastructure:Commercial real estate portfolios retain coaxial cable installations that require complete cabling replacement for IP-based system upgrades, inflating retrofit project costs.
Strategic Opportunities
- Healthcare cybersecurity convergence:HIPAA-covered entities in the United States are procuring unified physical-cybersecurity platforms that consolidate badge systems with network access controls under single vendor relationships.
- As-a-service distribution models:System integrators in Poland and Czechia are offering surveillance-as-a-service contracts that transfer capital expenditure to operational budgets for mid-sized retail chains.
- NIST cybersecurity framework alignment:Federal procurement pathways now require IoT-enabled security devices to demonstrate supply chain attestation, creating certification barriers that favor established domestic manufacturers.
Industry Challenges
- Embedded systems engineering scarcity:Camera firmware development requires specialized expertise in low-power computer vision that commands premium compensation and extends hiring timelines.
- Multi-protocol integration complexity:Enterprise buyers demand ONVIF, PSIA, and proprietary API compatibility within single management consoles, fragmenting R&D resources across interoperability testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Security Systems Market |
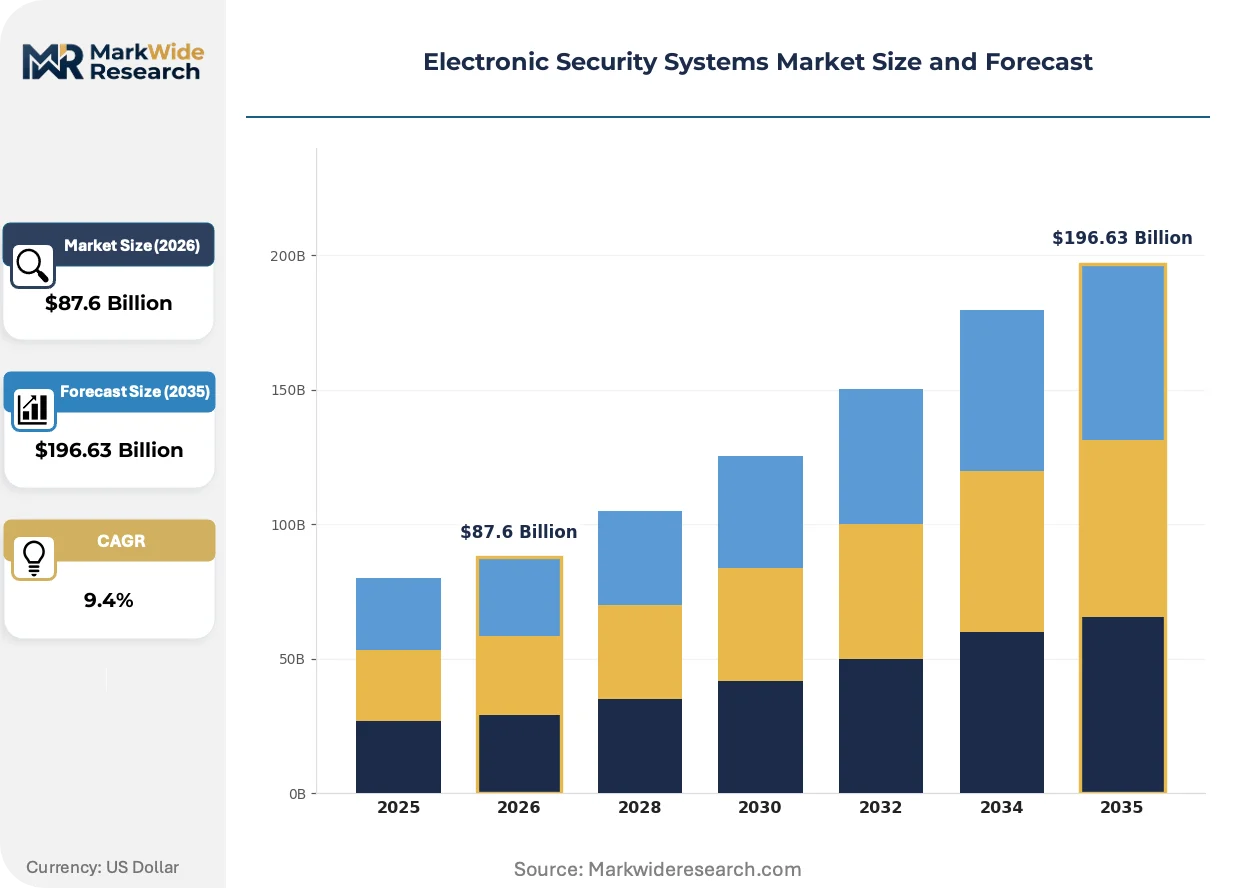
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusion Alarms, Access Control Systems, CCTV Cameras, Video Analytics Technology: Biometric, RFID, IP-based, Analog Application: Residential, Commercial, Industrial, Government End User: Retail, Hospitality, Education, Healthcare |
| Companies Covered | Honeywell International Inc., Robert Bosch GmbH, Johnson Controls International plc, Axis Communications AB, Hangzhou Hikvision Digital Technology Co., Ltd., ADT Inc., Zhejiang Dahua Technology Co., Ltd., ASSA ABLOY AB, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Security Systems Market Evolving Landscape
Video analytics, edge processing, and cloud-native management platforms are converging into unified architectures that compress deployment timelines while expanding software monetization opportunities for platform vendors.
Edge AI processors from Ambarella and Qualcomm are unifying video encoding, object detection, and metadata extraction within camera enclosures. Industrial facilities in Germany are adopting these systems to reduce backhaul bandwidth requirements for perimeter monitoring applications. This unification is compressing the traditional VMS server market while elevating camera ASPs through embedded intelligence premiums.
The EU AI Act's risk-based classification system is mandating conformity assessments for biometric identification systems deployed in public spaces. Video analytics vendors are restructuring product roadmaps to separate prohibited real-time remote biometric identification from permitted post-event investigation tools. Healthcare and transportation verticals are most affected, with French hospital groups delaying facial recognition pilots pending notified body certification clarity.
Buyers are consolidating vendor relationships through single-source framework agreements that bundle hardware, software, and maintenance under multi-year commitments. Property management groups operating pan-European portfolios are displacing regional integrators with direct manufacturer relationships that standardize equipment specifications across 50+ site deployments. This concentration is most visible in the United Kingdom, where REITs have compressed supplier bases from twelve vendors to three preferred partners since 2023.
Electronic Security Systems Market Segmentation
Electronic security systems fragment across hardware, software, and service layers with distinct margin profiles and replacement dynamics. Understanding segment boundaries clarifies where capital expenditure concentrates versus where operational budgets dominate procurement patterns.
Product Type:
Replacement cycles vary dramatically across hardware categories, with legacy analog installations driving simultaneous upgrade demand for cabling infrastructure and endpoint devices.
- CCTV Cameras:IP-based dome and bullet cameras with 4K resolution and edge processing capabilities now dominate new installations. German industrial facilities and Dutch smart city programs are consolidating tenders around ONVIF-compliant architectures that reduce vendor lock-in.
- Video Analytics:AI-driven software platforms perform real-time object detection, behavioral analysis, and anomaly flagging through on-device or server-based processing. Healthcare facilities in France and transportation hubs in Spain are accelerating deployments despite EU AI Act conformity assessment delays.
- Access Control Systems:Integrated biometric readers, card credentials, and centralized management consoles govern physical entry points.
- Intrusion Alarms:Perimeter sensors, glass-break detectors, and central monitoring station integrations provide foundational threat detection.
CCTV Cameras sits at the top of the volume ranking, with Video Analytics climbing the fastest.
Technology:
Cost tiers separate premium biometric deployments from commodity analog replacements, with mid-market buyers gravitating toward hybrid IP solutions that preserve existing infrastructure investments.
- IP-based:Network-connected devices transmit encrypted video and access events over Ethernet or WiFi infrastructure with Power-over-Ethernet simplification. Commercial real estate portfolios across Poland and Czechia are standardizing on PoE camera architectures to reduce electrical contractor dependencies.
- Biometric:Fingerprint, iris, and facial recognition readers provide non-transferable credential verification with liveness detection anti-spoofing. German healthcare groups are deploying these for patient data protection zones under EU AI Act transparency mandates.
- RFID:Contactless card and fob credentials operate through 125kHz legacy or 13.56MHz encrypted protocols.
- Analog:Coaxial-based CCTV and wired alarm sensors persist in aging commercial installations requiring complete infrastructure overhaul for digital migration.
IP-based holds the dominant installed base position, while Biometric is gaining share fastest among specification-grade buyers.
Application:
Customer type determines procurement sophistication, with government and industrial verticals demanding certified products through formal tender processes while residential buyers prioritize price and installation simplicity.
- Industrial:Manufacturing facilities, logistics centers, and critical infrastructure sites require perimeter hardening, hazardous area monitoring, and integration with operational technology networks. German automotive plants and Benelux distribution hubs are driving edge-computing camera demand to reduce bandwidth constraints.
- Government:Municipal buildings, law enforcement facilities, and transportation authorities mandate strict compliance with data protection and procurement transparency regulations. Spanish and Dutch smart city frameworks are consolidating surveillance contracts under multi-year integrated platform agreements.
- Commercial:Office buildings, retail establishments, and hospitality venues balance security effectiveness with visitor experience and staff convenience.
- Residential:Single-family homes and multi-unit dwellings rely on DIY-installable cameras, smart doorbells, and monitored alarm services with smartphone integration.
Industrial leads in average contract value, with Government showing the steepest expansion trajectory in framework agreement consolidation.
End User:
Application context shapes feature requirements, with regulated industries demanding audit trails and data residency controls that consumer-facing sectors de-prioritize.
- Healthcare:Hospitals, clinics, and aged care facilities must protect patient privacy under HIPAA and GDPR while securing pharmaceutical storage and restricted clinical zones. French hospital groups are delaying biometric pilots pending EU AI Act notified body clarity.
- Education:K-12 schools and university campuses require lockdown capabilities, visitor management, and integration with mass notification systems.
- Retail:Loss prevention, occupancy analytics, and queue management drive camera density with cloud-hosted video retention.
- Hospitality:Guest safety, back-of-house access control, and reputation protection guide procurement with emphasis on discreet aesthetics.
Healthcare commands the highest compliance-driven pricing premium, with Education expanding most quickly amid school safety infrastructure allocations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation investments outpace France's healthcare facility upgrades, though both countries face identical EU AI Act compliance deadlines for biometric deployments.
Germany
Automotive plants in Bavaria and Baden-Württemberg drive edge-computing camera demand for perimeter monitoring with limited bandwidth. The KBA and BSI enforce cybersecurity certification for IoT-enabled security devices under EU NIS2 transposition. Siemens AG anchors industrial security integration in the Ruhr manufacturing corridor.
United States
Federal procurement pathways require NIST cybersecurity framework alignment for IoT security devices. HIPAA-covered entities consolidate physical-cybersecurity platforms under single vendor relationships. Greater Boston and Pacific Northwest healthcare clusters lead biometric access control deployments for patient data protection zones.
France
Hospital groups in Île-de-France delay facial recognition pilots pending EU AI Act notified body certification clarity. The CNIL enforces GDPR data retention constraints limiting behavioral analytics training datasets. Auvergne-Rhône-Alpes transportation hubs accelerate video analytics despite regulatory uncertainty.
Spain
Municipal governments consolidate surveillance tenders into framework agreements favoring integrated platform providers. The Spanish Data Protection Agency enforces algorithmic transparency requirements for public space deployments. Madrid and Barcelona smart city programs standardize on ONVIF-compliant camera architectures.
Netherlands
Randstad municipal governments bundle hardware, software, and maintenance under multi-year commitments. The Dutch Data Protection Authority aligns enforcement with EU AI Act risk-based classification systems. Eindhoven industrial automation buyers adopt edge computing to reduce backhaul bandwidth requirements.
Electronic Security Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service layers. The vendor base stratifies into three tiers: integrated building automation providers, camera hardware specialists, and software-centric analytics platforms. Strategic archetypes include full-stack integrators leveraging bundled contracts, component specialists defending margin through embedded intelligence premiums, and platform vendors capturing recurring subscription revenue. Dominant competitive moves center on framework agreement consolidation for multi-site portfolios and backward integration into edge AI processor supply.
Among diversified conglomerates, Honeywell International Inc. and Siemens AG exemplify full-stack positioning through building automation integration. Robert Bosch GmbH occupies a position within the engineering-intensive tier, representing sustained R&D commitment for video analytics development. Axis Communications AB anchors the open-platform specialist archetype, exemplifying vendor-flexibility positioning that appeals to enterprise buyers seeking interoperability. These three entities collectively illustrate how competitive positioning fragments across integration depth, hardware specialization, and software platform strategies.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Robert Bosch GmbH |
| Johnson Controls International plc |
| Axis Communications AB |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| ADT Inc. |
| Zhejiang Dahua Technology Co., Ltd. |
| ASSA ABLOY AB |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Captive integration into edge AI processor design anchors both supply security and pricing power for camera manufacturers deploying embedded intelligence at scale. This backward integration choice separates premium-tier vendors commanding software subscription premiums from commodity hardware producers facing margin compression.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for image sensors and SoC components. The dominant pricing structure stratifies across premium, standard, and economy tiers, with certification grade under EU AI Act conformity assessments and volume scale driving differentiation. Cost compression in the economy tier is intensifying because Chinese manufacturers are flooding mid-market channels with ONVIF-compliant alternatives. Residential buyers exhibit highest price sensitivity, while healthcare and government verticals accept specification-grade premiums for biometric-integrated access control systems.
Supply Chain Analysis
Single-source vulnerability sits with TSMC foundry capacity for advanced node image signal processors and Samsung for stacked CMOS sensor fabrication. Component sourcing draws from Taiwan, South Korea, and China, with raw material dependencies spanning silicon wafers, rare earth magnets for camera positioning motors, and specialized optical glass. Tariff exposure on Chinese-assembled finished goods threatens margin stability for vendors without regional manufacturing footprints. Distribution runs through system integrators and direct manufacturer relationships for enterprise accounts, with e-commerce channels serving price-sensitive residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronic Security Systems Market functions as a regulatory compounder, with EU AI Act compliance deadlines forcing replacement cycles across European healthcare and transportation infrastructure.
For Market Incumbents: To counter margin erosion from AI-driven software licensing transitions, Honeywell and Siemens should deepen backward integration into edge AI processor supply chains while accelerating framework agreement consolidation for pan-European property management portfolios. Certification investment in EU AI Act notified body relationships represents the critical defensive lever. For New Entrants and Emerging Players: Capture the surveillance-as-a-service white space across Poland and Czechia mid-sized retail chains, where capital expenditure constraints favor operational budget transfers. The most penetrable segment sits in healthcare cybersecurity convergence platforms unifying physical badge systems with network access controls, best approached through channel partnerships with existing HIPAA compliance consultants. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with established notified body relationships because EU AI Act certification creates scalable barriers against unqualified competitors. Acquisition targets should demonstrate software platform recurring revenue above hardware resale. The signal to watch is notified body certification queue lengths as an inflection indicator for deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Backward Integration | Captive supply of Ambarella and Qualcomm alternatives reduces TSMC dependency for German automotive plant contracts. |
| EU AI Act Notified Body Certification | Early conformity assessment completion unlocks French hospital group biometric access control tenders. |
| Surveillance-as-a-Service Platform Launch | Operational budget conversion captures Polish retail chains unable to fund capital-intensive IP camera retrofits. |
| Framework Agreement Consolidation | Direct manufacturer relationships displace regional integrators for UK REIT 50+ site standardization programs. |
| Healthcare Cybersecurity Convergence | Unified physical-cybersecurity platforms address HIPAA-covered entity procurement mandates in Greater Boston clusters. |
Research Methodology
Coverage spans Germany, France, the United States, and the Netherlands, with primary inputs from each market triangulated against secondary validation. Security system procurement officers at healthcare facilities, industrial automation engineers at German automotive plants, regulatory affairs leads navigating EU AI Act implementation, and smart city program managers in Dutch municipalities provided structured interview inputs. Secondary sources include FCC spectrum allocation filings, EMA cybersecurity guidance documents, SEC 10-K disclosures from diversified conglomerates, and customs trade data for camera component flows. Bottom-up unit economics and top-down market sizing approaches were reconciled through iterative validation.
Rate-of-change decomposition across hardware replacement cycles, software licensing transitions, and regulatory compliance waves structured the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, technology tier, application vertical, and end-use industry, with biometric integration complexity and edge processing capability as industry-specific dimensions. CAGRs were derived from installed base evolution, pricing trajectory assumptions, and penetration rate shifts across the analysis window. Forecast inputs incorporated EU AI Act implementation timelines, NIST cybersecurity framework adoption curves, and semiconductor foundry capacity expansion announcements.
Regulatory enforcement variance, semiconductor supply disruptions, and AI algorithm performance breakthroughs are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about compliance deadline adherence and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Vehicle Security System Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Canada Access Control Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Wireless Security System Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
Asia-Pacific Access Control Hardware Market