
 Mechanical Locks Market | 2026-2036
Mechanical Locks Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Locks Market Outlook
Skilled locksmith labor availability is collapsing across North American and European manufacturing hubs, forcing incumbents to automate keyway machining and assembly processes. Assa Abloy leverages its captive foundry network to insulate production from volatile zinc alloy supply. Master Lock Company anchors its position through extreme-scale padlock output serving industrial and commercial channels. Dorma Kaba Group specializes in precision-engineered locking systems for institutional clients requiring certified access control integration.
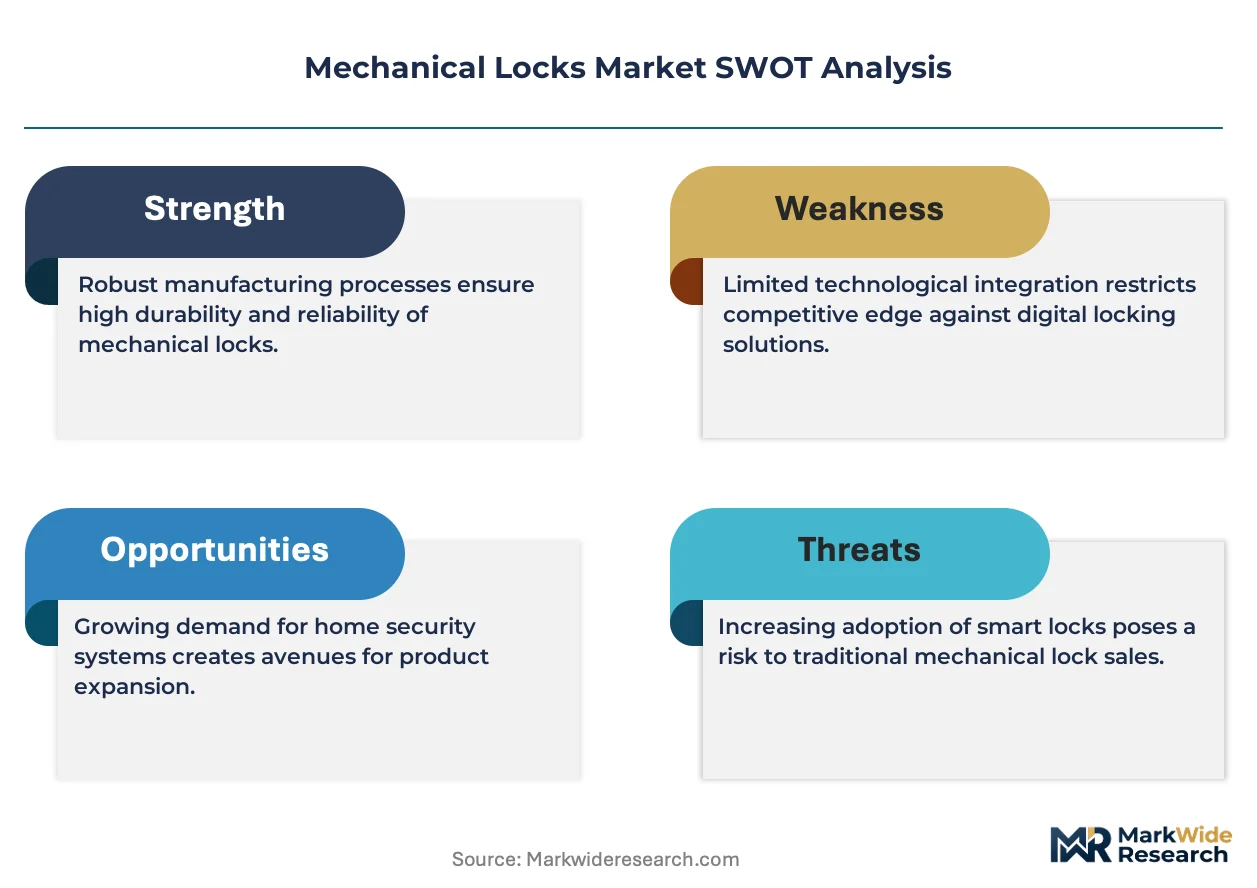
Mechanical locks are physical security devices constructed from brass, zinc alloy, or stainless steel housings that engage boltwork through key-operated pin tumbler, wafer, or lever mechanisms to restrict unauthorized entry. These devices typically achieve security ratings through standardized testing of bolt strength, pick resistance, and cycle durability, serving as foundational perimeter protection across buildings, storage assets, and critical infrastructure. Deadbolts and lever handle locks command the largest revenue pools in residential and commercial installation, while Grade 1 and Grade 2 security ratings capture disproportionate margin as institutional buyers mandate certified performance for schools, hospitals, and government facilities. Padlocks retain volume dominance in industrial applications where portable security requirements persist across construction, logistics, and utility sectors.
Underwriters Laboratories maintains the dominant North American testing protocol through its UL 437 standard for key locks, while the European Committee for Standardization governs mechanical lock performance through EN 12209 and EN 1303 classifications that dictate cycle testing and corrosion benchmarks. China's SAMR enforces GB standards mandating specific material compositions and dimensional tolerances for locks sold in domestic commerce. Stakeholders must monitor evolving building code harmonization between national standards bodies and the accelerating substitution threat from electronic access systems in premium commercial segments.
Market Dynamics
China's SAMR is enforcing stricter GB standards on alloy composition, forcing manufacturers to reformulate zinc-brass housings while Southeast Asian residential construction pulls lever handle and deadbolt volumes upward.
Growth Catalysts
- India's Tier-Two Commercial Expansion:Office and retail asset development in cities like Pune and Ahmedabad is accelerating mechanical lock procurement for new commercial installations.
- EN 1303 Certification Mandates:European institutional buyers now require corrosion-tested cylinders for schools and hospitals, pulling Grade 1 and Grade 2 rated products into premium positioning.
- Pin Tumbler Automation:CNC keyway machining systems are cutting unit production costs for high-volume deadbolt manufacturers serving North American big-box retail channels.
Market Restraints
- Zinc Alloy Price Volatility:Foundry-grade zinc concentrate supply concentrates in Chinese smelters, exposing non-integrated manufacturers to input cost swings.
- Electronic Access Substitution:RFID and biometric systems are capturing specification share in premium commercial segments where landlords prioritize tenant credential management.
- UL 437 Testing Bottlenecks:Underwriters Laboratories certification queues for high-security cylinders extend lead times by eight to fourteen weeks, freezing new product launches.
Strategic Opportunities
- Vietnam's Residential Pipeline:Foreign direct investment into Ho Chi Minh City and Da Nang condominium projects is creating first-time demand for ANSI Grade 2 lever sets.
- Smart Lock Hybridization:Mechanical-electronic convergence modules allow traditional deadbolts to integrate with building management systems without full replacement.
- Industrial Padlock Channel Expansion:Direct-to-fleet sales through construction equipment rental platforms bypass distributor markups for Master Lock-type volume suppliers.
Industry Challenges
- Skilled Machinist Scarcity:North American and European manufacturing hubs face collapsing availability of locksmiths capable of hand-fitting pin stacks and mastering key systems.
- Multi-Jurisdiction Certification Stacking:Exporters must simultaneously satisfy UL 437, EN 12209, and SAMR GB standards, tripling documentation and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Locks Market |
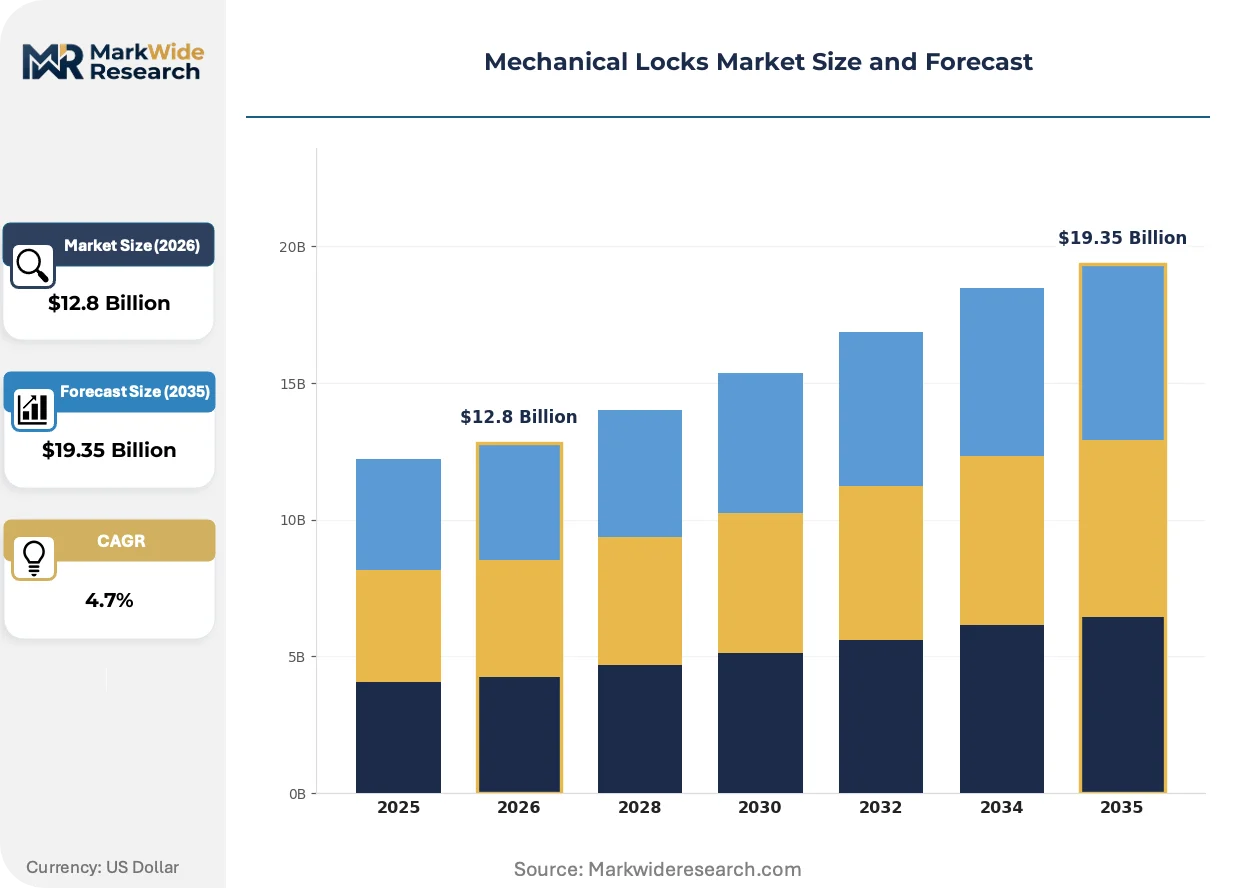
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolts, Padlocks, Knob Locks, Lever Handle Locks Installation Type: Floor Mounted, Wall Mounted, Surface Mounted, Flush Mounted End User: Residential, Commercial, Institutional, Industrial Security Rating: Grade 1, Grade 2, Grade 3, Grade 4 |
| Companies Covered | Dorma Kaba Group, Master Lock Company, Assa Abloy, Kwikset, Schlage, Allegion, Spectrum Brands, Baldwin, Godrej & Boyce Mfg. Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Locks Market Strategic Shifts
Material science advances and regulatory tightening are compressing traditional mechanical lock design cycles while opening modular integration pathways with electronic access platforms.
Stainless steel alloy formulations with enhanced corrosion resistance are fragmenting the traditional brass-dominant specification base for coastal and high-humidity installations. Marine facility operators and Southeast Asian condominium developers are specifying 304-grade housings at accelerating rates. This metallurgical shift is fragmenting supplier tiers between captive foundry operators and commodity brass casters unable to justify stainless capital expenditure.
China's SAMR updated GB/T 8383 lock standards now mandate specific copper-zinc ratios and dimensional tolerances for all locks sold in domestic commerce. Manufacturers must reformulate existing die-cast tooling or face market exclusion. Export-oriented Chinese foundries are bifurcating production lines between SAMR-compliant domestic SKUs and legacy formulations for Southeast Asian re-export markets.
Facility managers are unbundling hardware procurement from installation services, issuing separate RFPs for certified locksmiths versus lockset supply. This disintermediation compresses distributor margins while rewarding direct-manufacturer relationships with national maintenance contractors. The pattern is most visible in US multi-site retail chains standardizing on single-source deadbolt platforms with centralized keying protocols.
Mechanical Locks Market Segmentation
Mechanical lock procurement patterns diverge sharply across installation contexts, with security ratings and mounting configurations dictating margin capture. Manufacturers must align alloy specifications and certification investments to the precise tier where buyers concentrate spending.
Product Type:
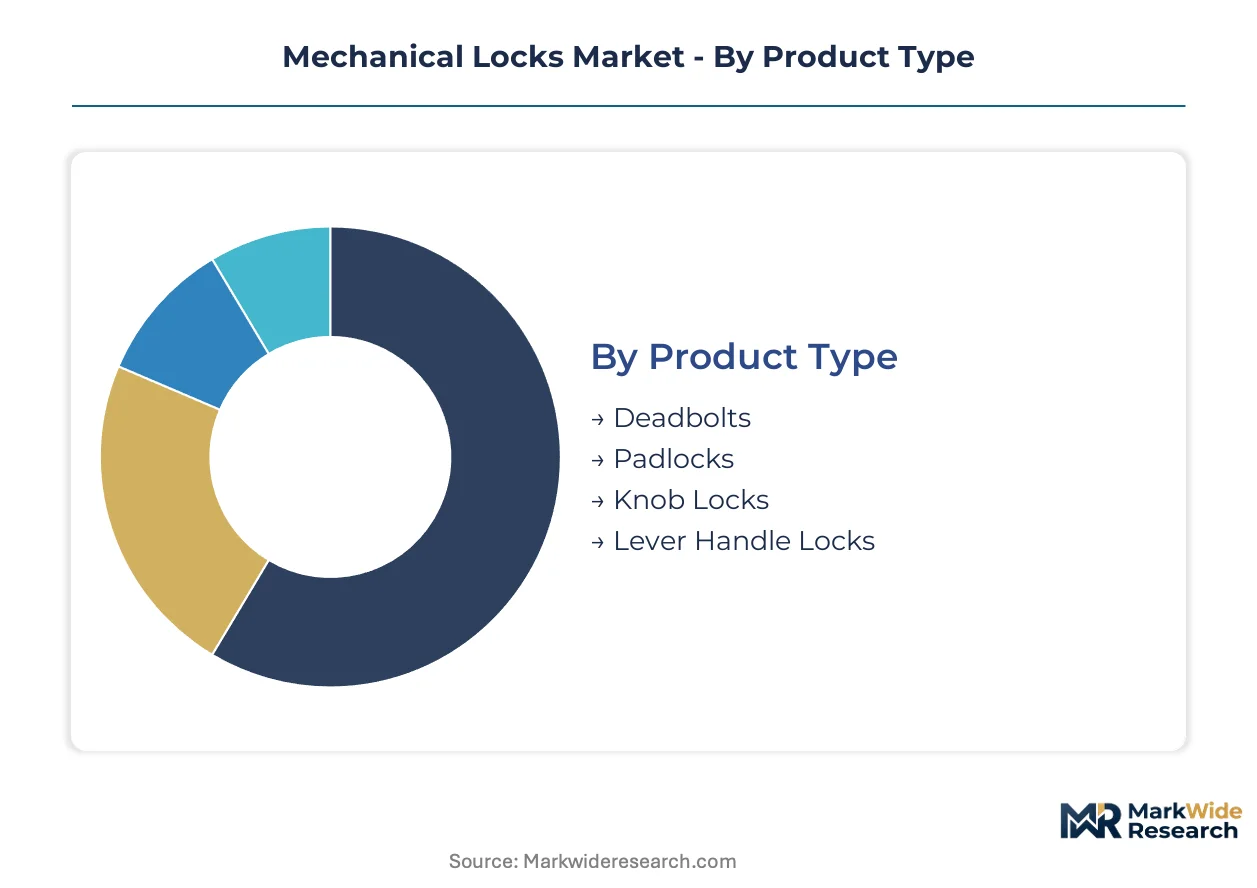
Margin pools concentrate in lever handle and deadbolt categories where residential and commercial specifications overlap most heavily.
- Deadbolts:Single-cylinder and double-cylinder variants employ hardened steel bolts extending into door jambs to resist forced entry. India's tier-two commercial construction in Pune and Ahmedabad is pulling ANSI Grade 1 and Grade 2 deadbolt volumes upward as office assets prioritize perimeter security.
- Lever Handle Locks:Spring-loaded lever mechanisms satisfy accessibility codes while accommodating master keying systems for multi-tenant facilities. Vietnam's condominium pipeline across Ho Chi Minh City and Da Nang is generating first-time demand for ANSI Grade 2 lever sets in residential towers.
- Padlocks:Portable shackle locks serve construction equipment fleets and logistics containers where temporary security requirements dominate.
- Knob Locks:Cylindrical knob configurations retain volume in interior residential applications where security demands remain minimal.
The dominant share belongs to deadbolts, while lever handle locks are closing the gap fastest.
Installation Type:
Cost-to-serve varies dramatically across mounting methods, with flush and floor installations demanding specialized labor that protects premium pricing.
- Surface Mounted:Exposed lock bodies attach directly to door faces without mortising, minimizing installation labor for retrofit applications. North American big-box retail channels favor surface-mounted deadbolts for consumer self-installation, compressing margin through price transparency.
- Flush Mounted:Recessed housings sit flush with door surfaces, requiring precise mortising that filters demand toward certified locksmith networks. European institutional buyers specify flush-mounted cylinders for EN 1303-certified school and hospital installations where corrosion resistance and clean aesthetics converge.
- Floor Mounted:Bottom-locking bolts engage floor strikes for high-security commercial entrances.
- Wall Mounted:Vertical locking hardware secures gates, shutters, and specialized industrial access points.
Surface-mounted hardware commands volume leadership, though flush-mounted specifications are expanding most quickly in institutional segments.
End User:
Customer-type segmentation reveals where certification mandates and procurement centralization reshape competitive access.
- Commercial:Office buildings, retail chains, and hospitality assets require standardized keying protocols across multi-site portfolios. US multi-site retail operators are unbundling hardware procurement from installation, issuing separate RFPs for lockset supply versus certified locksmith services.
- Institutional:Schools, hospitals, and government facilities mandate UL 437 or EN 1303 certified cylinders with documented cycle testing. China's SAMR GB standards enforcement is bifurcating supplier tiers between compliant domestic SKUs and legacy formulations for re-export markets.
- Residential:Single-family and multi-family housing drives lever handle and deadbolt volume through builder specification and retail replacement.
- Industrial:Construction, logistics, and utility sectors sustain padlock demand through portable security requirements.
Commercial end-use holds the largest revenue pool, while institutional procurement is gaining share fastest through certification mandates.
Security Rating:
Grade stratification determines pricing architecture, with higher tiers capturing disproportionate margin through testing investment barriers.
- Grade 1:Highest cycle durability and impact resistance ratings serve commercial and institutional applications where forced-entry protection is paramount. UL 437 certification queues extending eight to fourteen weeks freeze new product launches, insulating incumbents with approved portfolios.
- Grade 2:Mid-tier ratings balance residential security with cost accessibility, dominating Southeast Asian residential construction where foreign direct investment is accelerating mechanical lock procurement.
- Grade 3:Basic residential security ratings satisfy minimum code requirements in price-sensitive housing segments.
- Grade 4:Specialized high-security cylinders address government and critical infrastructure applications with restricted keyways.
Grade 2 specifications anchor volume, while Grade 1 ratings are climbing the fastest as institutional buyers harden security requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. North American buyers prioritize Grade 1 certification for institutional security, while Southeast Asian markets emphasize cost-accessible Grade 2 lever sets for residential towers. European procurement centers on corrosion-tested cylinders under EN 1303 mandates.
United States
Multi-site retail chains and hospitality portfolios drive centralized deadbolt procurement with standardized keying protocols. OSHA workplace safety guidelines influence commercial building access specifications. The Southeast construction corridor spanning Florida and Georgia generates sustained demand for ANSI Grade 2 surface-mounted hardware in residential subdivisions.
China
SAMR enforcement of updated GB/T 8383 standards is bifurcating production between compliant domestic SKUs and legacy formulations for export. The Yangtze River Delta manufacturing cluster around Shanghai houses captive foundry operations that insulate integrated producers from zinc alloy volatility. Shenzhen and Guangzhou developers specify stainless steel 304 housings for coastal condominium projects.
Germany
EN 12209 and EN 1303 certification mandates pull premium-grade cylinders into school and hospital specifications. The country's national building regulator emphasizes cycle durability testing for institutional procurement. Industrial fabricators in North Rhine-Westphalia supply precision-engineered locking systems for certified access control integration across European Union public infrastructure.
India
Tier-two commercial construction in Pune and Ahmedabad accelerates mechanical lock procurement for office and retail assets. BIS standards enforcement creates compliance barriers for imported hardware while favoring domestic manufacturers. The Maharashtra-Gujarat industrial corridor concentrates fabrication capacity serving both domestic institutional buyers and Middle East re-export markets.
Vietnam
Foreign direct investment into Ho Chi Minh City and Da Nang condominium projects creates first-time demand for ANSI Grade 2 lever sets in residential towers. The country's national standards body is harmonizing building codes with ASEAN technical regulations. Construction material suppliers in the Southern Key Economic Zone are expanding mechanical lock distribution networks to capture specification share in high-rise developments.
Mechanical Locks Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operations and certification portfolios determining competitive access. The market structure rewards backward integration into zinc alloy supply and punishes commodity assemblers exposed to raw material swings. Three archetypes dominate: scale-driven padlock manufacturers, precision-engineered institutional specialists, and hybrid mechanical-electronic integrators. Consolidation pressure is intensifying through M&A activity targeting regional certification portfolios, while capacity expansion concentrates in Southeast Asian hubs serving proximate residential construction.
Among integrated European-based manufacturers, Assa Abloy and Dorma Kaba Group exemplify the institutional-specialist archetype through precision-engineered locking systems and certified access control integration. Master Lock Company anchors the scale-driven tier with extreme-volume padlock output serving industrial and commercial channels. These three entities occupy positions that reflect the market's bifurcation between premium certification-heavy institutional procurement and price-sensitive volume segments.
| Leading Market Players |
|---|
| Dorma Kaba Group |
| Master Lock Company |
| Assa Abloy |
| Kwikset |
| Schlage |
| Allegion |
| Spectrum Brands |
| Baldwin |
| Godrej & Boyce Mfg. Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Stainless steel alloy substitution for traditional brass housings is simultaneously relocating foundry investment toward coastal China and compressing margin structures for commodity casters unable to fund metallurgical retooling. SAMR's GB/T 8383 enforcement bifurcates production economics between compliant domestic SKUs and legacy formulations, fragmenting pricing power across export-oriented and China-facing supply lines.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement for Grade 1 certified cylinders, while spot purchasing prevails in residential retail channels where big-box distributors compete on transparency. Three-tier pricing structure across premium, standard, and economy levels separates UL 437-certified institutional hardware from ANSI Grade 2 residential specifications and unbranded commodity deadbolts. Cost compression in Grade 2 lever sets is intensifying because Vietnamese condominium developers prioritize volume scale over corrosion-tested performance. Residential replacement buyers exhibit highest price sensitivity, while institutional facilities managers absorb premiums for documented cycle durability.
Supply Chain Analysis
Strategic stockpiling of foundry-grade zinc concentrate characterizes integrated manufacturers like Assa Abloy, while just-in-time raw material flows expose non-captive assemblers to Shanghai smelter price volatility. Supply concentrates in China, India, and Vietnam, with the Yangtze River Delta and Maharashtra-Gujarat corridor housing die-cast tooling capacity. Zinc alloy, brass rod, and 304-grade stainless steel constitute critical input dependencies. Single-source vulnerability concentrates in Chinese zinc smelters. Distribution runs through national locksmith networks and direct-to-fleet industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical lock demand is recovering from cyclical lows as Southeast Asian residential construction accelerates and institutional buyers harden security specifications post-pandemic.
For Market Incumbents: Compound certification portfolio depth by accelerating UL 437 and EN 1303 testing investments before queue bottlenecks worsen, while securing captive zinc alloy supply through backward integration into Yangtze River Delta foundry partnerships to neutralize raw material volatility threatening margin stability. For New Entrants and Emerging Players: Lead with ANSI Grade 2 lever set specifications targeting Vietnam's Ho Chi Minh City and Da Nang condominium pipeline, where foreign direct investment creates first-time demand without entrenched supplier relationships, deploying direct-manufacturer contracting with national maintenance contractors to bypass distributor markups. For Investors and Strategic Acquirers: The market sits at an early-cycle recovery phase that favors vertically integrated specialists with certification moats and captive metallurgical capacity. Five-to-ten year viability hinges on mechanical-electronic hybridization capabilities. Target acquisition archetypes combine SAMR-compliant Chinese production with Southeast Asian distribution reach. The signal to watch is electronic access system specification share in premium commercial segments crossing inflection thresholds that compress mechanical-only hardware pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | UL 437 and EN 1303 approvals insulate pricing from commodity competition in institutional procurement. |
| Captive Foundry Integration | Backward control over zinc alloy supply neutralizes Shanghai smelter price volatility for integrated manufacturers. |
| Hybrid Lock Development | Mechanical-electronic convergence modules extend product lifecycle against RFID substitution in commercial segments. |
| Direct-to-Fleet Channel Buildout | Bypassing distributor markups through construction equipment rental platforms captures industrial padlock volume. |
| Southeast Asian Manufacturing Footprint | Proximity to Vietnam and India demand clusters reduces logistics cost and tariff exposure for export-oriented supply. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facilities managers at multi-site retail chains, certified locksmiths in North American and European manufacturing hubs, procurement leads at Indian tier-two commercial developers, and foundry operations directors in the Yangtze River Delta. Secondary validation drew from SAMR GB standard filings, UL certification registries, EN 12209 and EN 1303 testing documentation, and customs trade data for zinc alloy and finished lockset flows. Bottom-up unit demand estimates from residential and commercial construction pipelines were triangulated against top-down manufacturer revenue assessments.
Across the analysis window, volume and value outputs reflect segmented modeling across product type, security rating, installation configuration, and end-user category, with additional granularity for regional regulatory cluster effects. CAGRs were derived from fitted growth curves applied to construction completion forecasts and replacement cycle assumptions. Industry-specific forecast inputs include SAMR enforcement timelines for GB/T 8383 compliance and FDI flows into Vietnamese condominium development.
Forecasts assume regulatory continuity in SAMR GB standard enforcement, BIS certification mandates for Indian imports, and OSHA workplace safety guidelines; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated electronic access substitution in premium commercial segments and prolonged UL 437 testing queue extensions beyond current eight-to-fourteen-week baselines. Revision becomes warranted when electronic access specification share in Class A office assets crosses threshold levels that trigger mechanical lock demand displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
North America Access Control Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
North America Access Control Software Market