
 Restricted Access Barrier System (RABS) Market | 2026-2036
Restricted Access Barrier System (RABS) Market Size, Share, and Industry Trends Forecast 2026-2036
Restricted Access Barrier System (RABS) Market Analytics
Stainless steel framing is repositioning product economics as polymer-composite alternatives gain traction in mid-capacity installations. Syntegon Technologies GmbH leverages integrated isolator-to-RABS conversion platforms across European pharma corridors. SKAN AG anchors its position through deep specialization in active air management systems for high-potency compounds. Getinge AB extends its reach via captive supply of HEPA filtration modules that lock in aftermarket service contracts.
A Restricted Access Barrier System is an enclosed processing environment that combines rigid physical barriers with unidirectional airflow to maintain ISO 5 conditions during sterile operations; systems typically achieve 0.45 m/s average air velocity through HEPA-filtered supply plenums. Static RABS dominates current installations due to lower capital outlay and validated legacy protocols, though hybrid RABS is gaining fastest in multi-product facilities seeking operational flexibility between open and closed processing modes. Contract Manufacturing Organizations represent a concentrated demand pool as CDMOs retrofit existing cleanrooms to meet evolving EU GMP Annex 1 requirements without full isolator capital commitment.
EMA guidelines, FDA aseptic processing guidance, and ISO 14644 cleanroom standards collectively dictate barrier classification thresholds and environmental monitoring protocols that determine RABS specification tiers. The EU GMP Annex 1 revision explicitly distinguishes RABS from isolators, creating compliance clarity that shapes procurement decisions among sterile injectable manufacturers. Stakeholders must monitor how regulatory divergence between EMA and FDA barrier definitions influences validation burden and equipment interchangeability across transatlantic supply chains.
Market Dynamics
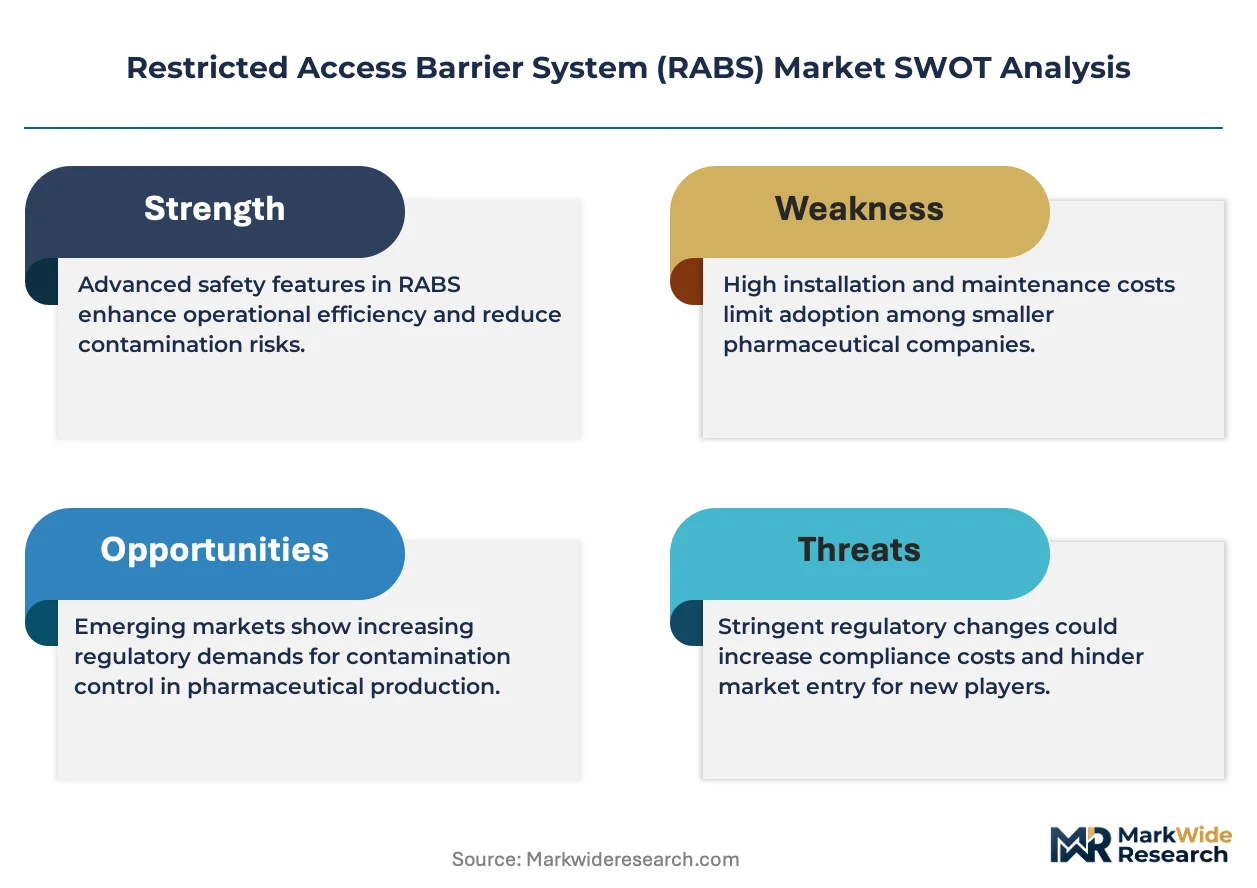
The EU GMP Annex 1 revision is compressing validation timelines and forcing sterile injectable manufacturers to choose between full isolator conversion or validated RABS upgrades before compliance deadlines.
Growth Catalysts
- EU GMP Annex 1 Contamination Mandates:The revised annex explicitly distinguishes RABS from isolators, creating procurement clarity that accelerates retrofit investments among sterile injectable producers seeking intermediate barrier solutions.
- CDMO Facility Modernization:Contract Manufacturing Organizations are retrofitting existing cleanrooms with hybrid RABS configurations to serve multi-product portfolios without isolator capital commitment.
- German Injectable Cluster Density:The concentration of sterile fill-finish operations around Frankfurt and Munich generates validated demand for active air management systems in high-potency compound processing.
Market Restraints
- HEPA Filtration Supply Concentration:Captive supply agreements for critical filtration modules lock buyers into single-source aftermarket service dependencies, limiting vendor switching.
- Polymer-Composite Material Cost Volatility:Mid-capacity installations face input cost pressure as polymer-composite framing alternatives compete with legacy stainless steel on total cost of ownership.
- Static RABS Protocol Inertia:Validated legacy protocols for static configurations create technical friction against hybrid mode adoption in facilities with established open-processing workflows.
Strategic Opportunities
- Isolator-to-RABS Conversion Platforms:Integrated retrofit systems enable pharmaceutical corridors to extend existing isolator infrastructure through modular barrier upgrades rather than full replacement.
- Multi-Product Facility Flexibility:Hybrid RABS configurations capture demand from facilities seeking operational toggling between open and closed processing modes without cleanroom reconstruction.
- EMA-FDA Regulatory Divergence Arbitrage:Equipment manufacturers can differentiate validation packages to address distinct barrier classification thresholds across transatlantic supply chains.
Industry Challenges
- Aseptic Processing Specialist Shortage:Facilities face compressed timelines for training personnel on unidirectional airflow validation and environmental monitoring protocol execution under ISO 14644 standards.
- Legacy Cleanroom Integration Complexity:Retrofit projects encounter structural constraints when embedding rigid physical barriers into existing HVAC architectures without disrupting adjacent production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restricted Access Barrier System (RABS) Market |
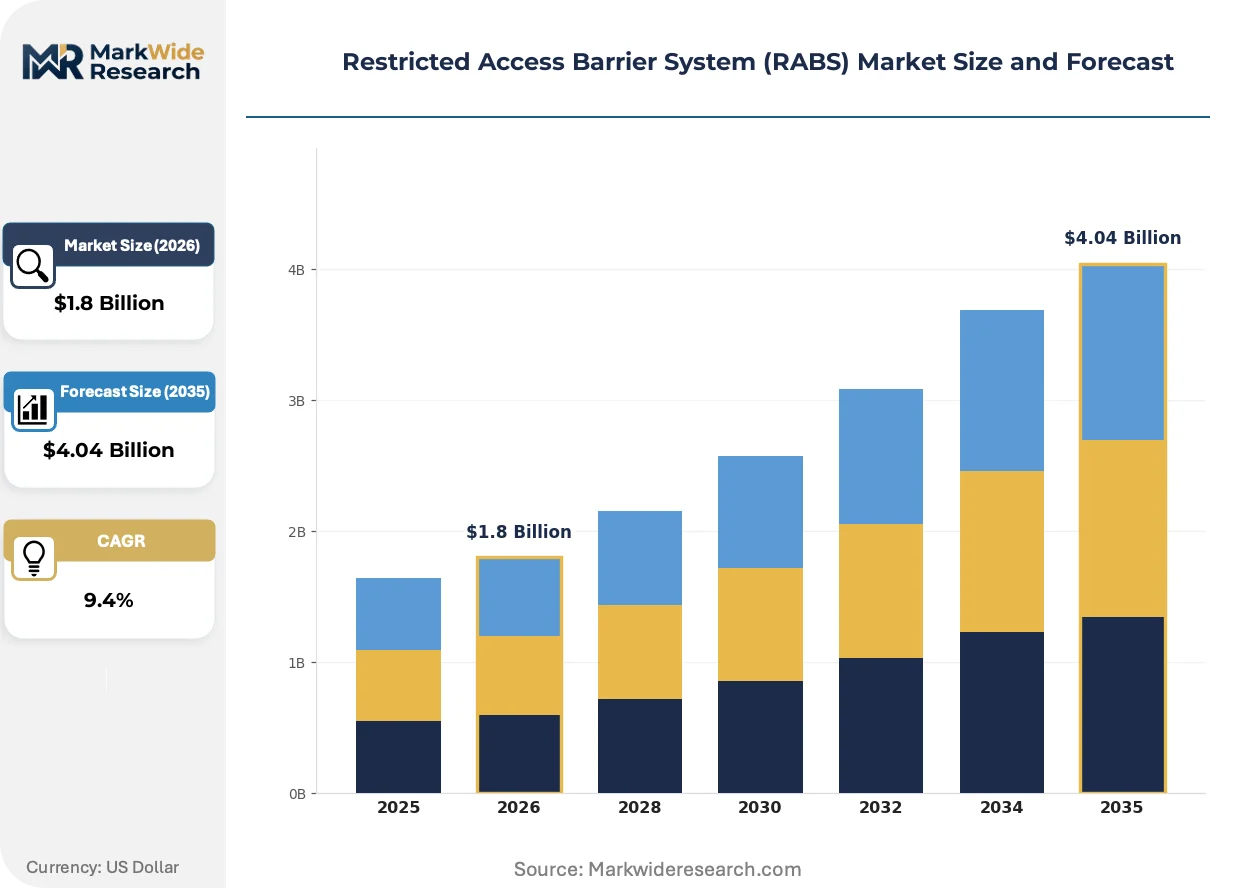
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static RABS, Dynamic RABS, Hybrid RABS, Others End User: Pharmaceutical Manufacturers, Biotechnology Companies, Contract Manufacturing Organizations, Research Laboratories Installation: On-site Installation, Off-site Installation, Modular Setup, Fixed Setup Technology: Isolation Technology, Containment Technology, Safety Systems, Monitoring Solutions |
| Companies Covered | Syntegon Technologies GmbH, SKAN AG, Extract Technology, IMA Life S.p.A., Esco Lifesciences Group, Getinge AB, Germfree Laboratories, Inc., Fedegari Autoclavi S.p.A., Telstar (azbil Group), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restricted Access Barrier System (RABS) Market Evolving Landscape
Active air management architectures are displacing passive configurations as the default specification for high-potency compound processing, while material science advances compress the performance gap between polymer and steel framing.
Polymer-composite framing is rewriting product economics in mid-capacity RABS installations. The material delivers comparable structural rigidity at reduced weight, enabling faster installation cycles in retrofit environments. CDMOs with multi-product portfolios are adopting this technology most aggressively, compressing the traditional stainless steel dominance in sub-10-line configurations.
EMA guidelines now explicitly codify barrier classification thresholds that diverge from FDA aseptic processing guidance on environmental monitoring frequency. This regulatory friction forces manufacturers to maintain dual validation protocols for transatlantic supply chains. Sterile injectable exporters to both markets face expanded documentation burdens that favor equipment vendors with pre-validated multi-jurisdiction packages.
Service contract unbundling is disrupting traditional captive supply arrangements in the aftermarket. Buyers are separating HEPA filtration module procurement from installation and validation services, creating procurement flexibility but introducing vendor coordination risk. This pattern concentrates in German pharmaceutical clusters where dense supplier networks enable multi-vendor sourcing strategies.
Restricted Access Barrier System (RABS) Market Segmentation
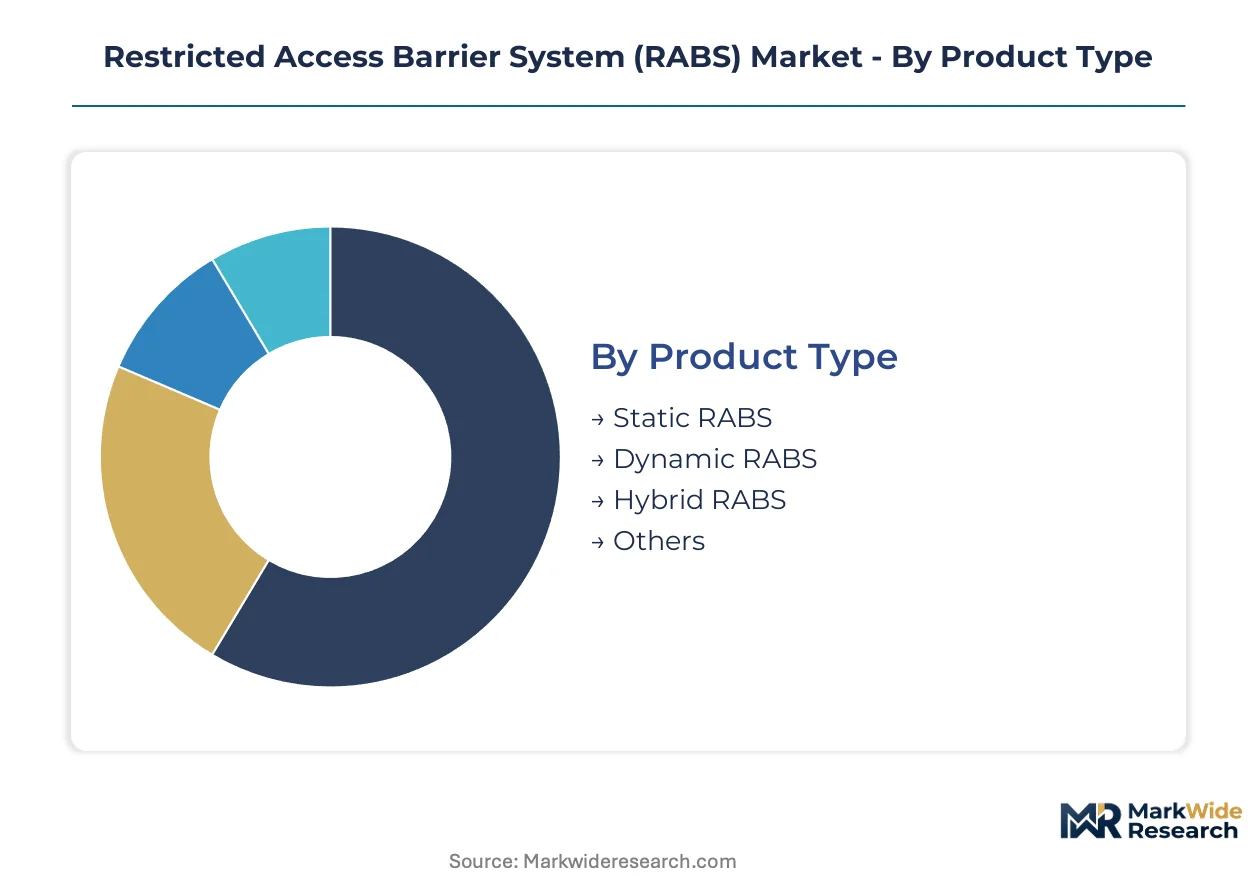
RABS procurement patterns diverge sharply between facilities seeking validated legacy continuity and those prioritizing operational flexibility. Segmentation reveals how contamination control requirements, facility age, and regulatory compliance timelines reshape equipment specifications across sterile manufacturing environments.
Product Type:
The customization-to-standardization spectrum spans rigid legacy protocols at one pole and adaptive hybrid architectures at the other, with material framing choices further differentiating capital deployment strategies.
- Static RABS:Fixed-barrier configurations with unidirectional airflow through HEPA-filtered plenums achieve ISO 5 conditions without active intervention. German sterile injectable producers around Frankfurt and Munich favor these systems for high-volume, single-product lines where validated legacy protocols minimize regulatory revalidation burden.
- Hybrid RABS:Modular architectures enable operational toggling between open and closed processing modes within shared cleanroom footprints. CDMOs serving multi-product portfolios adopt these configurations most aggressively to avoid full isolator capital commitment while meeting EU GMP Annex 1 contamination mandates.
- Dynamic RABS:Active intervention systems incorporate automated glove ports and rapid transfer ports for material exchange without breaking containment.
- Others:Emerging configurations include portable RABS for clinical trial manufacturing and disposable liner systems for high-potency cytotoxic compounds.
Leading the category by volume: Static RABS. Expanding most quickly: Hybrid RABS.
End User:
Customer type determines specification tier through facility age, internal technical capacity, and regulatory exposure intensity across transatlantic supply chains.
- Pharmaceutical Manufacturers:Large sterile injectable producers with established fill-finish operations drive demand for stainless steel-framed static systems in high-volume configurations. These buyers prioritize validated environmental monitoring protocols aligned with EMA barrier classification thresholds and FDA aseptic processing guidance simultaneously.
- Contract Manufacturing Organizations:CDMOs retrofit existing cleanrooms with polymer-composite hybrid configurations to serve fragmented client portfolios without isolator-level capital outlay. Their procurement concentrates on rapid installation cycles and vendor flexibility for aftermarket HEPA filtration service unbundling.
- Biotechnology Companies:Emerging biologics developers favor modular setups supporting scale-up from clinical to commercial phases.
- Research Laboratories:Academic and government facilities prioritize compact footprints and simplified validation for non-GMP applications.
Highest specification intensity: Pharmaceutical Manufacturers. Fastest procurement velocity: Contract Manufacturing Organizations.
Installation:
Deployment mode reflects the tension between minimizing production disruption and accelerating compliance timelines against EU GMP Annex 1 deadlines.
- On-site Installation:Traditional build-in-place approaches dominate greenfield sterile manufacturing facilities where HVAC integration occurs during initial construction. These projects enable precise airflow validation but extend commissioning timelines.
- Modular Setup:Pre-fabricated barrier assemblies compress installation cycles for retrofit environments where adjacent production lines cannot halt operations. CDMOs with dense multi-product schedules adopt this approach to thread RABS deployment between batch campaigns.
- Off-site Installation:Remote assembly and testing before facility delivery reduces on-site contamination risk during commissioning.
- Fixed Setup:Permanent architectural integration suits dedicated high-volume lines with minimal product changeover requirements.
Widest deployment: On-site Installation. Gaining share fastest: Modular Setup.
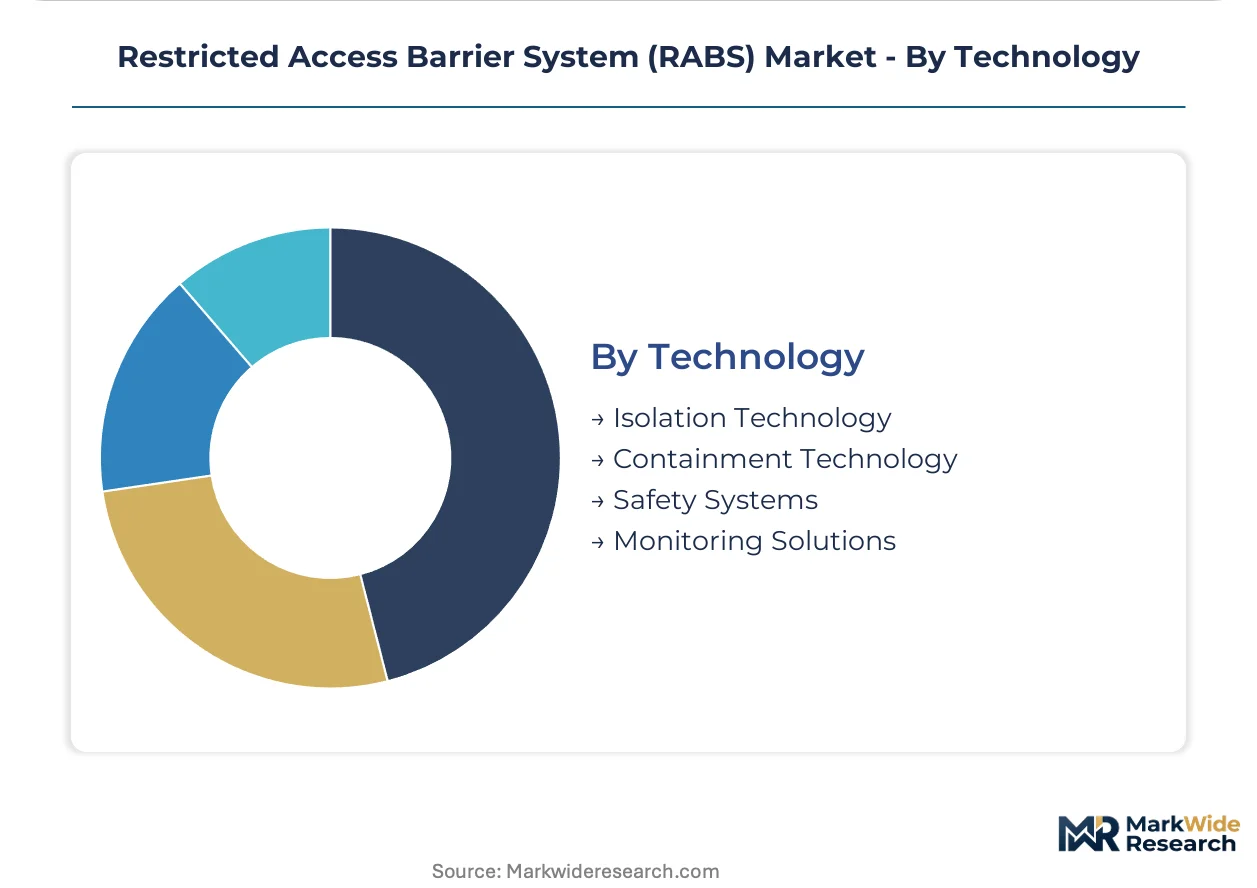
Technology:
Technology stack selection follows compound hazard classification, with high-potency APIs demanding active containment architectures beyond passive barrier functions.
- Containment Technology:Negative-pressure glove boxes and rapid transfer ports protect operators from cytotoxic and potent compounds during sterile processing. Facilities handling oncology biologics and antibody-drug conjugates specify these systems to meet EMA guidelines on occupational exposure limits.
- Isolation Technology:Fully sealed environments with vaporized hydrogen peroxide decontamination achieve higher sterility assurance levels than RABS, though procurement often stops at RABS-equivalent barriers for cost containment.
- Safety Systems:Emergency ventilation override and breach detection protocols safeguard personnel during barrier integrity failures.
- Monitoring Solutions:Continuous particle counting and viable environmental sampling integrate with facility SCADA architectures for real-time compliance documentation.
Deepest specialization: Containment Technology. Steepest specification climb: Monitoring Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterile injectable production clusters concentrate RABS procurement in pharmaceutical corridors with dense fill-finish operations. Regulatory deadlines compress investment timelines across jurisdictions with aseptic processing mandates.
Germany
The Frankfurt and Munich pharmaceutical corridors generate sustained demand for active air management systems in high-potency compound processing. EMA guidelines on barrier classification thresholds shape procurement specifications for sterile injectable manufacturers. Bavaria's concentration of CDMO facilities drives retrofit investments in polymer-composite hybrid configurations.
United States
FDA aseptic processing guidance dictates environmental monitoring protocols that determine RABS specification tiers for domestic sterile manufacturers. The agency's contamination control expectations accelerate validated system upgrades across legacy fill-finish facilities. Massachusetts and North Carolina biopharma clusters anchor demand for modular barrier solutions in multi-product environments.
Switzerland
Swissmedic requirements for high-potency compound containment drive specifications for negative-pressure glove box configurations. The country's dense oncology biologics pipeline concentrates demand in the Basel pharmaceutical corridor. Cantonal manufacturing zones prioritize rapid transfer port integration for antibody-drug conjugate processing.
Italy
IMA Life S.p.A. and Fedegari Autoclavi S.p.A. anchor domestic supply capacity for containment technology exports across European markets. The national pharmaceutical regulator enforces occupational exposure limits that shape active air management procurement. Lombardy's sterile manufacturing base generates retrofit demand for EU GMP Annex 1 compliance upgrades.
United Kingdom
MHRA alignment with EMA barrier classification thresholds creates procurement continuity for transatlantic sterile injectable exporters. The Southeast England pharmaceutical cluster concentrates CDMO facility modernization investments. Cambridge and Oxford biotech corridors drive modular RABS adoption for clinical-to-commercial scale transitions.
Restricted Access Barrier System (RABS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers commanding premium positioning in high-potency applications while modular fabricators capture CDMO retrofit cycles. The vendor base organizes around three strategic archetypes: European engineering houses with isolator heritage, Asian scale manufacturers, and North American containment specialists. Consolidation pressure concentrates among mid-tier fabricators lacking captive filtration supply. Dominant competitive moves include backward integration into HEPA module production and technology licensing partnerships for rapid transfer port architectures.
Among German engineering houses, Syntegon Technologies GmbH and SKAN AG occupy positions at opposite ends of the specialization spectrum, with the former representing integrated platform providers and the latter exemplifying deep vertical focus in active air management. Getinge AB anchors the Nordic contingent through filtration-adjacent positioning that locks in aftermarket service relationships. These three entities collectively illustrate how geographic clustering around pharmaceutical manufacturing corridors shapes competitive differentiation.
| Leading Market Players |
|---|
| Syntegon Technologies GmbH |
| SKAN AG |
| Extract Technology |
| IMA Life S.p.A. |
| Esco Lifesciences Group |
| Getinge AB |
| Germfree Laboratories, Inc. |
| Fedegari Autoclavi S.p.A. |
| Telstar (azbil Group) |
| Others |
Value Network & Pricing Analysis
HEPA filtration module costs cascade through three distinct pricing tiers as stainless steel framing competes with polymer-composite alternatives for mid-capacity installations. German pharmaceutical manufacturers absorb premium positioning for active air management systems, while CDMOs in Bavaria drive procurement flexibility through unbundled aftermarket service contracts.
Pricing Analysis
Volume concentration in static RABS configurations compresses margins at the economy tier, while hybrid systems command premium positioning through operational flexibility certification. Price differentiation hinges on ISO 14644 compliance grade and EMA-FDA dual validation documentation burden. Pricing pressure stems from polymer-composite material cost volatility disrupting total cost of ownership calculations for mid-capacity buyers. CDMOs exhibit highest price sensitivity due to fragmented client portfolios, whereas large sterile injectable producers prioritize validated legacy continuity over unit economics.
Supply Chain Analysis
Freight costs for rigid stainless steel framing assemblies from Germany and Italy amplify landed costs for North American retrofit installations. Critical inputs draw from Swiss precision engineering for rapid transfer port mechanisms, Swedish HEPA filtration modules, and Italian containment technology fabrication. Single-source vulnerability concentrates in captive supply agreements for filtration modules that lock buyers into aftermarket dependencies. Distribution runs through pharmaceutical corridor clustering around Frankfurt, Munich, and Basel with direct manufacturer-to-facility project management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU GMP Annex 1 revision constructs a compliance moat that elevates capital requirements for barrier system validation, entrenching incumbents with established regulatory dossiers while filtering speculative entrants.
For Market Incumbents: Deepen backward integration into HEPA module production to capture aftermarket service revenue streams and defend against unbundling pressures from German CDMO procurement strategies. Anchor capacity expansion in Bavaria's dense sterile manufacturing corridor to exploit proximity advantages for rapid installation cycles. Fortify EMA-FDA dual validation documentation capabilities as regulatory divergence intensifies transatlantic specification complexity. For New Entrants and Emerging Players: The premium-to-economy price gap in hybrid RABS configurations creates white-space opportunity for polymer-composite specialists targeting mid-capacity CDMO retrofit cycles. Penetrate Italian and UK CDMO markets where facility modernization timelines compress vendor qualification periods. Pursue rapid transfer port technology licensing partnerships to bypass isolator heritage deficits among European engineering incumbents. For Investors and Strategic Acquirers: CDMO facility modernization announcement velocity is the leading indicator that retrofit demand cycles are accelerating beyond greenfield capacity. Position acquisition screening toward mid-tier fabricators with polymer-composite installation expertise but lacking captive filtration supply. Monitor EMA-FDA regulatory divergence resolution as the signal for validation package standardization opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HEPA Filtration | Captive module production locks in aftermarket service contracts against unbundling pressures from CDMO procurement strategies. |
| EMA-FDA Dual Validation Package Development | Pre-validated documentation reduces regulatory friction for sterile injectable exporters across transatlantic supply chains. |
| Polymer-Composite Framing Scale-Up | Lightweight alternatives compress installation cycles in retrofit environments where adjacent production lines cannot halt operations. |
| Modular Barrier System Platform Launch | Pre-fabricated assemblies enable CDMOs to thread deployments between batch campaigns without cleanroom reconstruction. |
| Active Air Management Technology Licensing | Rapid transfer port partnerships bypass isolator heritage deficits and accelerate market entry for emerging containment specialists. |
Research Methodology
Independent corroboration across aseptic processing engineers, regulatory affairs specialists at sterile injectable manufacturers, CDMO facility directors, and HEPA filtration procurement managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FDA aseptic processing guidance documents, EMA GMP Annex 1 revision texts, ISO 14644 cleanroom classification standards, and SEC filings from publicly traded barrier system manufacturers. Bottom-up equipment shipment analysis triangulates against top-down pharmaceutical capital expenditure tracking across the European sterile manufacturing corridor.
Rate-of-change decomposition across product type, end user archetype, installation mode, and technology stack generates segment-level trajectories over the projection horizon. CAGRs derive from installed base evolution modeling, replacement cycle analysis, and regulatory deadline impact assessment. Forecast inputs incorporate EU GMP Annex 1 compliance timeline phasing, polymer-composite material substitution elasticities, and CDMO facility modernization pipeline visibility from Bavaria and Southeast England clusters.
Inputs from aseptic processing specialists and regulatory documentation were available through the study window; gaps in real-time CDMO capital commitment disclosure introduce uncertainty bands around retrofit demand timing. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and material cost stabilization. Stakeholders should weight assumptions against their own operating context and facility-specific compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
US Access Control Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market