
 France Access Control Market | 2026-2036
France Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
France Access Control Market Insights
French security component manufacturers is recalibrating production priorities toward cloud-native credential platforms. Thales Group leverages its defense electronics heritage to anchor high-assurance government contracts. Schneider Electric SE sustains building-automation integration advantages across commercial real estate portfolios. ASSA ABLOY competes through door-hardware-to-software convergence across European distribution channels.
Access control encompasses electromechanical and digital systems that authenticate identity through credentials, biometrics, or cryptographic tokens before granting entry to secured zones, typically operating with response times under one second and audit-log retention exceeding one year. Biometric systems lead product-type value pools due to fingerprint and facial recognition accuracy improvements, while cloud-based technology architectures displace standalone installations as enterprises prioritize centralized credential management and real-time anomaly detection. IP-based connectivity dominates retrofit scenarios where existing Ethernet infrastructure reduces cabling costs.
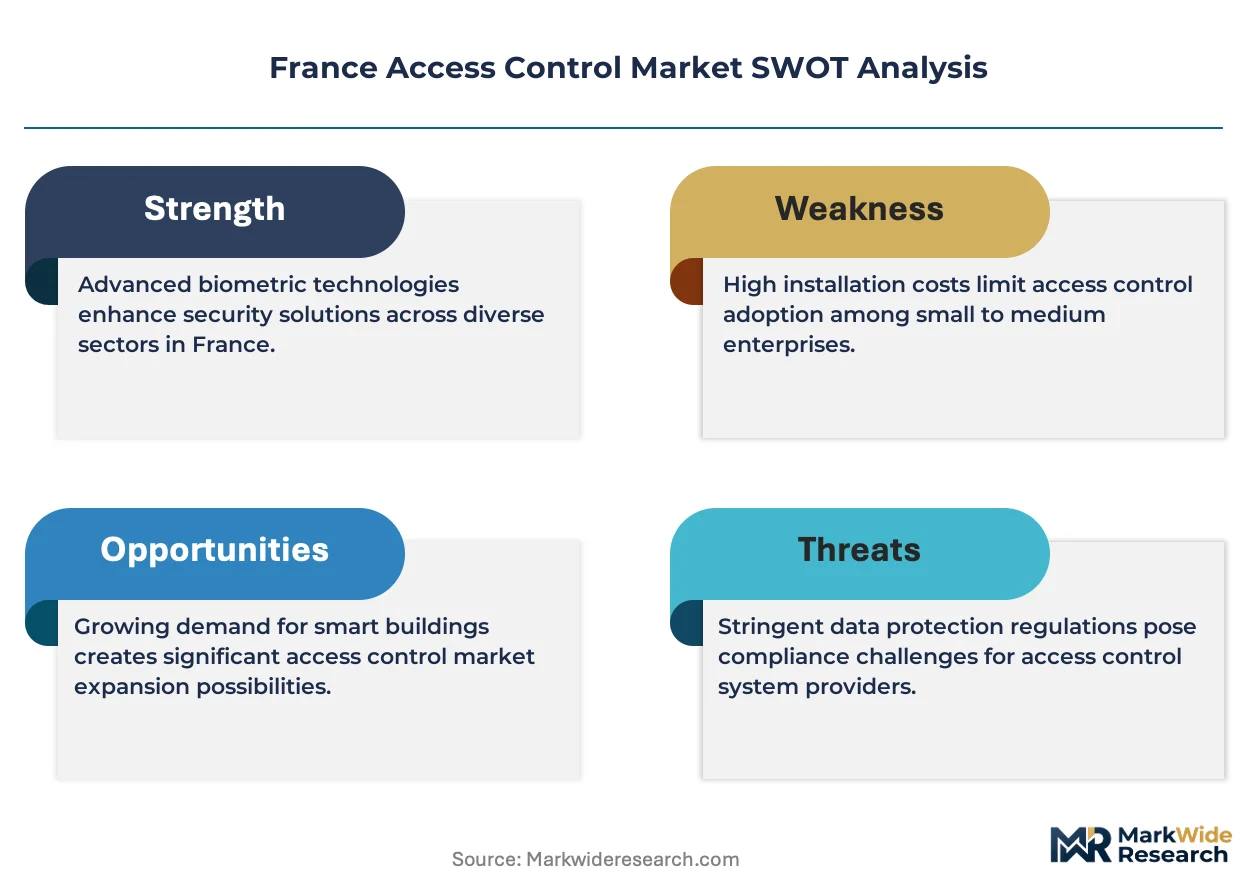
ANSM and CNIL jointly govern biometric data processing and health-facility security standards in France, with GDPR compliance costs pushing smaller installers toward certified platform partners. The EU AI Act imposes risk-classification obligations on facial recognition deployments, reshaping vendor liability and procurement specifications across public-sector tenders. Stakeholders must monitor harmonized European cybersecurity certification schemes as these frameworks will determine which cloud-based access platforms qualify for critical infrastructure contracts.
Market Dynamics
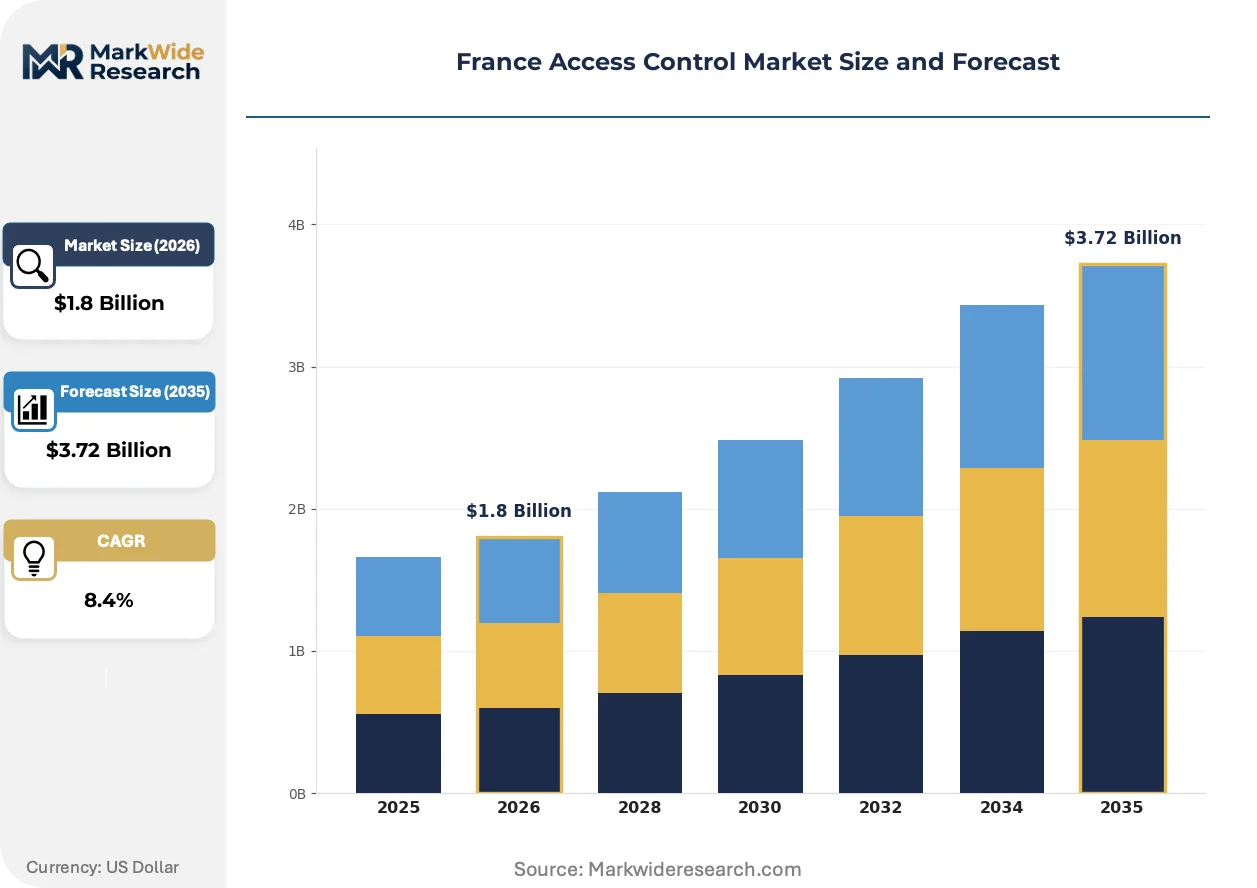
The France Access Control Market is experiencing structural compression as biometric authentication systems and cloud-native credential platforms converge to displace legacy standalone installations across commercial and government facilities.
Growth Catalysts
- EU AI Act compliance mandates:Public-sector tenders now require algorithmic transparency documentation for facial recognition deployments, accelerating procurement of certified biometric platforms in transportation hubs and administrative buildings.
- Paris metropolitan infrastructure expansion:Commercial real estate development in La Défense and peripheral business districts is driving electromechanical-to-digital upgrade cycles in Class A office portfolios.
- GDPR-aligned data governance:Health facilities governed by ANSM and CNIL joint protocols are consolidating fragmented credential systems into centralized audit-log platforms with one-year retention minimums.
Market Restraints
- Semiconductor component volatility:Supply concentration in East Asian foundries creates lead-time uncertainty for IP-connected controllers and biometric sensors.
- GDPR compliance cost escalation:Smaller installation firms face capital constraints when upgrading to certified platform partnerships required for biometric data processing.
- Legacy electromechanical persistence:Existing mechanical lock infrastructure in heritage buildings and public monuments resists retrofit due to preservation requirements.
Strategic Opportunities
- Île-de-France peripheral zones:Secondary commercial clusters in Seine-et-Marne and Essonne exhibit underpenetrated cloud-based access deployment relative to Paris core saturation.
- Building-automation convergence:Integration of access credentials with HVAC and lighting control systems creates cross-selling pathways through facility management service contracts.
- EU cybersecurity certification schemes:Harmonized ENISA frameworks for critical infrastructure will qualify select cloud platforms for national security tenders previously reserved for on-premise systems.
Industry Challenges
- Biometric systems integration expertise:Shortage of technicians certified in facial recognition calibration and liveness detection algorithms constrains deployment velocity.
- Multi-stakeholder compliance timelines:Projects requiring simultaneous ANSM health-facility approval and CNIL data protection authorization face procedural coordination delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Access Control Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Electronic Locks, Smart Cards, Keypads End User: Government, Transportation, Retail, Education Technology: Cloud-Based, IP-Based, Wireless, Standalone Installation Type: New Installation, Retrofit, Integrated Systems, Custom Solutions |
| Companies Covered | Bosch Security Systems, Johnson Controls International PLC, Thales Group, ASSA ABLOY, Allegion PLC, Schneider Electric SE, Honeywell International Inc., Nedap, Suprema Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Access Control Market Trends and Innovations
Cloud-native credential management is compressing the competitive landscape as building operators prioritize centralized oversight over distributed standalone systems. Three developments are accelerating this transition.
Mobile credential platforms leveraging smartphone-based cryptographic tokens are unifying physical and logical access into single identity profiles. Large commercial landlords in Lyon and Marseille are piloting Bluetooth Low Energy readers that eliminate card inventory costs. This convergence is unifying procurement decisions under chief information security officers rather than facilities managers.
The EU AI Act's risk-classification framework for biometric identification systems is restructuring vendor liability across French public procurement. High-risk system designations now mandate conformity assessments before deployment in transportation and government buildings. Municipal authorities in Bordeaux and Toulouse are revising tender specifications to incorporate these documentation requirements.
Subscription-based access-as-a-service models are displacing capital-intensive hardware purchases among mid-sized commercial tenants. Property management firms are bundling credential lifecycle management into monthly facility fees. This shift is most pronounced in the hospitality and flexible workspace sectors concentrated in Paris intramural districts.
France Access Control Market Segmentation
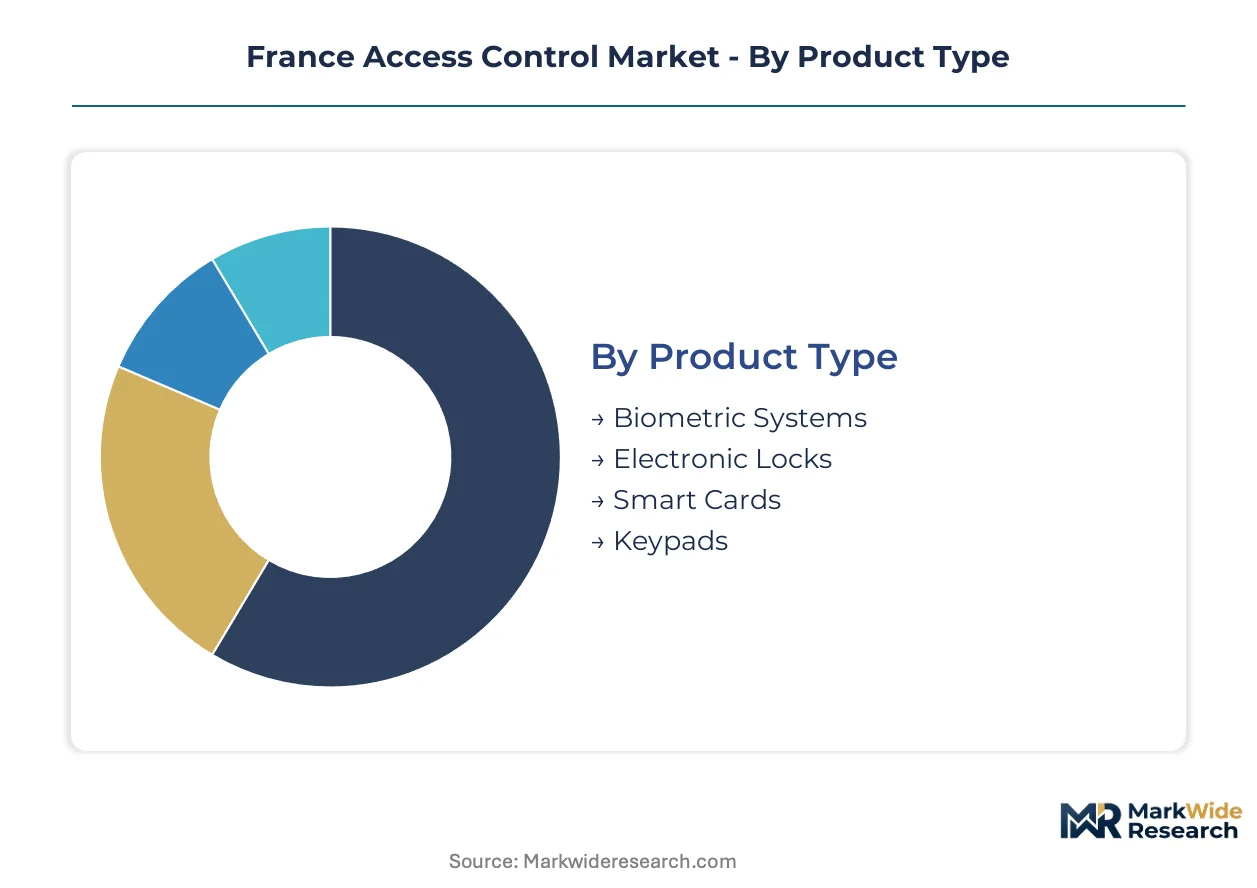
Segmentation in the France Access Control Market reveals how regulatory requirements, infrastructure maturity, and end-use security protocols create divergent procurement patterns across credential technologies and deployment architectures. Understanding these divisions exposes where GDPR compliance costs and EU AI Act certification burdens concentrate.
Product Type:
ANSM and CNIL joint protocols impose distinct certification burdens across product categories, with biometric systems facing the most stringent algorithmic transparency documentation under EU AI Act risk-classification frameworks.
- Biometric Systems:Fingerprint and facial recognition platforms authenticate identity through physiological pattern matching with sub-second response times. Demand concentrates in Paris metropolitan transportation hubs where EU AI Act high-risk system designations mandate conformity assessments before deployment.
- Electronic Locks:Electromechanical actuators integrate with building automation systems to enable remote credential verification and audit logging. La Défense Class A office portfolios drive replacement cycles as landlords consolidate fragmented mechanical infrastructure into centralized digital platforms.
- Smart Cards:Contact and contactless credential tokens store encrypted identity certificates for physical and logical access convergence.
- Keypads:PIN-entry devices persist in cost-sensitive retrofit scenarios where existing cabling infrastructure cannot support IP connectivity upgrades.
Leading the category by volume: Electronic Locks. Growing fastest: Biometric Systems.
End User:
GDPR-aligned data governance creates tiered compliance cost structures across customer types, with health-adjacent government facilities facing the most complex multi-stakeholder approval timelines.
- Government:Administrative buildings and national security facilities require high-assurance authentication with cryptographic token validation. ANSM and CNIL joint protocols govern biometric data processing in health-adjacent government sites, consolidating fragmented credential systems into centralized audit-log platforms with one-year retention minimums.
- Transportation:Airports, rail terminals, and metro systems deploy multi-factor authentication for passenger and staff zone separation. Paris metropolitan infrastructure expansion accelerates biometric entry deployments in Charles de Gaulle and Orly hubs where algorithmic transparency documentation is now mandatory for public tenders.
- Retail:Loss prevention and staff access management drive demand for cloud-native credential platforms with real-time anomaly detection.
- Education:Campus security and dormitory access systems prioritize cost-efficient retrofit compatibility with existing Ethernet infrastructure.
Transportation commands the highest per-site spend. Education exhibits the steepest expansion trajectory as university digitization accelerates.
Technology:
Cloud migration intensity varies by connectivity architecture, with IP-based deployments leveraging existing Ethernet infrastructure while wireless systems face cybersecurity certification scrutiny under emerging ENISA frameworks.
- Cloud-Based:Centralized credential management platforms enable real-time anomaly detection and distributed audit logging across multi-site portfolios. Subscription-based access-as-a-service models displace capital-intensive hardware purchases among mid-sized commercial tenants in Paris intramural hospitality and flexible workspace sectors.
- IP-Based:Ethernet-connected controllers reduce cabling costs in retrofit scenarios where existing network infrastructure supports Power-over-Ethernet deployment. Lyon and Marseille commercial landlords pilot Bluetooth Low Energy reader integration that eliminates card inventory costs through smartphone-based cryptographic tokens.
- Wireless:Radio-frequency and cellular connectivity enables rapid deployment in heritage buildings where preservation requirements resist structured cabling installation.
- Standalone:Distributed systems without network connectivity persist in small-format retail and remote facilities with limited IT support capacity.
IP-Based architectures dominate current deployment volume. Cloud-Based platforms are climbing the fastest as building operators prioritize centralized oversight.
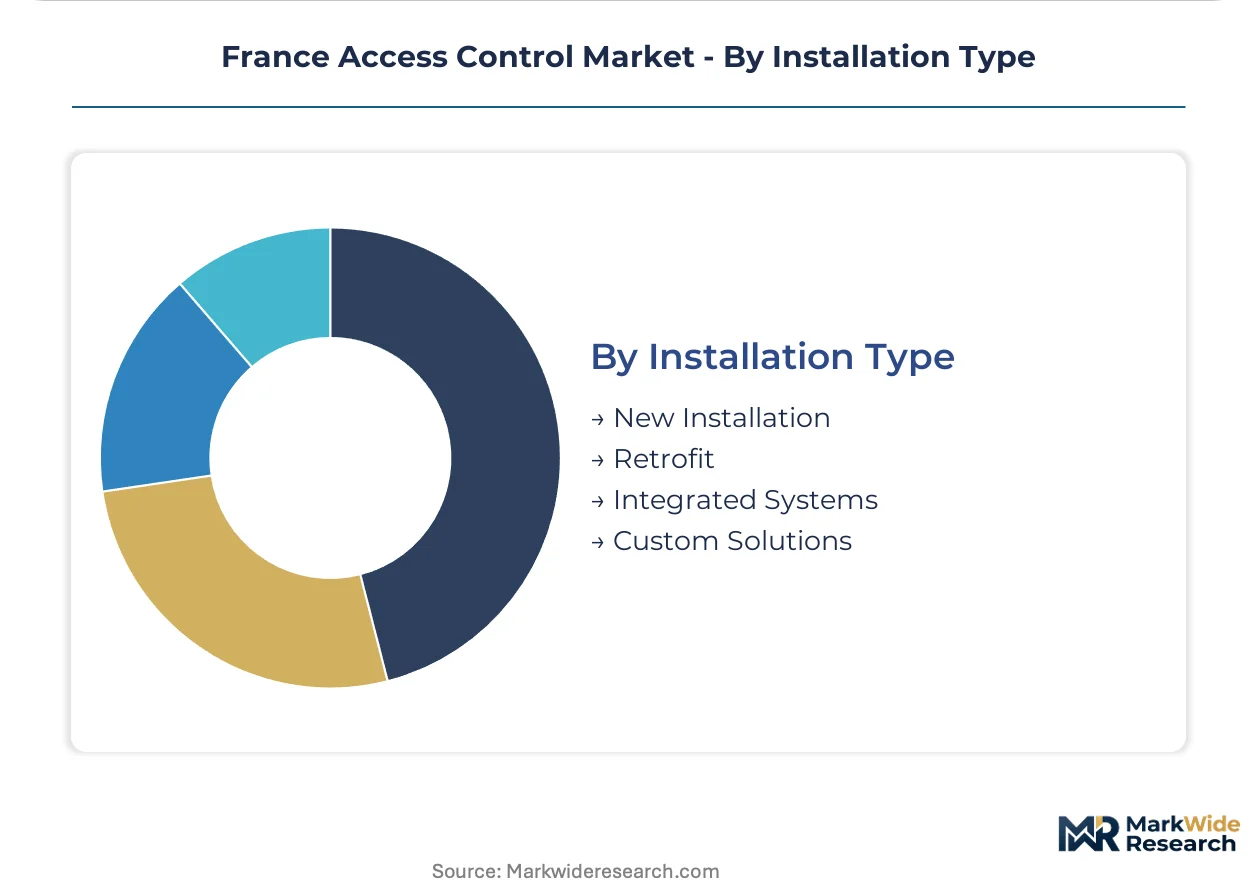
Installation Type:
Project complexity and margin profiles diverge sharply between greenfield new installations and retrofit scenarios constrained by legacy electromechanical persistence in heritage structures.
- New Installation:Greenfield deployments in La Défense and peripheral business districts enable native cloud architecture without legacy system integration burden. Île-de-France secondary commercial clusters in Seine-et-Marne and Essonne exhibit underpenetrated cloud-based access deployment relative to Paris core saturation.
- Retrofit:Electromechanical-to-digital upgrade cycles in existing buildings face preservation requirements that resist hardware modification in public monuments and heritage structures. Semiconductor component volatility in East Asian foundries creates lead-time uncertainty for IP-connected controllers and biometric sensors.
- Integrated Systems:Convergence of access credentials with HVAC and lighting control systems creates cross-selling pathways through facility management service contracts.
- Custom Solutions:Bespoke engineering addresses unique security protocols in defense and critical infrastructure facilities with non-standard authentication requirements.
Retrofit projects generate the largest absolute project pipeline. Integrated Systems are gaining share fastest as building-automation convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication concentrates in East Asian foundries, creating supply-chain dependencies for biometric sensor modules and IP-connected controllers serving French security infrastructure.
Île-de-France
Paris metropolitan commercial real estate drives electromechanical-to-digital upgrade cycles across La Défense Class A office portfolios. ANSM and CNIL joint protocols govern health-facility biometric deployments with one-year audit-log retention mandates. Charles de Gaulle and Orly airports anchor transportation hub demand for EU AI Act-compliant facial recognition systems.
Auvergne-Rhône-Alpes
Lyon's banking and pharmaceutical headquarters generate enterprise demand for cloud-native credential platforms with real-time anomaly detection. GDPR-aligned data governance pushes mid-sized commercial tenants toward subscription-based access-as-a-service models. Bluetooth Low Energy reader pilots in Lyon commercial districts eliminate card inventory through smartphone cryptographic tokens.
Provence-Alpes-Côte d'Azur
Marseille port facilities and tourism infrastructure deploy multi-factor authentication for staff zone separation and passenger flow management. EU AI Act risk-classification requirements reshape municipal tender specifications for biometric identification in transportation terminals. Aix-en-Provence technology clusters support integration expertise for facial recognition calibration.
Hauts-de-France
Lille metropolitan logistics hubs and cross-border commerce with Belgium drive warehouse access control modernization. Semiconductor component volatility from East Asian suppliers creates lead-time uncertainty for IP-connected controllers in this industrial corridor. Regional installation firms face capital constraints when upgrading to certified platform partnerships for biometric data processing.
Nouvelle-Aquitaine
Bordeaux municipal authorities revise tender specifications to incorporate EU AI Act algorithmic transparency documentation for public-sector facial recognition deployments. Wine industry tourism facilities and university campuses prioritize cost-efficient retrofit compatibility with existing Ethernet infrastructure. Secondary commercial clusters exhibit underpenetrated cloud-based access deployment relative to Paris core saturation.
France Access Control Market Competitive Landscape
Global majors compete with regional champions across defense-electronics heritage and building-automation integration dimensions. The vendor base stratifies into three tiers: diversified industrial conglomerates with security divisions, specialized access control pure-plays, and door-hardware manufacturers executing software convergence. Two dominant competitive moves are reshaping positioning: M&A activity consolidating cloud-native credential platforms and strategic partnerships linking biometric sensor suppliers with systems integrators.
Within the diversified industrial tier, Thales Group and Schneider Electric SE exemplify contrasting heritage-based positioning. Thales leverages defense-electronics lineage to anchor high-assurance government contracts requiring cryptographic token validation. Schneider Electric sustains building-automation integration advantages across commercial real estate portfolios through facility management service convergence. ASSA ABLOY occupies a distinct archetype as door-hardware-to-software convergence specialist competing across European distribution channels.
| Leading Market Players |
|---|
| Bosch Security Systems |
| Johnson Controls International PLC |
| Thales Group |
| ASSA ABLOY |
| Allegion PLC |
| Schneider Electric SE |
| Honeywell International Inc. |
| Nedap |
| Suprema Inc. |
| Others |
Pricing and Supply Chain Analysis
Semiconductor component costs for biometric sensors and IP-connected controllers flow from East Asian foundry concentration through tiered hardware pricing, with EU AI Act certification premiums layering atop base manufacturing costs for facial recognition deployments in French transportation hubs.
Pricing Analysis
Warranty and software maintenance bundling separates premium biometric platforms from unbundled hardware-only sales, with Thales Group and Schneider Electric SE anchoring high-assurance tiers through cryptographic token validation and building-automation integration. Three-tier pricing structure across premium, standard, and economy levels reflects GDPR compliance certification depth, algorithmic transparency documentation grade, and after-sales service intensity. Pricing pressure stems from subscription-based access-as-a-service models displacing capital-intensive purchases among mid-sized Paris commercial tenants. Education sector buyers exhibit highest price sensitivity due to fragmented procurement budgets, while government national security facilities demonstrate lowest sensitivity given mission-critical authentication requirements.
Supply Chain Analysis
Biometric sensor module supply rests on Taiwanese and South Korean semiconductor fabrication, with Chinese component assembly and Japanese specialty chemical inputs for fingerprint recognition coatings. Raw material dependencies include silicon wafers, CMOS image sensors, and BLE communication chipsets. Single-source vulnerability concentrates in advanced facial recognition algorithm processors from limited foundry capacity. Distribution runs through ASSA ABLOY and Allegion PLC European channel networks, with systems integrators handling final calibration and EU AI Act conformity assessment documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Access Control Market operates as a vertical-integration race where cloud-native credential platforms and biometric sensor supply chains represent the decisive upstream and downstream levers determining competitive durability.
For Market Incumbents: Deepen backward integration into biometric algorithm development to reduce dependency on East Asian sensor suppliers facing lead-time volatility. Consolidate fragmented installation partner networks in Île-de-France peripheral zones before GDPR compliance cost escalation eliminates smaller certified platform partners. Thales Group's defense-electronics heritage and Schneider Electric SE's building-automation integration provide defensive moats against pure-play SaaS entrants. For New Entrants and Emerging Players: Begin with Bluetooth Low Energy reader pilots in Lyon and Marseille commercial districts, where smartphone-based cryptographic tokens eliminate incumbent card inventory advantages. Target hospitality and flexible workspace sectors in Paris intramural districts where subscription-based access-as-a-service models face lowest switching costs from legacy standalone systems. Partner with regional facility management firms to embed credential lifecycle management into monthly service contracts. For Investors and Strategic Acquirers: EU cybersecurity certification scheme announcements from ENISA are the leading indicator that cloud platform qualification for critical infrastructure tenders will reshape vendor eligibility pools. Long-term viability favors platforms combining biometric hardware with native cloud architecture over standalone hardware manufacturers. Acquisition focus should center on mid-sized French installers holding ANSM health-facility and CNIL data protection dual certifications, with biometric systems integration expertise as the scarcest capability warranting premium multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Centralized credential management displaces standalone installations across La Défense Class A portfolios. |
| EU AI Act Conformity Assessment | Algorithmic transparency documentation becomes mandatory for facial recognition in Charles de Gaulle and Orly hubs. |
| Biometric Sensor Supply Agreement | Long-term contracts with Taiwanese foundries mitigate lead-time uncertainty for fingerprint and facial recognition modules. |
| Building-Automation Integration | HVAC and lighting convergence through Schneider Electric SE creates facility management cross-selling pathways. |
| Peripheral Zone Channel Expansion | Seine-et-Marne and Essonne commercial clusters exhibit underpenetrated cloud deployment relative to Paris saturation. |
Research Methodology
Document review covered EU AI Act implementation guidance, ANSM health-facility security protocols, CNIL biometric data processing guidelines, and ENISA cybersecurity certification frameworks, complemented by interviews with access control systems integrators, commercial real estate facility managers, government procurement officers, and biometric platform engineering leads. Secondary validation drew from Thales Group and Schneider Electric SE regulatory disclosures, French public tender databases for transportation infrastructure, and customs records for security component imports. Bottom-up project pipeline analysis across Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur regions triangulated against top-down market sizing from credential deployment volume estimates.
Historical biometric adoption curves in Paris metropolitan transportation hubs cross-referenced against panel input from cloud platform vendors and electromechanical lock manufacturers informed the projection framework. Segmentation modeling spanned product type, end user, technology architecture, and installation type dimensions, with biometric systems integration complexity and GDPR compliance certification tier as industry-specific variables. CAGRs derived from regression analysis of credential management platform subscription growth and hardware replacement cycle compression throughout the forecast period.
Underlying measurement precision varies by segment; cloud-based and IP-based technology deployments carry tighter precision than wireless and standalone systems due to vendor disclosure concentration. Forecasts reflect assumptions regarding EU AI Act enforcement timing, semiconductor supply normalization, and ANSM-CNIL joint protocol harmonization. Regulatory implementation delays, East Asian foundry capacity constraints, and cybersecurity certification scheme revisions constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
China Access Control Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
Access Control Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Italy Access Control Market