
 Europe Proximity Access Control Market | 2026-2036
Europe Proximity Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Proximity Access Control Market Insights
Subscription-based software licensing is rebalancing vendor revenue models away from one-time hardware sales across Europe. ASSA ABLOY (HID Global) leverages its integrated mobile credential platform to sustain recurring income streams. Bosch Security Systems GmbH anchors its competitive stance through deep manufacturing scale in RFID reader production. SALTO Systems differentiates via cloud-native access architecture that reduces on-premise infrastructure burdens for mid-market clients.
Europe proximity access control encompasses electronic systems that authenticate individuals through radio-frequency identification, biometric templates, or encrypted smart credentials to grant or deny physical entry. These systems operate on carrier frequencies between 125 kHz and 13.56 MHz, with read ranges from contact to approximately 10 centimeters depending on antenna configuration and environmental shielding. RFID technology occupies the largest installed base across commercial buildings and transportation hubs, though biometric modalities are gaining traction in government and healthcare settings where identity assurance requirements exceed card-based security. Cloud-based installation approaches are expanding fastest among educational institutions seeking centralized multi-campus administration without dedicated IT staffing.
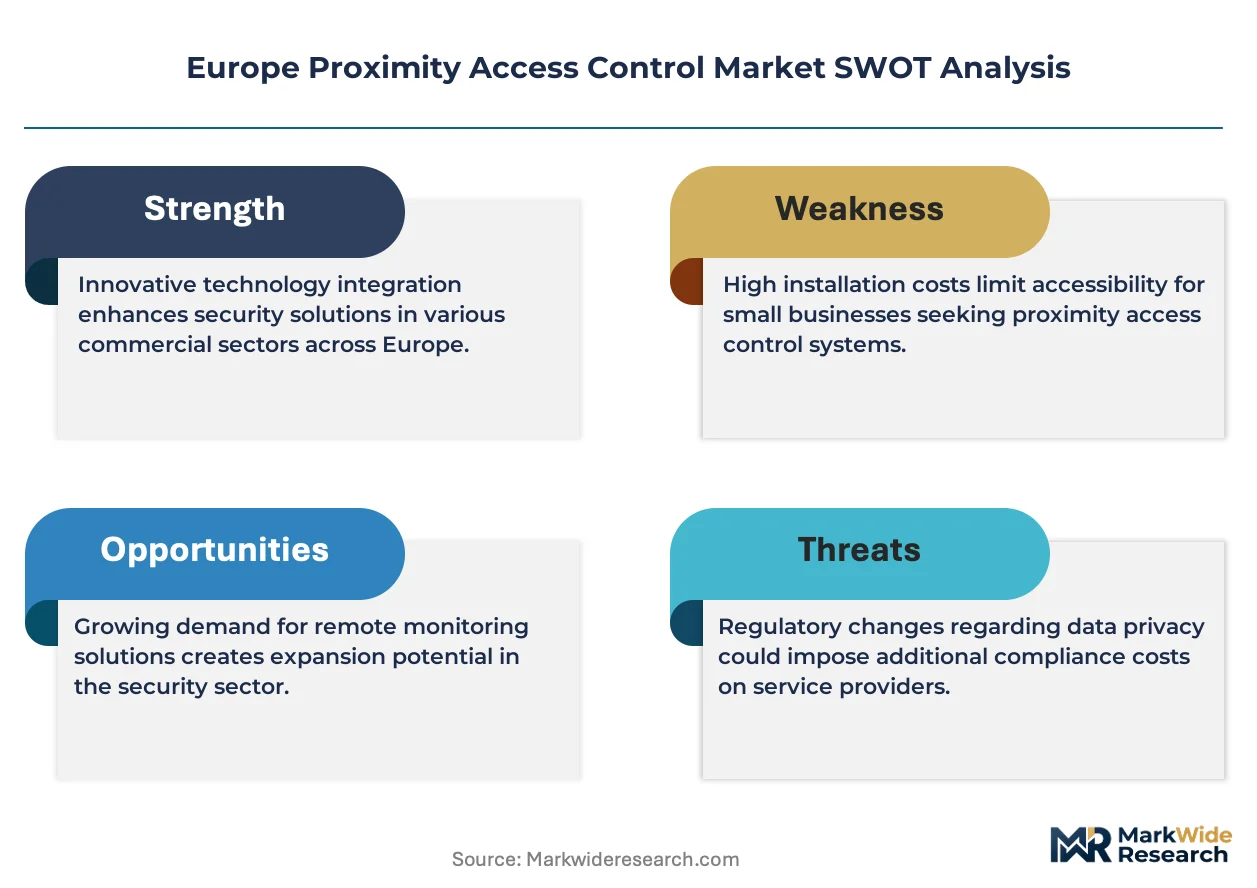
GDPR mandates from European data protection authorities and the EU AI Act's risk classification framework for biometric identification systems are reshaping product certification requirements and procurement criteria. ETSI cybersecurity standards and CE marking under the Radio Equipment Directive further constrain hardware imports and software deployments from non-compliant vendors. Stakeholders must monitor evolving conformity assessment pathways as regulators tighten algorithmic transparency obligations for facial recognition and fingerprint matching systems.
Market Dynamics
GDPR and the EU AI Act are compressing product development timelines as manufacturers redesign biometric capture modules to satisfy algorithmic transparency mandates before CE marking approval.
Growth Catalysts
- Healthcare digitization:French and German hospitals are deploying fingerprint-enabled staff authentication to secure electronic patient records against unauthorized access.
- EU AI Act risk classification:Biometric identification systems face mandatory conformity assessments that favor established vendors with compliance infrastructure.
- Cloud-native architecture:Educational institutions across Spain and Italy are adopting centralized multi-campus credential management without dedicated IT staffing.
Market Restraints
- Semiconductor input volatility:RFID reader production depends on specialized ASIC supply concentrated in East Asian foundries.
- CE marking friction:The Radio Equipment Directive creates extended certification timelines for non-EU hardware imports.
- Mobile credential substitution:Smartphone-based authentication threatens dedicated card and fob form factors in commercial real estate.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit low installed base density in manufacturing facilities relative to Western European benchmarks.
- Transportation hub modernization:Railway stations and airports across the Netherlands and Belgium seek contactless passenger flow management.
- CSRD reporting alignment:Sustainability disclosure requirements create procurement preference for vendors with documented supply chain emissions data.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for 13.56 MHz antenna tuning requires specialized RF expertise concentrated in Germany and the United Kingdom.
- Legacy Wiegand protocol integration:Decades-old wiring infrastructure in British commercial buildings complicates IP-based reader retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Proximity Access Control Market |
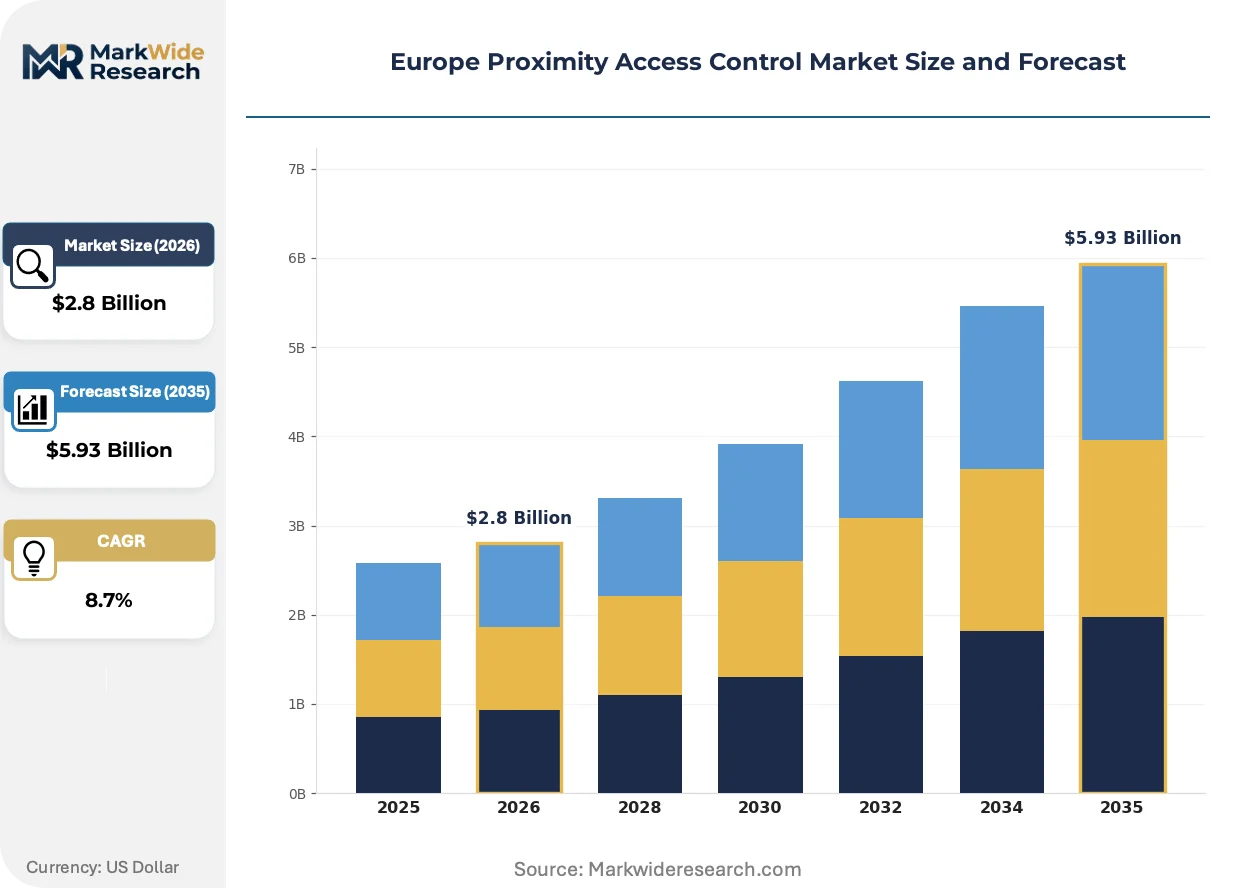
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Biometrics, Smart Cards, PIN Codes Application: Commercial Buildings, Residential Security, Educational Institutions, Transportation Hubs End User: Government, Healthcare, Retail, Manufacturing Installation: Standalone Systems, Integrated Systems, Cloud-Based Solutions, Mobile Solutions |
| Companies Covered | SALTO Systems, Bosch Security Systems GmbH, Kisi Inc, ASSA ABLOY (HID Global), Innovatrics s.r.o., Johnson Controls, Honeywell International Inc., SimpliSafe Inc., Identiv Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Proximity Access Control Market Trends and Innovations
Mobile credential platforms are collapsing the distinction between physical access and IT identity management, forcing hardware vendors to restructure around software recurring revenue.
Multi-technology readers capable of simultaneously processing 125 kHz proximity, 13.56 MHz smart card, and BLE mobile credentials are unifying previously fragmented installed bases. Property managers in Swedish and Danish office complexes are adopting these hybrid devices to avoid forklift upgrades during tenant transitions. This convergence is unifying vendor competition around firmware feature depth rather than single-protocol hardware performance.
ETSI cybersecurity certification for connected access control devices is tightening hardware security module requirements under EN 303 645 standards. Manufacturers must now document secure boot chains and encrypted firmware update mechanisms before market entry. French critical infrastructure operators and German industrial facilities are prioritizing ETSI-certified products in procurement specifications.
Subscription-based credential lifecycle management is displacing perpetual license models among mid-market buyers. Facility management firms in the United Kingdom are unbundling hardware acquisition from ongoing identity provisioning services. This reconfiguration is most visible in university and healthcare networks where seasonal staff turnover demands rapid credential issuance and revocation.
Europe Proximity Access Control Market Segmentation
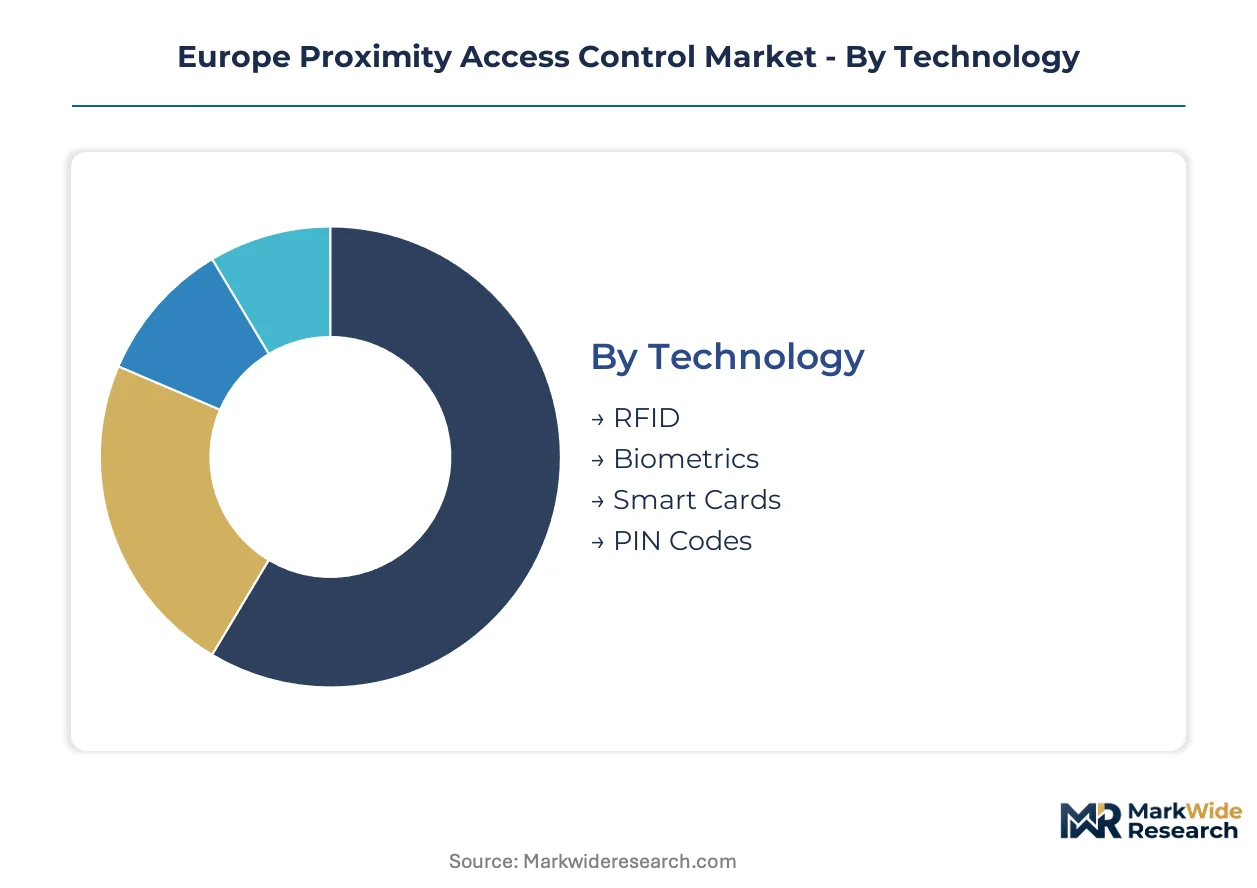
Technology heterogeneity across European access control creates distinct procurement patterns. Buyers balance legacy compatibility against biometric compliance demands under GDPR and the EU AI Act.
Technology:
Standalone RFID modules dominate retrofit projects, while biometric engines embed into integrated security stacks requiring algorithmic transparency certification.
- RFID:Operates on 125 kHz proximity and 13.56 MHz smart card frequencies with read ranges from contact to 10 centimeters. German transportation authorities and French hospital networks prioritize multi-technology readers to bridge legacy credential populations during phased upgrades.
- Biometrics:Fingerprint and facial recognition templates demand specialized hardware security modules under ETSI EN 303 645. Dutch critical infrastructure operators and British healthcare trusts are expanding fingerprint-enabled staff authentication to satisfy patient data protection mandates.
- Smart Cards:Encrypted contactless credentials with mutual authentication protocols.
- PIN Codes:Keypad entry systems serving as backup authentication or standalone low-security applications.
RFID leads volumes today; biometrics is gaining share fastest.
Application:
Cost tier separation drives procurement: premium integrated suites for high-assurance facilities versus modular standalone units for budget-constrained deployments.
- Commercial Buildings:Multi-technology readers processing proximity, smart card, and BLE mobile credentials unify fragmented tenant populations. Swedish and Danish office complexes adopt hybrid devices to avoid infrastructure replacement during lease transitions.
- Transportation Hubs:Contactless passenger flow management systems prioritize throughput over identity assurance. Railway stations across the Netherlands and Belgium are modernizing gate infrastructure to reduce physical credential handling.
- Educational Institutions:Cloud-native centralized administration without dedicated IT staffing.
- Residential Security:Smartphone-based mobile credentials threaten dedicated fob form factors.
Commercial buildings anchor revenue; transportation hubs show the steepest expansion trajectory.
End User:
Customer type determines compliance burden: government and healthcare face mandatory conformity assessments, while retail and manufacturing operate under lighter regulatory thresholds.
- Government:Biometric identification systems trigger EU AI Act high-risk classification requiring exhaustive documentation. French and German federal facilities prioritize established vendors with pre-built compliance infrastructure.
- Healthcare:Fingerprint-enabled staff authentication secures electronic patient records against unauthorized access. Hospitals across France and Germany are deploying biometric capture modules to satisfy GDPR data protection mandates.
- Retail:Loss prevention and employee time-and-attendance tracking.
- Manufacturing:Shop-floor access control with dust and vibration resistance requirements.
Healthcare leads procurement intensity; government contracts carry the highest compliance overhead.
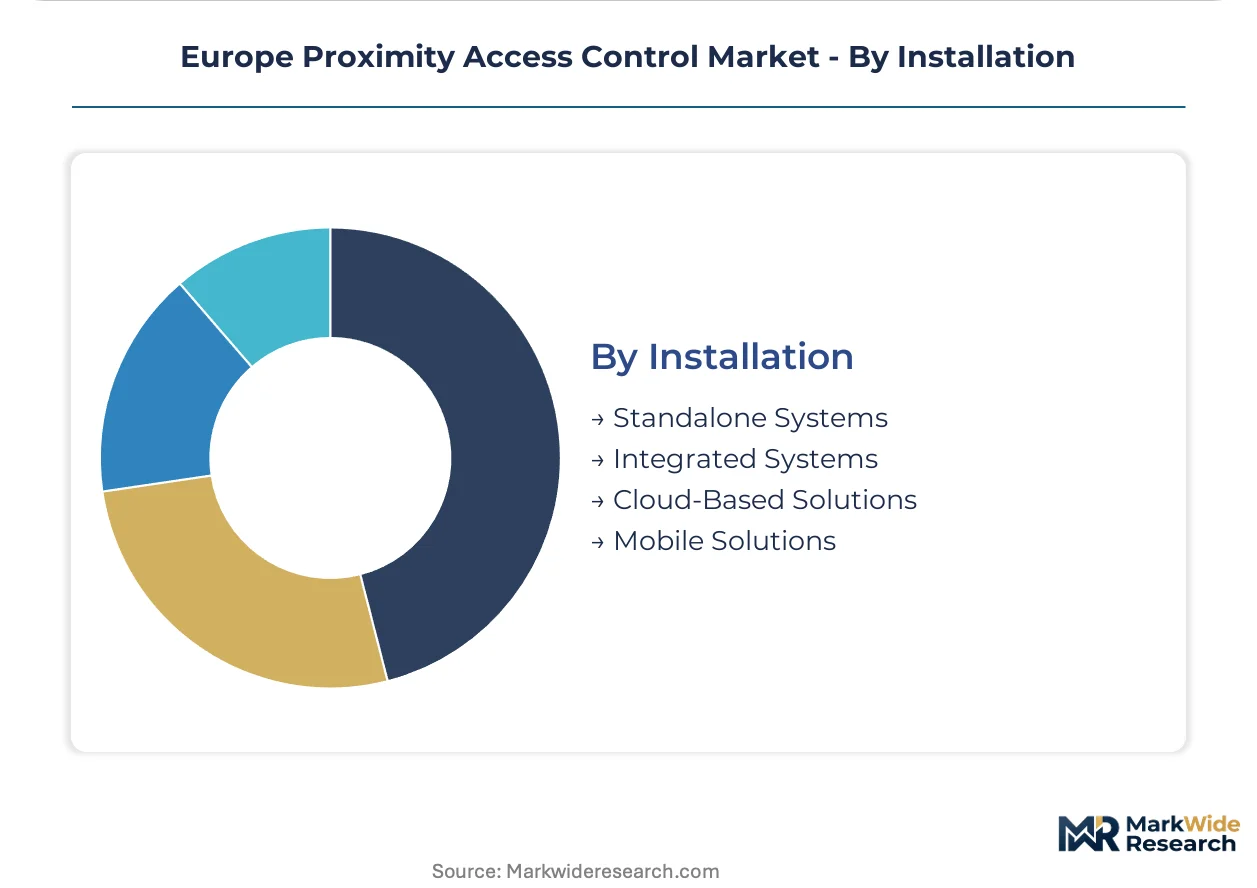
Installation:
Maturity gradient separates legacy on-premise deployments from cloud-native architectures expanding among mid-market buyers lacking dedicated security IT staffing.
- Cloud-Based Solutions:Subscription credential lifecycle management displaces perpetual licenses. Facility management firms in the United Kingdom unbundle hardware acquisition from ongoing identity provisioning services, particularly visible in university networks with seasonal staff turnover.
- Integrated Systems:IP-based readers tie into building management and video surveillance platforms. Decades-old Wiegand wiring in British commercial buildings complicates retrofit timelines.
- Standalone Systems:Self-contained units without network dependency.
- Mobile Solutions:BLE and NFC smartphone credentials collapsing physical and IT identity boundaries.
Integrated systems dominate installed base; cloud-based solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor investment patterns as GDPR and EU AI Act compliance costs widen the gap between established Western European markets and emerging Eastern European deployments. Manufacturers are redirecting production capacity toward countries with lighter algorithmic transparency burdens while maintaining sales presence in high-compliance jurisdictions.
Germany
Industrial automation and critical infrastructure protection drive biometric authentication demand across factory floors and energy facilities. The Federal Office for Information Security enforces BSI technical guidelines for access control systems in government buildings. Bavaria's Munich-Stuttgart corridor hosts concentrated vendor R&D activity for 13.56 MHz antenna engineering and firmware development.
France
Hospital digitization and federal facility security upgrades expand fingerprint-enabled staff authentication networks. CNIL data protection audits mandate privacy-by-design certification for facial recognition deployments in public spaces. The Paris-Saclay cluster concentrates system integrators serving Île-de-France healthcare trusts and transportation authorities.
United Kingdom
University networks and commercial real estate retrofits sustain multi-technology reader demand amid legacy Wiegand infrastructure constraints. The Information Commissioner's Office enforces GDPR-derived accountability frameworks for biometric data processing. London's facility management sector leads adoption of subscription-based credential lifecycle services.
Netherlands
Schiphol Airport and Rotterdam rail hub modernization programs prioritize contactless passenger flow management systems. ETSI cybersecurity certification under EN 303 645 shapes procurement specifications for critical infrastructure operators. The Randstad metropolitan ring concentrates pilot deployments for BLE mobile credential integration.
Poland
Manufacturing facility security upgrades lag Western European biometric penetration rates, creating retrofit opportunities for RFID-based systems. National cyber security agency guidelines align with EU NIS2 directive implementation timelines. The Silesian industrial basin exhibits rising demand for dust-resistant standalone units in mining and heavy manufacturing environments.
Europe Proximity Access Control Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated security conglomerates anchoring premium-tier government contracts while modular specialists capture mid-market commercial retrofits. The vendor landscape exhibits moderate consolidation around firms with pre-built GDPR and EU AI Act compliance infrastructure. Three archetypes dominate: hardware-anchored incumbents with manufacturing depth, cloud-native challengers with subscription revenue models, and biometric engine specialists with algorithmic transparency documentation. Competitive dynamics center on M&A activity targeting firmware capabilities and strategic partnerships bridging mobile credential platforms with legacy reader installed bases.
Within the integrated conglomerate tier, ASSA ABLOY and Bosch Security Systems GmbH exemplify manufacturing-scale incumbents leveraging deep European production footprints and established certification relationships with BSI and ETSI authorities. SALTO Systems occupies a position among cloud-native specialists, representing the architectural shift toward centralized credential management without on-premise server dependencies. These three anchors illustrate the strategic divergence between hardware-centric recurring revenue through mobile credential platforms and software-centric subscription models unbundled from physical device sales.
| Leading Market Players |
|---|
| SALTO Systems |
| Bosch Security Systems GmbH |
| Kisi Inc |
| ASSA ABLOY (HID Global) |
| Innovatrics s.r.o. |
| Johnson Controls |
| Honeywell International Inc. |
| SimpliSafe Inc. |
| Identiv Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing of 13.56 MHz RFID readers in Germany and the Netherlands anchors vendor pricing power through reduced tariff exposure and accelerated CE marking timelines under the Radio Equipment Directive. This integration pattern compresses landed costs for EU healthcare and government buyers while forcing non-integrated competitors to absorb customs friction and extended certification cycles.
Pricing Analysis
Distributor margin layers in Eastern European markets absorb 15-25 point markups over Western European direct procurement channels. Three-tier pricing structure across ETSI-certified premium, CE-marked standard, and uncertified economy levels separates German critical infrastructure operators from Polish manufacturing facilities and budget-constrained Romanian installers. Pricing pressure stems from smartphone-based mobile credential substitution threatening dedicated reader hardware volumes. Healthcare networks in France and the United Kingdom exhibit lowest price sensitivity due to GDPR compliance mandates, while Polish industrial buyers prioritize per-unit acquisition cost over lifecycle service bundling.
Supply Chain Analysis
Freight cost volatility from East Asian ASIC foundries to European assembly plants compresses margins on entry-level RFID modules. Specialized semiconductor supply concentrates in Taiwan, South Korea, and China, with antenna substrate materials sourcing from German and Czech precision metalwork suppliers. Single-source vulnerability in 125 kHz proximity chip supply creates procurement risk during foundry allocation cycles. Distribution runs through authorized security integrators in France and Germany, direct OEM relationships in the United Kingdom, and electrical wholesale channels in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR compliance cost differentials between Western European high-enforcement zones and Eastern European emerging markets create arbitrage opportunities for vendors with modular certification architectures. The EU AI Act's risk classification burden in France and Germany contrasts with lighter conformity assessment pathways in Poland and Romania.
For Market Incumbents: Hedge biometric algorithm obsolescence risk by acquiring firmware specialists with pre-built ETSI EN 303 645 documentation. Deepen backward integration into 13.56 MHz antenna production in Bavaria to defend margin position against East Asian module imports. Channel control through exclusive integrator partnerships in the Netherlands and Belgium protects pricing power against cloud-native challengers unbundling hardware from subscription services.
For New Entrants and Emerging Players: The EU AI Act in France and Germany opens a window for compliance-as-a-service offerings targeting mid-market healthcare trusts lacking internal conformity assessment resources. White-space targets include Polish manufacturing facilities with dust-resistant standalone unit requirements and Romanian educational institutions seeking cloud-native multi-campus administration. A direct-to-facility-manager go-to-market angle bypasses entrenched security integrator relationships in saturated Western European markets.
For Investors and Strategic Acquirers: Roll-up economics work for biometric engine specialists because GDPR and EU AI Act documentation requirements create scale advantages for consolidated compliance infrastructure. The 5-10 year viability window favors vendors with pre-certified algorithmic transparency libraries over hardware-anchored incumbents dependent on mobile credential platform transitions. Watch for ETSI cybersecurity certification mandate expansion into Dutch and Belgian critical infrastructure procurement as an inflection signal for premium-tier vendor concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| ETSI Cybersecurity Certification | BSI and CNIL procurement specifications now mandate EN 303 645 documentation for Dutch critical infrastructure and French federal facilities. |
| Mobile Credential Platform Integration | BLE and NFC smartphone authentication collapses physical access and IT identity boundaries, forcing hardware vendors toward recurring software revenue. |
| Cloud-Native Architecture Deployment | Centralized multi-campus credential management without on-premise servers addresses IT staffing constraints in Spanish and Italian educational networks. |
| Biometric Algorithm Transparency Investment | EU AI Act high-risk classification for facial recognition systems demands exhaustive documentation favoring established vendors with pre-built compliance infrastructure. |
| Eastern European Distribution Expansion | Authorized integrator partnerships in Poland and Romania capture underpenetrated manufacturing facility security upgrades with dust-resistant standalone units. |
Research Methodology
Bottom-up healthcare and transportation hub modeling reconciled against top-down RFID reader production tracking forms the analytical core of this study. Primary interviews with facility security managers, hospital biomedical engineers, government procurement officers, and cloud-native access control platform engineers combined with secondary validation from ETSI certification databases, BSI technical guideline publications, and CE marking registries. Trade data from German customs authorities and French hospital procurement databases anchored supply-side triangulation against end-use demand signals.
Historical trendline analysis across technology adoption curves informed projection modeling without reliance on single-source extrapolation. Segmentation dimensions include authentication modality, deployment architecture, end-user compliance burden, and regional regulatory enforcement intensity. CAGRs were derived from installed base replacement cycles and new-build penetration assumptions. Cloud-native subscription conversion rates in university networks and biometric compliance upgrade timelines in French hospitals served as industry-specific forecast inputs.
Revisions become necessary when EU AI Act implementing acts alter biometric identification system conformity assessment pathways or when semiconductor foundry allocation shocks disrupt 13.56 MHz ASIC supply. Forecasts reflect documented assumptions about GDPR enforcement consistency and ETSI certification mandate expansion timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Global Industrial Access Control Market