
 Complementary Therapy Devices Market | 2026-2036
Complementary Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Complementary Therapy Devices Market Analytics
The home wellness segment is repositioning complementary therapy devices from clinical adjuncts to mainstream consumer essentials. Herb Pharm leverages botanical formulation expertise to anchor its presence in naturopathic supply channels. Nordic Naturals sustains omega-3 adjacency strategies that extend into complementary device bundling. Himalaya dominates Ayurvedic device distribution through pharmacy networks across South Asia and North America.
Complementary therapy devices encompass non-pharmacological instruments designed to modulate physiological states through mechanical, thermal, or electrical stimulation, typically operating at frequencies between 1-120 Hz for TENS units and wavelengths of 600-1000 nm for infrared applications. These instruments serve primary commercial purposes in pain management, musculoskeletal recovery, and autonomic nervous system regulation across outpatient and domestic settings. TENS units and massage guns capture disproportionate margin pools as athletes and seniors drive replacement cycles. Acupuncture mats occupy a maturing niche with stable demand among wellness enthusiasts seeking low-cost entry points. Online retail channels are displacing specialty stores for initial purchases, though medical suppliers retain loyalty for prescription-grade units.
FDA 510(k) clearance requirements for electrical stimulation devices and ISO 13485 quality management standards shape manufacturing rigor and market access timelines for manufacturers. The EU MDR and CE marking framework imposes clinical evidence thresholds that filter out low-substantiation entrants from European distribution. Stakeholders must monitor reimbursement code expansions by Germany's statutory health insurers and Japan's Ministry of Health, Labour and Welfare as these decisions determine whether device costs shift to payers or remain consumer-borne.
Market Dynamics
FDA 510(k) clearance timelines and EU MDR clinical evidence thresholds are compressing product launch windows for electrical stimulation manufacturers, forcing upstream investments in ISO 13485-certified quality management systems before market access.
Growth Catalysts
- Japan's Ministry of Health, Labour and Welfare reimbursement expansions:Integrative device coverage decisions shift cost burden from consumers to statutory payers, accelerating clinic adoption of prescription-grade TENS units.
- Home-use wellness infrastructure:Athletes and aging populations are driving replacement cycles for massage guns and infrared devices through direct-to-consumer channels.
- REACH compliance harmonization:European material safety standards for electrical components reduce cross-border manufacturing friction, enabling centralized production serving multiple member states.
Market Restraints
- Input cost volatility in medical-grade polymers:Specialized housing materials for biocompatible devices face petrochemical price swings that compress assembly margins.
- Technical limitation in waveform precision:Low-cost TENS units lack the frequency modulation range of clinical systems, creating efficacy perception gaps among professional physiotherapists.
- Regulatory friction from FDA electrical safety standards:IEC 60601-1 testing requirements extend certification timelines for novel stimulation modalities.
Strategic Opportunities
- Germany's statutory health insurer preventive care mandates:New reimbursement codes for musculoskeletal prevention create payer-funded entry points for home-use devices.
- Ayurvedic device convergence:Integration of thermal stimulation with traditional medicine protocols opens pharmacy distribution across South Asian and North American diaspora networks.
- Subscription-based device replenishment:Electrode pad and gel consumable auto-ship models are capturing recurring revenue streams from installed base users.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized firmware developers for closed-loop stimulation algorithms command premium compensation, constraining R&D scaling.
- CE marking timeline compression:EU MDR notified body backlogs delay European launches by 12-18 months for novel device categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complementary Therapy Devices Market |
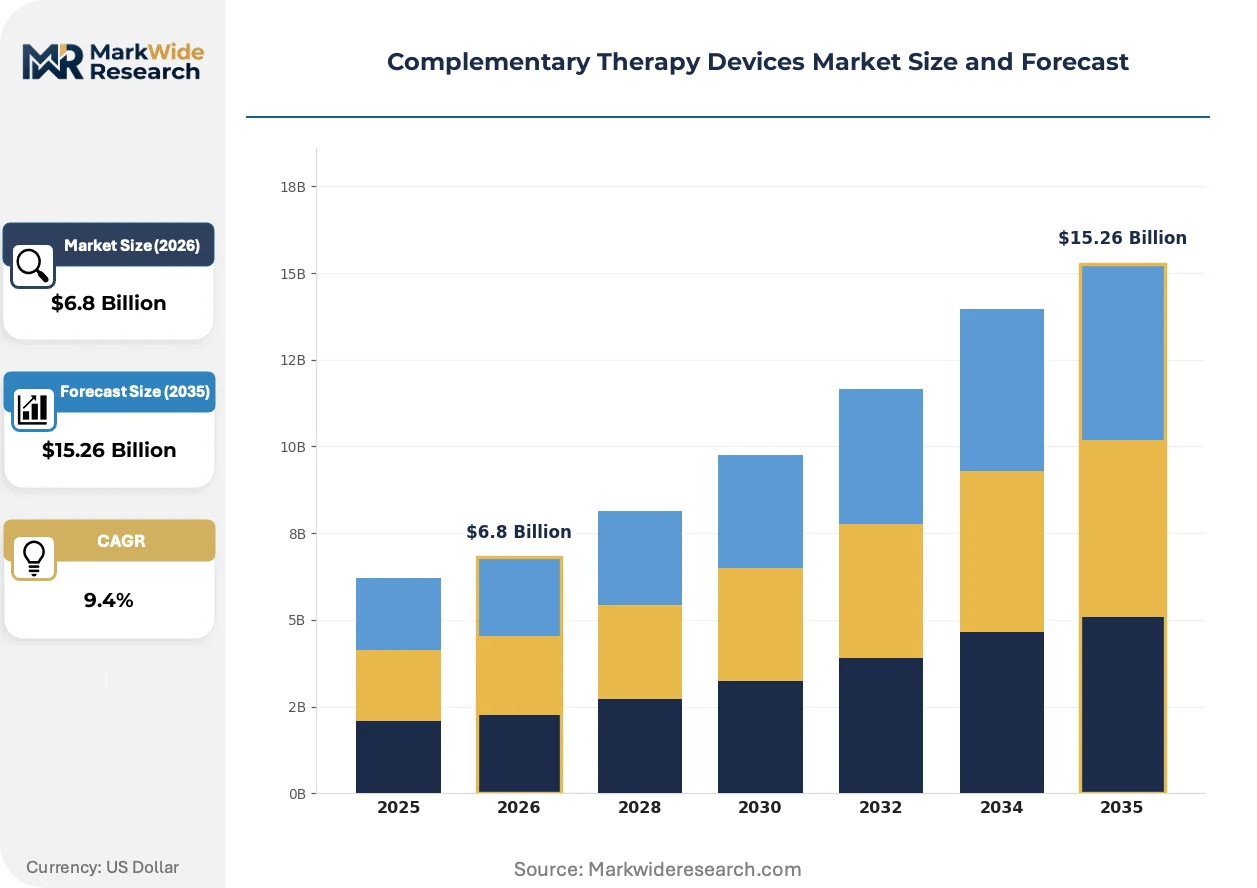
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Acupuncture Mats, TENS Units, Massage Guns, Infrared Lamps Treatment Type: Muscle Relaxation, Pain Relief, Stress Reduction, Energy Therapy User Demographic: Seniors, Athletes, Patients, Wellness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Medical Suppliers, Pharmacies |
| Companies Covered | Herb Pharm, Pure Encapsulations, Nordic Naturals, Columbia Nutritional, Helio USA, Ayush Ayurvedic Pte Ltd, Herbal Hills, The Healing Company, Himalaya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complementary Therapy Devices Market Evolving Landscape
App-connected biofeedback systems are rewriting how users calibrate stimulation intensity, shifting device value from hardware specifications to algorithm-driven personalization engines.
Closed-loop neuromodulation platforms that adjust electrical output based on real-time physiological response are electrifying the competitive landscape for premium pain management devices. Professional sports medicine programs and military rehabilitation facilities are adopting these systems at triple-digit annual purchase rates. The technology is electrifying margin structures by bundling hardware with recurring software licensing rather than one-time device sales.
EU MDR clinical evidence requirements for electrical stimulation devices are tightening substantiation thresholds for market entry. Manufacturers must now submit prospective studies demonstrating safety and performance equivalence to predicate devices. Class IIa devices with novel waveforms face extended notified body review timelines, pushing development roadmaps toward predicate-based 510(k) pathways in the United States as a faster alternative.
Specialty retail channels for complementary therapy devices are losing initial purchase volume to algorithm-curated online marketplaces. Wellness enthusiasts now discover TENS units and massage guns through social platform recommendations rather than in-store demonstrations. This behavioral shift is most pronounced among millennial and Gen Z buyers in the United States and Germany, where subscription-box bundling of devices with supplements is displacing standalone electronics purchases.
Complementary Therapy Devices Market Segmentation
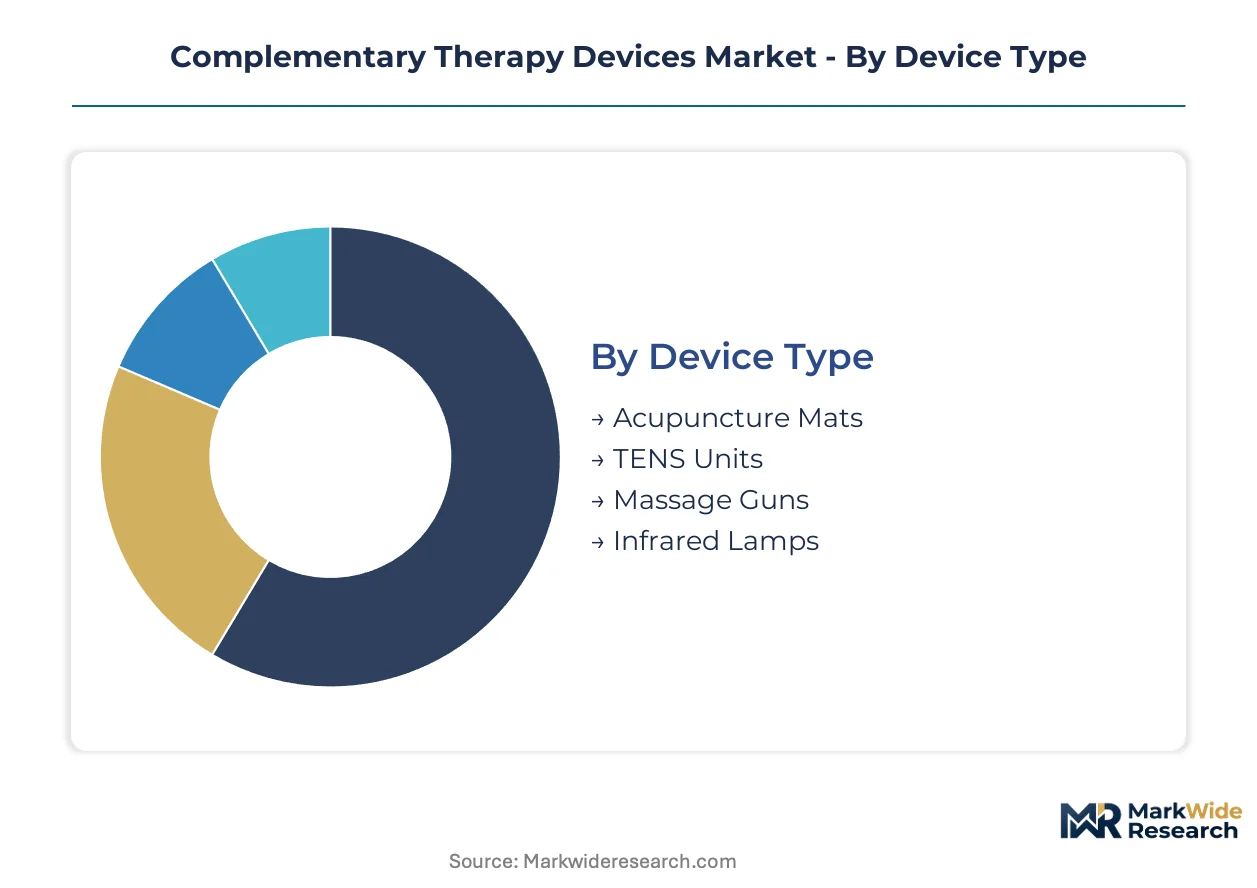
Device taxonomy in complementary therapy markets determines reimbursement eligibility, regulatory pathway complexity, and margin architecture. Manufacturers align R&D portfolios with segments offering the clearest clinical substantiation routes.
Device Type:
Standardization dominates low-frequency electrical stimulation while thermal and mechanical modalities retain artisanal production footprints.
- TENS Units:These electrical stimulation devices operate at 1-120 Hz with waveform modulation capabilities. FDA 510(k) clearance requirements concentrate demand among ISO 13485-certified manufacturers serving United States pain management clinics. Professional physiotherapists drive specification requirements for frequency precision.
- Massage Guns:Percussive therapy devices deliver 16-60 Hz mechanical stimulation through interchangeable attachment heads. Athletes in Germany and Japan sustain replacement cycles through direct-to-consumer channels. Battery longevity and noise reduction specifications differentiate premium tiers.
- Infrared Lamps:Thermal devices emitting 600-1000 nm wavelengths for tissue penetration. Home-use wellness infrastructure in Japan absorbs volume for musculoskeletal maintenance protocols.
- Acupuncture Mats:Pressure point stimulation platforms with plastic or natural material nodes. Wellness enthusiasts seeking low-cost entry points sustain stable demand through online retail discovery.
Most installed capacity flows through TENS Units. Expansion is steepest in Massage Guns.
Treatment Type:
Application focus shifts from symptomatic relief toward preventive autonomic regulation as reimbursement frameworks mature.
- Pain Relief:Electrical and thermal modalities targeting nociceptive and neuropathic pathways. Germany's statutory health insurer preventive care mandates are opening payer-funded distribution for prescription-grade devices.
- Muscle Relaxation:Percussive and vibration technologies addressing myofascial tension. Professional sports medicine programs in the United States adopt closed-loop systems at accelerated procurement rates.
- Stress Reduction:Parasympathetic activation through thermal and pressure-based interventions. Acupuncture mats capture this application through pharmacy networks in South Asian diaspora communities.
- Energy Therapy:Biofield modulation concepts with limited clinical substantiation. Regulatory friction from FDA electrical safety standards constrains commercial scale for novel stimulation modalities.
Pain Relief commands the largest installed base. Muscle Relaxation is gaining share fastest among younger demographics.
User Demographic:
Aging population infrastructure and athletic performance optimization create divergent specification requirements across customer cohorts.
- Seniors:Users aged 65+ requiring ergonomic design and simplified interfaces. Japan's Ministry of Health, Labour and Welfare reimbursement expansions shift cost burden from this demographic to statutory payers.
- Athletes:Performance-focused buyers demanding rapid recovery protocols. Subscription-based device replenishment models capture recurring revenue through electrode pad auto-ship programs.
- Patients:Clinical referral recipients using prescription-grade units under physiotherapist supervision. Medical suppliers retain loyalty for this segment through insurance billing integration.
- Wellness Enthusiasts:Self-directed consumers discovering devices through algorithm-curated online marketplaces. Social platform recommendations displace specialty store demonstrations for initial purchases.
Seniors represent the deepest installed penetration. Athletes show the steepest expansion trajectory through direct-to-consumer channels.
Distribution Channel:
Channel strategy determines margin capture, customer acquisition cost, and regulatory compliance burden simultaneously.
- Online Retail:Algorithm-curated marketplaces and subscription-box bundling platforms. Millennial and Gen Z buyers in the United States and Germany drive volume through social discovery mechanisms.
- Medical Suppliers:Prescription-grade distribution with insurance billing infrastructure. FDA oversight of electrical stimulation devices necessitates specialized compliance capabilities.
- Specialty Stores:Physical demonstration environments for tactile product evaluation. This channel loses initial purchase volume to digital discovery but retains service-oriented replacement sales.
- Pharmacies:Retail health networks integrating Ayurvedic device convergence across South Asian and North American markets. Himalaya anchors presence through this channel for thermal stimulation products.
Medical Suppliers handle the highest-value transactions. Online Retail is climbing the fastest as discovery behavior shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-Saint Paul medical device corridor anchors production capacity for FDA-cleared electrical stimulation systems. Manufacturing clusters in this region supply prescription-grade TENS units to pain management networks across North America and export markets.
United States
Athletes and aging populations drive replacement cycles for massage guns and infrared devices through direct-to-consumer channels. FDA 510(k) clearance requirements for electrical stimulation devices compress product launch timelines and favor ISO 13485-certified manufacturers. The Minneapolis-Saint Paul corridor concentrates production of prescription-grade units for clinic networks.
Germany
Statutory health insurer preventive care mandates open payer-funded distribution channels for musculoskeletal prevention devices. EU MDR clinical evidence thresholds filter low-substantiation entrants from European distribution. Manufacturing activity clusters in Baden-Württemberg, where precision engineering capabilities serve both domestic and export demand.
Japan
Ministry of Health, Labour and Welfare reimbursement expansions shift cost burden from seniors to statutory payers, accelerating clinic adoption of prescription-grade TENS units. Home-use wellness infrastructure absorbs volume for thermal maintenance protocols. Industrial concentration in the Kanto region around Tokyo supports device assembly for domestic and Asian markets.
India
Ayurvedic device convergence opens pharmacy distribution across South Asian diaspora networks and domestic urban centers. CDSCO medical device regulations impose quality standards on electrical stimulation imports and local manufacturing. Maharashtra and Gujarat host emerging assembly operations for thermal stimulation products targeting wellness retail channels.
United Kingdom
Integrative health reimbursement frameworks expand through National Health Service pilot programs for non-pharmacological pain management. MHRA regulations align with EU MDR standards post-Brexit, maintaining clinical evidence requirements for market access. The Southeast England corridor around London concentrates distribution infrastructure for European supply chains.
Complementary Therapy Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as botanical specialists extend into device adjacencies and wellness platforms bundle hardware with consumable subscriptions. The vendor base spans three tiers: established nutraceutical houses with device distribution partnerships, dedicated therapy device manufacturers with ISO 13485 certification, and direct-to-consumer wellness brands leveraging algorithm-curated discovery. Strategic archetypes include Ayurvedic-anchored pharmacy networks, omega-3 adjacent bundling platforms, and sports medicine-focused recovery systems. M&A activity and subscription-based replenishment models represent the dominant competitive moves reshaping revenue architecture.
Among botanical-heritage players, Herb Pharm and Himalaya exemplify archetypes leveraging formulation credibility to anchor device distribution through naturopathic and pharmacy channels respectively. Nordic Naturals occupies a position within the omega-3 adjacency tier, where supplement bundling strategies extend into complementary device ecosystems. These three companies represent distinct pathways for non-device specialists to capture wellness infrastructure spend without vertical integration into manufacturing.
| Leading Market Players |
|---|
| Herb Pharm |
| Pure Encapsulations |
| Nordic Naturals |
| Columbia Nutritional |
| Helio USA |
| Ayush Ayurvedic Pte Ltd |
| Herbal Hills |
| The Healing Company |
| Himalaya |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA 510(k)-cleared prescription units and unregulated consumer wellness devices manifests in pricing spreads exceeding threefold, with supply chain configurations clustering ISO 13485-certified manufacturers in the Minneapolis-Saint Paul corridor for premium tiers while commodity assemblers in Southeast Asia feed economy segments through direct-to-consumer channels.
Pricing Analysis
Input-cost pass-through from medical-grade polymers and specialized electrode materials intensifies margin compression across mid-tier manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, battery longevity specifications, and software companion integration. Pricing pressure stems from petrochemical volatility in biocompatible housing materials. Wellness enthusiasts through algorithm-curated marketplaces exhibit highest price sensitivity, while hospital purchasing committees demonstrate lowest sensitivity due to reimbursement code alignment.
Supply Chain Analysis
Certification gating through ISO 13485 and FDA 510(k) requirements concentrates component sourcing among United States, Germany, and Japan-based precision electronics suppliers. Supply chains draw from Taiwanese semiconductor foundries for biofeedback microcontrollers, South Korean battery cell manufacturers, and German precision motor suppliers for percussive therapy devices. Single-source vulnerability in medical-grade polymer feedstocks from petrochemical complexes presents structural exposure. Distribution runs through medical suppliers with insurance billing infrastructure for prescription-grade units, while online retail platforms capture wellness-segment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 510(k) clearance timelines and EU MDR clinical evidence thresholds continuously elevate compliance barriers, with Germany's statutory health insurer preventive care mandates serving as the pivotal demand catalyst shifting cost burden from consumers to payers.
For Market Incumbents: Lock in channel control through exclusive hospital system partnerships and GPO contract extensions before reimbursement code expansions attract new entrants. Deepen backward integration into electrode pad manufacturing to capture consumable recurring revenue streams. ISO 13485 certification investments remain the priority lever against emerging direct-to-consumer brands lacking clinical substantiation capabilities. For New Entrants and Emerging Players: The price-point gap between premium closed-loop neuromodulation systems and basic TENS units creates white-space opportunity in the mid-tier app-connected segment. Target wellness enthusiasts through subscription-box bundling with Ayurvedic thermal devices as the most penetrable entry vector. Pursue pharmacy distribution partnerships in South Asian diaspora networks as the specific go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware development talent scarcity constrains R&D scaling for mid-cap specialists. Five-to-ten year viability favors platforms bundling hardware with software licensing over pure device manufacturers. Acquisition target archetype: ISO 13485-certified manufacturers with existing FDA clearances and underutilized production capacity. Watch EU MDR notified body backlog resolution as the inflection indicator for European launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management certification unlocks FDA 510(k) pathways and hospital procurement eligibility. |
| Software Companion Development | App-connected biofeedback systems shift value capture from hardware sales to recurring licensing revenue. |
| Reimbursement Strategy Execution | Germany's statutory health insurer code expansions create payer-funded distribution channels for preventive devices. |
| Electrode Pad Auto-Ship Programs | Consumable replenishment models capture lifetime value from installed base users. |
| Ayurvedic Device Convergence | Integration with traditional medicine protocols opens pharmacy networks across South Asian and North American markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement code expansions. Bottom-up segment sizing and top-down macroeconomic triangulation ensured convergence across estimation approaches.
Segment-weighting across device type, treatment application, user demographic, and distribution channel dimensions drove analytical framework construction across the projection horizon. CAGRs derived from installed base growth rates, replacement cycle frequencies, and reimbursement expansion timelines. Forecast inputs incorporated FDA clearance pipeline velocity and EU MDR notified body capacity constraints as industry-specific demand modifiers.
Caveats apply where FDA 510(k) backlog resolution, EU MDR clinical evidence requirement amendments, or petrochemical price volatility could materially shift the outlook. Forecasts reflect assumptions regarding reimbursement code expansion continuity and consumer wellness infrastructure investment trajectories. A model refresh is warranted upon material change in Germany's statutory health insurer preventive care mandate implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Artificial Eye Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
US C-Arms Market
Medical Devices
Global Microcatheter Market