
 Anesthesia Circuits Market | 2026-2036
Anesthesia Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Circuits Market Insights
China is narrowing the anesthesia circuit supply gap through expanded domestic extrusion and molding capacity for corrugated breathing tubes. Medtronic plc leverages backward integration into polymer compounding to secure resin supply for its circuit assemblies. Drägerwerk AG & Co. KGaA anchors European demand through dedicated manufacturing lines in Lübeck, Germany. Fisher & Paykel Healthcare differentiates via heated humidification modules that integrate directly with its breathing circuit platforms.
Anesthesia circuits are closed or semi-closed tubular assemblies—typically constructed from polyvinyl chloride, polyethylene, or silicone—that transport anesthetic gases, oxygen, and carbon dioxide between the anesthesia machine and the patient airway, maintaining precise pressure and flow parameters during controlled ventilation. Breathing circuits command the largest product segment due to universal deployment across every inhalation anesthetic procedure, while EtCO2 detectors represent the fastest-expanding category as capnography becomes standard of care in pre-hospital and procedural sedation settings. Surgical centers are emerging as a concentrated end-user segment where disposable circuit adoption outpaces reusable alternatives because of throughput efficiency and infection control protocols.
The FDA governs circuit materials under biocompatibility ISO 10993 testing requirements, while the EU MDR demands clinical evidence for breathing system components marketed in Europe, extending certification timelines and raising barriers for new entrants. China's NMPA enforces GB standards for medical polymer tubing that affect import eligibility for foreign-manufactured circuits. Stakeholders must monitor how evolving sterilization validation requirements and sustainability mandates for single-use plastics reshape material selection and geographic sourcing strategies across the supply base.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while mandating biocompatibility documentation upgrades under FDA Class II device rules, forcing manufacturers to absorb compliance costs or lose centralized supply contracts.
Growth Catalysts
- Capnography standardization:Pre-hospital and procedural sedation protocols now mandate EtCO2 monitoring, expanding detector attachment points on every breathing circuit.
- China's polymer tubing capacity:Domestic extrusion and molding investments are closing supply gaps for corrugated breathing tubes, reducing import dependency.
- EU MDR clinical evidence requirements:Extended certification timelines are advantaging incumbents with established technical files, locking out undercapitalized entrants.
Market Restraints
- Resin supply concentration:Medtronic's backward integration into polymer compounding highlights vulnerability for non-integrated assemblers facing medical-grade PVC and silicone shortages.
- Single-use plastic sustainability mandates:EU Green Deal packaging regulations and state-level hospital waste reduction targets threaten polyethylene circuit economics.
- Reusable circuit disinfection validation:Steam sterilization compatibility testing adds fixed costs that disfavor smaller surgical center buyers.
Strategic Opportunities
- Ambulatory surgical center penetration:Freestanding facilities in the United States are adopting disposable circuits for throughput efficiency, creating volume pools outside hospital purchasing agreements.
- Heated humidification integration:Fisher & Paykel's module-circuit convergence points toward platform stickiness through respiratory therapy system bundling.
- India's PLI scheme for medical devices:Domestic manufacturing incentives could establish South Asian export capacity for corrugated tubing assemblies serving Middle East and Southeast Asian markets.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:Third-party laboratory capacity constraints are extending FDA 510(k) clearance timelines for new circuit materials.
- Legacy anesthesia machine interface fragmentation:Proprietary connector standards across Dräger, GE, and Mindray platforms force circuit manufacturers to maintain redundant SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Circuits Market |
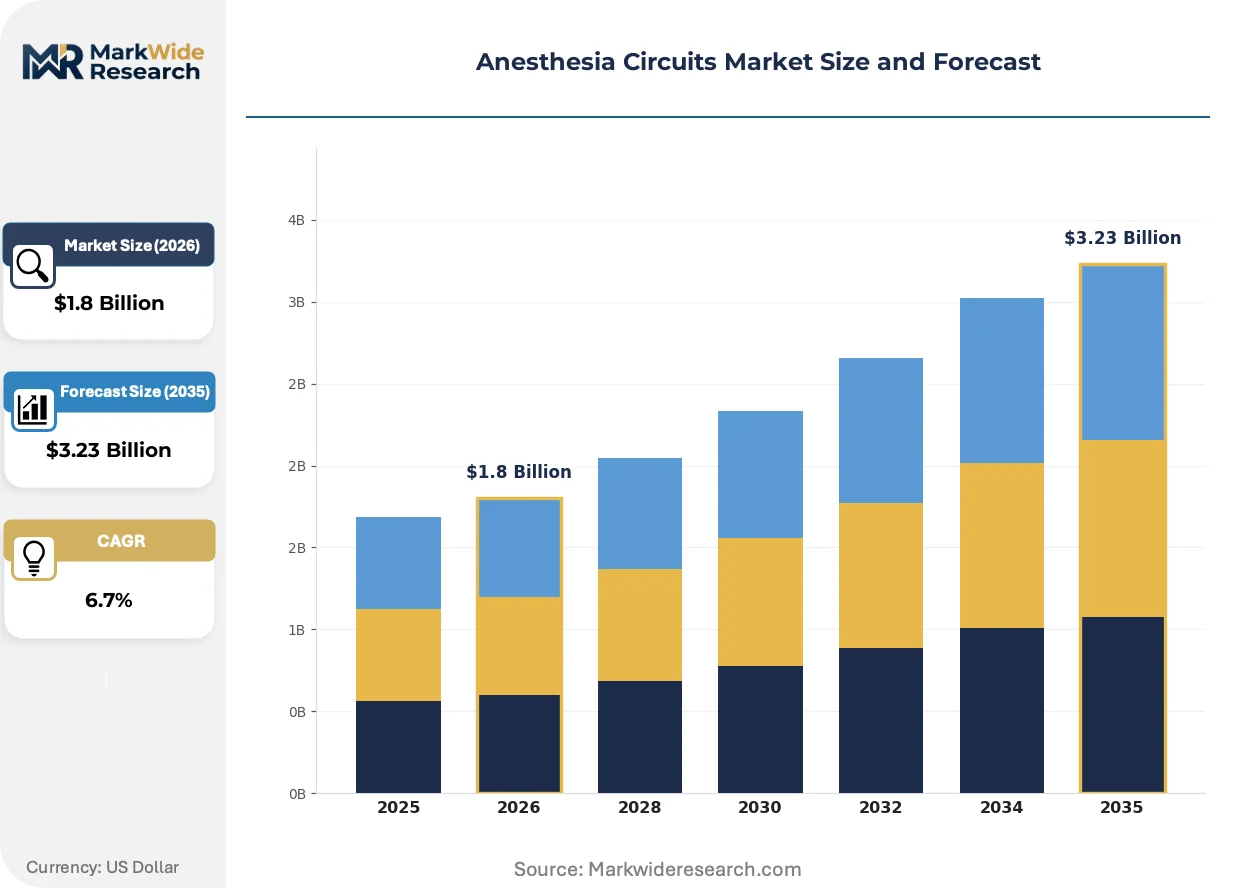
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breathing Circuits, EtCO2 Detectors, Flex Tubing, Humidifiers Therapy Area: General Surgery, Cardiac Procedures, Pain Management, Respiratory Care End User: Hospitals, Surgical Centers, Ambulatory Care, Home Care Delivery Mode: Inhalation, Intravenous, Regional Anesthesia, Others |
| Companies Covered | Medtronic plc, GE HealthCare, Drägerwerk AG & Co. KGaA, Teleflex Incorporated, Fisher & Paykel Healthcare, Ambu A/S, Becton Dickinson and Company, Koninklijke Philips N.V., Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Circuits Market Trends and Innovations
Material science convergence and regulatory documentation intensity are redefining competitive advantage, with circuit platforms evolving from commodity tubing assemblies toward integrated respiratory management systems.
Silicone-PVC hybrid tubing is hybridizing circuit construction by combining silicone's biocompatibility with PVC's cost structure for extended-duration procedures. Academic medical centers in Germany and the United States are piloting these assemblies for cardiac and neurosurgical cases exceeding six hours. The technology is hybridizing procurement criteria, forcing purchasing committees to weight material performance against single-use economics.
China's NMPA enforcement of GB standards for medical polymer tubing is tightening import eligibility for foreign-manufactured circuits, requiring retesting of legacy products. Domestic manufacturers in Shandong and Jiangsu provinces are capturing share from multinational suppliers unable to navigate documentation requirements. European and North American exporters are responding by establishing in-country testing partnerships or ceding the mid-tier hospital segment.
Centralized purchasing agreements are consolidating anesthesia supply contracts under health system procurement umbrellas, collapsing the independent distributor channel. Integrated delivery networks in the United States now negotiate directly with circuit assemblers, extracting volume discounts that squeeze traditional medical-surgical distributor margins. This concentration is most visible in the Midwest and Southeast regions where hospital merger activity has created super-regional buying entities controlling 40-plus facility networks.
Anesthesia Circuits Market Segmentation
Anesthesia circuit procurement varies sharply across clinical settings, with infection control protocols and procedure duration dictating material specifications. Segmentation reveals where disposable premiums command price tolerance versus where reusable economics survive.
Product Type:
After-sales intensity concentrates in humidification modules and capnography attachments, where calibration cycles and sensor replacement generate recurring revenue streams distinct from tubing commoditization.
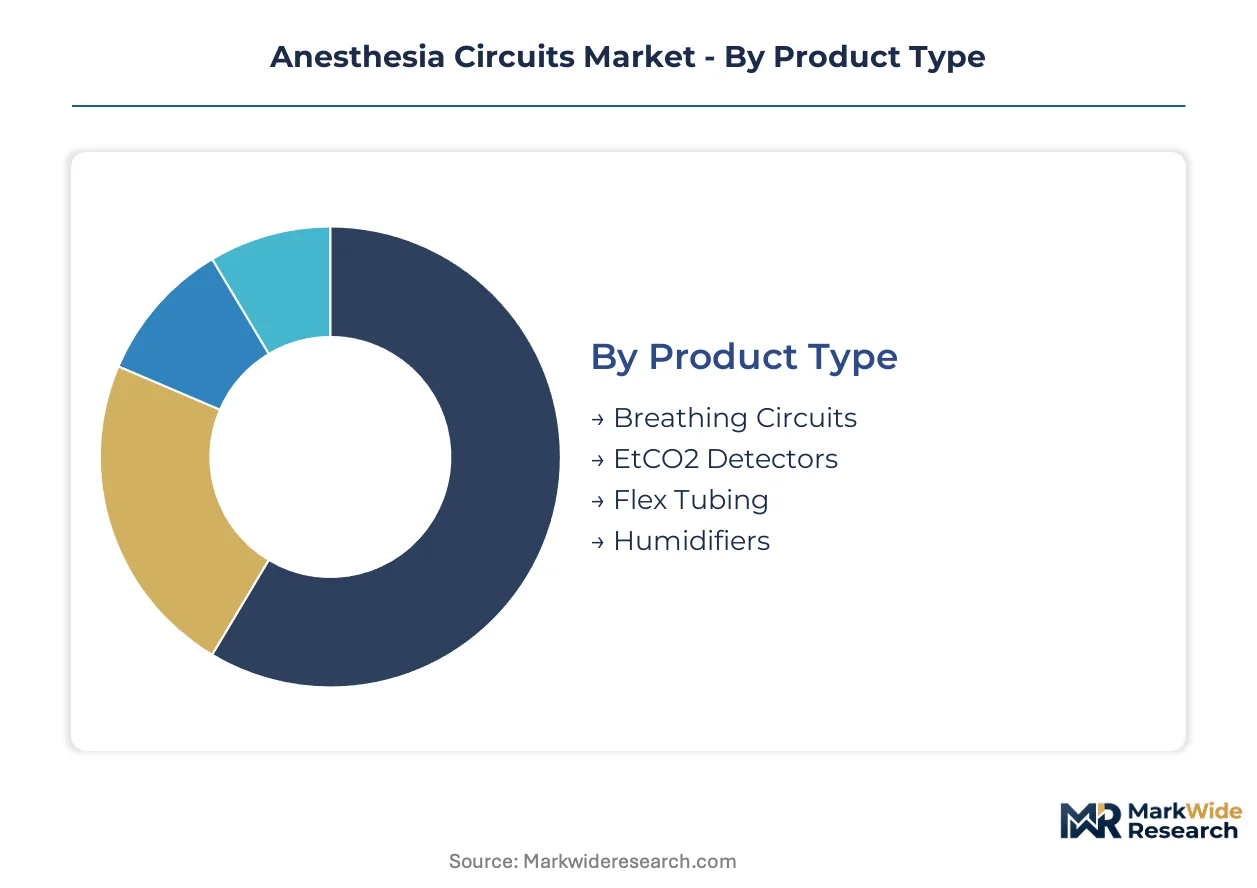
- Breathing Circuits:Corrugated tubular assemblies in polyvinyl chloride, polyethylene, or silicone transport anesthetic gases between machine and patient airway. Hospital procurement departments in the United States are consolidating supply contracts for single-use variants to eliminate cross-contamination risks in high-throughput surgical suites.
- EtCO2 Detectors:Sidestream and mainstream capnography sensors attach at circuit junctions to monitor end-tidal carbon dioxide. Pre-hospital emergency protocols and procedural sedation standards are mandating these attachments across Germany and the United States, expanding detector points per circuit assembly.
- Flex Tubing:Lightweight, kink-resistant polymer conduits for positioning flexibility during head-and-neck procedures.
- Humidifiers:Heated or passive moisture exchange modules integrated at the patient end of breathing circuits.
By volume, Breathing Circuits leads. By growth pace, EtCO2 Detectors is ahead.
Therapy Area:
Procedure complexity stratifies circuit specifications, with extended-duration interventions demanding enhanced biocompatibility and thermal stability.
- General Surgery:Routine abdominal and orthopedic procedures under 120 minutes utilize standard PVC circuits without specialized humidification. Surgical centers in the United States Midwest are driving volume through bundled disposable circuit packs optimized for turnover efficiency.
- Cardiac Procedures:Cardiopulmonary bypass and open-heart surgeries exceeding six hours require silicone-PVC hybrid tubing for extended biocompatibility. Academic medical centers in Germany and the United States are piloting these assemblies for temperature-stable performance during prolonged anesthesia.
- Pain Management:Regional anesthesia and sedation protocols for chronic pain interventions.
- Respiratory Care:Critical ventilation support in intensive care and emergency settings.
General Surgery dominates unit volume. Cardiac Procedures commands the steepest expansion trajectory for premium circuit materials.
End User:
Facility scale determines contract structure, with centralized purchasing favoring high-volume assemblers over niche suppliers.
- Hospitals:Integrated delivery networks negotiate directly with circuit manufacturers, collapsing independent distributor margins. Super-regional buying entities controlling 40-plus facility networks in the United States Southeast extract volume discounts that reshape vendor economics.
- Surgical Centers:Freestanding ambulatory facilities prioritize disposable circuits for throughput efficiency and infection control compliance. These centers in the United States are adopting single-use breathing systems faster than reusable alternatives, creating demand pools outside hospital procurement umbrellas.
- Ambulatory Care:Outpatient clinics and emergency departments with intermittent anesthesia needs.
- Home Care:Long-term ventilation patients requiring portable circuit configurations.
Hospitals retain volume leadership. Surgical Centers is gaining share fastest as site-of-service migration accelerates.
Delivery Mode:
Anesthetic agent administration method dictates circuit architecture, with inhalation systems requiring the most complex gas management assemblies.
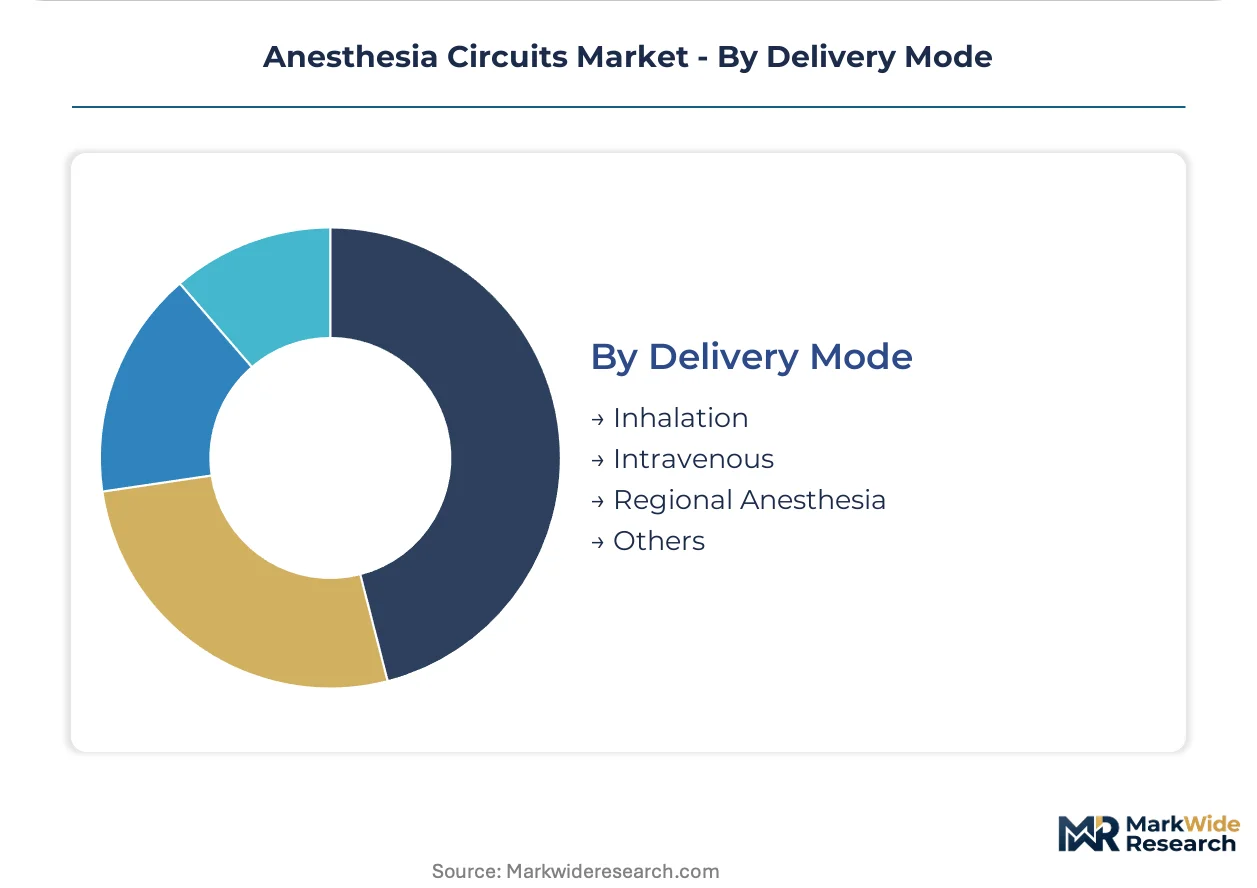
- Inhalation:Volatile anesthetic delivery through precision vaporizer-circuit interfaces demands pressure-stable, leak-resistant tubing. FDA Class II device rules and ISO 10993 biocompatibility requirements are extending clearance timelines for new circuit materials in this category.
- Intravenous:Total intravenous anesthesia reduces circuit complexity to oxygen delivery and ventilation monitoring.
- Regional Anesthesia:Spinal and epidural techniques minimize circuit requirements to supplemental oxygen delivery.
- Others:Combined techniques and emerging delivery modalities.
Inhalation leads by installed base. Regional Anesthesia is climbing the fastest as ultrasound-guided techniques expand procedural volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Class II device rules anchor United States procurement, while China's NMPA enforces GB standards that reshape import eligibility. Germany's EU MDR compliance timelines and India's PLI manufacturing incentives complete the regulatory geography shaping circuit supply chains.
United States
Integrated delivery networks in the Southeast and Midwest control 40-plus facility networks, extracting volume discounts that collapse independent distributor margins. FDA biocompatibility documentation requirements under ISO 10993 extend 510(k) clearance timelines for new circuit materials. Super-regional buying entities in Texas and Florida negotiate directly with manufacturers, bypassing traditional medical-surgical distribution channels.
China
Domestic manufacturers in Shandong and Jiangsu provinces capture share from multinationals unable to navigate NMPA documentation requirements. NMPA enforcement of GB standards for medical polymer tubing tightens import eligibility for foreign-manufactured circuits. Expanded extrusion and molding capacity in the Yangtze River Delta closes supply gaps for corrugated breathing tubes, reducing import dependency.
Germany
Academic medical centers in Berlin and Munich pilot silicone-PVC hybrid tubing for cardiac procedures exceeding six hours. EU MDR clinical evidence requirements extend certification timelines, advantaging incumbents with established technical files. Drägerwerk maintains dedicated manufacturing lines in Lübeck, anchoring European demand through localized production.
India
Domestic manufacturing incentives under the PLI scheme for medical devices could establish South Asian export capacity for corrugated tubing assemblies. Central government production-linked incentives target component fabrication for Middle East and Southeast Asian markets. Maharashtra and Gujarat industrial corridors attract polymer processing investments serving regional anesthesia equipment demand.
United Kingdom
NHS procurement consolidation drives centralized anesthesia supply contracting across England's hospital networks. MHRA alignment with EU MDR transitional provisions maintains extended certification requirements for breathing system components. London and Southeast England health systems prioritize disposable circuit adoption in day surgery units to optimize throughput efficiency.
Anesthesia Circuits Market Competitive Landscape
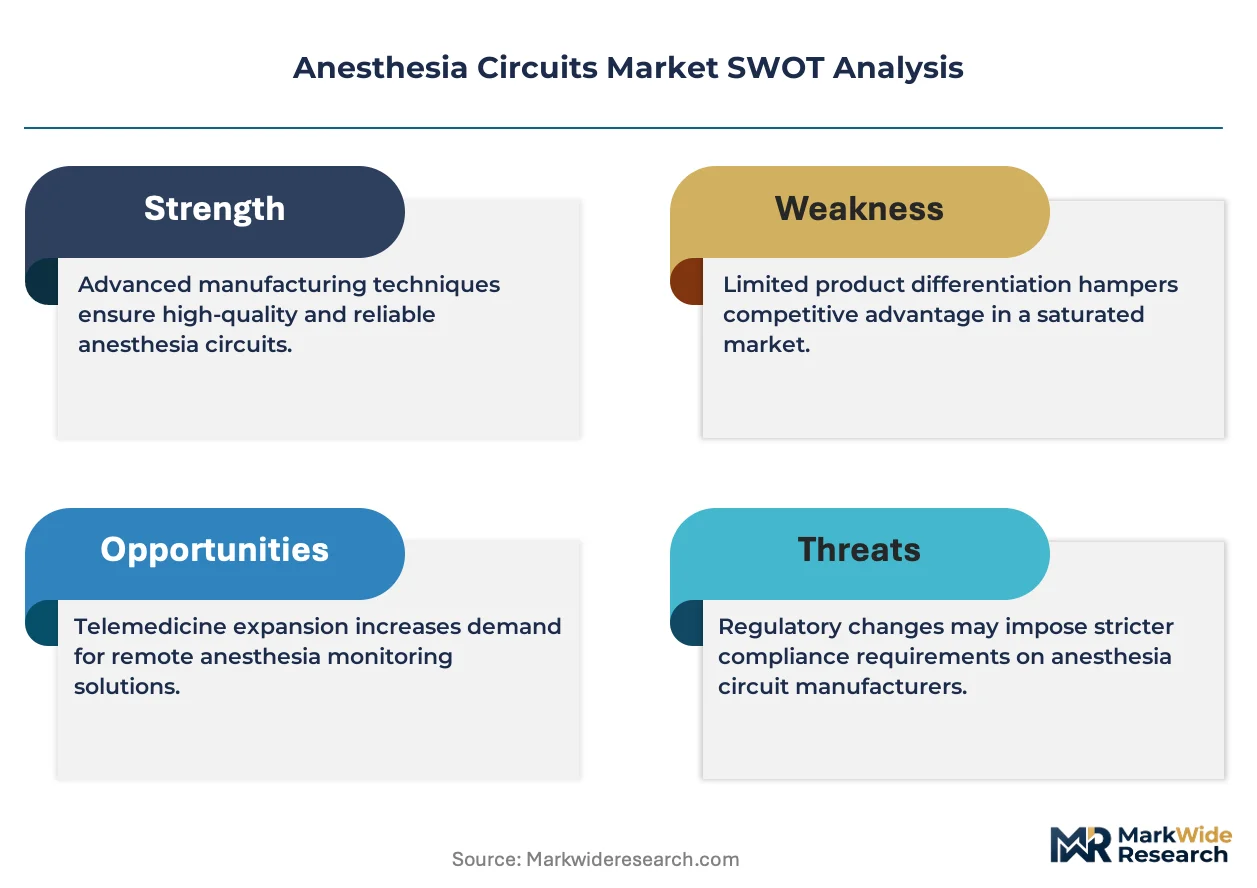
Capability concentration sits with integrated polymer compounders; scale advantage sits with high-volume disposable assemblers. The vendor base separates into three tiers: backward-integrated multinationals controlling resin supply, specialized respiratory platform builders, and regional tubing fabricators. Dominant competitive moves include capacity expansion in China and India, plus strategic partnerships to navigate divergent FDA, EU MDR, and NMPA documentation requirements.
Among diversified medical technology conglomerates, Medtronic plc exemplifies the integrated archetype through captive polymer compounding operations. Drägerwerk AG & Co. KGaA occupies a position within the precision anesthesia equipment tier, anchored by German manufacturing heritage. Fisher & Paykel Healthcare represents the respiratory platform specialization vector, with heated humidification modules that integrate directly with breathing circuit assemblies. These three entities illustrate how competitive positioning stratifies across supply chain control, geographic manufacturing concentration, and therapy system bundling.
| Leading Market Players |
|---|
| Medtronic plc |
| GE HealthCare |
| Drägerwerk AG & Co. KGaA |
| Teleflex Incorporated |
| Fisher & Paykel Healthcare |
| Ambu A/S |
| Becton Dickinson and Company |
| Koninklijke Philips N.V. |
| Getinge AB |
| Others |
Pricing and Supply Chain Analysis
Medical-grade polymer compounding in the United States and Germany concentrates upstream margin capture among backward-integrated multinationals, while downstream assemblers face procurement consolidation that redirects margin pools toward high-volume disposable contracts and attached service revenues.
Pricing Analysis
United States hospital systems pay 15-25% premiums over European procurement for identical circuit specifications due to GPO administrative fees and liability insurance loadings. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 biocompatibility certification tier and after-sales calibration bundling. Cost compression in the standard tier is intensifying because China's domestic manufacturers are undercutting multinational landed costs by 30-40%. Ambulatory surgical centers exhibit the sharpest price sensitivity, while academic medical centers prioritize material performance over unit economics.
Supply Chain Analysis
Contract manufacturing for circuit extrusion and molding concentrates with Foxconn Health Technology, Jabil Healthcare, and regional specialists in Dongguan and Suzhou industrial zones. Geographic supply anchors in China, Germany, and the United States, with raw material dependencies drawing from Saudi petrochemical feedstocks, German silicone monomer production, and Japanese precision molding equipment. Single-source vulnerability runs through medical-grade PVC resin supply where three compounders control 70% of global capacity. Distribution runs through integrated delivery network direct contracts that have displaced 40% of independent distributor volume in the United States Southeast and Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anesthesia circuits function as attach-rate platforms where humidification module subscriptions and capnography sensor replacement cycles expand recurring revenue faster than hardware unit growth alone.
For Market Incumbents: Entrench platform stickiness through heated humidification module integration that locks surgical centers into proprietary circuit architectures. Prioritize FDA 510(k) clearance pipeline expansion for silicone-PVC hybrid materials before EU MDR certification timelines advantage European competitors. Backward integration into polymer compounding secures resin allocation during medical-grade PVC shortages that threaten non-integrated assemblers. For New Entrants and Emerging Players: India's surgical center buildout under the PLI scheme offers white-space penetration where established GPO contracts do not yet dominate procurement. Target freestanding ambulatory facilities in Maharashtra and Gujarat with disposable circuit packs optimized for turnover efficiency rather than competing for hospital IDN contracts. Navigate NMPA GB standard documentation through in-country testing partnerships that multinational exporters have abandoned. For Investors and Strategic Acquirers: Capital is best deployed toward respiratory platform specialists with heated humidification integration capabilities and established hospital system partnerships. Long-term viability centers on therapy system bundling rather than commodity tubing fabrication. Watch for FDA 510(k) clearance acceleration as signal that biocompatibility testing backlogs are clearing, enabling new material entrants to challenge incumbent positions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerates market access for silicone-PVC hybrid circuits in cardiac procedures exceeding six hours. |
| EU MDR Technical File Expansion | Extends certification timelines for breathing system components, advantaging Drägerwerk and established European incumbents. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida negotiate direct contracts that collapse independent distributor margins. |
| Heated Humidification Module Development | Fisher & Paykel's platform integration creates switching costs that protect recurring sensor replacement revenues. |
| Reimbursement Strategy for Capnography | CMS procedural sedation coverage expansion mandates EtCO2 monitoring, standardizing detector attachment points per circuit. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and anesthesia equipment distributors converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement contract awards. Bottom-up unit demand modeling triangulated against top-down healthcare expenditure flows across the analysis window.
Demand-supply balance dynamics anchored the analytical framework, with segmentation across product type, therapy area, end user facility scale, and delivery mode informing elasticity assumptions. CAGRs derived from procedure volume growth, site-of-service migration patterns, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated ISO 10993 biocompatibility testing backlog durations and NMPA GB standard enforcement phases.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated polymer compounders or state-sponsored Chinese manufacturers would shift outcomes beyond modeled ranges. Quarterly review of FDA 510(k) clearance velocity, EU MDR certification completion rates, and hospital IDN merger announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Global Otoscopes Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Global Keratometers Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Medical Polyetheretherketone Market