
 Global Vagus Nerve Stimulation Market | 2026-2036
Global Vagus Nerve Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vagus Nerve Stimulation Market Foresight
The EU Medical Device Regulation is repositioning clinical evidence requirements for implantable neurostimulators, forcing manufacturers to expand post-market surveillance infrastructure. LivaNova PLC leverages its integrated manufacturing footprint across European and North American facilities to sustain compliance leadership. Medtronic anchors its competitive position through deep R&D investment in closed-loop stimulation algorithms. electroCore Inc. specializes in non-invasive transcutaneous platforms that navigate the lower regulatory burden of external devices.
Vagus nerve stimulation delivers targeted electrical impulses to the left cervical vagus nerve through implantable pulse generators or transcutaneous electrodes, operating at frequencies typically between 20-30 Hz with pulse widths of 250-500 microseconds to modulate parasympathetic tone. Implantable devices dominate value capture due to chronic therapy positioning and surgical service bundling, while non-invasive stimulators represent the fastest-expanding segment as psychiatric centers seek drug-free alternatives for patients with treatment-resistant conditions. The therapy area segmentation shows epilepsy maintaining volume leadership while depression applications attract premium pricing in psychiatric center deployments.
FDA breakthrough device designations and EMA conditional approval pathways shape competitive timelines for novel entrants, with ISO 14155 clinical investigation standards governing trial conduct across major markets. Japan's PMDA sakigake framework offers accelerated review for vagus nerve stimulation innovations targeting unmet neurological needs. Stakeholders must monitor evolving reimbursement decisions by CMS and Germany's G-BA, as coverage determinations for new indications will dictate commercial scalability faster than regulatory clearance alone.
Market Dynamics
The Global Vagus Nerve Stimulation Market is being fundamentally restructured by the FDA's breakthrough device designation pathway, which compresses commercialization timelines for novel neurostimulation interfaces while simultaneously elevating the clinical evidence burden required for market access.
Growth Catalysts
- Japan's PMDA sakigake framework:This accelerated review mechanism targets unmet neurological needs and reduces time-to-market for vagus nerve stimulation innovators addressing treatment-resistant depression.
- Neurology clinics:Psychiatric centers in Germany and the United States are expanding non-invasive stimulator adoption as drug-free alternatives for patients who have failed multiple pharmacological interventions.
- Closed-loop algorithms:Advances in adaptive stimulation protocols enable real-time autonomic response modulation, improving therapeutic efficacy for epilepsy patients beyond fixed-parameter devices.
Market Restraints
- EU MDR post-market surveillance:The Medical Device Regulation mandates expanded clinical evidence requirements for implantable neurostimulators, forcing manufacturers to rebuild compliance infrastructure.
- Precious metal electrode costs:Iridium and platinum price volatility directly impacts pulse generator manufacturing economics, compressing margins on implantable systems.
- Surgical service bundling:Implantable device value capture depends on specialized neurosurgical capacity concentrated in tertiary medical centers across the United States, Germany, and Japan.
Strategic Opportunities
- Pediatric epilepsy in India:The country's national pharmaceutical regulator is streamlining neurostimulation approvals for drug-resistant seizure disorders in adolescent populations.
- Transcutaneous auricular platforms:Convergence of wearable biosensors with non-invasive vagus nerve interfaces creates ambulatory monitoring-stimulation hybrid devices for anxiety management.
- CMS coverage expansion:Reimbursement determinations for new psychiatric indications will unlock commercial scalability faster than regulatory clearance alone in United States psychiatric centers.
Industry Challenges
- ISO 14155 trial conduct:Multi-site clinical investigations across European and North American facilities require harmonized data collection protocols that extend development timelines.
- Biocompatibility certification:Implantable pulse generators must demonstrate long-term tissue compatibility under IEC 60601-1 electrical safety standards, creating regulatory bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vagus Nerve Stimulation Market |
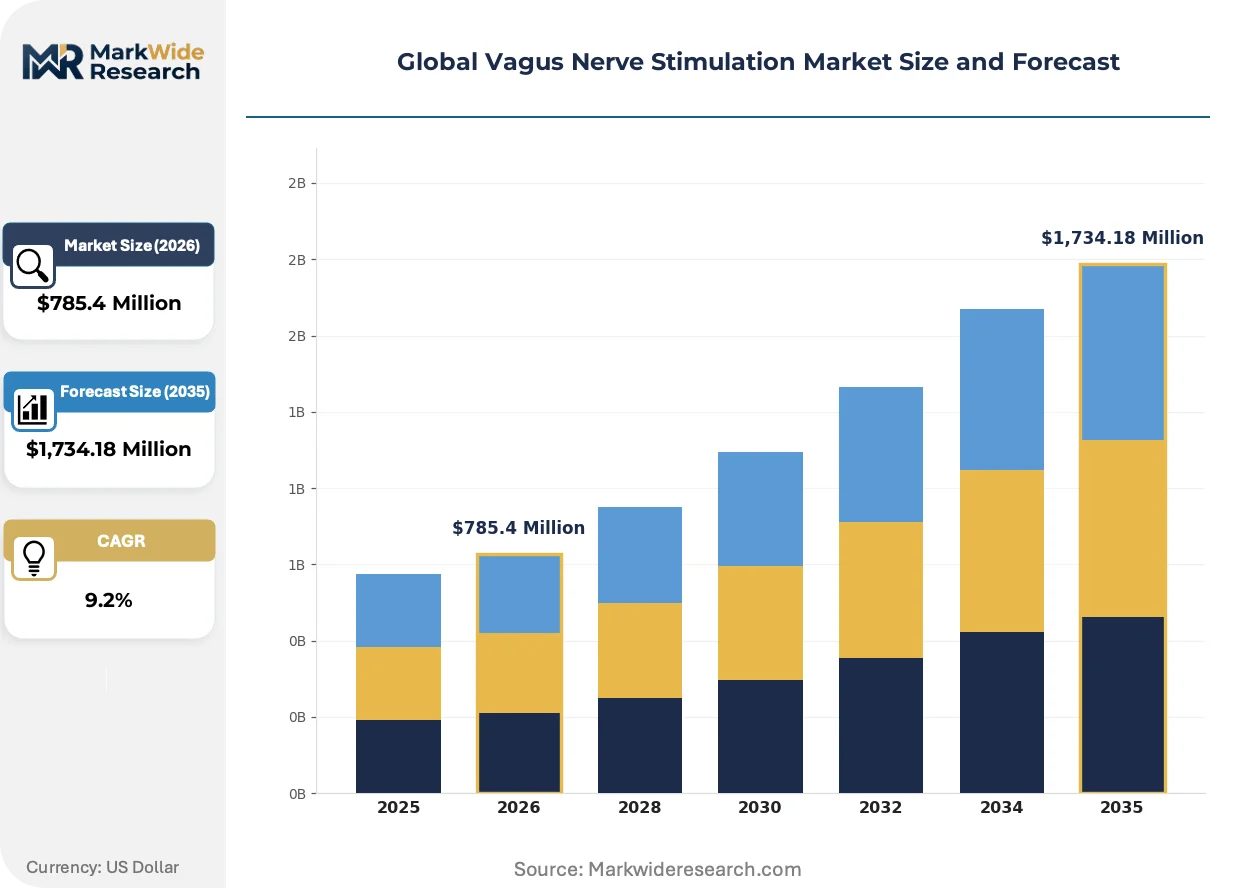
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,734.18 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, Non-Invasive Stimulators, Transcutaneous Devices, External Pulse Generators Therapy Area: Epilepsy, Depression, Migraine, Obesity, Heart Failure, Anxiety Disorders End User: Neurology Clinics, Psychiatric Centers, Cardiovascular Units, Pain Management Facilities Deployment: Hospital-Based, Outpatient Clinics, Homecare Settings, Research Institutions |
| Companies Covered | NeuroPace, SetPoint Medical, LivaNova PLC, Parasym Ltd, tVNS Technologies, Medtronic, Boston Scientific, BioControl Medical, electroCore Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vagus Nerve Stimulation Market Shifts & Advancements
Neurostimulation technology is undergoing a platform shift from open-loop to adaptive systems, while regulatory frameworks across major markets simultaneously tighten evidence standards and accelerate review pathways for breakthrough-designated devices.
Closed-loop vagus nerve stimulation is electrifying therapeutic precision in epilepsy management. These systems continuously monitor cardiac and neural biomarkers to automatically adjust stimulation parameters. Tertiary epilepsy centers in the United States and Germany are adopting these platforms for patients with refractory seizure disorders. The technology is electrifying competitive differentiation by enabling outcome-based contracting models that tie reimbursement to seizure reduction metrics.
EU Medical Device Regulation repositioning is reshaping post-market obligations for implantable neurostimulators. The framework now requires proactive safety surveillance and periodic clinical updates beyond initial CE marking. Manufacturers serving European psychiatric and neurology clinics must maintain dedicated regulatory affairs teams in Brussels and national competent authorities. Implantable device segments face the steepest compliance cost escalation, while external transcutaneous platforms navigate lighter oversight.
Psychiatric procurement patterns are fragmenting across hospital-owned integrated delivery networks and independent specialty clinics. United States psychiatric centers increasingly unbundle device acquisition from surgical implantation services, pressuring traditional bundled pricing models. Independent neurology clinics in Germany and Japan are forming purchasing consortia to negotiate direct manufacturer relationships. This shift is most visible in depression indication deployments where non-invasive alternatives enable outpatient-based therapy without surgical infrastructure.
Global Vagus Nerve Stimulation Market Segmentation
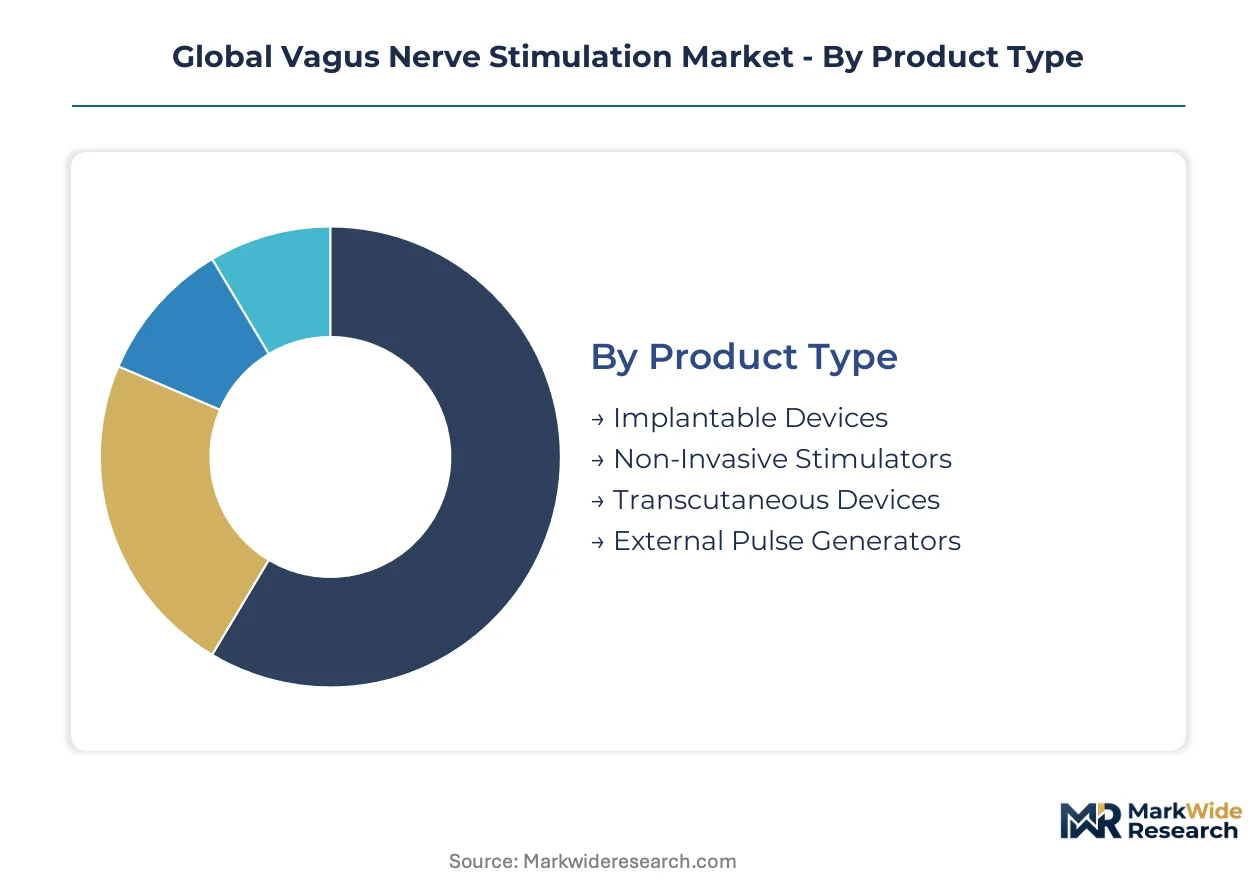
Segmentation in vagus nerve stimulation reflects divergent clinical workflows and reimbursement pathways. Implantable systems require surgical infrastructure and chronic disease management protocols, while non-invasive alternatives target outpatient psychiatric expansion.
Product Type:
Buyers differentiate primarily by regulatory burden and capital commitment required for therapy initiation.
- Implantable Devices:These systems embed pulse generators subcutaneously with leads tunneling to the left cervical vagus nerve, typically operating at 20-30 Hz with 250-500 microsecond pulse widths. Demand concentrates in tertiary epilepsy centers across the United States and Germany where surgical service bundling captures lifetime therapy value. FDA breakthrough designations and EMA conditional approvals accelerate commercial timelines for next-generation closed-loop variants.
- Non-Invasive Stimulators:Transcutaneous platforms deliver electrical impulses through surface electrodes positioned at cervical or auricular sites without surgical intervention. Psychiatric centers in Japan and the United States are expanding adoption for treatment-resistant depression patients who have failed multiple pharmacological protocols. The lower regulatory burden of external devices enables faster indication expansion.
- Transcutaneous Devices:Specialized auricular interfaces targeting the cymba concha region modulate parasympathetic tone through cutaneous branches of the vagus nerve.
- External Pulse Generators:Portable stimulation units with programmable parameter sets support home-based therapy protocols under remote clinical supervision.
Implantable devices lead volumes today; non-invasive stimulators are gaining share fastest.
Therapy Area:
Reimbursement coverage determines commercial scalability more than clinical efficacy alone in this category.
- Epilepsy:The original approved indication maintains volume leadership through established CMS and G-BA coverage frameworks. Tertiary centers in the United States, Germany, and Japan anchor implantable device penetration for drug-resistant seizure disorders. Closed-loop algorithms now enable adaptive stimulation based on cardiac biomarker detection.
- Depression:Treatment-resistant depression applications attract premium pricing in psychiatric center deployments where multiple pharmacological failures create urgency for neuromodulation alternatives. Japan's PMDA sakigake framework accelerates review for novel vagus nerve interfaces targeting this indication.
- Migraine:Non-invasive transcutaneous platforms show promise for prophylactic management in outpatient headache clinics.
- Obesity:Metabolic modulation through vagal afferent signaling targets bariatric surgery alternatives.
- Heart Failure:Cardiac autonomic regulation applications remain investigational with pivotal trials ongoing under FDA breakthrough pathways.
- Anxiety Disorders:Generalized anxiety and PTSD protocols leverage wearable-integrated auricular stimulation for ambulatory deployment.
Epilepsy anchors reimbursement-covered volumes; depression applications command the steepest pricing premiums.
End User:
Procurement authority and capital allocation models vary sharply across these clinical settings.
- Neurology Clinics:Specialized epilepsy centers concentrate implantable device volumes through surgeon-led decision-making and bundled service contracts. These facilities in the United States and Germany maintain dedicated vagus nerve stimulation programs with neurosurgical capacity.
- Psychiatric Centers:Depression and anxiety applications drive non-invasive stimulator adoption as drug-free alternatives. United States psychiatric centers increasingly unbundle device acquisition from clinical services, pressuring traditional pricing models.
- Cardiovascular Units:Heart failure applications require cardiology-electrophysiology collaboration for autonomic modulation protocols.
- Pain Management Facilities:Chronic pain indications leverage transcutaneous platforms for migraine and neuropathic conditions.
Neurology clinics dominate implantable volumes; psychiatric centers are expanding most quickly for non-invasive alternatives.
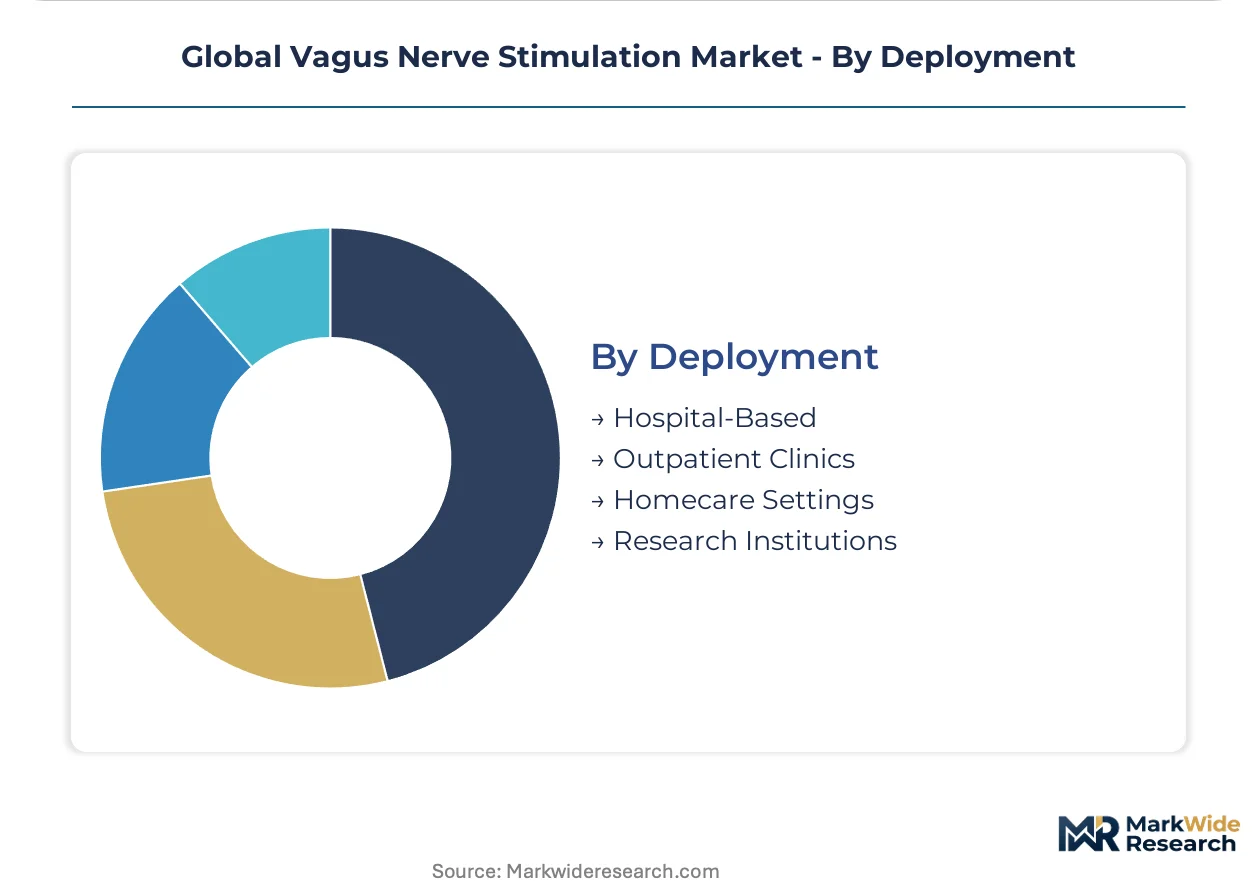
Deployment:
Site-of-care economics and regulatory classification shape manufacturer go-to-market strategies.
- Hospital-Based:Tertiary medical centers in the United States, Germany, and Japan concentrate surgical implantation capacity for pulse generator procedures. These facilities capture bundled reimbursement covering device, implantation, and follow-up programming.
- Outpatient Clinics:Independent neurology and psychiatric clinics in Germany and Japan are forming purchasing consortia to negotiate direct manufacturer relationships for non-invasive platforms.
- Homecare Settings:Transcutaneous devices with simplified user interfaces enable patient-administered therapy under remote clinical monitoring protocols.
- Research Institutions:Academic medical centers conduct pivotal trials under ISO 14155 standards for novel indications and adaptive algorithm validation.
Hospital-based deployment leads value capture today; outpatient clinics are climbing the fastest as non-invasive alternatives proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurosurgical talent concentrates in tertiary medical centers across the United States, Germany, and Japan, anchoring implantable device adoption while psychiatric specialists in these markets drive non-invasive platform expansion.
United States
CMS reimbursement frameworks for treatment-resistant depression and epilepsy sustain hospital-based neurostimulation volumes. FDA breakthrough device designations compress commercialization timelines for closed-loop vagus nerve interfaces. The Cleveland Clinic and Mayo Clinic anchor surgical implantation capacity in the Midwest, while Boston's academic medical centers conduct pivotal trials under ISO 14155 standards.
Germany
G-BA coverage determinations for neurostimulation in psychiatric indications create predictable procurement pathways for university hospitals. EU Medical Device Regulation mandates expanded post-market surveillance for implantable pulse generators, elevating compliance costs for manufacturers serving Bavarian and North Rhine-Westphalian neurology clinics. Heidelberg and Berlin concentrate epilepsy center density.
Japan
PMDA's sakigake accelerated review framework targets unmet neurological needs, reducing time-to-market for novel vagus nerve stimulation innovations. Treatment-resistant depression applications attract premium pricing in Tokyo and Osaka psychiatric centers. The Ministry of Health, Labour and Welfare's reimbursement listings for external neurostimulators enable outpatient-based therapy expansion.
United Kingdom
NICE technology appraisals for implantable neurostimulators shape NHS commissioning decisions in epilepsy management. MHRA post-Brexit regulatory autonomy permits tailored pathways for transcutaneous vagus nerve devices. London's National Hospital for Neurology and Neurosurgery and Manchester's Salford Royal anchor specialized surgical capacity.
India
CDSCO streamlining of neurostimulation approvals for pediatric drug-resistant epilepsy creates access pathways in adolescent populations. Central Drugs Standard Control Organization regulatory harmonization with ISO standards reduces trial duplication for multinational manufacturers. Mumbai and Delhi neurology centers concentrate implantable device expertise while Bengaluru's medical device clusters support component sourcing.
Global Vagus Nerve Stimulation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the vagus nerve stimulation landscape, creating a tiered structure where scale-driven medical technology majors anchor implantable segments and agile external device developers capture psychiatric outpatient expansion. Three strategic archetypes dominate: integrated neuromodulation platforms with closed-loop algorithm capabilities, non-invasive transcutaneous specialists navigating lighter regulatory burdens, and emerging bioelectronic medicine ventures targeting novel autonomic indications. Competitive intensity concentrates on M&A activity securing neurosurgical service networks and strategic partnerships with academic medical centers for pivotal trial execution.
Among diversified medical technology majors, Medtronic and Boston Scientific occupy positions representing scale-driven integrated platform strategies, while LivaNova PLC exemplifies focused neuromodulation specialization with European manufacturing footprint advantages. electroCore Inc. sits within the non-invasive specialist tier, leveraging external device regulatory pathways to penetrate psychiatric center procurement channels. These three anchors illustrate the competitive divergence between implantable surgical bundling and outpatient-accessible transcutaneous alternatives.
| Leading Market Players |
|---|
| NeuroPace |
| SetPoint Medical |
| LivaNova PLC |
| Parasym Ltd |
| tVNS Technologies |
| Medtronic |
| Boston Scientific |
| BioControl Medical |
| electroCore Inc. |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance mandates gate qualified supply access for implantable pulse generators while simultaneously segmenting pricing tiers by clinical evidence burden. Manufacturers bearing expanded compliance infrastructure costs command premium positioning in tertiary epilepsy centers across the United States and Germany, whereas external transcutaneous platforms navigate lighter oversight to capture outpatient psychiatric expansion at compressed price points.
Pricing Analysis
Bundled surgical service contracts versus unbundled device acquisition splits pricing power between hospital-based neurology clinics and independent psychiatric centers. Three-tier pricing structure across premium closed-loop systems, standard implantable generators, and economy transcutaneous units differentiates by algorithm sophistication and regulatory certification tier. Pricing pressure stems from precious metal electrode cost volatility in iridium and platinum feedstocks. Psychiatric centers exhibit highest price sensitivity as they unbundle services and form purchasing consortia, while tertiary epilepsy centers absorb premium tiers for adaptive stimulation capabilities.
Supply Chain Analysis
Direct-to-hospital contracting channels handle implantable device demand from specialized neurosurgical centers, while distributor networks serve outpatient clinic procurement for non-invasive platforms. Manufacturing concentrates in the United States, Germany, and Switzerland for pulse generator assembly, with electrode component sourcing from South African platinum refiners and Russian iridium suppliers. Supply chain risk centers on single-source vulnerability for biocompatible electrode materials. Distribution runs through GPO contracts in United States hospital systems and direct manufacturer relationships in German purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where closed-loop algorithm differentiation and reimbursement coverage depth now outweigh raw volume capture. Demand is shifting toward premium adaptive systems that enable outcome-based contracting in epilepsy management.
For Market Incumbents: Extend closed-loop algorithm R&D investment to defend against non-invasive platform encroachment in psychiatric indications. Secure neurosurgical service network partnerships to maintain bundled pricing power against unbundling pressure from independent clinics. Prioritize EU MDR compliance infrastructure as a competitive moat that elevates rival cost structures. For New Entrants and Emerging Players: Digital health platform integration offers a lower-capital route to ambulatory anxiety management applications. Target transcutaneous auricular platforms for United States psychiatric center procurement channels where surgical infrastructure gaps create white space. Pursue FDA breakthrough designation to compress commercialization timelines against entrenched implantable players. For Investors and Strategic Acquirers: Valuations sit cheapest among non-invasive specialists with psychiatric center revenue concentration and pending regulatory expansions. The five-to-ten year viability window favors platforms with adaptive algorithm capabilities and multiple indication pipelines. Watch CMS coverage determinations for novel psychiatric indications as the primary inflection signal for commercial scalability acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pathway | Accelerates commercial timelines for closed-loop vagus nerve interfaces targeting treatment-resistant depression. |
| Hospital System Partnership | Secures bundled surgical service contracts with Cleveland Clinic and Mayo Clinic epilepsy centers. |
| CE Marking Pathway | Opens EU market access under MDR post-market surveillance requirements for implantable pulse generators. |
| Software Companion Development | Enables remote parameter adjustment and patient monitoring for home-based transcutaneous therapy protocols. |
| Reimbursement Strategy | Aligns clinical evidence generation with CMS and G-BA coverage determination timelines for new indications. |
Research Methodology
Bottom-up neurology clinic and psychiatric center demand modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at device manufacturers were cross-validated against secondary sources including FDA 510(k) filings, EMA CE marking databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Triangulation across these data streams isolates true installed base from channel inventory fluctuations.
Historical trendline analysis of implantable versus non-invasive device volumes informs the projection framework across the analysis window. Segmentation dimensions include product type, therapy area, end-user setting, and deployment site-of-care. CAGRs derive from curve-fitting techniques applied to regulatory approval timelines and reimbursement coverage expansion patterns. Forecast inputs incorporate PMDA sakigake review velocity and EU MDR compliance cost trajectories as industry-specific modifiers.
The model assumes a particular technology adoption path; alternative pathways for closed-loop adaptive algorithms would alter the outlook if cardiac biomarker detection accuracy fails to meet pivotal trial endpoints. Forecasts reflect assumptions about CMS coverage determination timing for depression indications and precious metal electrode cost stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Implantable Drug Delivery Devices Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market