
 Endometrial Ablation Market | 2026-2036
Endometrial Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Endometrial Ablation Market Intelligence
FDA 510(k) clearance timelines are rebalancing the cost-of-entry calculus for device startups seeking commercial traction. Medtronic leverages its interventional surgery infrastructure to sustain broad hospital access across North American markets. Hologic, Inc. anchors its position through dedicated women's health R&D pipelines and direct-to-clinic service models. Boston Scientific Corporation differentiates via integrated visualization platforms that pair ablation delivery with real-time hysteroscopic guidance.
Endometrial ablation encompasses minimally invasive procedures that destroy the uterine lining using thermal, radiofrequency, cryogenic, or laser energy modalities, typically performed under local or general anesthesia with operative times under thirty minutes. The technique eliminates or reduces heavy menstrual bleeding in premenopausal patients who have completed childbearing, offering hysterectomy-sparing alternatives with shorter recovery trajectories. Radiofrequency ablation systems command the largest installed base among product categories, while cryoablation platforms attract premium placement in outpatient settings due to reduced anesthesia requirements. Ambulatory surgery centers represent the fastest-expanding end-user channel as payors and patients prioritize same-day discharge protocols over traditional hospital admission.
FDA premarket notification requirements, CE marking under the EU Medical Device Regulation, and ISO 13485 quality management standards collectively shape device design, clinical evidence thresholds, and market access pathways across developed economies. The EU MDR transition has extended conformity assessment durations, prompting manufacturers to front-load clinical data collection and notified body engagement. Stakeholders must monitor reimbursement parity between office-based and facility-based ablation settings, as site-of-service payment differentials will determine capital deployment priorities and technology platform selection.
Market Dynamics
Ambulatory surgery centers are capturing procedure volume from hospital inpatient settings as payors harden site-of-service differentials and patients prioritize same-day discharge protocols.
Growth Catalysts
- Radiofrequency platform maturation:Second-generation devices reduce operative time below twenty minutes, expanding addressable patient pools beyond traditional surgical candidates.
- FDA 510(k) pathway efficiency:Predicate device reliance for next-generation ablation systems compresses premarket notification timelines versus de novo submissions.
- Gynecology clinic network consolidation:Multi-site specialty groups in the United States achieve capital equipment economies of scale that independent practices cannot replicate.
Market Restraints
- Reimbursement compression:CMS facility fee cuts for hospital-based ablation procedures narrow margin structures for integrated delivery systems.
- Input concentration:Specialized radiofrequency generators and disposable electrode arrays depend on single-source suppliers in German precision electronics clusters.
- Technical ceiling:Existing thermal modalities cannot treat submucosal fibroids exceeding three centimeters, limiting addressable pathology.
Strategic Opportunities
- Office-based procedure migration:Cryoablation platforms with local anesthesia protocols unlock standalone clinic channels previously requiring ASC affiliation.
- EU MDR transitional relief:Extended conformity assessment deadlines allow manufacturers to front-load clinical data collection for legacy device recertification.
- Hysteroscopic integration:Combined visualization-ablation systems address unmet needs in complex cavity anatomy cases.
Industry Challenges
- Specialized electrosurgery training:Radiofrequency device operation requires gynecologic surgeons to complete manufacturer-specific credentialing modules.
- Notified body queue congestion:EU MDR technical documentation reviews extend beyond twenty-four months for Class IIb active therapeutic devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endometrial Ablation Market |
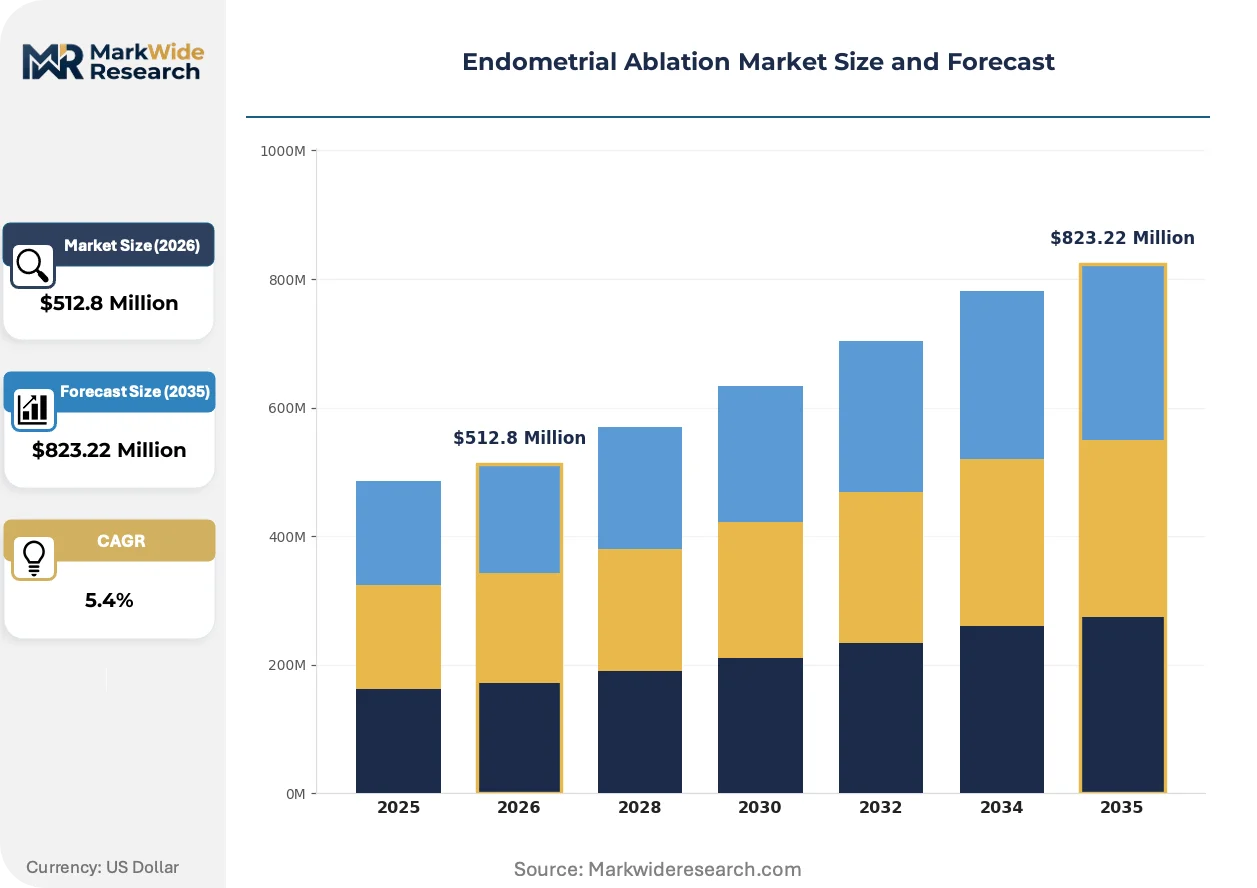
| Market Size in 2026 | $512.8 Million |
| Market Size in 2035 | $823.22 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Cryoablation, Laser Ablation, Thermal Ablation End User: Hospitals, Surgical Centers, Gynecology Clinics, Ambulatory Surgery Centers Technology: Electrosurgery, Microwave Ablation, Hydrothermal Ablation, Bipolar Delivery Application: Heavy Menstrual Bleeding, Endometrial Hyperplasia, Fibroids Treatment, Reproductive Health |
| Companies Covered | Medtronic, Hologic, Inc., Boston Scientific Corporation, Olympus Corporation, Johnson & Johnson Services Inc., CooperSurgical Inc., Minerva Surgical, Inc., Richard Wolf GmbH, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endometrial Ablation Market Strategic Shifts & Innovations
Device architectures are converging around single-procedure efficiency, real-time tissue feedback, and reduced anesthesia requirements that reshape capital deployment priorities across care settings.
Next-generation radiofrequency systems is unifying impedance-sensing algorithms with automated energy modulation. Ambulatory surgery centers in the United States are adopting these platforms at replacement-cycle velocity. The technology is unifying operative consistency across variable operator experience levels, compressing training overhead and expanding eligible provider pools.
EU MDR Article 52 clinical evaluation requirements are extending post-market surveillance obligations for active therapeutic devices. Manufacturers must now generate periodic safety update reports with registry-derived real-world evidence. Cryoablation platforms face heightened scrutiny due to their novel mechanism classification, prompting front-loaded clinical trial investment.
Patients are demanding hysterectomy-sparing alternatives with documented fertility preservation outcomes. Direct-to-consumer education channels are displacing traditional physician-referral pathways for initial consultation. This behavioral pivot concentrates in United States metropolitan markets with dense gynecology clinic network presence.
Endometrial Ablation Market Segmentation
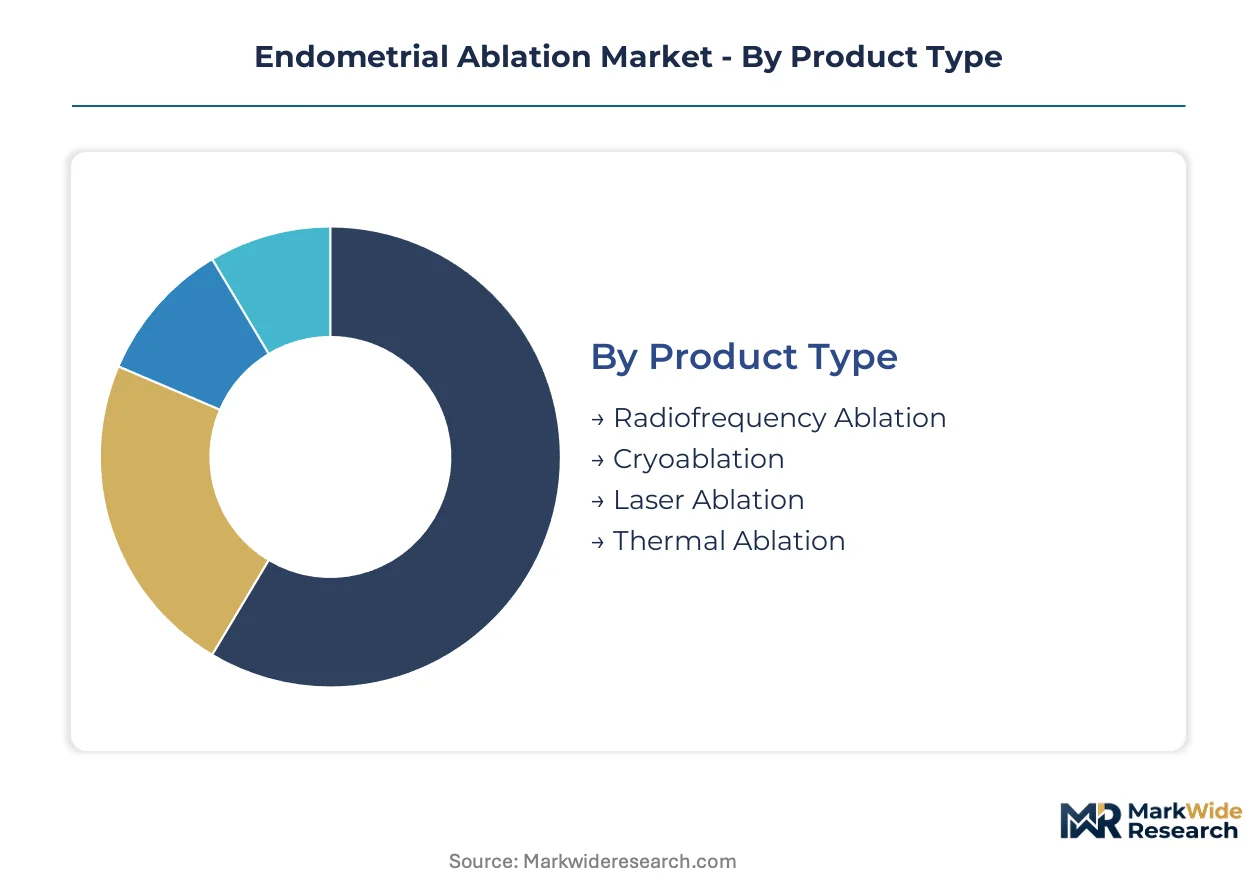
Endometrial ablation device purchasing follows distinct decision logics across care settings. Product selection hinges on anesthesia protocols, capital budgets, and procedure volume economics. Understanding these segment boundaries clarifies where manufacturers must configure differentiated go-to-market approaches.
Product Type:
Capital allocation priorities diverge sharply between high-volume hospital systems and resource-constrained outpatient clinics.
- Radiofrequency Ablation:Impedance-sensing electrode arrays deliver controlled thermal energy across the endometrial surface. United States hospital systems concentrate procurement here due to established surgeon training pathways and broad payer coverage. Second-generation platforms compress operative time below twenty minutes, expanding eligible patient pools.
- Cryoablation:Nitrous oxide-based cooling probes create precise tissue necrosis without general anesthesia requirements. Ambulatory surgery centers in metropolitan United States markets favor this modality for same-day discharge protocols. Reduced sedation infrastructure needs lower per-procedure fixed costs.
- Laser Ablation:Nd:YAG or diode laser systems target discrete endometrial lesions with minimal thermal spread. Specialized academic medical centers maintain limited installed bases for complex cavity anatomy cases.
- Thermal Ablation:Heated fluid balloon systems distribute uniform thermal energy without hysteroscopic guidance. Smaller gynecology clinics select this technology for simplified operator training curves.
Radiofrequency Ablation leads on scale; Cryoablation leads on momentum.
End User:
Site-of-service payment differentials are rebalancing procedure volume across facility types.
- Hospitals:Inpatient surgical departments maintain ablation capacity within broader gynecology service lines. Integrated delivery systems in the United States leverage these settings for complex cases requiring concurrent hysteroscopic intervention.
- Surgical Centers:Multi-specialty facilities allocate dedicated block time for high-volume ablation specialists. Medicare facility fee structures reward efficient throughput here.
- Gynecology Clinics:Standalone women's health practices pursue office-based migration to capture professional fee revenue directly. Cryoablation platforms with local anesthesia protocols unlock this channel.
- Ambulatory Surgery Centers:Purpose-built outpatient facilities optimize discharge logistics and supply chain standardization. United States payor network contracts increasingly steer volume to these settings.
Hospitals retain the deepest case complexity; Ambulatory Surgery Centers capture the steepest expansion trajectory.
Technology:
Energy delivery mechanisms determine capital equipment requirements and disposable revenue models.
- Electrosurgery:Monopolar and bipolar radiofrequency generators constitute the dominant installed base. German precision electronics clusters supply specialized impedance-monitoring components.
- Microwave Ablation:Electromagnetic field heating achieves rapid tissue temperatures with minimal char formation. Limited commercial penetration reflects higher capital costs versus radiofrequency alternatives.
- Hydrothermal Ablation:Circulating heated saline conforms to irregular cavity geometries without direct tissue contact. Simplified device architecture reduces per-procedure supply expenses.
- Bipolar Delivery:Confined current pathways minimize thermal spread to adjacent structures. FDA 510(k) predicate pathways accelerate clearance for iterative device improvements.
Electrosurgery commands the largest installed footprint; Bipolar Delivery offers the clearest regulatory efficiency.
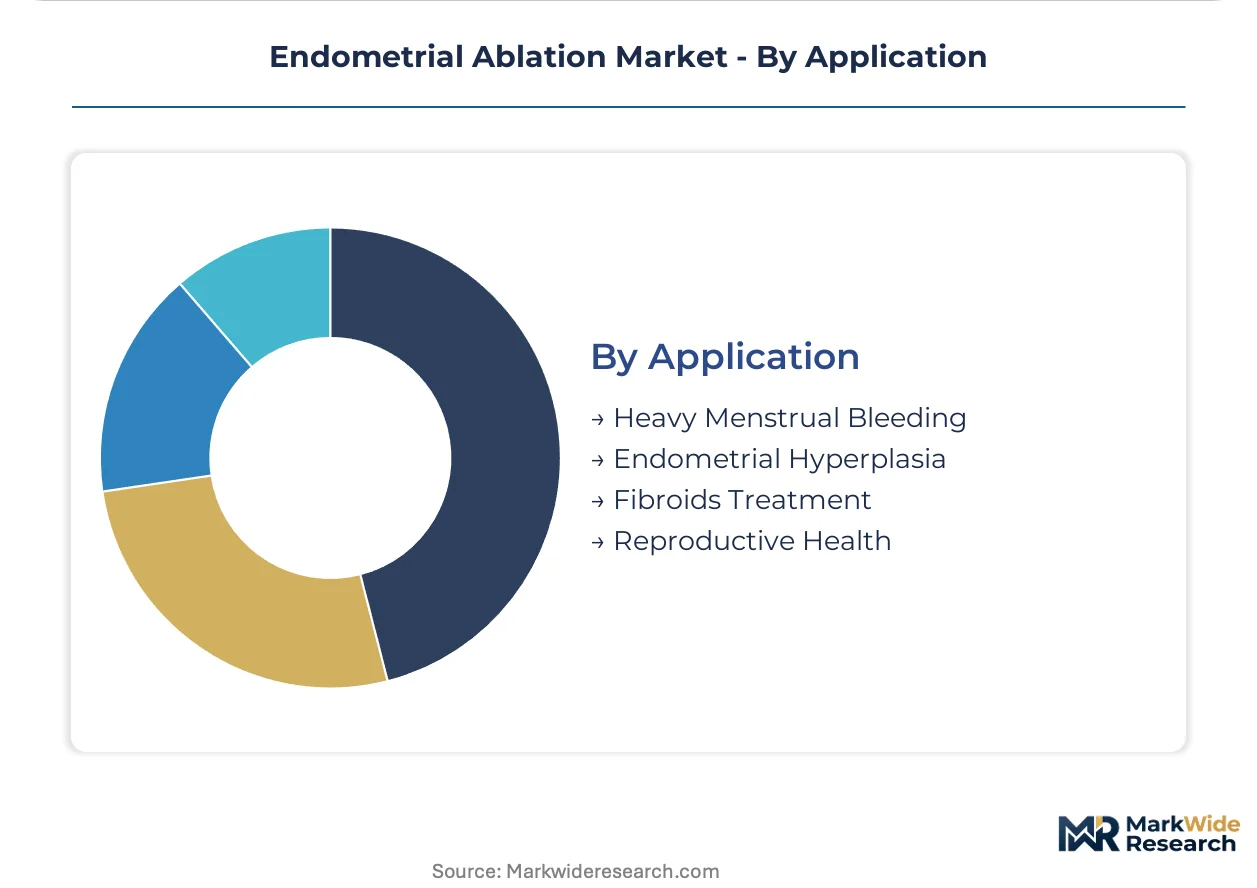
Application:
Clinical indication severity dictates anesthesia requirements and setting selection.
- Heavy Menstrual Bleeding:Primary indication driving procedure volume among premenopausal patients who have completed childbearing. United States gynecology clinic networks concentrate marketing investment here.
- Endometrial Hyperplasia:Precancerous cellular changes require histologic confirmation before ablation candidacy. Academic medical centers manage these cases with integrated pathology workflows.
- Fibroids Treatment:Submucosal lesions under three centimeters respond to thermal ablation; larger fibroids require alternative intervention. This constraint limits addressable pathology.
- Reproductive Health:Fertility-sparing objectives demand conservative tissue destruction parameters. Specialized centers document pregnancy outcomes for this patient segment.
Heavy Menstrual Bleeding generates the highest procedure count; Fibroids Treatment presents the largest unmet need ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endometrial ablation technology originated in United States academic medical centers during the 1980s, with radiofrequency and thermal balloon systems first commercialized through Boston and Minneapolis-based device clusters before European and Asia-Pacific adoption.
United States
Gynecology clinic network consolidation and ambulatory surgery center expansion drive procedure volume concentration. FDA 510(k) clearance pathways compress premarket timelines for next-generation radiofrequency platforms. Minneapolis and Boston metropolitan areas host the dominant device engineering clusters, with surgeon training programs anchored at Mayo Clinic and Massachusetts General Hospital.
Germany
Precision electronics manufacturing for impedance-monitoring components supplies global radiofrequency generator assembly. EU MDR Article 52 conformity assessment requirements extend technical documentation review timelines for Class IIb active therapeutic devices. Stuttgart and Munich industrial corridors concentrate specialized electrosurgical component fabrication serving device OEMs.
United Kingdom
NHS Integrated Care Systems steer heavy menstrual bleeding referrals toward community gynecology hubs. NICE clinical guidelines influence ablation candidacy criteria and technology assessment protocols. London and Manchester metropolitan networks concentrate specialist training capacity for hysteroscopic-guided procedures.
Japan
Aging demographic profiles expand premenopausal patient pools seeking hysterectomy-sparing interventions. PMDA premarket approval pathways require domestic clinical trial data for novel energy delivery systems. Tokyo-Osaka medical device corridors concentrate distribution partnerships linking manufacturers to university hospital procurement channels.
Australia
Private health insurance coverage parity between hospital and day-surgery settings accelerates outpatient migration. TGA conformity assessment leverages European notified body reports under mutual recognition agreements. Sydney and Melbourne gynecology practice networks drive capital equipment replacement cycles for second-generation platforms.
Endometrial Ablation Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with interventional surgery infrastructure. Three to four multinational device manufacturers command installed base dominance through integrated delivery system contracts. Strategic archetypes separate into broad surgical portfolio holders, women's health specialists, and visualization-integrated platform developers. Consolidation activity concentrates on ambulatory surgery center channel access and cryoablation technology licensing.
Within the diversified surgical technology tier, Medtronic and Boston Scientific Corporation occupy positions shaped by interventional procedure infrastructure and visualization platform integration respectively. Hologic, Inc. anchors the women's health specialist archetype through dedicated R&D pipelines. Richard Wolf GmbH exemplifies the precision electrosurgical equipment segment rooted in German engineering clusters.
| Leading Market Players |
|---|
| Medtronic |
| Hologic, Inc. |
| Boston Scientific Corporation |
| Olympus Corporation |
| Johnson & Johnson Services Inc. |
| CooperSurgical Inc. |
| Minerva Surgical, Inc. |
| Richard Wolf GmbH |
| AngioDynamics |
| Others |
Cost & Logistics Intelligence
Specialized electrosurgical engineering talent concentrated in Stuttgart and Munich industrial corridors feeds directly into German precision electronics clusters, with labor-cost differentials between Bavarian manufacturing zones and offshore assembly locations driving three-tier spreads across premium radiofrequency platforms, mid-tier thermal balloon systems, and economy hydrothermal alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with FDA 510(k) predicate pathway efficiency and ISO 13485 certification tier serving as primary differentiation drivers alongside surgeon training bundling. Pricing pressure stems from CMS facility fee compression narrowing hospital-based procedure margins. Ambulatory surgery centers exhibit highest price sensitivity due to fixed-cost absorption constraints, while integrated delivery systems leverage volume scale for least sensitivity.
Supply Chain Analysis
Specialized radiofrequency generators and disposable electrode arrays rest on single-source suppliers in German precision electronics clusters, with nitrous oxide cooling systems drawing from Belgian and French industrial gas networks. Impedance-monitoring chipsets, thermal balloon catheters, and cryogenic probe assemblies constitute critical input dependencies. Single-source vulnerability in Stuttgart-area component fabrication poses structural risk. Distribution runs through GPO contracts and direct-to-clinic service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endometrial ablation market reads as a late-cycle quality story where patient demand is concentrating toward hysterectomy-sparing alternatives with documented fertility preservation outcomes and reduced anesthesia protocols.
For Market Incumbents: Anticipate cryoablation platform licensing from emerging entrants as radiofrequency market saturation intensifies, and anchor defensive positioning through backward integration into impedance-monitoring chipset supply. Channel control via exclusive ambulatory surgery center block-time contracts offers margin protection against reimbursement compression. For New Entrants and Emerging Players: Begin with office-based gynecology clinic migration as the most penetrable channel, where cryoablation platforms with local anesthesia protocols unlock standalone practice revenue previously requiring ASC affiliation. Target metropolitan United States markets with dense women's health network presence. Direct-to-consumer education partnerships bypass established referral gatekeeping. For Investors and Strategic Acquirers: Diversified surgical technology conglomerates with interventional infrastructure are the most active acquirers in this space, seeking ambulatory surgery center channel access and visualization-integrated platform capabilities. Long-term viability centers on hysteroscopic integration and real-time tissue feedback differentiation. Watch FDA 510(k) clearance velocity for next-generation platforms as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device reliance compresses premarket timelines for iterative radiofrequency improvements. |
| CE Marking Pathway | EU MDR Article 52 conformity assessment extends technical documentation review for Class IIb devices. |
| Hospital System Partnership | Integrated delivery system contracts secure installed base dominance through exclusive procurement. |
| Software Companion Development | Impedance-sensing algorithms with automated energy modulation unify operative consistency. |
| Reimbursement Strategy | Site-of-service payment parity between office-based and facility-based settings determines capital deployment. |
Research Approach
Bottom-up ambulatory surgery center and gynecology clinic procedure volume modeling reconciled against top-down radiofrequency generator and disposable electrode array supply tracking forms the analytical core. Primary interviews with gynecologic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and EU MDR notified body technical documentation records. Secondary validation draws from hospital procurement databases and medical device trade flow customs data.
Historical trendline analysis of radiofrequency platform replacement cycles and cryoablation adoption trajectories informs projection parameters across the analysis window. Segmentation dimensions include energy delivery modality, care setting type, anesthesia protocol requirement, and regional regulatory cluster. CAGRs derive from installed base expansion rates and per-procedure disposable revenue attachment. Forecast inputs incorporate EU MDR transitional relief timelines and ambulatory surgery center network consolidation velocity.
Several conditions sit outside the modeled scope, including individual surgeon training completion rates, payer-specific prior authorization denial patterns, and raw material cost volatility in precision electronics components. Forecasts reflect documented assumptions about reimbursement stability and regulatory pathway efficiency. Supply chain disruption in German electrosurgical component clusters and CMS facility fee restructuring warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Surgical Clips Market