
 Hospital and Pre-Hospital External Defibrillator Market | 2026-2036
Hospital and Pre-Hospital External Defibrillator Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital and Pre-Hospital External Defibrillator Market Analysis
Trained emergency medical technician availability is bifurcating market growth between advanced hospital systems and under-staffed rural pre-hospital networks. Medtronic PLC leverages its integrated cardiovascular portfolio to sustain catheter lab defibrillator placements across tertiary care centers. Philips anchors pre-hospital segments through ruggedized automated external defibrillator designs purpose-built for ambulance deployment.
Hospital and pre-hospital external defibrillators are electrotherapy devices delivering calibrated biphasic energy shocks to terminate ventricular fibrillation or pulseless ventricular tachycardia, with energy outputs typically ranging from 120 to 360 joules depending on patient impedance and waveform algorithms. Their primary purpose is restoring organized cardiac rhythm during sudden cardiac arrest events in both clinical and field settings. Automated external defibrillators lead volume shipments due to public access legislation and lay-rescuer training mandates, while manual defibrillators command premium pricing in hospital critical care units where clinician-directed energy titration remains essential. Wireless technology integration is gaining fastest adoption as emergency medical services demand real-time transmission of resuscitation data to receiving hospitals.
FDA 510(k) clearance pathways and EU MDR conformity assessment procedures shape product development timelines and market access requirements for manufacturers serving Western markets. Japan's PMDA enforces distinct electrical safety and electromagnetic compatibility standards that create additional certification burdens for imported devices. Stakeholders must monitor evolving pre-hospital data connectivity requirements and reimbursement shifts toward outcome-based emergency cardiac care protocols.
Market Dynamics
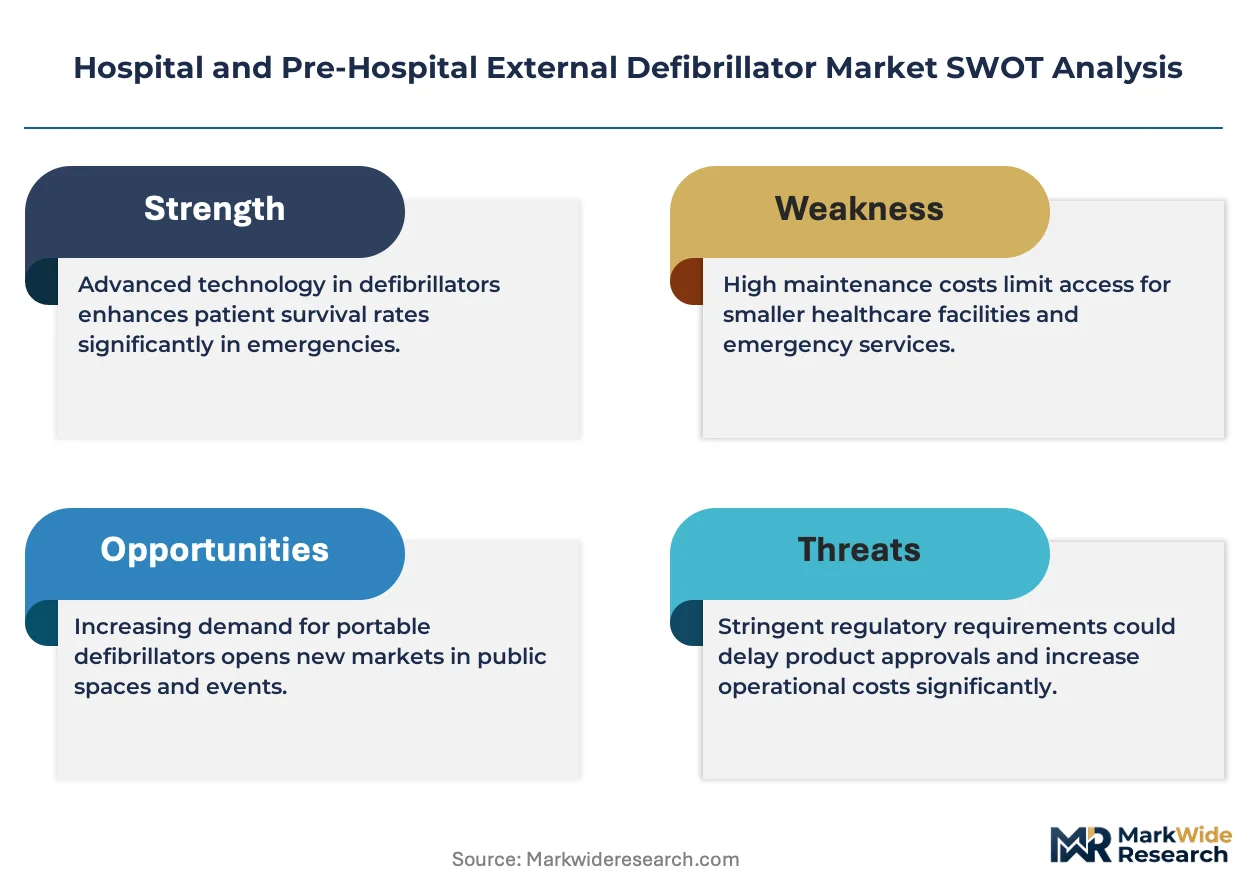
Biphasic waveform algorithms with real-time impedance compensation are compressing the performance gap between manual and automated external defibrillators, forcing manufacturers to differentiate through data connectivity rather than energy delivery specifications.
Growth Catalysts
- Public Access Defibrillation Mandates:Legislative requirements in the United States, Germany, and Japan are compelling municipalities, airports, and sports venues to install automated external defibrillator networks with standardized signage and maintenance protocols.
- EU MDR Recertification Waves:The Medical Device Regulation's stricter clinical evidence requirements are accelerating hospital replacement cycles for legacy defibrillator fleets as institutions preempt compliance deadlines.
- Cellular Telemetry Integration:Emergency medical services are demanding automated external defibrillators with embedded 4G/5G modems to stream resuscitation data directly to catheterization labs before patient arrival.
Market Restraints
- Capacitor Supply Concentration:High-voltage film capacitor production concentrates among Japanese and German component suppliers, creating input cost volatility and extended lead times for defibrillator manufacturers.
- FDA 510(k) Review Bottlenecks:Premarket notification backlogs for software-as-a-medical-device features are extending product launch timelines by 8-14 months for wireless-enabled defibrillator systems.
- Alternative Resuscitation Modalities:Mechanical chest compression devices and extracorporeal CPR programs are capturing capital allocation in tertiary cardiac centers, constraining pure defibrillator budget expansion.
Strategic Opportunities
- Rural Pre-Hospital Networks:Underpenetrated emergency medical services districts in the United States Mountain West and German eastern federal states present deployment gaps for ruggedized automated external defibrillator units with extended battery life.
- Outcome-Based Reimbursement Alignment:Japan's Ministry of Health, Labour and Welfare is piloting bundled payment models for sudden cardiac arrest survival chains, rewarding defibrillator-CPR integration with higher reimbursement tiers.
- AI-Assisted Rhythm Interpretation:Machine learning algorithms for artifact rejection during patient movement are converging with traditional ECG analysis to reduce false shock advisories in ambulance transport environments.
Industry Challenges
- Biomedical Technician Certification Gaps:Hospital clinical engineering departments face acute shortages of technicians qualified to service biphasic waveform generators and wireless telemetry modules under ISO 13485 quality management protocols.
- Legacy Fleet Integration Complexity:Pre-hospital agencies struggle to synchronize new automated external defibrillator data formats with existing dispatch software and electronic patient care reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital and Pre-Hospital External Defibrillator Market |
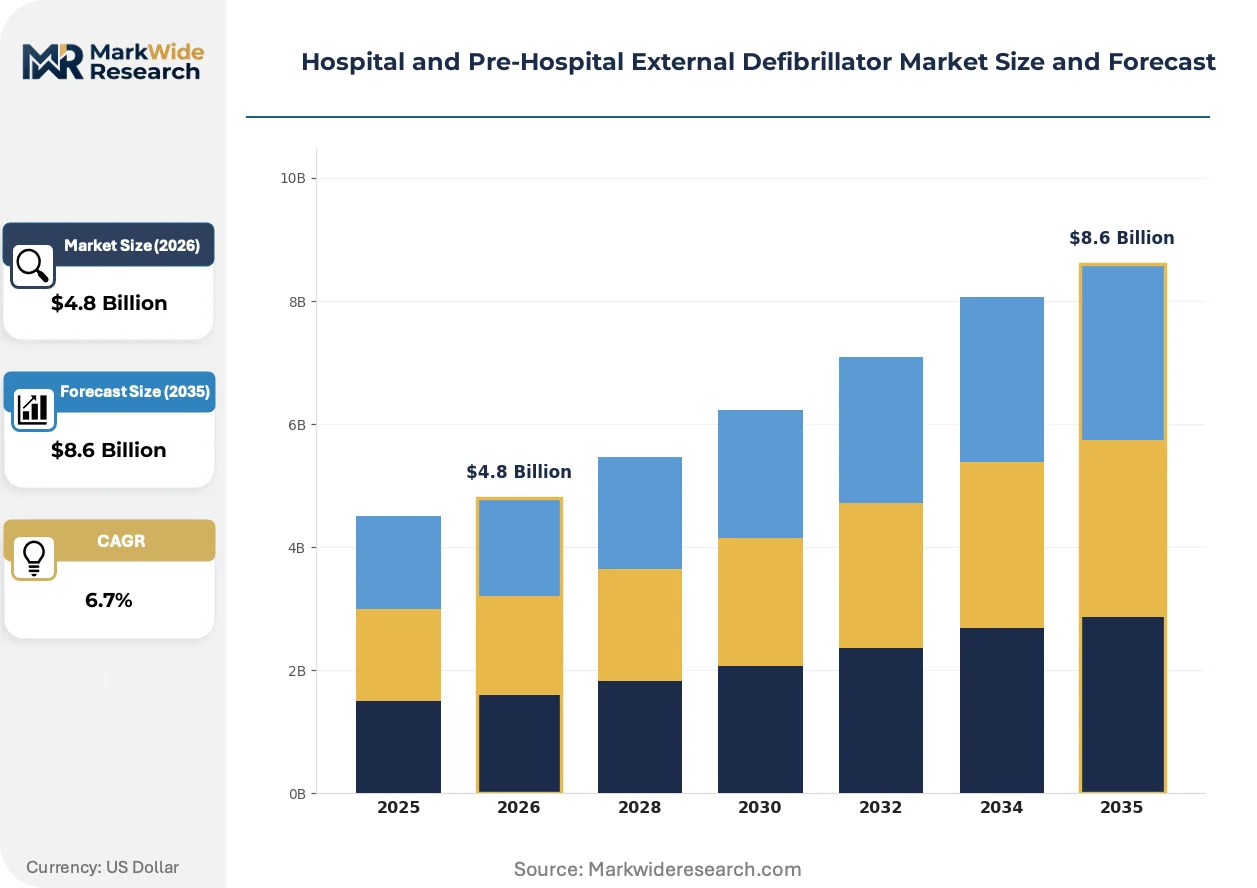
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated External Defibrillators, Manual Defibrillators, Implantable Cardioverter Defibrillators, Wearable Defibrillators End User: Emergency Medical Services, Hospitals, Clinics, Homecare Providers Technology: Analog, Digital, Hybrid, Wireless Deployment: Fixed, Mobile, Portable, Stationary |
| Companies Covered | Asahi Kasei Corporation, Nihon Kohden Corporation, Medtronic PLC, Mindray, GE Healthcare, Stryker Corporation, Boston Scientific Corporation, Abbott Laboratories, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital and Pre-Hospital External Defibrillator Market Emerging Trajectories
Wireless data transmission is redefining competitive differentiation as emergency medical services prioritize seamless handoff of resuscitation metrics to receiving hospitals over standalone device reliability.
Adaptive biphasic energy protocols with patient-specific impedance modeling are supplanting fixed-dose shock algorithms in premium hospital defibrillator segments. Cardiac catheterization labs at tertiary centers in the United States and Japan are adopting these systems to reduce post-resuscitation myocardial dysfunction. The technology is compressing the traditional separation between manual and automated external defibrillator performance tiers, forcing mid-market manufacturers to accelerate algorithm development or retreat to price-driven municipal contracts.
Japan's PMDA has tightened electrical safety testing requirements for imported defibrillators under revised electromagnetic compatibility standards effective 2024. Manufacturers must now submit additional clinical evidence for wireless transmission functions previously cleared under simplified pathways. European and North American vendors are responding by establishing dedicated Tokyo regulatory affairs teams and local electromagnetic testing partnerships to avoid market exclusion.
Hospital purchasing committees are unbundling device procurement from long-term service agreements, treating preventive maintenance and software updates as separately negotiable line items. This pattern is most pronounced in German hospital networks undergoing centralization, where procurement offices negotiate fleet-wide defibrillator purchases while clinical engineering departments retain independent service provider selection. The shift is compressing manufacturer service margins and accelerating third-party independent service organization penetration in Western European markets.
Hospital and Pre-Hospital External Defibrillator Market Segmentation
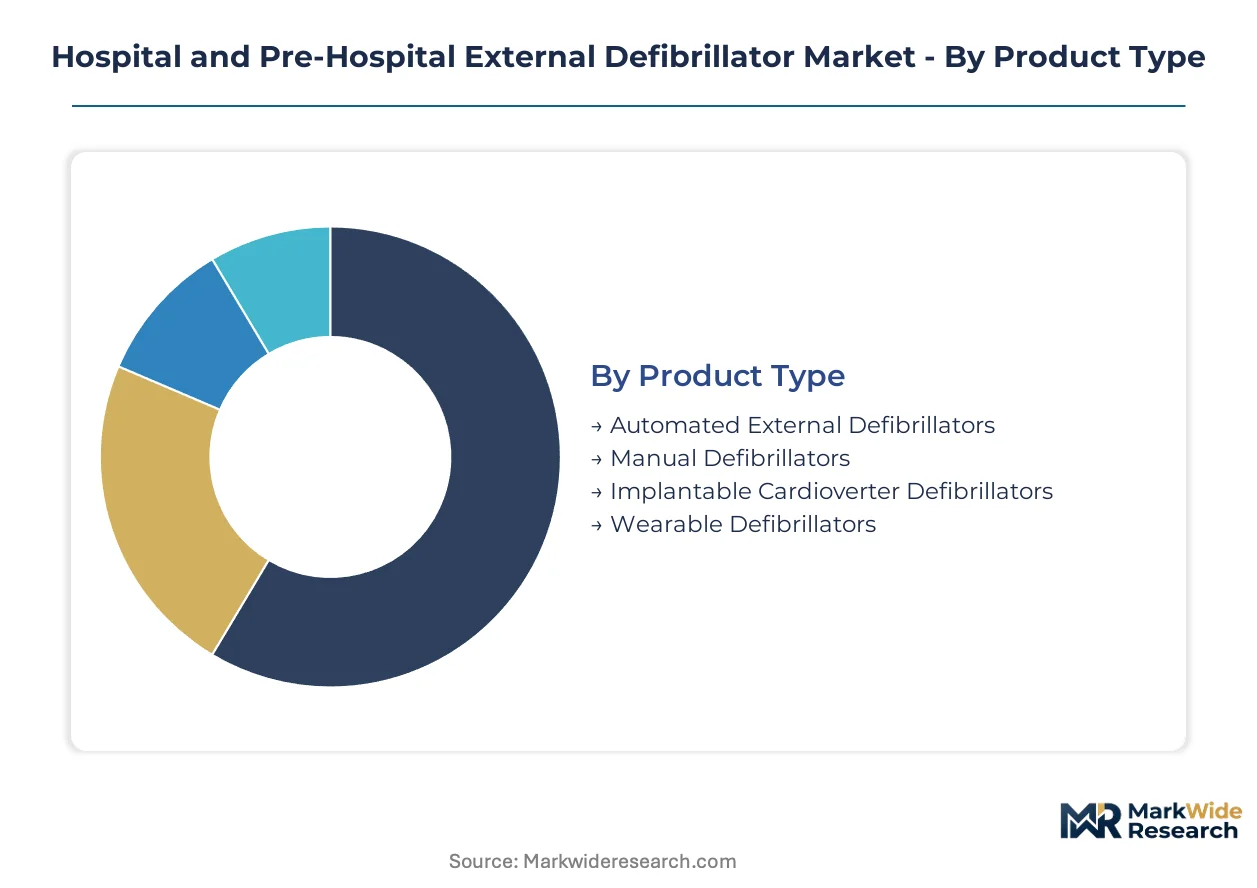
Defibrillator procurement patterns diverge sharply between institutional buyers with centralized fleet management and distributed pre-hospital networks requiring ruggedized portability. Segment-specific technology requirements and regulatory compliance burdens create distinct margin profiles across product categories.
Product Type:
Domestic production concentrates in manual and automated systems for hospital integration, while wearable and implantable segments rely heavily on cross-border supply chains from specialized cardiovascular device manufacturers.
- Automated External Defibrillators:Biphasic waveform units with voice-prompted operation dominate municipal procurement for public access deployment. Demand concentrates in United States emergency medical services fleets upgrading to cellular-enabled models for real-time data transmission to receiving catheterization labs.
- Manual Defibrillators:Clinician-directed energy titration systems with 12-lead ECG diagnostic capability anchor critical care and catheter lab installations. German hospital networks undergoing centralization drive replacement cycles as EU MDR recertification deadlines approach.
- Implantable Cardioverter Defibrillators:Subcutaneous and transvenous systems for chronic arrhythmia management.
- Wearable Defibrillators:Vest-based systems for temporary bridge-to-transplant or post-MI monitoring in ambulatory settings.
Manual defibrillators command the established base in tertiary cardiac centers. The steepest expansion runs through automated external defibrillators as public access legislation mandates proliferate across municipalities.
End User:
Cost tier separation distinguishes capital-intensive hospital procurement from price-sensitive municipal emergency medical services contracting.
- Emergency Medical Services:Ruggedized automated units with extended battery life and shock advisory algorithms optimized for moving vehicle environments. United States Mountain West districts and German eastern federal states present deployment gaps for fleet modernization.
- Hospitals:Integrated resuscitation platforms with manual override capability and wireless telemetry for catheter lab coordination. Japanese tertiary centers prioritize adaptive biphasic energy protocols with patient-specific impedance modeling to reduce post-resuscitation myocardial dysfunction.
- Clinics:Compact automated units for outpatient cardiac rehabilitation and diagnostic facilities.
- Homecare Providers:Simplified automated systems for high-risk patient discharge protocols and residential monitoring programs.
Hospitals anchor premium pricing through integrated service agreements. Emergency medical services are gaining share fastest as pre-hospital data connectivity requirements reshape competitive differentiation.
Technology:
Application maturity separates legacy analog systems from digital platforms with embedded software-as-a-medical-device features facing extended FDA 510(k) review timelines.
- Digital:Microprocessor-controlled waveform generation with real-time impedance compensation and artifact rejection algorithms. FDA premarket notification backlogs for software-enabled features extend launch timelines by 8-14 months for wireless-integrated systems.
- Wireless:Embedded 4G/5G modems streaming resuscitation metrics directly to hospital electronic health records and dispatch software. EU MDR conformity assessment procedures impose additional clinical evidence requirements for transmission functions.
- Analog:Legacy fixed-dose shock delivery systems in aging hospital fleets facing replacement cycles.
- Hybrid:Combined analog-digital architectures bridging legacy infrastructure with modern connectivity modules.
Analog systems retain residual installed base in budget-constrained facilities. Wireless configurations are climbing the fastest as emergency medical services demand seamless handoff capabilities.
Deployment:
Volume concentration favors portable units for pre-hospital distribution, while fixed installations dominate hospital catheterization lab and critical care unit capital budgets.
- Portable:Lightweight battery-operated units with carrying cases for first-responder field deployment. Japanese PMDA tightened electromagnetic compatibility standards create certification burdens for imported devices in this high-mobility segment.
- Fixed:Wall-mounted or cart-based systems with integrated monitoring and defibrillation capability in hospital resuscitation bays. German procurement offices negotiate fleet-wide purchases while clinical engineering departments retain independent service provider selection.
- Mobile:Vehicle-integrated units with power conditioning for ambulance electrical systems.
- Stationary:Permanent installations in public access locations with standardized signage and maintenance protocols mandated by United States legislative requirements.
Fixed deployments anchor hospital infrastructure investment. Portable configurations are expanding most quickly as emergency medical services fleets automate external defibrillator deployment across ambulances and first-response vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States emergency medical services fleets deploy automated external defibrillators with cellular telemetry as standard, while Japanese tertiary centers prioritize adaptive biphasic energy protocols for catheter lab integration. German hospital networks undergoing centralization drive replacement cycles distinct from pre-hospital procurement patterns elsewhere.
United States
Mountain West emergency medical services districts present deployment gaps for ruggedized automated external defibrillator fleet modernization. FDA 510(k) premarket notification requirements extend product launch timelines for wireless-enabled systems by 8-14 months. Municipal public access defibrillation mandates in California and New York compel standardized signage and maintenance protocols across airports and sports venues.
Germany
Hospital networks in North Rhine-Westphalia and Bavaria preempt EU MDR recertification deadlines with accelerated defibrillator replacement cycles. The Medical Device Regulation's stricter clinical evidence requirements reshape procurement timelines for legacy fleet upgrades. Procurement offices in Berlin-Brandenburg negotiate fleet-wide purchases while clinical engineering departments retain independent service provider selection.
Japan
Tertiary cardiac centers in Kanto and Kansai regions adopt adaptive biphasic energy protocols with patient-specific impedance modeling to reduce post-resuscitation myocardial dysfunction. PMDA tightened electromagnetic compatibility standards for imported defibrillators effective 2024, requiring additional clinical evidence for wireless transmission functions. Tokyo-based regulatory affairs teams and local electromagnetic testing partnerships help European and North American vendors avoid market exclusion.
United Kingdom
London and Southeast England concentrate National Health Service procurement for integrated resuscitation platforms with manual override capability. NHS England outcome-based emergency cardiac care protocols reward defibrillator-CPR integration with higher reimbursement tiers. Midlands hospital trusts face biomedical technician certification gaps for servicing biphasic waveform generators under ISO 13485 quality management protocols.
Australia
New South Wales and Victoria emergency medical services demand automated external defibrillators with embedded 4G/5G modems for real-time resuscitation data streaming to receiving hospitals. TGA conformity assessment procedures align with EU MDR evidence requirements for wireless transmission functions. Rural pre-hospital networks in Queensland present underpenetrated deployment opportunities for ruggedized units with extended battery life.
Hospital and Pre-Hospital External Defibrillator Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cardiovascular device conglomerates controlling catheter lab placements while dedicated emergency care manufacturers anchor pre-hospital segments. The market structure concentrates around firms with integrated cardiovascular portfolios capable of sustaining tertiary care relationships alongside ruggedized field-deployment expertise. Three archetypes dominate: diversified cardiovascular conglomerates with catheter lab presence, dedicated emergency care specialists with ambulance fleet relationships, and diversified medical technology suppliers with broad hospital contracting reach. Competitive moves center on wireless telemetry integration partnerships and service agreement unbundling to capture third-party maintenance revenue.
Among diversified cardiovascular conglomerates, Medtronic PLC exemplifies the integrated leader archetype through its sustained catheter lab defibrillator placements. Koninklijke Philips N.V. occupies a position within the emergency care specialist tier, with its ruggedized automated external defibrillator designs purpose-built for ambulance deployment. Asahi Kasei Corporation represents the diversified medical technology supplier archetype, anchoring hospital resuscitation equipment procurement across multiple acute care segments.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Nihon Kohden Corporation |
| Medtronic PLC |
| Mindray |
| GE Healthcare |
| Stryker Corporation |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) and EU MDR certification regimes gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified component vendors while amplifying pricing power for manufacturers with cleared wireless telemetry platforms. Hospital procurement committees exploit this bifurcation by unbundling device purchases from service agreements, forcing price transparency across premium manual systems and economy-tier automated external defibrillators.
Pricing Analysis
Long-term fleet-of-service agreements dominate hospital procurement, while municipal emergency medical services contracts favor project-based competitive bidding with multi-year maintenance riders. Price differentiation hinges on FDA clearance tier for software-as-a-medical-device features and ISO 13485 quality certification status. Cost compression intensifies in economy-tier automated external defibrillators as Japanese capacitor supply constraints propagate through bill-of-materials. Emergency medical services fleets exhibit highest price sensitivity; catheterization labs demonstrate lowest sensitivity due to outcome-based reimbursement alignment.
Supply Chain Analysis
Just-in-time inventory strategies prevail for high-voltage film capacitors sourced from Japan and Germany, though strategic stockpiling of battery cells buffers against lithium-ion supply volatility. Manufacturing draws from specialized component ecosystems in Japan, Germany, and the United States, with final assembly concentrating in FDA-registered facilities. Single-source vulnerability concentrates in Japanese capacitor suppliers, exposing manufacturers to extended lead time fluctuations. Distribution runs through hospital group purchasing organizations and emergency medical services fleet procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through German hospital network centralization and United States emergency medical services district consolidation, fragmenting vendor negotiation leverage across fewer procurement decision-makers.
For Market Incumbents: Consolidate service agreement portfolios to offset device margin compression from unbundled procurement trends. Deepen backward integration into high-voltage capacitor supply through dedicated partnerships with Japanese component houses. Prioritize FDA 510(k) clearance for AI-assisted rhythm interpretation features before software review backlogs extend further. For New Entrants and Emerging Players: Lead with ruggedized automated external defibrillator designs targeting underpenetrated United States Mountain West emergency medical services districts, where extended battery life specifications remain underserved. Pursue direct municipal contracting channels bypassing incumbent distributor relationships. Anchor initial beachhead through outcome-based pilot programs demonstrating cellular telemetry integration with receiving hospitals. For Investors and Strategic Acquirers: EU MDR recertification waves reshape the acquisition landscape by accelerating replacement demand for legacy defibrillator fleets. Target mid-cap manufacturers with cleared wireless platforms and established catheter lab relationships. Watch FDA premarket notification backlog resolution as the signal indicating software-enabled defibrillator launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Accelerates hospital replacement cycles as institutions preempt compliance deadlines in Germany. |
| Cellular Telemetry Integration | Enables real-time resuscitation data streaming to catheterization labs before patient arrival. |
| Backward Integration into Capacitors | Reduces input cost volatility from concentrated Japanese and German supplier bases. |
| Hospital System Partnership | Secures fleet-wide defibrillator placements through centralized procurement offices. |
| Software Companion Development | Supports AI-assisted rhythm interpretation for artifact rejection during ambulance transport. |
Methodological Framework
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, emergency medical services fleet managers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and emergency medical services capital expenditure disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Sensitivity analysis tested forecast outputs against varying assumptions for EU MDR recertification velocity, FDA software review timeline extensions, and emergency medical services cellular telemetry adoption rates. Segmentation dimensions spanned product type, end user, technology architecture, and deployment configuration. CAGRs derived from logistic diffusion curves fitted to historical replacement cycles and projected public access defibrillation mandate expansion.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EU MDR regulatory stability would require recalibration. Forecasts reflect assumptions regarding capacitor supply continuity and wireless spectrum allocation for medical device telemetry. Revision becomes warranted when FDA premarket notification backlogs exceed current trajectory thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Ablation Technologies Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Flow Diverters Market
Medical Devices
Enteral Stents Market
Medical Devices
Asthma Device Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Anterior Cervical Fixation Devices Market