
 Global Esophageal Catheters Market | 2026-2036
Global Esophageal Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Esophageal Catheters Market Foresight
CE-marked and FDA-cleared high-fidelity pressure monitoring tiers is unwinding legacy low-resolution catheter inventories across tertiary cardiac centers. Medtronic plc leverages its vertically integrated sensor manufacturing to sustain cost advantages in solid-state assemblies. Boston Scientific Corporation anchors its position through specialized distribution into electrophysiology labs across North America and Western Europe.
Esophageal catheters are flexible, multi-lumen devices incorporating pressure transducers, temperature sensors, or impedance electrodes, typically manufactured from medical-grade polyurethane or silicone with diameters ranging from 4 to 10 French, designed for transnasal or transoral insertion to record intraluminal pressures, pH levels, or electrical conductivity from the upper esophageal sphincter to the gastroesophageal junction. Pressure monitoring catheters capture the largest revenue pool due to entrenched use in cardiac ablation procedures, while impedance catheters represent the fastest-expanding segment as gastroenterology practices adopt combined pH-impedance testing for refractory reflux diagnosis. Fiber optic technology dominates R&D pipelines because of its immunity to electromagnetic interference during MRI-guided interventions, though wireless microelectromechanical systems prototypes are gaining traction in sleep medicine applications.
FDA 510(k) pathways and the EU Medical Device Regulation shape product development timelines, with MDR's enhanced clinical evidence requirements extending certification cycles for novel sensor configurations. Japan's PMDA enforces JIS-compliant biocompatibility testing that filters out lower-tier manufacturers seeking East Asian market entry. Stakeholders must monitor evolving reimbursement codes for ambulatory pH monitoring, as payer decisions in the United States and Germany will determine whether impedance-based diagnostics displace conventional catheter categories.
Market Dynamics
Solid-state pressure sensor miniaturization is compressing replacement cycles across tertiary cardiac centers while FDA 510(k) clearance pathways accelerate competitive entry timelines for new catheter configurations.
Growth Catalysts
- EU MDR Clinical Evidence Mandate:Enhanced post-market surveillance requirements for Class IIa medical devices are filtering out marginal manufacturers and consolidating procurement toward CE-marked high-fidelity tiers across German and French hospital networks.
- Ambulatory Surgical Center Expansion:Outpatient esophageal monitoring services in the United States are driving catheter volume through specialized electrophysiology lab partnerships and same-day procedure protocols.
- Fiber Optic Immunity Properties:MRI-guided cardiac ablation procedures are creating pull for electromagnetic-interference-resistant sensor platforms that enable real-time pressure mapping during magnetic resonance imaging.
Market Restraints
- Medical-Grade Polyurethane Input Concentration:Three Asian chemical conglomerates control specialty polymer feedstocks, exposing catheter manufacturers to price volatility and supply allocation risk.
- PMDA Biocompatibility Testing Burden:Japan's JIS-compliant cytotoxicity and sensitization protocols extend registration timelines and filter out lower-tier entrants lacking dedicated regulatory affairs infrastructure.
- Reusable Catheter Substitution:Sterilizable impedance probe systems in cost-constrained European public hospitals are displacing single-use premium configurations in non-cardiac diagnostic applications.
Strategic Opportunities
- Wireless MEMS Sleep Medicine Integration:Microelectromechanical systems prototypes for nocturnal esophageal pressure monitoring are opening ambulatory diagnostic channels outside traditional gastroenterology and electrophysiology settings.
- India CDSCO Accelerated Approval:The country's streamlined Class B medical device registration pathway for predicate-equivalent catheters reduces time-to-market for manufacturers targeting tier-2 city hospital procurement.
- Combined pH-Impedance Protocol Adoption:Refractory gastroesophageal reflux diagnosis is converging multi-sensor catheter designs that capture simultaneous acid exposure and bolus transit data in single procedures.
Industry Challenges
- Sensor Calibration Expertise Scarcity:Solid-state pressure transducer manufacturing requires specialized microfabrication technicians that catheter assemblers must recruit from semiconductor and aerospace labor pools.
- Legacy EMR Integration Complexity:High-fidelity catheter data streams require custom HL7 interface development to populate hospital electronic medical record systems, extending sales cycles and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Esophageal Catheters Market |
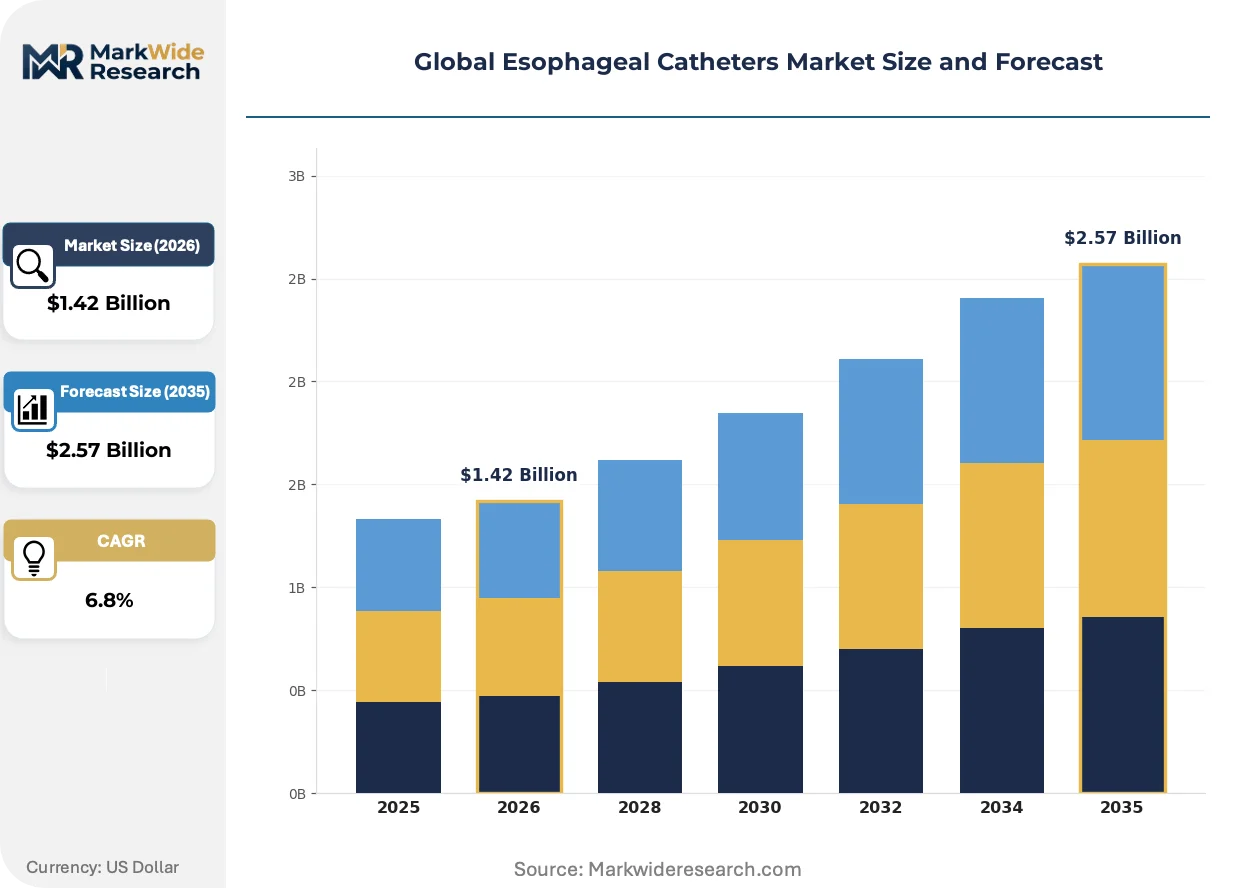
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Monitoring Catheters, Temperature Sensors, Impedance Catheters, pH Monitoring Catheters, Conductivity Catheters Application: Cardiac Monitoring, Respiratory Assessment, Gastroesophageal Reflux, Sleep Apnea Testing, Neurological Evaluation End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Research Institutes Technology: Fiber Optic, Wireless, Balloon Catheter, Solid-State, Microelectromechanical Systems |
| Companies Covered | Teleflex Incorporated, Merit Medical Systems Inc., Medtronic plc, CooperSurgical Inc., Avanos Medical Inc., Boston Scientific Corporation, Cook Medical Inc., PENTAX Medical Co, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Esophageal Catheters Market Shifts & Advancements
Catheter technology trajectories are diverging between premium fiber-optic platforms for MRI-compatible cardiac procedures and cost-optimized solid-state assemblies for high-volume ambulatory diagnostics.
Fiber optic pressure sensing is bifurcating the cardiac ablation catheter segment. The technology transmits intraluminal pressure data via light signals rather than electrical impedance, eliminating electromagnetic interference during magnetic resonance imaging. Tertiary cardiac centers in Germany and Japan are adopting these platforms for hybrid electrophysiology-MRI labs. This bifurcation is compressing demand for conventional piezoelectric sensor inventories and forcing distributors to segment their catheter portfolios by imaging compatibility tier.
EU Medical Device Regulation enhanced clinical evidence requirements are extending certification cycles for novel sensor configurations. Manufacturers must now submit post-market clinical follow-up protocols and periodic safety update reports for Class IIa esophageal devices. The impedance catheter segment faces the steepest compliance burden, as combined pH-impedance designs lack established predicate equivalence pathways and require de novo clinical investigations.
Hospital procurement committees are consolidating catheter purchasing through specialized electrophysiology distribution networks rather than general medical device wholesalers. This channel concentration is compressing price transparency and favoring suppliers with dedicated clinical specialist teams. The shift is most visible in United States integrated delivery networks, where catheter standardization across affiliated hospitals has replaced site-by-site purchasing autonomy.
Global Esophageal Catheters Market Segmentation
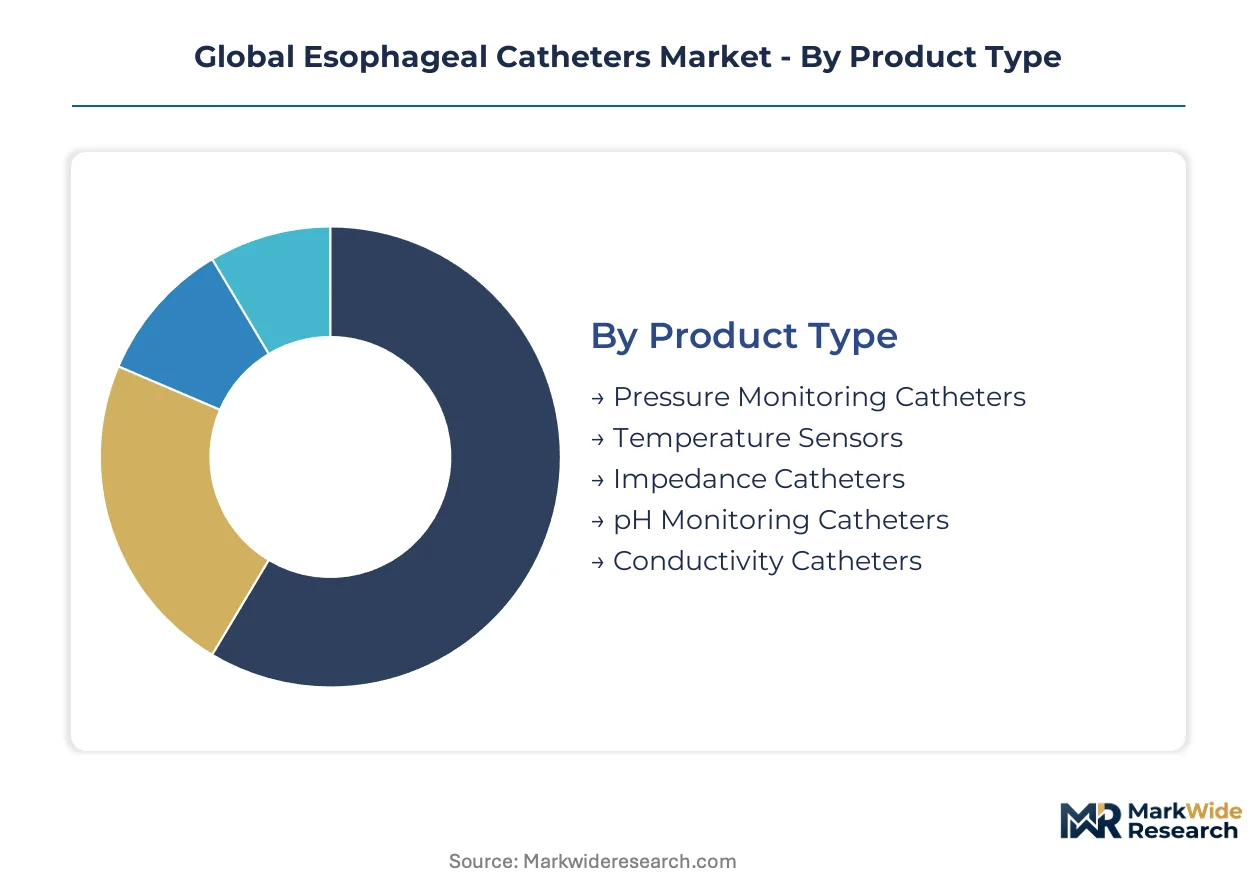
Catheter purchasing patterns diverge sharply across clinical settings, with tertiary cardiac centers driving premium sensor procurement while ambulatory channels prioritize cost-optimized disposable configurations. Understanding these segment-channel pairings reveals where manufacturers must align product specifications with reimbursement codes and sterilization protocols.
Product Type:
Pressure monitoring catheters flow through electrophysiology specialty distributors, while impedance and pH configurations reach gastroenterology practices through broader hospital supply channels.
- Pressure Monitoring Catheters:Multi-lumen polyurethane assemblies incorporating solid-state piezoelectric transducers measure intraluminal pressures from upper esophageal sphincter to gastroesophageal junction. Demand concentrates in German and Japanese tertiary cardiac centers performing cardiac ablation procedures, where high-fidelity pressure mapping guides radiofrequency energy delivery.
- Impedance Catheters:Combined pH-impedance designs employ circumferential electrode arrays to detect bolus transit and acid exposure simultaneously. United States gastroenterology practices are adopting these platforms for refractory reflux diagnosis, displacing conventional pH-only monitoring as payer codes evolve toward combined testing reimbursement.
- Temperature Sensors:Thermocouple-embedded catheter tips track thermal changes during ablation procedures.
- pH Monitoring Catheters:Single-sensor acid exposure recorders maintain volume in cost-constrained European public hospitals.
- Conductivity Catheters:Electrical impedance spectroscopy variants serve specialized neurological evaluation protocols.
Pressure monitoring catheters dominate installed base. Impedance catheters are where expansion concentrates.
Application:
Volume scales inversely with reimbursement complexity—cardiac applications command premium pricing with established codes, while sleep and neurological indications face coverage uncertainty.
- Cardiac Monitoring:Intracardiac pressure transduction during electrophysiology studies requires MRI-compatible fiber optic platforms for hybrid imaging-ablation suites. German university hospitals anchor procurement volume, with Japanese cardiac centers driving replacement cycles toward solid-state miniaturization.
- Gastroesophageal Reflux:Ambulatory pH-impedance testing protocols create catheter demand across United States integrated delivery networks, where same-day procedure economics favor disposable high-resolution configurations over reusable alternatives.
- Respiratory Assessment:Esophageal manometry evaluates diaphragm function and airway mechanics in pulmonary clinics.
- Sleep Apnea Testing:Nocturnal esophageal pressure monitoring prototypes target home-based diagnostic channels outside traditional sleep lab infrastructure.
- Neurological Evaluation:Swallowing disorder assessment employs conductivity catheters in specialized neurogastroenterology units.
Cardiac monitoring captures margin concentration. Gastroesophageal reflux applications are climbing the fastest.
End User:
Procurement authority is consolidating—hospital system standardization committees now override individual department preferences, while ambulatory surgical centers negotiate procedure-based bundles rather than device-specific purchasing.
- Hospitals:Tertiary cardiac centers in the United States and Germany drive catheter specification through electrophysiology lab accreditation requirements. These institutions demand FDA-cleared and CE-marked high-fidelity tiers with dedicated clinical specialist support.
- Ambulatory Surgical Centers:Outpatient esophageal monitoring services in United States metropolitan areas prioritize single-use pressure catheters compatible with same-day discharge protocols and streamlined sterilization workflows.
- Diagnostic Laboratories:Independent reference labs process pH-impedance studies under contract with gastroenterology practices.
- Research Institutes:Academic medical centers pilot wireless MEMS prototypes for sleep medicine applications.
Hospitals anchor procurement volume. Ambulatory surgical centers are gaining share fastest.
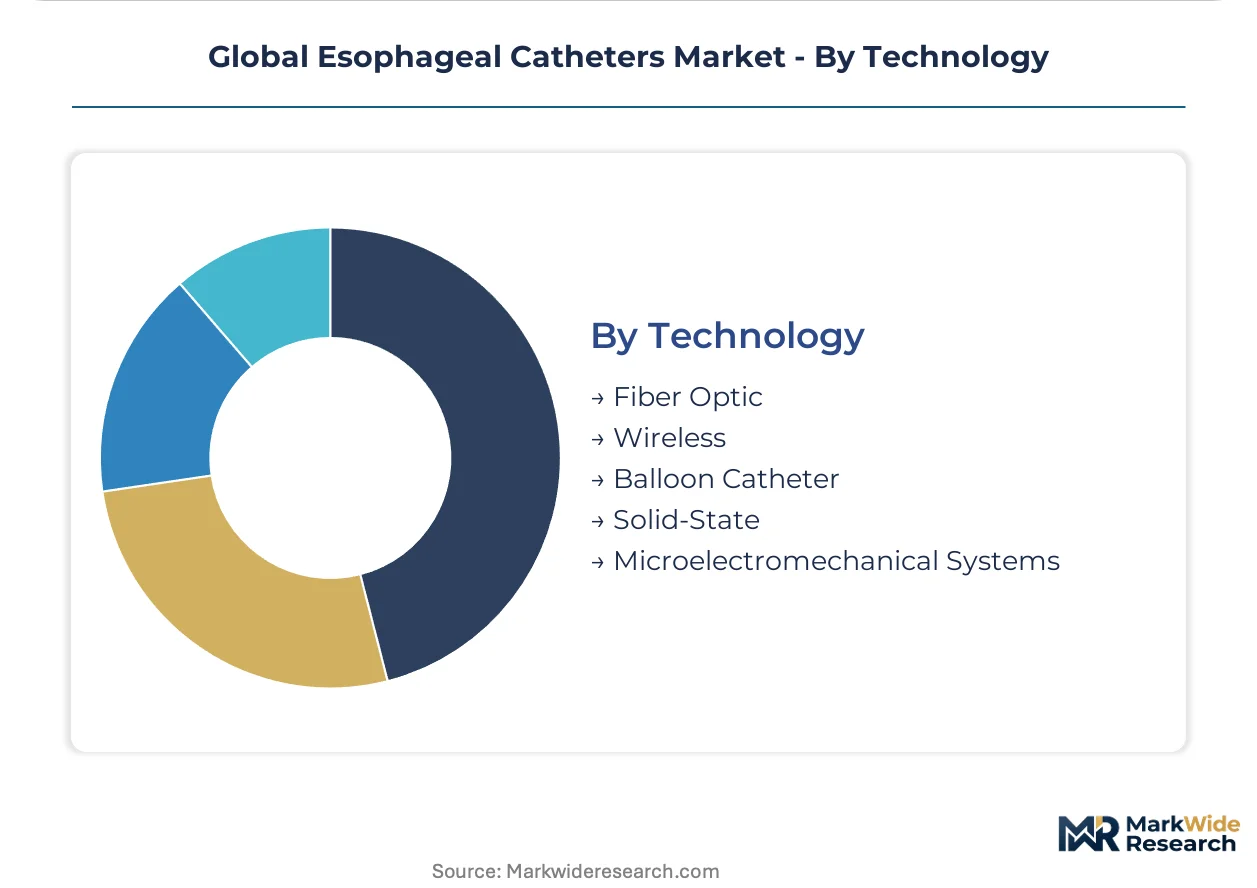
Technology:
Platform selection hinges on electromagnetic compatibility requirements—MRI-guided procedures pull toward fiber optic immunity, while cost-sensitive volume applications favor solid-state miniaturization.
- Fiber Optic:Light-based pressure transduction eliminates electromagnetic interference during magnetic resonance imaging, enabling real-time catheter navigation in hybrid electrophysiology-MRI labs. German and Japanese tertiary centers are standardizing these platforms for complex ablation procedures.
- Solid-State:Piezoresistive microsensors manufactured through semiconductor fabrication processes deliver cost-optimized pressure measurement for high-volume ambulatory diagnostics. Medtronic's captive sensor production sustains assembly cost advantages.
- Wireless:Bluetooth-enabled data transmission prototypes target home-based sleep apnea monitoring outside clinical settings.
- Balloon Catheter:Inflatable occlusion designs serve specialized respiratory mechanics assessment.
- Microelectromechanical Systems:MEMS pressure transducer miniaturization enables catheter diameter reduction below 6 French for pediatric and transnasal applications.
Solid-state platforms dominate installed base. Fiber optic configurations are where premium expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty polymer feedstock suppliers in South Korea and Japan dominate medical-grade polyurethane production, concentrating catheter manufacturing inputs in East Asian chemical clusters. German and United States tertiary cardiac centers absorb the highest-value catheter configurations, while Indian and Brazilian outpatient networks drive volume procurement of cost-optimized assemblies.
United States
Integrated delivery networks in Texas and California standardize catheter specifications across affiliated electrophysiology labs, consolidating procurement authority at system level. FDA 510(k) clearance pathways compress time-to-market for predicate-equivalent pressure monitoring configurations. Minneapolis and Boston anchor specialist distribution networks serving ambulatory surgical center expansion in metropolitan corridors.
Germany
University hospitals in Bavaria and Baden-Württemberg drive replacement cycles toward MRI-compatible fiber optic platforms for hybrid imaging-ablation suites. EU MDR enhanced clinical evidence requirements filter marginal manufacturers from CE-marking pathways. The Mannheim-Heidelberg medical technology cluster concentrates regulatory affairs expertise for Class IIa device certification.
Japan
Tertiary cardiac centers in Tokyo and Osaka prioritize solid-state pressure sensor miniaturization for high-fidelity electrophysiology procedures. PMDA enforces JIS-compliant biocompatibility testing that extends registration timelines beyond twelve months for novel sensor configurations. The Kobe medical device manufacturing hub supplies precision microfabrication capacity for transducer assembly.
India
Tier-2 city hospitals in Maharashtra and Karnataka expand esophageal monitoring services through public-private partnership diagnostic networks. CDSCO accelerated approval pathways for predicate-equivalent Class B devices reduce registration burden for standard pressure catheter configurations. Hyderabad and Chennai medical technology parks attract contract manufacturing investment targeting domestic procurement quotas.
Brazil
Outpatient gastroenterology clinics in São Paulo and Rio de Janeiro displace reusable catheter inventories with single-use impedance configurations for ambulatory pH monitoring. ANVISA medical device registration requirements prioritize biocompatility documentation for polyurethane-based multi-lumen assemblies. The São Paulo medical device distribution corridor channels imported catheter volumes into Southeast regional hospital networks.
Global Esophageal Catheters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated sensor manufacturers commanding premium positioning and contract assemblers capturing volume segments. The vendor base stratifies across three tiers: multinational conglomerates with captive microfabrication capacity, mid-scale specialists focused on electrophysiology distribution partnerships, and regional fabricators serving cost-constrained public hospital networks. Dominant competitive moves include backward integration into pressure transducer manufacturing and geographic licensing arrangements for MRI-compatible fiber optic platforms.
Among diversified medical technology conglomerates, Medtronic plc and Boston Scientific Corporation exemplify the integrated-manufacturing archetype, while Teleflex Incorporated occupies a position within the specialty distribution-focused tier. Olympus Corporation and PENTAX Medical Co represent the endoscopy-anchored diversification pattern, leveraging existing gastroenterology channel relationships for catheter portfolio extension. These groupings reflect structural positioning rather than operational equivalence, with each archetype facing distinct margin pressure from sensor calibration expertise scarcity and legacy EMR integration complexity.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Merit Medical Systems Inc. |
| Medtronic plc |
| CooperSurgical Inc. |
| Avanos Medical Inc. |
| Boston Scientific Corporation |
| Cook Medical Inc. |
| PENTAX Medical Co |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Sensor microfabrication scale economies in South Korea and Japan concentrate high-fidelity transducer supply among three chemical conglomerates, compressing cost floors for solid-state catheter assemblies while elevating premium tiers for MRI-compatible fiber optic platforms. This concentration grants incumbent manufacturers with captive sensor production decisive leverage in contract negotiations with hospital procurement committees.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across the esophageal catheter market, separating predicate-equivalent solid-state configurations from de novo fiber optic platforms requiring enhanced clinical evidence. Three-tier pricing stratifies across premium MRI-compatible, standard high-fidelity pressure monitoring, and economy reusable impedance designs. Cost compression in the standard tier intensifies as ambulatory surgical centers consolidate purchasing through specialized electrophysiology distributors. European public hospital networks exhibit highest price sensitivity due to sterilization infrastructure enabling reusable substitution, while United States integrated delivery networks absorb premium markups for same-day procedure compatibility.
Supply Chain Analysis
Medical-grade polyurethane inventory cycles extend sixteen to twenty weeks for specialty polymer grades, tethering catheter manufacturers to quarterly allocation schedules from South Korean, Japanese, and German chemical suppliers. Feedstock dependencies center on aromatic isocyanates, polyether polyols, and platinum-cured silicone elastomers. Single-source vulnerability concentrates in photoresist-patterned pressure transducer wafers fabricated at Kobe-area microfabrication hubs. Distribution runs through electrophysiology specialty networks rather than general medical device wholesalers, compressing price transparency and favoring suppliers with dedicated clinical specialist teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The esophageal catheter market sits in early-cycle expansion as combined pH-impedance protocols displace conventional single-sensor diagnostics across gastroenterology practices, with wireless MEMS prototypes opening ambulatory channels outside traditional clinical settings.
For Market Incumbents: Secure backward integration into solid-state pressure transducer manufacturing to defend margin position against sensor calibration expertise scarcity, while accelerating CE-marking pathways for MRI-compatible fiber optic platforms before EU MDR enhanced clinical evidence requirements fully mature. Consolidate electrophysiology distribution partnerships to preempt channel concentration by mid-scale specialists. For New Entrants and Emerging Players: Post-market clinical follow-up service gaps in German and French hospital networks offer white-space entry points for regulatory-native challengers willing to absorb extended certification timelines. Target India's CDSCO accelerated approval pathway for predicate-equivalent pressure catheters, leveraging Hyderabad contract manufacturing capacity to serve tier-2 city procurement expansion. Lead with disposable high-resolution impedance configurations priced below reusable European alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated sensor manufacturers with captive microfabrication capacity and established GPO contracts across United States integrated delivery networks. Five-to-ten-year viability favors players with demonstrated FDA 510(k) clearance velocity and dedicated clinical specialist teams. Watch wireless MEMS sleep medicine pilot data from academic medical centers as inflection indicator for ambulatory diagnostic channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR enhanced clinical evidence requirements filter marginal competitors from German hospital procurement. |
| Hospital System Partnership | United States integrated delivery network standardization committees override site-by-site catheter purchasing autonomy. |
| Sensor Microfabrication Scale-Up | Kobe-area precision manufacturing capacity anchors solid-state pressure transducer cost advantages. |
| Software Companion Development | Custom HL7 interface development extends sales cycles without dedicated EMR integration teams. |
| Reimbursement Strategy | Payer code evolution toward combined pH-impedance testing determines impedance catheter displacement velocity. |
Research Methodology
A spread of perspectives from electrophysiology lab directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying catheter demand projections. Primary intelligence combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement code filings, and hospital procurement system records. Bottom-up catheter unit economics triangulated against top-down tertiary cardiac center addressable market estimates.
Segmentation dimensions modeled encompass product type, application, end user, and technology platform across the projection horizon. CAGRs derived from replacement cycle analysis in German and Japanese cardiac centers, ambulatory surgical center expansion trajectories in United States metropolitan corridors, and impedance catheter protocol adoption curves in gastroenterology practices. Forecast inputs incorporated PMDA registration timeline distributions and CDSCO accelerated approval pathway utilization rates.
Underlying assumptions cover stable medical-grade polyurethane feedstock allocation, FDA 510(k) clearance velocity maintenance, and reimbursement code stability for ambulatory pH monitoring, with deviation risk concentrated in EU MDR post-market clinical follow-up burden escalation and single-source sensor wafer supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Gracey Curette Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Prescription Lens Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Digital Impression System Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Cholecystectomy Devices Market