
 Global Anesthesia Video Laryngoscope Market | 2026-2036
Global Anesthesia Video Laryngoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anesthesia Video Laryngoscope Market Foresight
Hospital procurement channels for anesthesia video laryngoscopes is fragmenting as group purchasing organizations lose leverage to direct manufacturer contracts and specialty distributors. KARL STORZ SE & Co. KG anchors German production of rigid endoscopic systems with in-house optical fabrication. Teleflex Incorporated competes through specialized airway portfolios that target emergency and critical care segments. Medtronic plc extends its reach via integrated operating room ecosystems that bundle visualization with surgical navigation.
An anesthesia video laryngoscope combines a blade-integrated or standalone camera with a display to enable indirect visualization of the glottis during tracheal intubation, typically employing CMOS sensors or fiberoptic bundles with resolutions exceeding 640 x 480 pixels for real-time airway assessment. The device serves to reduce failed first-attempt intubation rates and minimize dental or soft-tissue trauma in patients with difficult airways. Reusable systems dominate installed base value in tertiary hospitals where sterilization infrastructure supports high utilization, while disposable and single-use variants capture fastest volume growth driven by infection control mandates and ambulatory expansion. CMOS sensor technology leads new platform development for its low power draw and miniaturization potential, whereas fiberoptic configurations retain share in military and field medicine applications requiring ruggedized optics.
FDA 510(k) clearance and EU MDR conformity assessment shape product entry timelines and clinical evidence requirements for anesthesia video laryngoscope manufacturers seeking access to the United States and European markets. ISO 13485 quality management and IEC 60601 electrical safety standards further constrain design choices, particularly for battery-powered portable units. Stakeholders must monitor evolving MDR notified body capacity and FDA guidance on reusable device reprocessing as these determine which product formats achieve sustainable market presence.
Market Dynamics
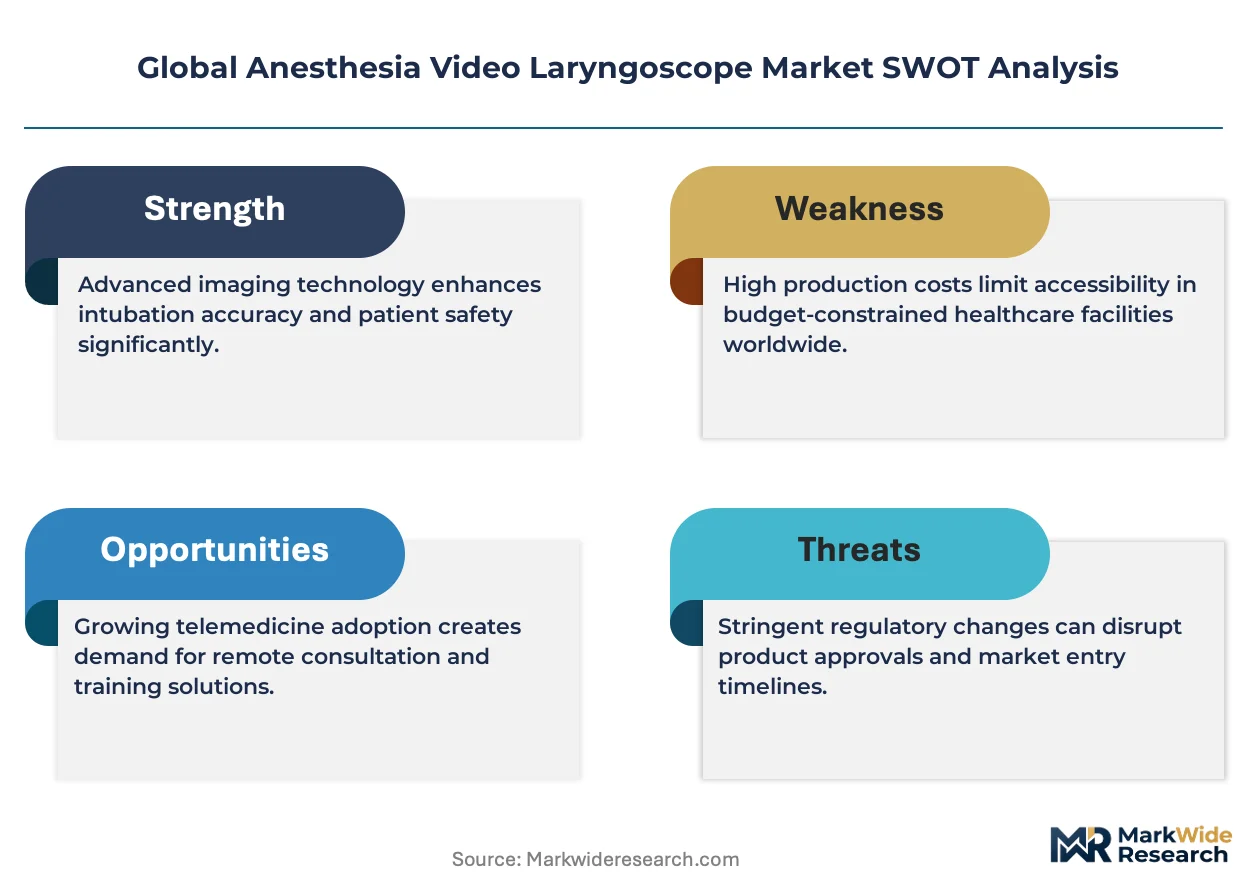
Hospital procurement for anesthesia video laryngoscopes is fragmenting as group purchasing organizations lose leverage to direct manufacturer contracts and specialty distributors. This structural shift is redistributing margin capture across the value chain and forcing vendors to rebuild channel relationships.
Growth Catalysts
- EU MDR conformity assessment:Stricter clinical evidence requirements for reusable device reprocessing are accelerating hospital transitions to single-use blade systems. German university hospitals are driving high-definition CMOS platform procurement.
- Infection control mandates:Ambulatory surgical centers in the United States are expanding disposable video laryngoscope adoption to eliminate cross-contamination risks and sterilization infrastructure costs.
- Battery-powered portable units:CMOS sensor miniaturization and low power draw are enabling field-ready configurations for military and emergency medicine applications.
Market Restraints
- Optical component concentration:German and Japanese suppliers dominate high-grade lens and fiberoptic bundle fabrication, creating supply vulnerability for manufacturers outside these clusters.
- FDA 510(k) pathway tightening:Material and electrical safety requirements for battery-powered units are extending clearance timelines and increasing premarket testing costs.
- Reusable system installed base:Tertiary hospitals with sterilization infrastructure face high switching costs to disposable formats despite infection control benefits.
Strategic Opportunities
- Underpenetrated Indian market:CDSCO regulatory alignment with global standards is opening pathways for mid-tier CMOS platforms in secondary city hospitals.
- Integrated operating room ecosystems:Bundling video laryngoscopy with surgical navigation and visualization systems creates vendor lock-in and recurring revenue streams.
- 5G-enabled remote airway consultation:Real-time video streaming from emergency scenes to tertiary centers is creating new service models for rural and military deployment.
Industry Challenges
- ISO 13485 quality management implementation:Small manufacturers struggle with documentation and audit requirements for multi-site production of disposable and reusable variants.
- Legacy sterilization protocol integration:Hospitals with established autoclave workflows face operational friction when introducing single-use systems requiring entirely different supply chain management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anesthesia Video Laryngoscope Market |
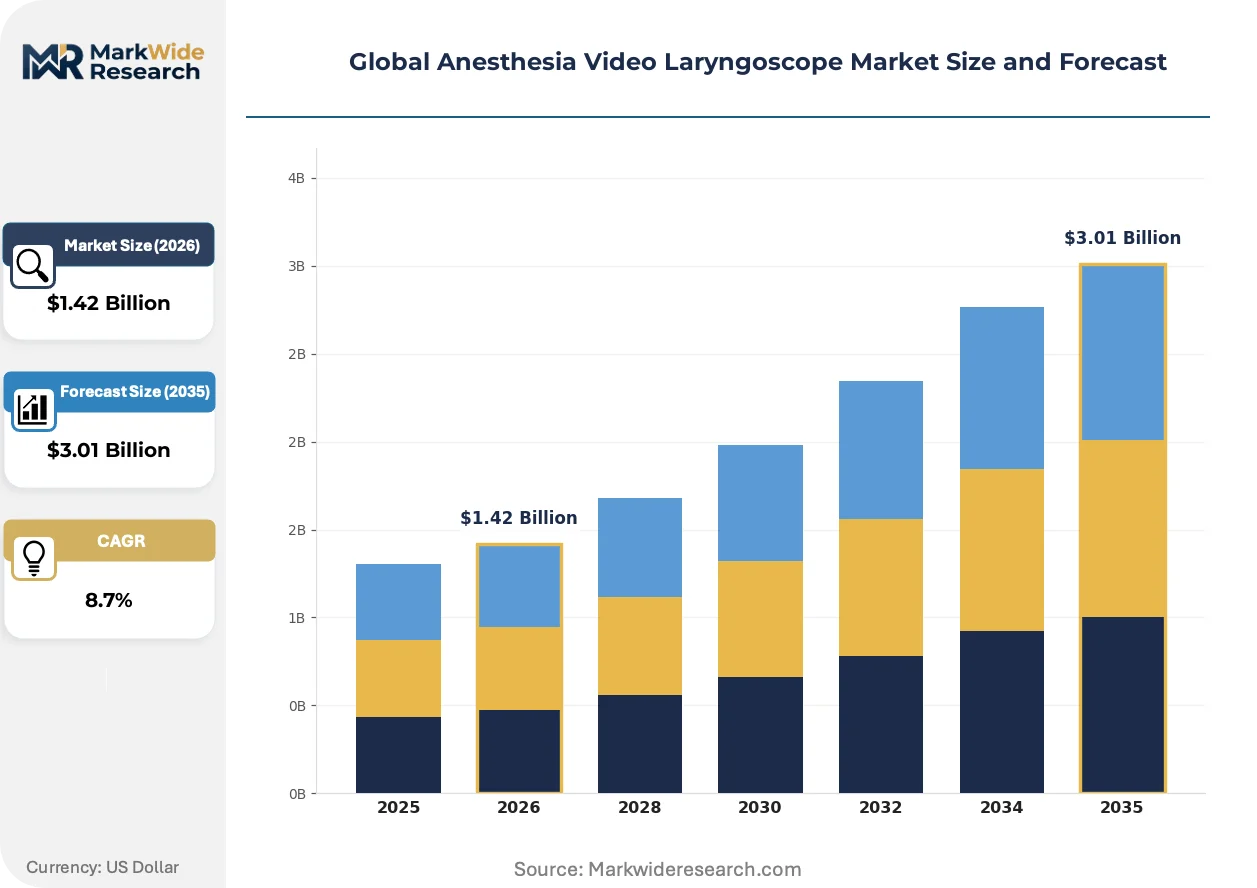
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Disposable, Single-use, Portable, Integrated, Lightweight Technology: Optical, Digital, Fiberoptic, CMOS Sensor, High-Definition, Laser Application: General Surgery, Emergency Care, Military Medicine, Pediatric Care, Ambulatory Surgery, Critical Care End User: Hospitals, Ambulatory Surgical Centers, Trauma Centers, Diagnostic Clinics, Therapeutic Facilities, Specialty Clinics |
| Companies Covered | KARL STORZ SE & Co. KG, Teleflex Incorporated, Verathon Inc., Vyaire Medical Inc., Pentax Medical, Medtronic plc, Olympus Corporation, Clarus Medical LLC, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anesthesia Video Laryngoscope Market Shifts & Advancements
CMOS sensor technology is digitizing anesthesia video laryngoscope platforms and compressing the performance gap between portable and fixed-base systems. This technological shift is redistributing competitive advantage from optical heritage to semiconductor integration capabilities.
CMOS-based imaging arrays are digitizing real-time airway visualization by replacing fiberoptic bundles with solid-state sensors that enable higher resolution at lower power consumption. Emergency medicine services in the United States are adopting these portable configurations for pre-hospital intubation. The technology is digitizing supply chain requirements as manufacturers source from semiconductor foundries rather than optical glass specialists.
EU MDR notified body capacity constraints are reshaping product entry timelines for anesthesia video laryngoscope manufacturers seeking European market access. Clinical evidence requirements for reusable device reprocessing have intensified, favoring disposable platform development. German manufacturers with established quality management systems are capturing disproportionate share of new MDR certificates.
Direct manufacturer contracting is displacing group purchasing organization intermediaries in North American hospital procurement. Specialty distributors with clinical training capabilities are capturing margin that previously flowed to broad-line GPOs. This channel restructuring is most visible in United States academic medical centers where procurement teams prioritize device-specific clinical evidence over contract aggregation.
Global Anesthesia Video Laryngoscope Market Segmentation
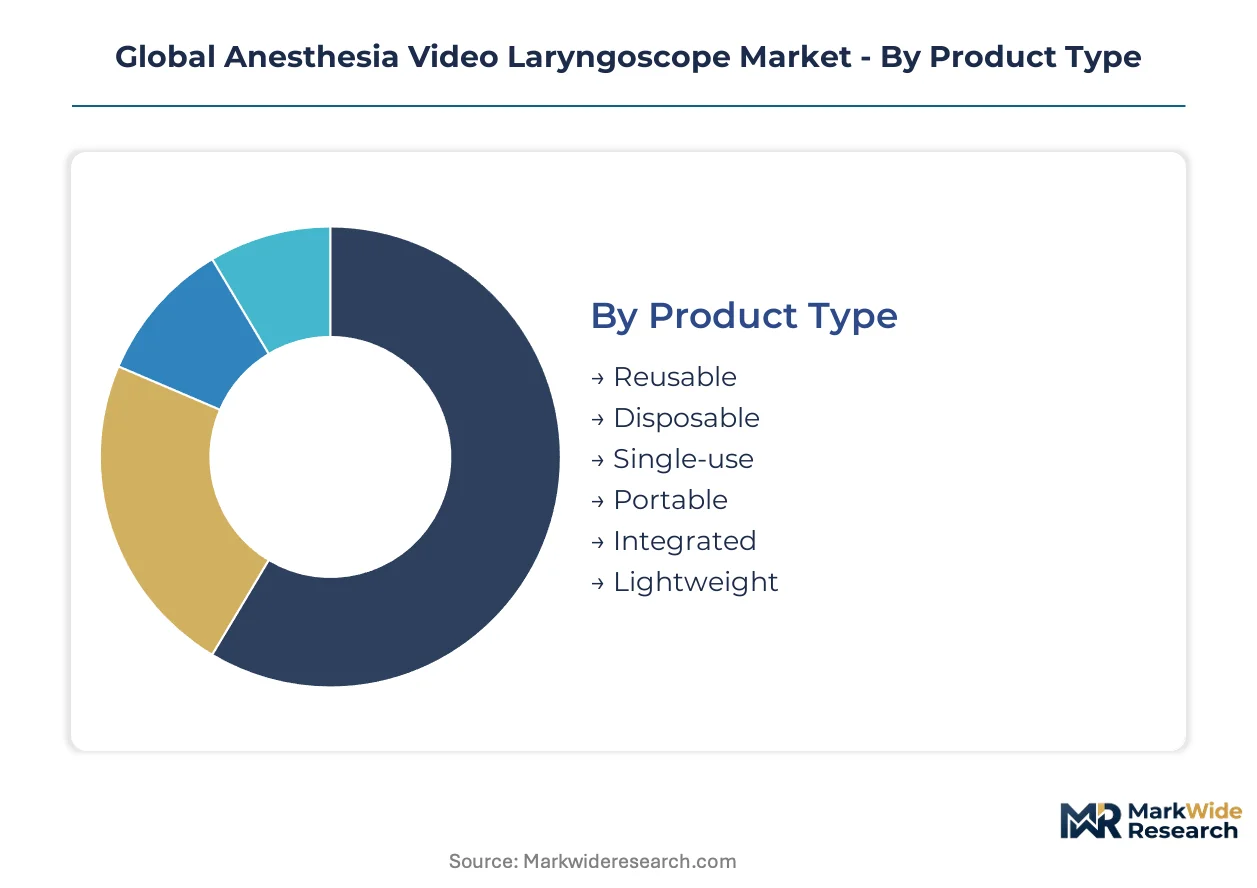
Product configuration choices in anesthesia video laryngoscopes determine sterilization workflows, capital expenditure profiles, and regulatory pathways. Technology selection shapes image quality thresholds and supply chain dependencies on semiconductor or optical component suppliers. Application context dictates portability requirements and durability specifications across civilian and military deployment scenarios.
Product Type:
Cost tier stratification separates capital-intensive reusable platforms from consumable-focused disposable formats and hybrid portable configurations.
- Reusable:Stainless steel or autoclavable polymer blades with detachable camera modules withstand repeated sterilization cycles. Tertiary hospitals in Germany maintain installed bases of these systems where centralized sterilization departments justify upfront capital investment against per-procedure economics.
- Disposable:Single-patient-use blades with integrated CMOS sensors eliminate cross-contamination risk and reprocessing documentation burdens. Ambulatory surgical centers across the United States are rotating procurement toward this format as FDA tightens material safety requirements for battery-powered reusable units.
- Single-use:Fully sealed optical-mechanical assemblies designed for one intubation procedure without component separation. Military field medicine units in expeditionary settings prioritize these for logistics simplicity.
- Portable:Battery-powered handheld units with onboard displays enable pre-hospital and transport intubation. Emergency medical services in rural United States counties deploy these for extended response times without fixed power access.
- Integrated:Fixed-base systems with cart-mounted monitors and video recording capabilities for teaching and quality assurance. University hospitals in Germany drive specification of high-definition CMOS variants for residency training programs.
- Lightweight:Reduced-mass blade designs for pediatric and difficult airway applications requiring extended manipulation. Pediatric specialists in tertiary centers specify these for neonatal intubation protocols.
Reusable systems hold installed capacity. Disposable formats are rotating up the share rankings.
Technology:
Imaging modality selection determines power consumption, resolution ceilings, and supply chain exposure to semiconductor foundries or optical glass specialists.
- Optical:Lens-based direct visualization through prismatic or mirror arrangements without electronic amplification. Legacy systems in resource-constrained settings retain these for mechanical reliability absent electronic failure modes.
- Digital:Electronic image capture with signal processing for contrast enhancement and glare reduction. These platforms are expanding most quickly as CMOS costs decline and image processing algorithms mature.
- Fiberoptic:Flexible glass or plastic fiber bundles transmit illumination and image data through curved pathways. Military medicine procurement specifications in field trauma applications specify these for shock and vibration tolerance.
- CMOS Sensor:Complementary metal-oxide-semiconductor arrays enabling 720p to 1080p resolution at sub-watt power draw. German university hospitals specify high-definition CMOS platforms for difficult airway documentation and teaching archives.
- High-Definition:1080p or higher resolution standards with enhanced dynamic range for glottic visualization in obscured airways. Tertiary referral centers with fellowship programs invest in these for complex case documentation.
- Laser:Structured light or coherent illumination for depth mapping and surface topography in research configurations. Experimental deployment in academic medical centers explores augmented intubation guidance.
CMOS Sensor commands current procurement preference. Digital platforms are climbing the fastest.
Application:
Clinical setting determines device durability, portability, and documentation requirements across institutional and field deployment contexts.
- General Surgery:Operating room intubation for elective procedures with standardized positioning and anesthesia support. High-volume surgical suites in United States community hospitals specify integrated CMOS systems for throughput efficiency.
- Emergency Care:Rapid-sequence intubation in chaotic environments with unfasted patients and limited positioning control. Pre-hospital services across rural United States counties deploy portable battery-powered units for scene and transport intubation.
- Military Medicine:Tactical field care under threat conditions with environmental exposure and prolonged evacuation chains. Expeditionary medical units prioritize ruggedized fiberoptic configurations for temperature and shock tolerance.
- Pediatric Care:Neonatal and infant airway management with anatomical constraints and oxygen reserve limitations. Tertiary children's hospitals specify lightweight blade geometries and reduced-diameter configurations.
- Ambulatory Surgery:Same-day discharge procedures requiring rapid turnover and minimal postoperative airway monitoring. United States ASCs are driving disposable format adoption to eliminate reprocessing delays and documentation.
- Critical Care:ICU intubation with hemodynamic instability, coagulopathy, and limited neck mobility. Academic medical centers integrate video laryngoscopy with difficult airway carts and fiberoptic backup protocols.
General Surgery maintains procedure volume concentration. Ambulatory Surgery is gaining share fastest.
End User:
Customer type shapes procurement channel access, capital availability, and clinical training infrastructure for device deployment.
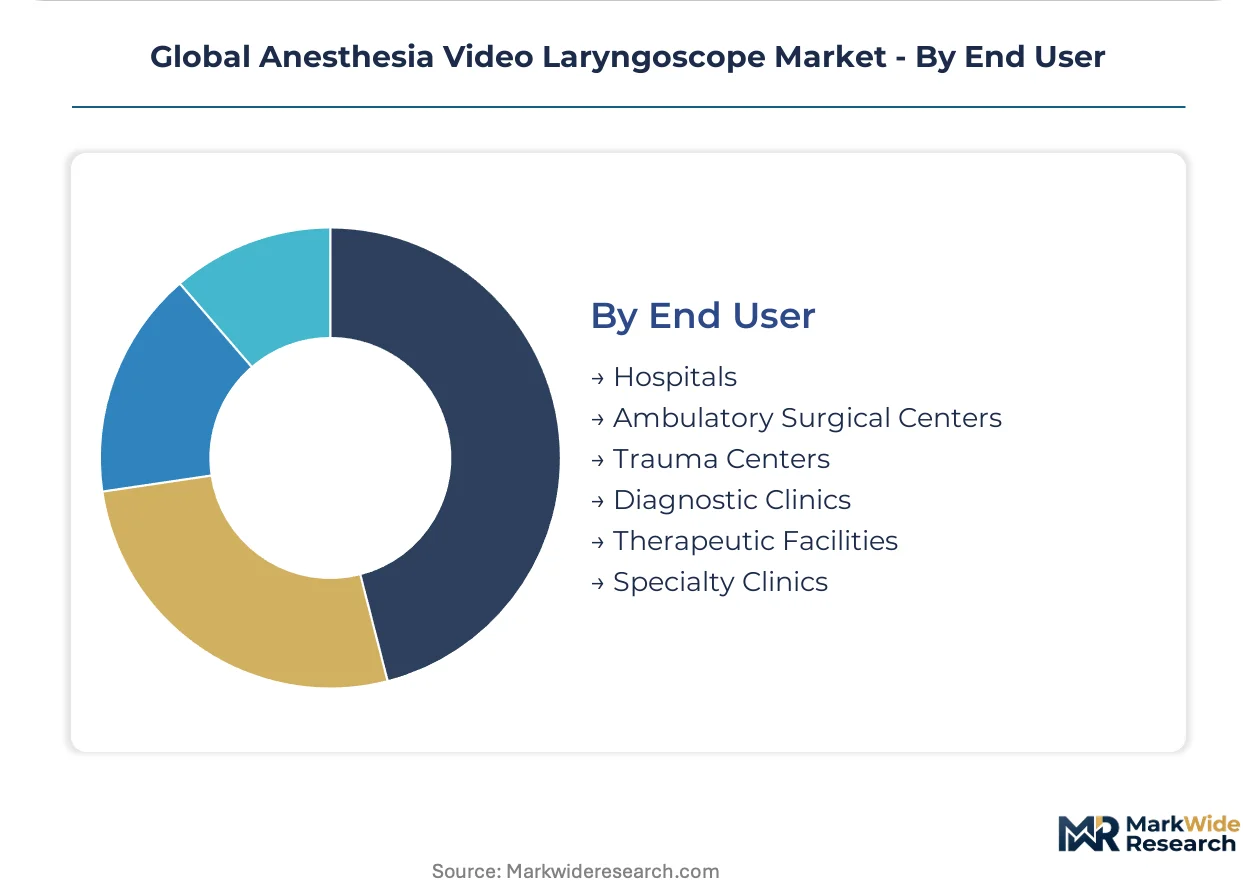
- Hospitals:Multi-specialty institutions with anesthesia departments, operating room suites, and in-house sterilization capacity. German university hospitals anchor procurement of high-definition CMOS platforms with integrated teaching capabilities.
- Ambulatory Surgical Centers:Freestanding same-day surgery facilities with streamlined workflows and infection control mandates. United States ASCs are accelerating disposable video laryngoscope adoption to eliminate sterilization infrastructure.
- Trauma Centers:Level I and II emergency departments with 24-hour anesthesia coverage and difficult airway protocols. These facilities specify portable backup units for resuscitation bay deployment.
- Diagnostic Clinics:Outpatient facilities performing bronchoscopy or sleep study procedures requiring airway assessment. Pulmonology-focused practices in urban United States markets acquire mid-tier CMOS systems for office-based procedures.
- Therapeutic Facilities:Rehabilitation and long-term acute care hospitals managing tracheostomy and ventilator weaning. These settings prioritize reusable formats with established sterilization partnerships.
- Specialty Clinics:ENT, pain management, and dental anesthesia practices with narrow procedure focus. Oral surgery centers in United States metropolitan areas specify integrated systems with video documentation for sedation monitoring compliance.
Hospitals retain installed base dominance. Ambulatory Surgical Centers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA material safety mandates for battery-powered airway devices are reshaping procurement patterns in the United States while EU MDR conformity timelines compress European market entry. German optical fabrication clusters and Japanese precision component suppliers anchor supply-side concentration for high-definition imaging platforms.
United States
Ambulatory surgical centers in Florida and Texas are accelerating disposable blade procurement to eliminate sterilization infrastructure costs. FDA 510(k) clearance timelines for reusable device reprocessing are extending, favoring single-use format transitions. Academic medical centers in Boston and Houston specify integrated CMOS platforms with video documentation capabilities for residency training.
Germany
University hospitals in Bavaria and North Rhine-Westphalia drive procurement of high-definition CMOS platforms with teaching archive integration. EU MDR notified body capacity constraints favor established quality management systems, accelerating certificate capture by domestic manufacturers. Tübingen and Berlin optical fabrication clusters supply precision lens assemblies to global device makers.
Japan
Metropolitan Tokyo hospitals specify fiberoptic configurations for difficult airway protocols requiring shock tolerance. PMDA regulatory alignment with IEC 60601 electrical safety standards shapes battery-powered portable unit development. Nagoya precision component suppliers dominate high-grade fiberoptic bundle fabrication for military and field medicine applications.
India
Secondary city hospitals in Maharashtra and Karnataka are expanding mid-tier CMOS platform adoption as CDSCO regulatory alignment with global standards opens market access. Government procurement programs for district hospital infrastructure are creating volume opportunities for portable configurations. Chennai and Hyderabad medical device assembly clusters are scaling disposable blade production for domestic and export markets.
China
Tier-one hospitals in Shanghai and Beijing specify integrated operating room ecosystems bundling video laryngoscopy with surgical navigation. NMPA material safety requirements for reusable device reprocessing are tightening, accelerating interest in single-use alternatives. Shenzhen semiconductor foundries are capturing CMOS sensor sourcing relationships previously held by Japanese and German suppliers.
Global Anesthesia Video Laryngoscope Market Competitive Landscape
Optical heritage specialists and semiconductor-integrated platforms split the market along technology sourcing lines. The vendor base concentrates around German precision fabrication, Japanese fiberoptic supply, and emerging Chinese CMOS integration capabilities. Two strategic archetypes dominate: legacy endoscopic manufacturers with in-house optical production and diversified medtech conglomerates with anesthesia portfolio breadth. Competitive moves center on M&A for optical component supply security and direct hospital contracting to bypass distributor intermediaries.
Within the optical heritage tier, KARL STORZ SE & Co. KG exemplifies German in-house fabrication capabilities, while Teleflex Incorporated and Medtronic plc occupy positions as diversified anesthesia portfolio anchors. These three represent distinct strategic postures: captive optical production, specialized airway focus, and integrated operating room ecosystem bundling respectively.
| Leading Market Players |
|---|
| KARL STORZ SE & Co. KG |
| Teleflex Incorporated |
| Verathon Inc. |
| Vyaire Medical Inc. |
| Pentax Medical |
| Medtronic plc |
| Olympus Corporation |
| Clarus Medical LLC |
| Ambu A/S |
| Others |
Supply & Pricing Matrix
Undercapacity at German precision optical fabrication facilities is tightening component availability and compressing margin structures for CMOS-integrated platform manufacturers. This utilization squeeze simultaneously elevates input costs for high-definition imaging arrays and reinforces pricing power among incumbent suppliers with captive lens production.
Pricing Analysis
Geographic price spreads between German university hospital procurement and Indian secondary city tenders exceed three-to-one on equivalent CMOS sensor specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification tier and after-sales service bundling. Pricing pressure stems from FDA material safety mandates extending reusable device reprocessing compliance costs. Ambulatory surgical centers exhibit highest price sensitivity due to sterilization infrastructure elimination mandates, while German academic medical centers prioritize performance over unit economics.
Supply Chain Analysis
Extended payment terms from Japanese fiberoptic bundle suppliers are compressing working capital cycles for portable unit assemblers. Component sourcing draws from German precision lens clusters, Japanese fiberoptic fabrication, and emerging Shenzhen semiconductor foundries. Critical dependencies include CMOS sensor wafers, autoclavable polymer resins, and high-grade optical glass. Single-source vulnerability concentrates in military-specification fiberoptic bundles from Nagoya suppliers. Distribution runs through direct manufacturer contracts displacing group purchasing organization intermediaries, with specialty distributors capturing clinical training service margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware attachment rates for software-enabled remote airway consultation and video archive licensing are expanding faster than device unit shipments, repositioning vendor economics toward recurring service layers.
For Market Incumbents: Pre-empt disposable format commoditization by securing exclusive CMOS sensor supply agreements with Shenzhen foundries before capacity constraints tighten. Defend installed base positions in German university hospitals through integrated teaching archive subscriptions that embed switching costs. Channel control via direct contracting with academic medical center procurement teams neutralizes group purchasing organization leverage erosion. For New Entrants and Emerging Players: Mid-tier CMOS platforms for Indian secondary city hospitals represent the most penetrable entry point given CDSCO regulatory alignment and government infrastructure procurement volume. Portable battery-powered configurations for United States rural emergency medical services offer white-space expansion with lower certification burden than fixed-base systems. Go-to-market execution should prioritize specialty distributors with pre-hospital clinical training capabilities over broad-line medical device wholesalers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable blade manufacturing as semiconductor integration reduces optical component fabrication requirements. Five-to-ten year viability favors acquisition targets with established EU MDR quality management systems and German notified body relationships rather than pure technology plays. The signal to watch is FDA guidance timeline compression on reusable device reprocessing, which would accelerate format transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certificate Capture | Accelerates market access as notified body capacity constraints favor established quality systems. |
| CMOS Sensor Supply Agreement | Secures semiconductor foundry allocation before precision optical component shortages intensify. |
| Direct Hospital System Partnership | Bypasses group purchasing organization intermediaries to capture margin and clinical training revenue. |
| Software Companion Development | Enables 5G-enabled remote airway consultation service layers with recurring licensing economics. |
| Reimbursement Strategy Investment | Positions disposable formats for ambulatory surgical center procurement under infection control mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with anesthesiologists, hospital purchasing committee members, biomedical engineers, group purchasing organization contracts managers, and emergency medical services directors. Secondary validation drew from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and GPO contract disclosure records. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Calibration against historical CMOS sensor cost curves and optical component pricing indices anchored volume and value outputs across the modeling period. Segmentation dimensions included product configuration, imaging technology, clinical application, end-user facility type, and regional regulatory cluster. CAGRs derived from procedure volume growth rates, technology substitution curves, and format mix shift assumptions. Forecast inputs incorporated EU MDR implementation timelines and FDA guidance evolution on reusable device reprocessing.
Practitioners should monitor notified body capacity constraints, FDA material safety guidance releases, and CMOS foundry utilization rates for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Specimen Retrieval Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Telehealth Device Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Appendage Management Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
Pulmonology Devices Market