
 Electromagnetic Navigation Bronchoscopy Market | 2026-2036
Electromagnetic Navigation Bronchoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Navigation Bronchoscopy Market Analysis
North American manufacturing capacity for electromagnetic navigation bronchoscopy systems is rewriting supply assumptions for the interventional pulmonology sector. Medtronic leverages its integrated surgical ecosystem to sustain installed-base loyalty across hospital networks. Noah Medical anchors its position through robotic-assisted bronchoscopy specialization. Body Vision Medical competes on compact, portable system architecture for outpatient deployment.
Electromagnetic navigation bronchoscopy employs sensor-tipped instruments tracked via low-frequency electromagnetic fields to guide peripheral lung lesion sampling with sub-centimeter accuracy, typically operating at field frequencies between 1–30 kHz and requiring electromagnetic field generators positioned adjacent to the patient. The technology serves primarily to diagnose suspicious peripheral pulmonary nodules inaccessible through conventional bronchoscopy. Robotic-assisted platforms represent the fastest-expanding product category as procedural consistency demands intensify. Navigation systems command the dominant share of product-type revenue, though software modules exhibit the steepest margin expansion potential through recurring licensing structures. Hospital end users absorb the majority of capital equipment placements, while specialty clinics represent the emerging growth vector for smaller-footprint configurations.
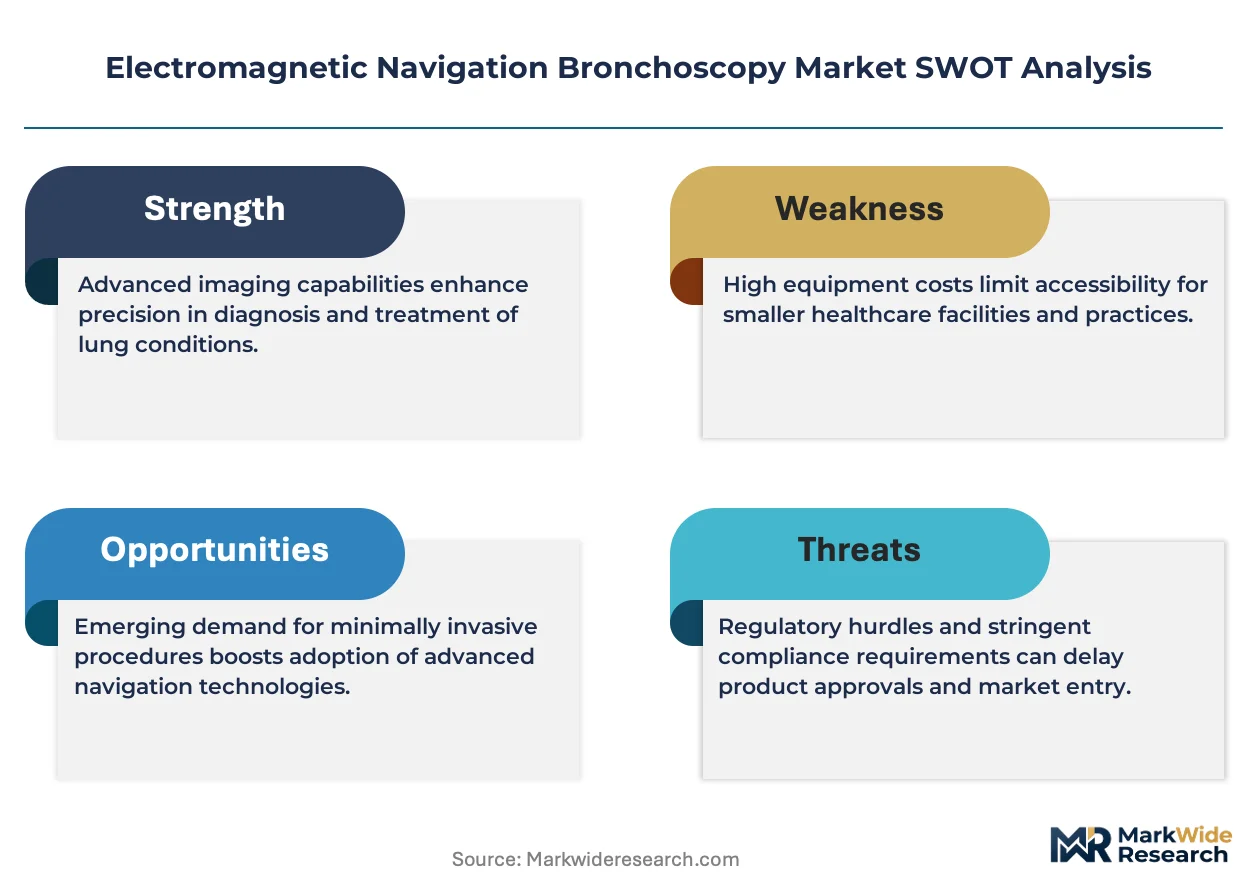
FDA premarket notification requirements govern device commercialization in the United States, with the agency's breakthrough device designation pathway accelerating access for innovations targeting lung cancer diagnosis. The EU Medical Device Regulation imposes strengthened clinical evidence standards for electromagnetic navigation systems marketed in Europe, extending conformity assessment timelines. Stakeholders must monitor evolving reimbursement coding for robotic bronchoscopy procedures, as coverage determinations will dictate capital deployment velocity across health systems regardless of technical performance benchmarks.
Market Dynamics
Robotic-assisted bronchoscopy platforms are compressing the procedural learning curve for interventional pulmonologists, fundamentally altering how hospital systems evaluate capital deployment against traditional manual navigation systems. This technological inflection is redistributing value capture toward integrated platform vendors while fragmenting the aftermarket for disposable components.
Growth Catalysts
- Lung Cancer Screening Expansion:Medicare reimbursement for low-dose CT screening in the United States is generating a pipeline of peripheral nodules requiring tissue diagnosis, directly expanding addressable procedure volumes for navigation bronchoscopy systems.
- EU Medical Device Regulation:MDR's strengthened clinical evidence requirements, while extending conformity timelines, are creating competitive moats for manufacturers with robust trial infrastructure and punishing marginal players lacking post-market surveillance capabilities.
- Sensor Miniaturization:Advances in electromagnetic coil fabrication are enabling smaller-diameter working channels, allowing navigation to sub-centimeter lesions previously inaccessible through standard bronchoscopes.
Market Restraints
- Capital Intensity:Robotic platform acquisition costs exceeding $500,000 per unit, plus annual service contracts, constrain penetration outside academic medical centers and large health system networks.
- Supply Concentration:Electromagnetic field generator components rely on specialized ferrite core suppliers concentrated in East Asian manufacturing clusters, exposing OEMs to geographic supply disruption risk.
- Procedural Reimbursement Uncertainty:CMS valuation of robotic-assisted bronchoscopy codes remains contested, with commercial payor coverage determinations lagging technology diffusion and creating revenue recognition delays for hospital adopters.
Strategic Opportunities
- Ambulatory Surgical Centers:Compact, portable navigation configurations are opening deployment in outpatient settings previously excluded by footprint and infrastructure requirements, with specialty pulmonology clinics representing untapped placement volume.
- Artificial Intelligence Integration:Convergence of real-time navigation software with machine learning-based nodule segmentation is enabling autonomous pathway planning, reducing operator dependence and expanding addressable physician base.
- Japan's Aging Demographics:METI's healthcare innovation subsidies and elevated lung cancer incidence among elderly populations are accelerating regulatory review timelines for navigation devices, creating favorable market entry conditions.
Industry Challenges
- Interventional Pulmonology Training Pipeline:Fellowship programs produce insufficient operators trained in advanced bronchoscopic techniques, creating a bottleneck between installed base expansion and sustainable procedure volume growth.
- Legacy EMR Integration:Navigation systems must interface with heterogeneous hospital information architectures, requiring costly custom middleware development and extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Navigation Bronchoscopy Market |
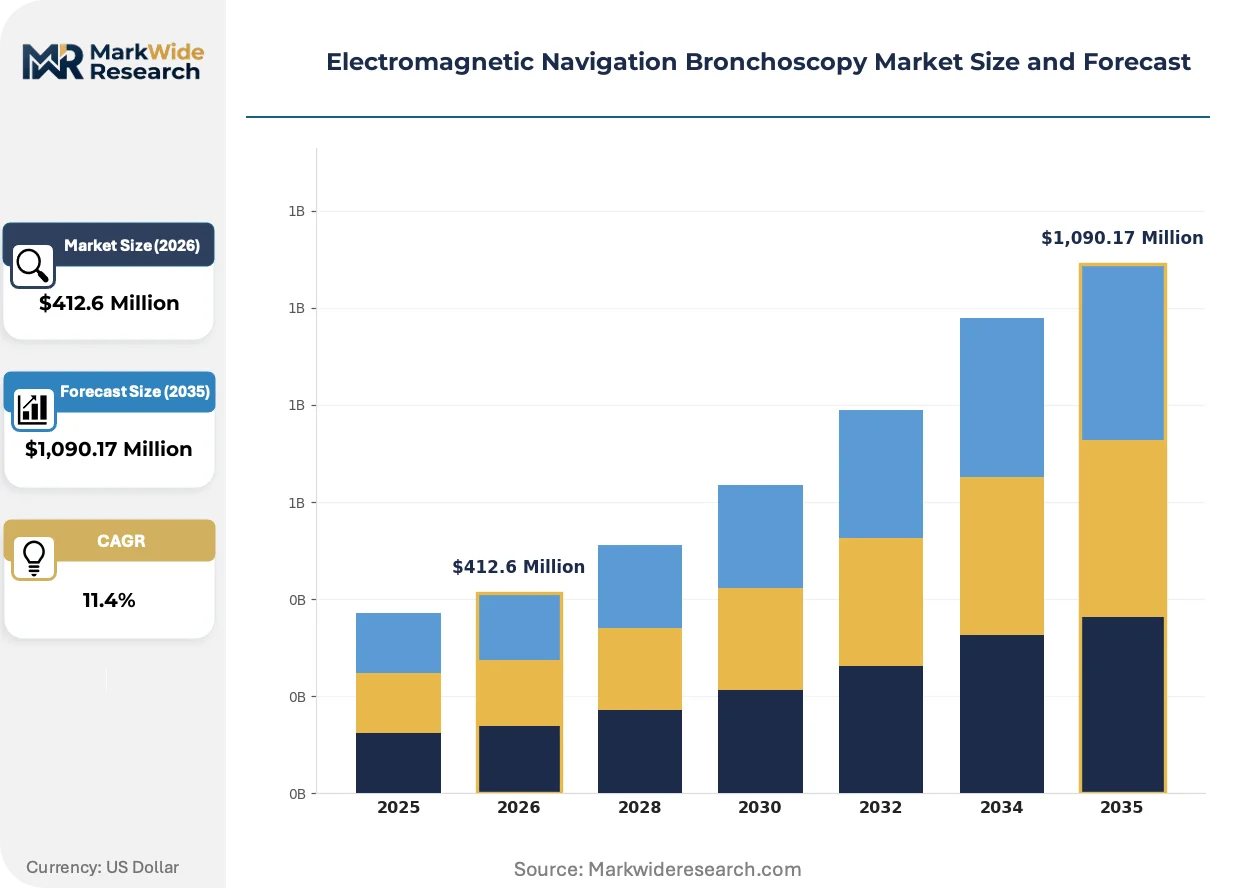
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromagnetic, Optical Navigation, Image-guided, Robotic-assisted Product Type: Bronchoscopes, Navigation Systems, Accessories, Software End User: Hospitals, Specialty Clinics, Research Institutions, Outpatient Centers Procedure Type: Diagnostic, Therapeutic, Interventional, Surgical |
| Companies Covered | Medtronic, Olympus Corporation, Intuitive Surgical, Boston Scientific, Veran Medical Technologies, Body Vision Medical, Noah Medical, LungCare, Broncus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Navigation Bronchoscopy Market Emerging Trajectories
Convergence of robotic mechanics with electromagnetic tracking is dissolving the historical trade-off between procedural precision and operator ergonomics, enabling new clinical workflows that were technically infeasible under manual navigation paradigms.
Shape-sensing fiber optic technology is collapsing the distinction between electromagnetic and alternative navigation modalities by providing real-time instrument localization without external field generators. Academic medical centers in the United States are piloting these systems for complex peripheral biopsies, compressing capital equipment requirements and enabling deployment in smaller procedure rooms previously excluded by electromagnetic shielding needs.
MDR's post-market surveillance obligations are compelling manufacturers to invest in prospective registry data collection. European notified bodies now demand continuous safety monitoring for Class III bronchoscopic devices, extending conformity assessment timelines but elevating clinical evidence standards that favor established players with robust quality management systems. Pulmonology departments in Germany and France are prioritizing MDR-certified platforms in procurement evaluations.
Hospital value analysis committees are unbundling capital acquisition from disposable supply agreements, forcing vendors to compete on per-procedure economics rather than bundled pricing. Integrated delivery networks in the United States are consolidating purchasing authority at system level, compressing vendor negotiation leverage and standardizing platform selections across multiple hospital sites. This concentration is most visible in the southeastern United States, where regional health systems have centralized interventional pulmonology capital planning.
Electromagnetic Navigation Bronchoscopy Market Segmentation
Technology choices in electromagnetic navigation bronchoscopy dictate capital deployment cycles, with some platforms requiring five-year replacement horizons while others extend to eight years. Understanding segment turnover patterns enables vendors to align R&D pipelines with hospital budget calendars and anticipate upgrade demand windows.
Technology:
Cycle times vary dramatically across navigation modalities, with electromagnetic field generators requiring recalibration every 12-18 months while robotic platforms demand full replacement every 5-7 years.
- Electromagnetic:Low-frequency field generators operating at 1-30 kHz track sensor-tipped instruments with sub-centimeter accuracy. Pulmonology departments in academic medical centers favor this technology for its established reimbursement pathways and proven clinical validation, though electromagnetic shielding requirements constrain procedure room selection.
- Robotic-assisted:Integrated mechanical arms combine electromagnetic tracking with motorized instrument control, compressing the procedural learning curve for interventional pulmonologists. Hospital systems in the United States prioritize this segment for physician recruitment and retention, despite capital costs exceeding $500,000 per unit.
- Optical Navigation:Camera-based tracking eliminates electromagnetic interference concerns, enabling deployment in standard procedure rooms without shielding modifications.
- Image-guided:CT or fluoroscopy overlay systems provide anatomical context but require radiation exposure protocols and specialized training.
Electromagnetic systems dominate installed base. Robotic-assisted platforms are where expansion concentrates.
Product Type:
Margin profiles diverge sharply between capital equipment with single-digit service contract renewals and disposable accessories generating recurring revenue streams.
- Navigation Systems:Electromagnetic field generators and tracking consoles anchor platform ecosystems, typically sold with multi-year service agreements. Large health system networks in the United States consolidate purchasing authority at system level, compressing vendor negotiation leverage for these capital placements.
- Software:Pathway planning modules and real-time visualization platforms command the steepest margin expansion potential through recurring licensing structures. Integrated delivery networks prioritize vendors offering seamless EMR interoperability, extending implementation timelines but reducing long-term IT maintenance burdens.
- Bronchoscopes:Flexible scopes with electromagnetic sensor compatibility enable peripheral lesion access.
- Accessories:Disposable biopsy tools, needles, and brushes generate per-procedure revenue.
Navigation systems anchor vendor revenue. Software licensing is climbing the fastest.
End User:
Facility type determines infrastructure requirements, with hospitals absorbing complex shielding installations while outpatient centers demand portable configurations.
- Hospitals:Academic medical centers and tertiary care facilities absorb the majority of capital equipment placements, driven by lung cancer screening program volumes and interventional pulmonology fellowship training pipelines. Value analysis committees in these settings unbundle capital acquisition from disposable supply agreements, forcing per-procedure economic competition.
- Specialty Clinics:Compact, portable navigation configurations enable deployment in outpatient settings previously excluded by footprint requirements. Pulmonology-focused practices in the southeastern United States represent untapped placement volume as regional health systems centralize capital planning.
- Outpatient Centers:Ambulatory surgical centers seek smaller-footprint systems for same-day biopsy procedures.
- Research Institutions:Clinical trial sites drive demand for investigational device configurations.
Hospitals dominate installed base. Specialty clinics are where expansion concentrates.
Procedure Type:
Reimbursement coding stability varies across clinical applications, with diagnostic procedures enjoying established coverage while therapeutic indications face valuation disputes.
- Diagnostic:Tissue sampling of suspicious peripheral pulmonary nodules represents the primary application, directly linked to low-dose CT screening program expansion. Medicare reimbursement for these procedures in the United States generates predictable procedure volumes, though commercial payor coverage determinations lag technology diffusion.
- Interventional:Combined diagnostic-therapeutic workflows including fiducial marker placement and localized drug delivery command premium reimbursement when prior authorization requirements are met.
- Therapeutic:Tumor ablation and stent placement applications face contested CMS valuation.
- Surgical:Pre-operative localization for video-assisted thoracoscopic resection remains niche.
Diagnostic procedures dominate installed base. Interventional applications are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for novel bronchoscopic devices anchor commercialization strategy in the United States, while lung cancer screening program expansion drives procedure volumes. Academic medical centers in Germany and Japan are accelerating platform adoption through targeted healthcare innovation subsidies.
United States
Medicare reimbursement for low-dose CT screening generates a pipeline of peripheral nodules requiring tissue diagnosis, expanding addressable procedure volumes for navigation bronchoscopy systems. FDA breakthrough device designation accelerates market access for innovations targeting lung cancer diagnosis. Pulmonology departments in the southeastern United States are consolidating capital planning at regional health system level.
Germany
EU Medical Device Regulation post-market surveillance obligations compel manufacturers to invest in prospective registry data collection for Class III bronchoscopic devices. Pulmonology departments in Germany prioritize MDR-certified platforms in procurement evaluations. The Ruhr industrial cluster hosts specialized ferrite core suppliers critical to electromagnetic field generator production.
Japan
METI healthcare innovation subsidies and elevated lung cancer incidence among elderly populations accelerate regulatory review timelines for navigation devices. PMDA streamlined approval pathways favor manufacturers with robust clinical trial infrastructure. Tokyo academic medical centers pilot shape-sensing fiber optic systems for complex peripheral biopsies.
China
NMPA medical device registration requirements govern commercialization of electromagnetic navigation systems, with priority review pathways for cancer diagnostic innovations. Domestic manufacturing of electromagnetic field generator components concentrates in Shenzhen and Suzhou industrial zones. Shanghai tertiary hospitals absorb the majority of imported platform placements.
Electromagnetic Navigation Bronchoscopy Market Vendor Landscape
Integrated platform vendors and specialized navigation technology developers split the market along capital intensity lines. Hospital procurement committees evaluate bundled ecosystem offerings against best-of-breed component architectures. Diversified medical technology conglomerates and focused bronchoscopy specialists represent the dominant strategic archetypes. Competitive dynamics center on installed-base loyalty programs and per-procedure disposable supply agreements.
Within the diversified technology tier, Medtronic leverages integrated surgical ecosystem breadth, while Olympus Corporation anchors endoscopic instrument manufacturing scale. Noah Medical occupies a position exemplifying robotic-assisted specialization. These three entities represent contrasting strategic postures: ecosystem integration, manufacturing depth, and robotic platform focus respectively.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| Intuitive Surgical |
| Boston Scientific |
| Veran Medical Technologies |
| Body Vision Medical |
| Noah Medical |
| LungCare |
| Broncus Medical |
| Others |
Supply Flow & Price Mechanics
Undercapacity in East Asian ferrite core manufacturing is driving extended lead times for electromagnetic field generator components, compressing OEM margins while elevating pricing power among specialized suppliers serving the interventional pulmonology sector. This utilization imbalance propagates through the value chain, forcing navigation system vendors to absorb cost increases or accelerate qualification of alternative coil fabrication sources.
Pricing Analysis
Geographic price spreads between United States and Japanese procurement contracts for robotic-assisted platforms exceed twenty percent, reflecting divergent reimbursement environments and service bundling practices. The dominant pricing structure combines capital equipment placement with per-procedure disposable commitments, though software licensing modules increasingly migrate toward recurring SaaS tiers. Price differentiation rests on FDA breakthrough designation status and EMR interoperability certification, with academic medical centers least sensitive to upfront capital outlays while specialty clinics prioritize per-procedure economics. Pricing pressure stems from hospital value analysis committees unbundling capital and supply agreements, eroding vendor bundling leverage.
Supply Chain Analysis
Supplier financing facilities extended by Japanese trading houses are stabilizing working capital for ferrite core manufacturers concentrated in China, South Korea, and Japan, insulating upstream production from liquidity shocks. Electromagnetic navigation systems draw from specialized ferrite cores, precision-wound sensor coils, and robotic actuator assemblies. Single-source vulnerability concentrates in high-permeability ferrite formulations governed by proprietary sintering processes. Distribution runs through integrated delivery network procurement offices in the United States and hospital group purchasing organizations in Europe, with direct OEM-to-hospital contracting gaining share for robotic platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in electromagnetic navigation bronchoscopy are undergoing an interoperability inflection as hospital systems demand seamless EMR integration, rewarding vendors with established IT infrastructure partnerships over point-solution specialists.
For Market Incumbents: Entrench installed-base loyalty through captive supply agreements for disposable biopsy tools, locking specialty clinics into per-procedure revenue streams. Deepen backward integration into electromagnetic sensor coil manufacturing to insulate margin structures from East Asian ferrite price volatility. Prioritize MDR certification maintenance as European notified bodies elevate post-market surveillance thresholds.
For New Entrants and Emerging Players: Build out ambulatory surgical center deployment capabilities with compact, shielding-free optical navigation configurations, exploiting the white-space left by robotic platform footprint constraints. Target southeastern United States regional health systems where capital planning centralization creates demand for standardized, lower-cost alternatives. Pursue GPO contract qualification as the primary go-to-market channel.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software pathway planning vendors with established hospital IT integration, offering superior cash flow predictability against capital-intensive robotic hardware plays. Long-term viability favors platform-agnostic navigation software over single-modality hardware manufacturers. Monitor FDA breakthrough device designation grants as the critical signal for reimbursement pathway acceleration and valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts lock multi-site standardization, securing installed base across regional networks. |
| Software Companion Development | AI-powered nodule segmentation modules command recurring licensing fees, shifting revenue toward predictable SaaS structures. |
| Reimbursement Strategy | CMS coding valuation for robotic-assisted procedures determines hospital capital deployment velocity regardless of technical merit. |
| CE Marking Pathway | MDR conformity assessment timelines favor manufacturers with robust clinical trial infrastructure and quality management systems. |
| Backward Integration | In-house production of electromagnetic sensor coils reduces exposure to East Asian ferrite supply concentration and price volatility. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS reimbursement determinations, and EU MDR notified body guidance documents. Interviews with interventional pulmonologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers informed demand-side dynamics. Secondary validation drew from hospital procurement databases, patent filings, and trade customs records. Bottom-up procedure volume estimates triangulated against top-down capital equipment placement data.
Forecast inputs span technology modality, product type margin profile, end-user facility tier, and procedure reimbursement status across the projection horizon. Segmentation dimensions modeled include navigation technology, capital versus disposable revenue mix, hospital versus outpatient setting, and diagnostic versus interventional application. CAGRs derive from installed base turnover cycles, procedure volume expansion linked to lung cancer screening penetration, and software licensing attach rates. Industry-specific inputs incorporate fellowship training pipeline output and electromagnetic shielding infrastructure availability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified surgical robotics conglomerates or shape-sensing fiber optic entrants would shift outcomes. Macroeconomic contraction affecting hospital capital budgets, regulatory delay in robotic procedure reimbursement, or technological disruption from alternative navigation modalities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Transilluminators Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Coated Endotracheal Tube Market