
 Balloon Inflation Devices Market | 2026-2036
Balloon Inflation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Balloon Inflation Devices Market Analytics
The balloon inflation devices market is expanding along a sharp split between premium medical-grade systems and commodity party or retail pumps. Boston Scientific Corporation leverages in-house pressure sensor manufacturing to command premium positioning in cardiac catheterization. Terumo anchors its presence across Asia-Pacific through dedicated interventional cardiology distribution networks. B. Braun Medical competes on sterile single-use configurations that align with hospital infection control protocols.
Balloon inflation devices are mechanical or electromechanical instruments designed to deliver controlled pressure volumes, typically calibrated in atmospheres or psi, to expand balloons during medical interventions or commercial applications. Medical variants incorporate digital pressure displays, Luer-lock connections, and compliance charts to prevent overinflation during angioplasty or stent deployment. Electric pumps for medical procedures lead value generation given their precision requirements and higher replacement cycles, while manual pumps for party decorations occupy a mature, price-sensitive tier with thinner margins. Gas-filled canisters for sports events represent a growing niche driven by portable field-use requirements.
FDA 510(k) premarket notification requirements and the EU MDR conformity assessment process shape product development timelines and clinical evidence burdens for manufacturers seeking dual-market access. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification by hospital procurement departments in the United States and European Union. Stakeholders must monitor evolving pressure accuracy standards and regional reimbursement shifts for interventional procedures to align portfolio investments with regulatory-validated demand.
Market Dynamics
Electric pump systems are displacing manual inflation devices in catheterization labs as pressure precision becomes the decisive procurement criterion for interventional cardiology suites.
Growth Catalysts
- EU MDR pressure documentation mandates:Hospitals across Germany and France are upgrading to digital pressure-indicating systems to satisfy enhanced clinical evidence requirements for Class IIa medical devices.
- Interventional cardiology procedure volumes:Aging demographics in Japan and the United States are expanding patient throughput in cardiac catheterization units, directly lifting replacement cycles for inflation equipment.
- Sterile single-use configurations:Infection control protocols in Western European hospitals are mandating disposable pressure delivery systems, eliminating cross-contamination risks in high-volume procedural settings.
Market Restraints
- Specialized polymer supply concentration:Medical-grade silicone and polyurethane diaphragms for pressure chambers originate from a narrow supplier base in Germany and Switzerland, creating input vulnerability.
- FDA 510(k) clinical evidence burdens:Premarket notification pathways for novel pressure-sensor integrations require extensive predicate device comparisons, extending development timelines.
- Manual pump substitution in cost-sensitive settings:Budget-constrained outpatient clinics in secondary markets continue relying on analog inflation systems, capping premium system penetration.
Strategic Opportunities
- Portable field-use gas canisters:Sports medicine and emergency response units in Australia and Canada are adopting lightweight CO2 inflation systems for rapid balloon deployment outside hospital infrastructure.
- ISO 13485-certified contract manufacturing:Original equipment manufacturers are outsourcing pressure-sensor assembly to specialized electronics foundries, reducing capital intensity for market entry.
- Digital compliance chart integration:Software-embedded pressure curves that auto-populate electronic health records are creating preference pull from hospital IT procurement committees.
Industry Challenges
- Pressure calibration technician scarcity:Servicing electromechanical pump systems requires specialized biomedical engineering expertise that outpaces training program output in the United States and United Kingdom.
- Legacy Luer-lock interoperability:New digital inflation devices must maintain backward compatibility with existing catheter connector standards, constraining industrial design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balloon Inflation Devices Market |
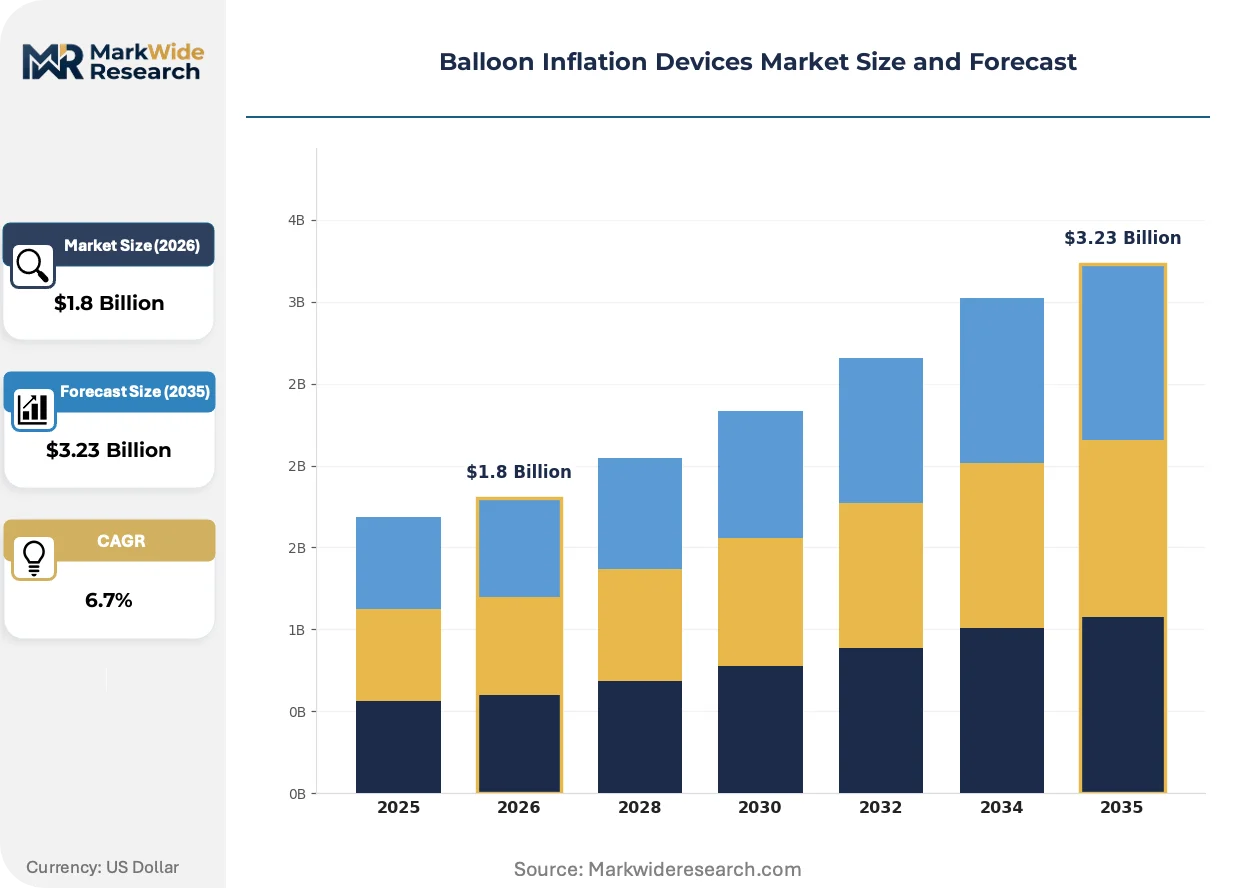
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Manual Pumps, Electric Pumps, Gas-Filled Canisters, Foot Pumps Application: Party Decorations, Medical Procedures, Automotive Repairs, Sports Events End User: Event Planners, Hospitals, Auto Shops, Retail Stores Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Terumo, B. Braun Medical, Boston Scientific Corporation, Becton, Dickinson and Company, Cook Medical, Medtronic, Teleflex Incorporated, Ambu A/S, C.R. Bard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balloon Inflation Devices Market Evolving Landscape
Digital pressure sensing is consolidating control architectures across medical inflation systems, compressing the competitive gap between electromechanical and purely mechanical platforms while elevating performance baselines.
Capacitive pressure transducers with real-time atmospheric compensation are consolidating sensor footprints into single-chip modules. Interventional cardiology suites in tertiary hospitals across the United States and Germany are specifying these integrated units for new catheterization lab builds. The technology is consolidating vendor tiers by collapsing the distinction between premium digital and mid-range analog systems.
EU MDR Annex XIV clinical evaluation requirements are forcing manufacturers to generate post-market surveillance data on pressure accuracy drift over device lifespan. This regulatory load is compressing product development calendars and elevating documentation costs. Class IIa inflation devices face the steepest compliance gradient, with notified bodies in Ireland and the Netherlands extending review timelines.
Hospital procurement committees are bundling inflation device contracts with multi-year preventive maintenance agreements. Integrated delivery networks in the United States are consolidating supplier relationships to capture volume discounts and standardized training protocols. This purchasing consolidation is visible most acutely in the Southeast and Midwest, where health system mergers have concentrated buying power.
Balloon Inflation Devices Market Segmentation
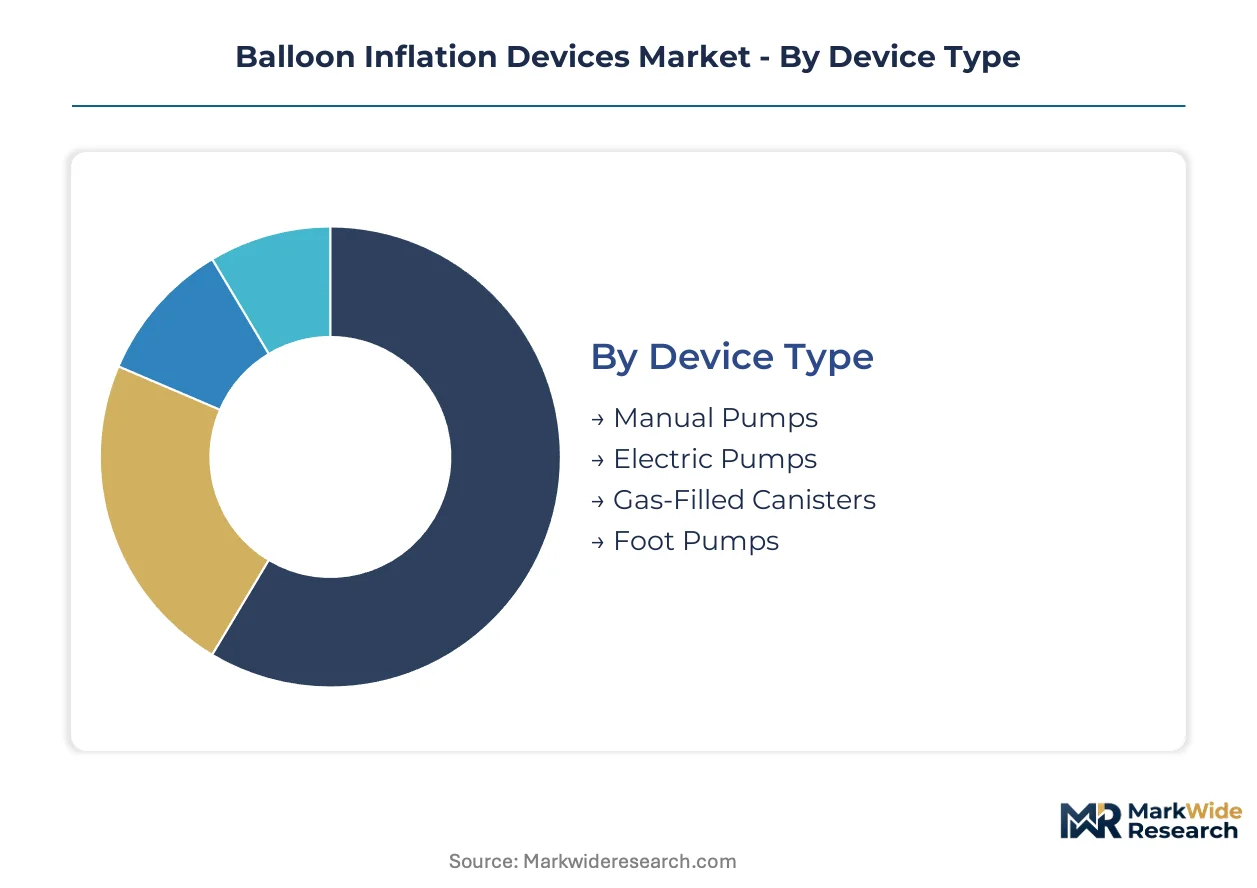
Segmentation in balloon inflation devices separates precision-critical medical systems from commodity-grade alternatives. Supply chain configuration and regulatory burden vary dramatically across these boundaries, dictating margin structures and vendor qualification requirements.
Device Type:
Supply concentration for pressure-sensing components concentrates manufacturing leverage among electromechanical specialists with captive sensor production.
- Manual Pumps:Hand-operated mechanical systems using piston or bellows architectures deliver pressure through analog gauges. Demand clusters in party supply retail across Germany and the United States where cost sensitivity dominates procurement decisions for non-medical applications.
- Electric Pumps:Microprocessor-controlled units with digital pressure displays and programmable stop thresholds serve catheterization labs in Japan and the United States. FDA 510(k) clearance requirements and EU MDR conformity assessments elevate development costs and extend commercialization timelines for new entrants.
- Gas-Filled Canisters:Portable CO2 or helium cylinders with regulated discharge valves enable field deployment without electrical infrastructure.
- Foot Pumps:Pedal-actuated mechanical systems free operator hands during inflation tasks in automotive and light industrial settings.
Electric pumps absorb the bulk of installed capacity in tertiary hospital settings; gas-filled canisters are expanding most quickly in emergency response and sports medicine applications.
Application:
Cost tier separation between regulated medical environments and unregulated consumer markets creates distinct vendor ecosystems with minimal overlap.
- Medical Procedures:Angioplasty, stent deployment, and balloon catheter inflation demand pressure precision within 0.1 atmosphere tolerance. Cardiac catheterization units in the United States and Germany specify digital compliance charting to satisfy Joint Commission and EU MDR documentation mandates.
- Party Decorations:Latex and foil balloon inflation for events and retail represents a mature, price-elastic segment. Volume concentrates in seasonal purchasing patterns through mass-market retail channels in the United States and United Kingdom.
- Automotive Repairs:Tire inflation and sealant deployment systems serve repair shops and roadside assistance providers.
- Sports Events:Rapid inflation of balls, protective equipment, and emergency splints drives demand for portable, field-durable systems in Australia and Canada.
Medical procedures command the highest unit economics and replacement frequency; sports events represent the steepest expansion trajectory as emergency response protocols standardize.
End User:
Customer type determines procurement sophistication, with institutional buyers imposing qualification regimes that exclude commodity vendors.
- Hospitals:Integrated delivery networks and catheterization lab managers specify ISO 13485-certified suppliers with preventive maintenance contracts. Procurement committees in the United States Southeast and Midwest leverage consolidated buying power post-merger to extract volume pricing and standardized training protocols.
- Event Planners:Commercial decorators and rental companies prioritize lightweight portability and rapid setup speed over pressure precision.
- Auto Shops:Service bay operators demand durability and rapid cycling capacity for high-throughput tire service operations.
- Retail Stores:Party supply and general merchandise outlets stock entry-level manual pumps for consumer self-service purchase.
Hospitals absorb the bulk of premium system deployment; event planners are gaining share fastest as experiential spending recovers in urban markets.
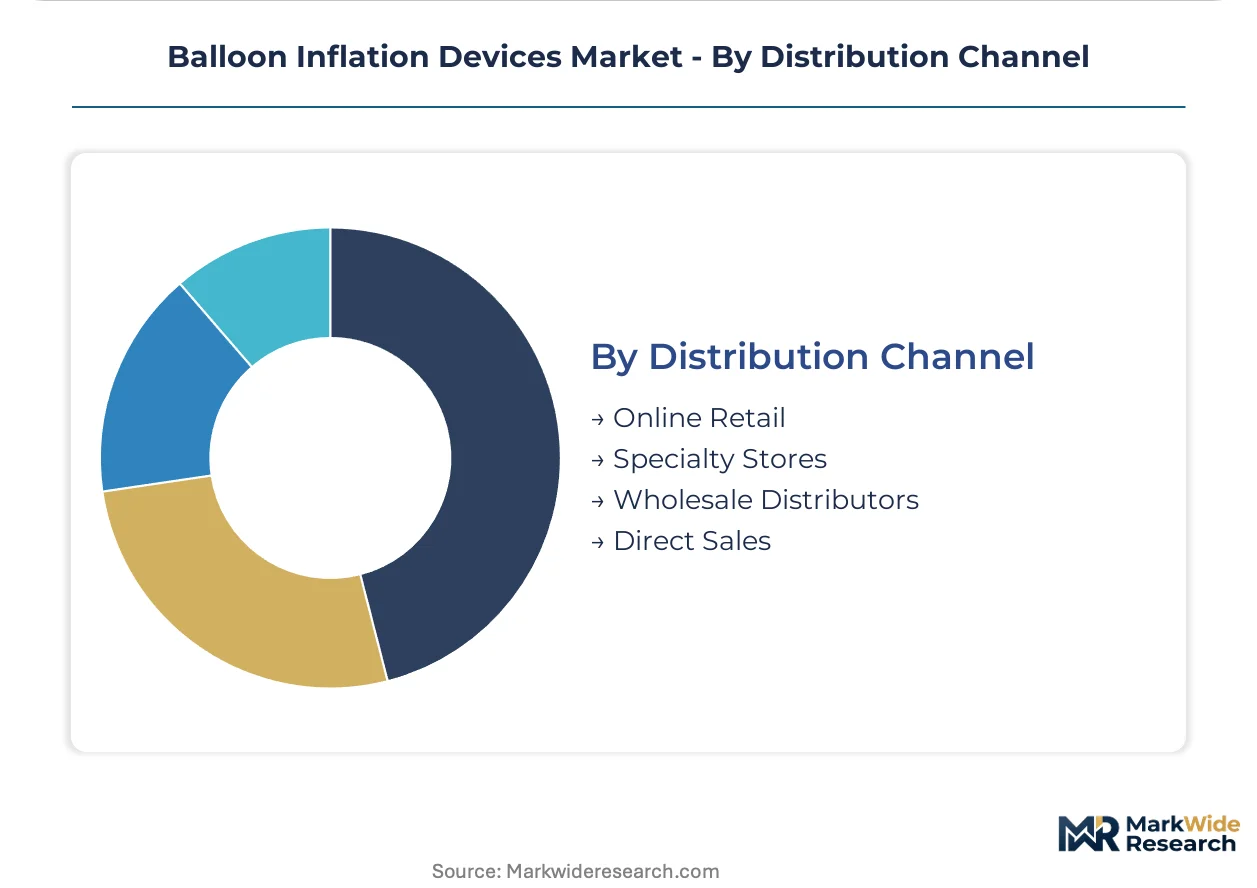
Distribution Channel:
Volume flow through wholesale medical distributors contrasts with direct manufacturer relationships for high-value hospital contracts.
- Specialty Stores:Medical supply distributors and party equipment retailers provide tactile evaluation and immediate availability. German and Japanese hospital procurement departments maintain preferred supplier agreements with regional specialty distributors holding ISO 13485 certification.
- Wholesale Distributors:Broadline medical and industrial distributors aggregate demand across fragmented end users, capturing economies in logistics and inventory carrying costs.
- Online Retail:E-commerce platforms serve price-sensitive consumers and small-scale commercial buyers with limited technical support requirements.
- Direct Sales:Manufacturer field representatives engage hospital value analysis committees for capital equipment purchases and multi-year service agreements.
Specialty stores and wholesale distributors together capture the majority of transaction volume; direct sales is climbing the fastest as health system consolidation concentrates purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American catheterization lab equipment procurement, with integrated delivery networks consolidating inflation device contracts across the Upper Midwest corridor.
United States
Cardiac catheterization units in the Southeast and Midwest are driving electric pump replacement cycles as health system mergers concentrate purchasing authority. FDA 510(k) clearance pathways for pressure-sensor integrations require extensive predicate device comparisons, extending commercialization timelines for new market entrants. Minneapolis-St. Paul and Boston-Worcester corridors host the densest clusters of interventional cardiology suites specifying digital compliance charting.
Germany
Hospitals across Bavaria and North Rhine-Westphalia are upgrading to digital pressure-indicating systems to satisfy EU MDR Annex XIV clinical evidence requirements for Class IIa medical devices. Notified bodies in Ireland and the Netherlands are extending review timelines for inflation device conformity assessments, compressing product development calendars. Frankfurt and Stuttgart medical technology clusters concentrate sterile single-use configuration manufacturing for Western European hospital networks.
Japan
Aging demographics in the Kanto and Kansai regions are expanding patient throughput in cardiac catheterization units, directly lifting equipment replacement demand. PMDA marketing approval pathways align with international standards but impose additional quality system documentation burdens on foreign manufacturers. Tokyo-Osaka interventional cardiology networks anchor Asia-Pacific distribution for premium electromechanical pump systems.
Switzerland
Medical-grade silicone and polyurethane diaphragm suppliers in the Basel-Zurich corridor face capacity constraints as German and French hospital procurement accelerates. Swissmedic conformity assessment procedures for pressure chamber components add regulatory layering to upstream supply chains. The country's precision polymer processing clusters supply critical inputs to EU MDR-compliant inflation device assemblers.
Australia
Emergency response units and sports medicine providers in New South Wales and Victoria are adopting portable CO2 inflation systems for rapid field deployment outside hospital infrastructure. TGA medical device inclusion requirements for pressure delivery systems are less burdensome than EU or US pathways, enabling faster market access for novel gas canister configurations. Sydney-Melbourne procurement networks are standardizing lightweight inflation protocols for pre-hospital care.
Balloon Inflation Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the precision-pressure spectrum, with medical-grade electromechanical specialists commanding pricing power unavailable to manual pump fabricators. The vendor base stratifies into three tiers: integrated multinationals with captive sensor production, regional contract manufacturers holding ISO 13485 certification, and price-driven commodity assemblers serving non-medical applications. Strategic archetypes include precision-electronics integrators, sterile disposable specialists, and field-portable gas system innovators. Dominant competitive moves encompass backward integration into pressure transducer manufacturing and multi-year preventive maintenance bundling with hospital procurement committees.
Within the integrated multinational tier, Terumo Corporation and Boston Scientific Corporation exemplify archetypal positioning through their respective Asia-Pacific distribution depth and in-house sensor manufacturing capabilities. B. Braun Medical GmbH occupies a distinct position among German-engineered sterile disposable specialists serving Western European infection control protocols. These three entities anchor the premium tier's competitive structure without exhausting the market's strategic diversity.
| Leading Market Players |
|---|
| Terumo |
| B. Braun Medical |
| Boston Scientific Corporation |
| Becton, Dickinson and Company |
| Cook Medical |
| Medtronic |
| Teleflex Incorporated |
| Ambu A/S |
| C.R. Bard |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone price indices from German and Swiss polymer suppliers cascade through three distinct pricing tiers for balloon inflation devices, with cardiac catheterization labs absorbing premium markups while party supply retailers operate on compressed margins.
Pricing Analysis
Value-based pricing anchored to procedural throughput and uptime guarantees dominates hospital procurement contracts for electric pump systems. Pricing stratifies across FDA 510(k)-cleared premium tiers, ISO 13485-certified standard configurations, and unregulated economy manual pumps. Cost compression in the party decoration segment intensifies because of Asian manufacturing oversupply. Retail consumers exhibit highest price sensitivity; integrated delivery networks negotiating multi-year service bundles show lowest.
Supply Chain Analysis
Refurbishment flows for electromechanical pump systems concentrate in Minneapolis and Boston-Worcester service hubs, extending asset lifecycles for hospital capital equipment. Manufacturing draws from Germany, Switzerland, and Japan for pressure-sensing components and polymer diaphragms. Single-source vulnerability in medical-grade polyurethane supply creates structural risk. Distribution runs through specialty medical distributors holding EU MDR and FDA establishment registrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Balloon inflation devices constitute a vertical-integration race where captive pressure-sensor production separates premium-margin players from commodity assemblers. Backward integration into transducer manufacturing offers the decisive upstream lever.
For Market Incumbents: Hedge against manual pump substitution in cost-sensitive outpatient clinics by locking multi-year preventive maintenance contracts with Southeast and Midwest integrated delivery networks. Defend margin position through in-house pressure-sensor fabrication that eliminates German polymer supplier concentration risk. Prioritize ISO 13485 certification maintenance as EU MDR documentation burdens tighten.
For New Entrants and Emerging Players: Specialty distributors serving German and Japanese hospital procurement departments offer the most accessible channel partnership pathway. White-space targets include portable CO2 canister configurations for Australian emergency response units and software-embedded compliance charting for US hospital IT committees. Target sports medicine field deployment as the least penetrated application vertical.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified contract manufacturers with established FDA 510(k) predicate device libraries in the Upper Midwest corridor. Long-term viability hinges on sustained interventional cardiology procedure volume expansion in aging demographics. Monitor PMDA marketing approval timeline extensions for foreign manufacturers as an inflection indicator for Asia-Pacific competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Transducers | Captive sensor production insulates Boston Scientific and Terumo from German polymer supply shocks. |
| EU MDR Conformity Assessment Fast-Track | Notified body pre-submission in Ireland or Netherlands compresses Class IIa device approval calendars. |
| Hospital System Partnership | Integrated delivery network sole-source agreements in Southeast US consolidate procurement leverage. |
| Software Companion Development | Digital compliance chart integration auto-populates Epic and Cerner EHR systems for Joint Commission audits. |
| Reimbursement Strategy | CPT code alignment for digital pressure-indicating systems secures favorable Medicare hospital outpatient payment. |
Research Methodology
Independent corroboration across catheterization lab managers, biomedical engineering directors, GPO contracts specialists, and sterile processing coordinators underwrites the qualitative findings. Primary fieldwork with hospital value analysis committees and secondary validation through FDA 510(k) databases, EU MDR notified body registries, CMS Medicare cost reports, and hospital procurement databases established demand-side parameters. Bottom-up equipment replacement cycle analysis and top-down interventional cardiology procedure volume triangulation anchored market sizing.
Rate-of-change decomposition across device type, application, end user, and distribution channel dimensions structured the analytical framework. CAGRs derived from fitted growth curves applied to replacement cycle frequencies and new catheterization lab build projections. Modeled inputs included aging demographic trajectories in Japan and the United States, EU MDR Annex XIV clinical evidence cost burdens, and PMDA quality system documentation requirements for foreign manufacturers.
Caveats apply where FDA 510(k) predicate device shortages or German polymer supplier capacity constraints could materially shift the outlook. Forecasts reflect assumptions on interventional cardiology reimbursement stability and notified body review timeline normalization. Practitioners should monitor EU MDR post-market surveillance data requirements and Swissmedic polymer component conformity assessments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Cytology Brush Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Root Canal Irrigators Market
Medical Devices
Europe C-Arms Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Powered Mattress System Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
US Mechanical Ventilator Market