
 Polymer-Based Prefilled Syringe Market | 2026-2036
Polymer-Based Prefilled Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer-Based Prefilled Syringe Market Analytics
Biologics manufacturing is repositioning toward polymer-based prefilled syringes as protein-sensitivity concerns make glass delamination unacceptable. Gerresheimer AG leverages its cyclic olefin polymer expertise to serve European biopharma customers requiring low-extractable containers. Becton, Dickinson and Company sustains global manufacturing scale across multiple polymer platforms. Stevanato Group differentiates through integrated containment and delivery system design.
Polymer-based prefilled syringes are injection-molded plastic primary containers, typically manufactured from cyclic olefin polymers or polypropylene, designed to store and administer premeasured drug doses with reduced breakage and extractables risk compared to glass alternatives. Their primary purpose centers on safe delivery of biologics, vaccines, and other parenteral therapies where material compatibility and patient self-administration matter. Safety syringes command attention as regulatory pressure for needlestick prevention intensifies across healthcare settings. Copolymer materials capture growing interest for their tunable barrier properties and processing flexibility relative to homopolymers.
The FDA enforces stringent extractables and leachables profiles under container closure guidance, while the EMA's MDR framework elevates traceability and biocompatibility documentation for polymer primary packaging. ISO 11040 standards govern functional testing and dimensional consistency, creating compliance thresholds that filter smaller molders from pharmaceutical supply chains. Stakeholders must monitor how USP Class VI testing evolution and evolving biologics pipeline requirements reshape material qualification timelines and converter qualification burdens.
Market Dynamics
Biologics manufacturers are abandoning glass containers as protein aggregation and delamination risks trigger wholesale material transitions. Cyclic olefin polymer adoption is accelerating because extractables testing under FDA container closure guidance now disqualifies conventional plastics from high-value therapeutic applications.
Growth Catalysts
- EMA MDR Traceability Mandates:European medical device regulation now requires serialized polymer primary packaging for parenteral delivery systems, forcing converters toward qualified cyclic olefin copolymer supply chains.
- Self-Administration Therapies:Rheumatoid arthritis and diabetes patients demand portable injection devices that polymer syringes enable through reduced breakage risk versus glass alternatives.
- German Production Clustering:Specialized molding capabilities concentrate around Düsseldorf and Mainz, creating proximity advantages for European biopharma customers requiring just-in-time container supply.
Market Restraints
- Cyclic Olefin Monomer Supply Concentration:Three Japanese chemical producers control bulk cyclic olefin polymer resin supply, creating input cost volatility when pharmaceutical demand spikes.
- Glass-to-Polymer Conversion Timelines:Biologics sponsors face 18-24 month stability study requirements under FDA guidance before switching primary container materials for approved therapies.
- Barrier Property Limitations:Polypropylene syringes exhibit oxygen permeability rates unsuitable for oxidation-sensitive biologics, restricting addressable therapeutic categories.
Strategic Opportunities
- Indian Biosimilar Manufacturing:CDSCO accelerated approval pathways for follow-on biologics are drawing investment toward polymer syringe-compatible filling lines in Hyderabad and Bangalore.
- Connected Delivery Convergence:Integration of near-field communication tags with polymer syringe bodies enables dose tracking and adherence monitoring for value-based reimbursement contracts.
- US IRA Price Negotiation Exemptions:Small-molecule drugs selected for Medicare price controls face margin compression, redirecting R&D investment toward biologics requiring specialized polymer containment.
Industry Challenges
- Extractables Chemist Shortage:Qualified analytical personnel capable of executing USP Class VI and ISO 10993-18 testing protocols command premium compensation, extending converter qualification timelines.
- Multi-Cavity Mold Validation:High-speed injection molding for pharmaceutical-grade syringes requires IQ/OQ/PQ documentation cycles that compress operational throughput during new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer-Based Prefilled Syringe Market |
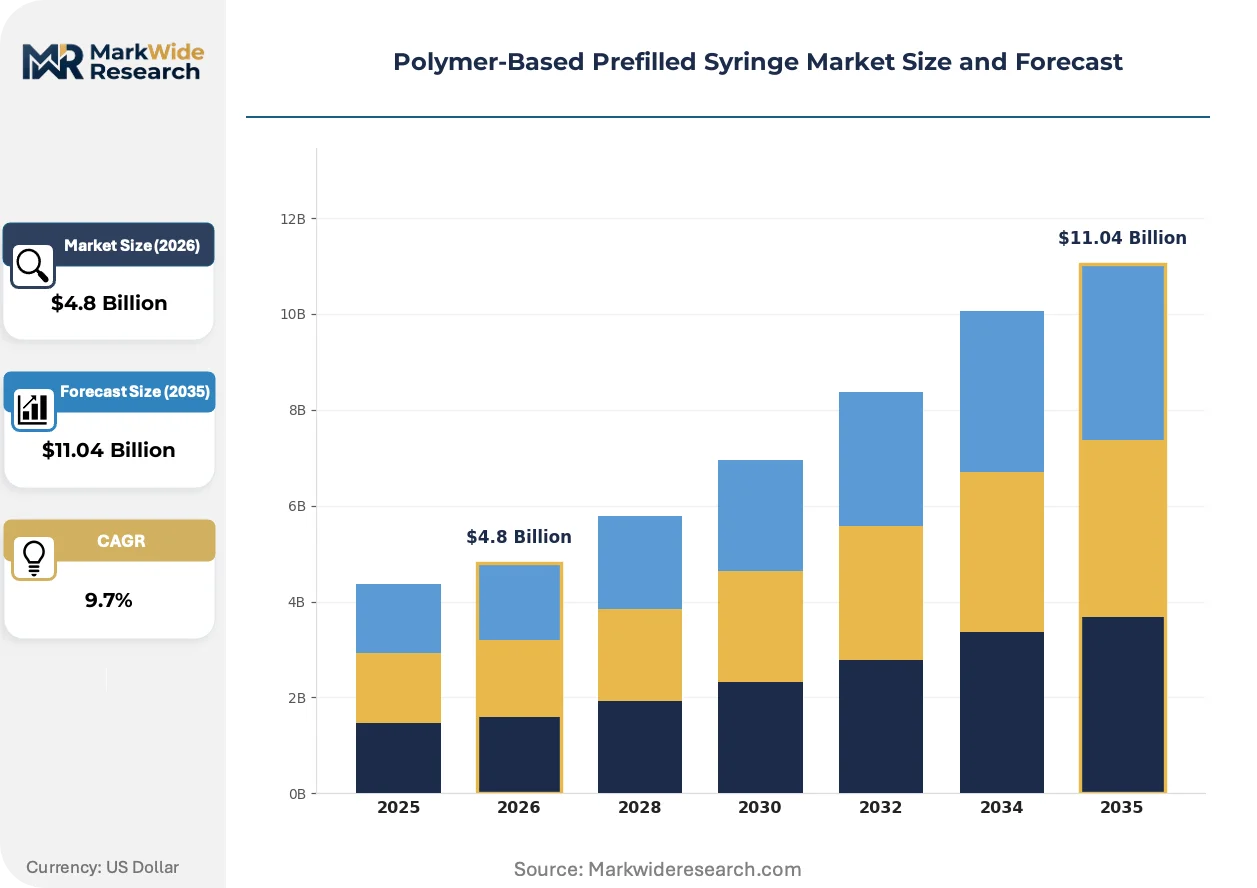
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Safety Syringes, Customized Syringes, Specialty Syringes Material: Polypropylene, Polycarbonate, Polyethylene, Copolymer End User: Hospitals, Home Care, Clinics, Pharmaceutical Companies Application: Vaccinations, Pain Management, Hormonal Therapy, Biologics |
| Companies Covered | Becton, Dickinson and Company, Gerresheimer AG, Schott Pharma, Stevanato Group, West Pharmaceutical Services, Inc., Baxter International Inc., Terumo Corporation, Nipro Corp., Aptar Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer-Based Prefilled Syringe Market Evolving Landscape
Container closure integrity testing is migrating from destructive sampling toward in-line spectroscopic verification, compressing quality assurance cycles. Material science advances now permit tuning of cyclic olefin copolymer barrier properties without sacrificing optical clarity.
Siliconization automation is automating needle lubrication deposition through plasma-enhanced chemical vapor deposition, replacing manual dip-coating processes. Contract manufacturers in Switzerland and Germany are adopting these systems to meet batch-to-batch consistency requirements for monoclonal antibody formulations. This technology is automating the elimination of variable silicone oil distribution that previously caused protein aggregation failures.
REACH Annex XVII restrictions on phthalate plasticizers are compelling reformulation of elastomeric plunger components used in polymer syringe assemblies. European converters must now qualify thermoplastic elastomer alternatives that maintain seal integrity across temperature cycling. German compounders are responding with hydrogenated styrenic block copolymer grades that satisfy both ECHA compliance and USP physicochemical testing.
Home healthcare providers are consolidating purchasing decisions through group procurement organizations, displacing decentralized hospital pharmacy buying. This concentration is forcing polymer syringe suppliers to demonstrate total cost-of-ownership advantages across breakage reduction, waste minimization, and disposal simplification. The United States exhibits the most pronounced procurement consolidation, with three national GPOs now controlling majority share of prefilled syringe volume for chronic disease management.
Polymer-Based Prefilled Syringe Market Segmentation
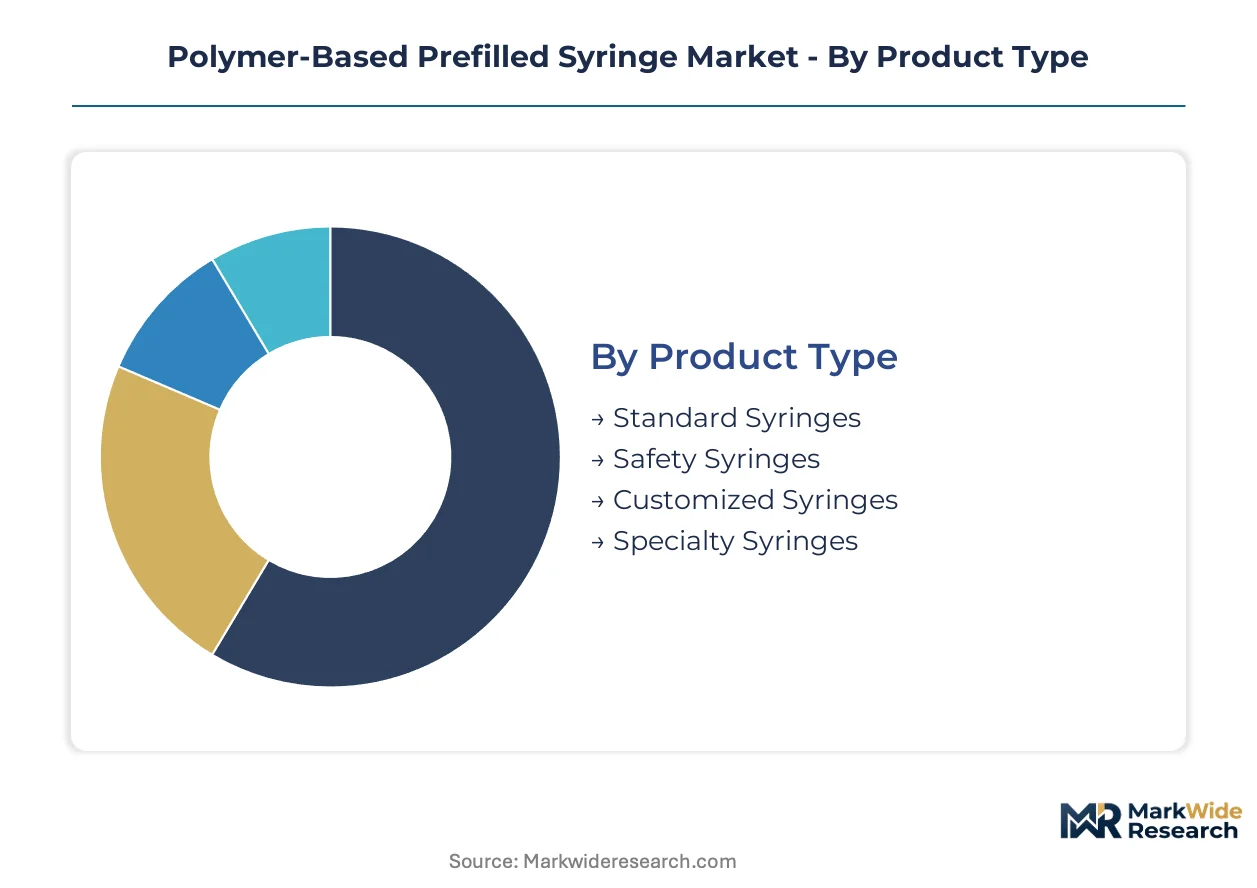
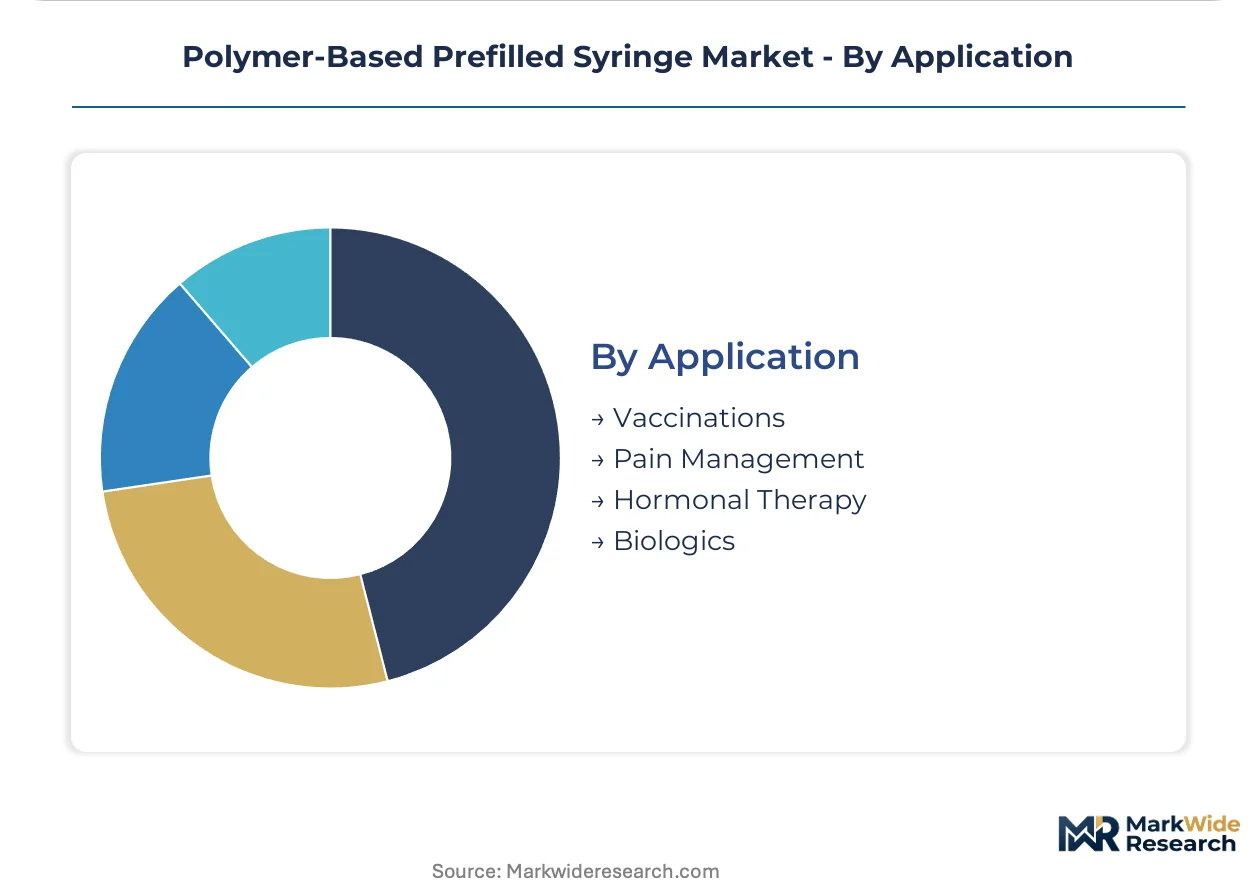
Segmentation in polymer-based prefilled syringes reveals how regulatory pathways and material qualifications fragment addressable demand. Each category carries distinct certification burdens that shape converter investment priorities and customer qualification timelines.
Product Type:
Safety syringes carry the heaviest regulatory load, requiring FDA 510(k) or EMA MDR certification for needlestick prevention features alongside ISO 11040 functional testing.
- Safety Syringes:These incorporate retractable or shielded needle mechanisms engineered to prevent healthcare worker injury. German hospital systems and US GPOs now mandate these for institutional procurement, driven by OSHA bloodborne pathogen standards and state-level needlestick prevention laws. Retractable designs face higher mold precision requirements than passive shields.
- Standard Syringes:Conventional luer-lock or staked-needle configurations without integrated safety features. These dominate Indian and Brazilian vaccine programs where cost sensitivity outweighs premium safety engineering, though EMA MDR traceability mandates are narrowing this advantage.
- Customized Syringes:Patient-specific geometries or dosing increments for rare disease therapies.
- Specialty Syringes:Dual-chamber or lyophilization-compatible designs for complex biologic reconstitution.
Standard syringes sit at the top of the volume ranking, with safety syringes climbing the fastest.
Material:
Material selection directly determines extractables profiles and oxygen barrier performance, with cyclic olefin variants commanding premium positioning over commodity thermoplastics.
- Copolymer:Cyclic olefin copolymer delivers tunable moisture and oxygen barrier properties through ethylene content adjustment while maintaining glass-like optical clarity. Japanese resin producers in Kawasaki and Ichihara anchor global supply, with German converters paying freight premiums for pharmaceutical-grade batches. EMA MDR biocompatibility documentation requirements favor this material for European biologics.
- Polypropylene:Homopolymer and random copolymer grades offer lowest unit cost and established sterilization compatibility. Indian CDSCO generic filings and US 503B compounding pharmacies source these for non-oxygen-sensitive small molecules, though barrier limitations exclude them from monoclonal antibody applications.
- Polycarbonate:High-impact strength suits autoinjector integration and ruggedized delivery systems.
- Polyethylene:Lowest extractables signature among commodity plastics, preferred for diagnostic reagent containment.
Polypropylene holds the largest installed base, while copolymer gains share fastest in biologics-qualified applications.
End User:
End-user concentration shapes procurement scale and technical service intensity, with pharmaceutical companies driving specification complexity and home care demanding patient-centric design.
- Pharmaceutical Companies:Sponsors of novel biologics and biosimilars specify primary containers during formulation development, locking in polymer grades through multi-year stability studies. US IRA price negotiation exemptions for biologics are redirecting R&D investment toward these specialized containment systems. German and Swiss contract manufacturers maintain dedicated quality agreements with cyclic olefin copolymer converters.
- Hospitals:Acute care settings prioritize safety-engineered devices and standardized connection interfaces for medication safety. Three US national GPOs now aggregate purchasing for chronic disease therapies, compressing supplier margins while demanding breakage reduction documentation.
- Home Care:Self-administration trends favor portable, intuitive designs with reduced needle phobia features.
- Clinics:Outpatient infusion centers balance cost control with regulatory compliance for parenteral therapies.
Pharmaceutical companies dominate value concentration, with home care expanding most quickly on self-injection therapy trends.
Application:
Application segments stratify by protein sensitivity, with oxidation-prone biologics imposing the strictest material qualification protocols.
- Biologics:Monoclonal antibodies, fusion proteins, and gene therapies require container closure systems with sub-ppm extractables and demonstrable protein stability over 24-36 month shelf lives. FDA container closure guidance and USP Class VI testing create qualification bottlenecks that filter out non-specialized molders. Swiss and German fill-finish contractors lead adoption of plasma-enhanced siliconization to prevent aggregation.
- Vaccinations:High-volume, cost-constrained demand from national immunization programs and pandemic preparedness stockpiles. Indian CDSCO and Brazilian ANVISA accelerated approval pathways for COVID-19 and influenza vaccines drove temporary polypropylene acceptance, though mRNA platforms are upgrading to cyclic olefin barriers for lipid nanoparticle protection.
- Pain Management:Opioid and non-opioid analgesics for postoperative and chronic pain, with abuse-deterrent features gaining traction.
- Hormonal Therapy:Fertility treatments and endocrine disorders requiring precise dosing and temperature-stable containment.
Vaccinations lead absolute volume, while biologics commands the steepest expansion trajectory on pipeline concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision molding clusters anchor polymer-based prefilled syringe manufacturing for European biopharma. FDA and EMA regulatory convergence around extractables testing is reshaping converter qualification requirements across major markets. Japanese resin suppliers control cyclic olefin polymer feedstock, creating geographic dependencies in material supply chains.
United States
Three national group purchasing organizations now aggregate prefilled syringe procurement for chronic disease therapies, compressing supplier margins while demanding breakage reduction documentation. FDA container closure guidance mandates 18-24 month stability studies for material switches, extending qualification timelines for biologics sponsors. The Greater Boston and San Francisco Bay Area biotech corridors drive specification complexity for specialized containment systems.
Germany
EMA MDR traceability mandates require serialized polymer primary packaging, forcing converters toward qualified cyclic olefin copolymer supply chains. REACH Annex XVII phthalate restrictions compel reformulation of elastomeric plunger components. The Düsseldorf-Mainz production corridor concentrates specialized molding capabilities serving just-in-time European pharmaceutical demand.
Switzerland
Contract manufacturers in Basel and Zurich lead adoption of plasma-enhanced siliconization to prevent protein aggregation in monoclonal antibody formulations. Swissmedic biocompatibility documentation requirements favor cyclic olefin copolymer for high-value therapeutic applications. The country's fill-finish contractors maintain dedicated quality agreements with specialized polymer converters.
India
CDSCO accelerated approval pathways for follow-on biologics draw investment toward polymer syringe-compatible filling lines in Hyderabad and Bangalore. Cost-constrained vaccine programs temporarily accept polypropylene, though mRNA platform upgrades are shifting demand toward cyclic olefin barriers. Domestic pharmaceutical packaging is expanding technical capabilities to serve export markets.
Japan
METI industrial policy supports domestic medical device packaging innovation, with PMDA quality standards aligning with international extractables testing protocols. Three chemical producers in Kawasaki and Ichihara control bulk cyclic olefin polymer resin supply, creating input cost leverage when pharmaceutical demand spikes. Japanese converters supply precision-molded components to global pharmaceutical customers.
Polymer-Based Prefilled Syringe Market Competitive Landscape
Capacity expansion dominates the current landscape as converters race to qualify cyclic olefin copolymer lines under tightened FDA and EMA extractables protocols. The vendor base stratifies between integrated containment specialists and component-focused molders. Two archetypes define competitive positioning: German-Swiss precision clusters serving European biopharma, and diversified medical device conglomerates with global manufacturing footprints. M&A activity concentrates on siliconization technology and multi-cavity mold capabilities, while strategic partnerships between resin suppliers and converters secure qualified material pipelines.
Among German-based specialists, Gerresheimer AG exemplifies the cyclic olefin polymer expertise archetype serving European biopharma customers. Becton, Dickinson and Company occupies a position representing global manufacturing scale across multiple polymer platforms. Stevanato Group sits within the integrated containment and delivery system design tier, anchoring specialized capabilities for complex biologic formulations.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Gerresheimer AG |
| Schott Pharma |
| Stevanato Group |
| West Pharmaceutical Services, Inc. |
| Baxter International Inc. |
| Terumo Corporation |
| Nipro Corp. |
| Aptar Pharma |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII phthalate restrictions gate qualified supply and premium-tier pricing access, forcing converters toward hydrogenated styrenic block copolymer plunger compounds that satisfy both ECHA compliance and USP physicochemical testing. German and Swiss biopharma customers now pay freight premiums for pharmaceutical-grade cyclic olefin copolymer batches that meet FDA container closure guidance, while Indian vaccine programs accept polypropylene at lower price points.
Pricing Analysis
Distributor margins compress as three US national GPOs aggregate prefilled syringe procurement for chronic disease therapies, forcing suppliers to demonstrate total cost-of-ownership advantages across breakage reduction and waste minimization. Three-tier pricing structure across premium, standard, and economy levels separates cyclic olefin copolymer biologics-qualified systems from polypropylene vaccine containers and commodity diagnostic-grade polyethylene. Cost compression in standard syringe tiers is intensifying because Indian CDSCO accelerated approval pathways for follow-on biologics are drawing investment toward polymer-compatible filling lines. Pharmaceutical companies exhibit lowest price sensitivity due to 18-24 month stability study lock-in effects, while 503B compounding pharmacies and national immunization programs drive hardest bargain.
Supply Chain Analysis
Reverse-logistics flows for polymer syringe returns remain underdeveloped relative to glass container refurbishment networks, creating disposal cost burdens that home healthcare providers increasingly factor into procurement decisions. Bulk cyclic olefin polymer resin production concentrates in Japan, Germany, and the United States, with three Japanese chemical producers in Kawasaki and Ichihara anchoring global feedstock supply. The supply chain rests on specialized multi-cavity mold tooling from German precision engineering clusters and plasma-enhanced siliconization equipment from Swiss automation specialists. Single-source vulnerability in cyclic olefin monomer supply creates input cost volatility when pharmaceutical demand spikes. Distribution runs through specialized medical device distributors serving hospital systems and direct quality agreements between converters and German-Swiss fill-finish contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymer-based prefilled syringe market represents a late-cycle quality story as biologics manufacturers abandon glass containers and FDA extractables testing disqualifies conventional plastics from high-value therapeutic applications. Demand is concentrating toward premium cyclic olefin copolymer specifications that command sustained margin premiums.
For Market Incumbents: Extend cyclic olefin copolymer qualification capabilities through dedicated quality agreements with Japanese resin suppliers, securing captive supply pipelines before demand spikes trigger allocation constraints. Add multi-cavity mold capacity in the Düsseldorf-Mainz corridor to serve just-in-time European pharmaceutical demand. Invest in plasma-enhanced siliconization automation to eliminate variable silicone oil distribution that causes protein aggregation failures in monoclonal antibody formulations. For New Entrants and Emerging Players: Capture white-space opportunity in Indian biosimilar manufacturing by qualifying polymer syringe-compatible filling lines for CDSCO accelerated approval pathways in Hyderabad and Bangalore. Target connected delivery convergence by integrating near-field communication tags with polymer syringe bodies for dose tracking and adherence monitoring contracts. Pursue strategic partnerships with German compounders developing hydrogenated styrenic block copolymer plunger alternatives to REACH-restricted phthalates. For Investors and Strategic Acquirers: Valuations sit cheapest among polypropylene-focused converters serving vaccine programs, though mRNA platform upgrades are shifting demand toward cyclic olefin barriers. Long-term viability favors integrated containment specialists with backward control over siliconization technology and multi-cavity mold capabilities. Acquisition target archetype: mid-cap German-Swiss precision molders with existing EMA MDR traceability documentation and cyclic olefin copolymer processing expertise. Monitor FDA container closure guidance evolution and USP Class VI testing protocol changes as inflection indicators for material qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclic Olefin Copolymer Line Qualification | EMA MDR traceability mandates force converters toward qualified supply chains serving European biopharma. |
| Plasma-Enhanced Siliconization Adoption | Swiss and German fill-finish contractors automate needle lubrication to prevent protein aggregation failures. |
| Multi-Cavity Mold Capacity Expansion | German precision clusters in Düsseldorf and Mainz concentrate capabilities for just-in-time pharmaceutical demand. |
| Connected Delivery Integration | Near-field communication tags enable dose tracking for value-based reimbursement contracts in US GPO procurement. |
| Thermoplastic Elastomer Reformulation | Hydrogenated styrenic block copolymer plunger compounds satisfy REACH Annex XVII and USP physicochemical testing. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and GPO contracts managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases; plus customs trade data and SEC 10-K disclosures — were reconciled through bottom-up and top-down triangulation. Conversations with biomedical engineers and formulary directors informed specification complexity trends, while field engagement with cyclical olefin polymer converters and Japanese resin suppliers anchored supply-side dynamics.
Historical volume trajectories were cross-referenced against panel input from industry specialists to derive expansion rates across the analysis window. Segmentation dimensions modeled include material grade tier, end-use application, regional regulatory cluster, and therapeutic category protein sensitivity. CAGRs were derived from reconciling bottom-up converter capacity buildouts with top-down biologics pipeline forecasts, incorporating ISO 11040 functional testing evolution and USP Class VI protocol changes as structural variables.
Underlying measurement precision varies by segment; biologics-qualified cyclic olefin copolymer applications carry tighter precision than commodity polypropylene vaccine programs due to concentrated converter visibility. Forecasts incorporate assumptions regarding FDA extractables guidance stability, EMA MDR implementation timelines, and Japanese resin supplier capacity expansion intentions. Practitioners should monitor CDSCO biosimilar approval velocity, US IRA biologics investment redirection, and REACH Annex XVII enforcement intensity for early signals of demand and regulatory inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Medical Goggle Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Pericardial Patches Market
Medical Devices
Suction Catheters Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Medical Radiation Detectors Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Middle East and Africa Surgical Equipment Market