
 Interventional Cardiology Devices Market | 2026-2036
Interventional Cardiology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Cardiology Devices Market Intelligence
Subscription-based software for remote patient monitoring and procedural data analytics is expanding the value proposition beyond the physical device. This shift benefits large, integrated players. Medtronic leverages its extensive portfolio to bundle software with its catheter and stent systems. Boston Scientific Corporation specializes in bioresorbable scaffolds and drug-eluting technologies. Abbott Laboratories competes on the strength of its diagnostic and imaging integration with its interventional tools.
Interventional cardiology devices encompass a range of tools, including guidewires and catheters, used for minimally invasive procedures to diagnose and treat cardiovascular diseases. These devices, often featuring hydrophilic coatings or specific tip stiffness ratings, are designed to navigate complex vascular anatomy to restore blood flow. The drug-eluting stents segment continues to command the largest revenue share due to superior clinical outcomes in treating coronary artery disease. Catheters and guidewires represent a high-volume, consistent revenue stream, particularly for complex interventions like chronic total occlusion.
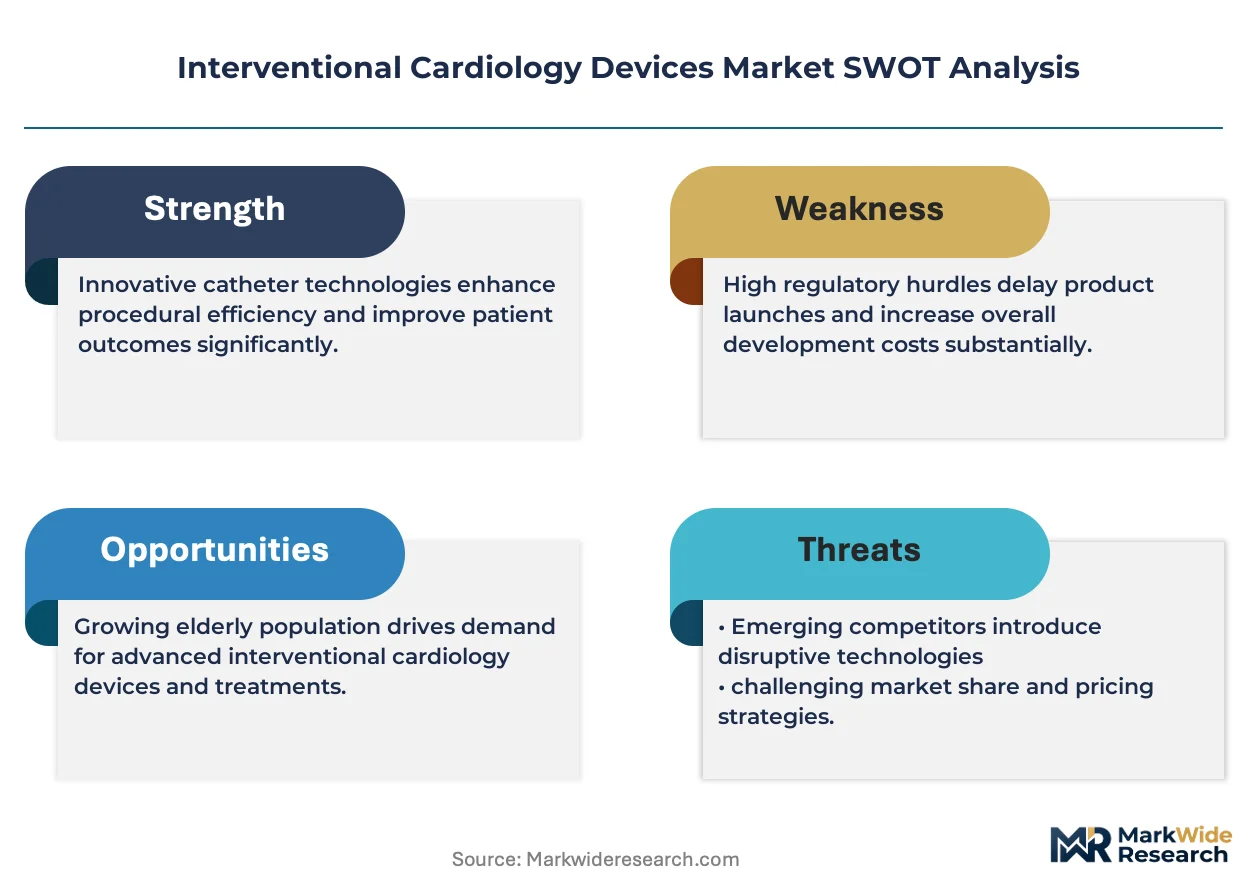
Market access requires stringent approvals from bodies like the US FDA, the European Union under its Medical Device Regulation (MDR), and China's NMPA. These regulations enforce rigorous pre-market clinical trials and post-market surveillance, shaping product development timelines and costs. Device manufacturers must now decide how to balance innovation in biodegradable materials with the increasing demand for long-term clinical performance data.
Market Dynamics
Stricter regulatory frameworks, exemplified by the European Union's Medical Device Regulation, are the central force shaping product development. This pressure mandates extensive clinical data and post-market surveillance for all devices, influencing R&D investment priorities and product launch timelines across the industry.
Growth Catalysts
- Advanced Material Science:Novel hydrophilic coatings and polymers improve guidewire navigation through complex anatomies, particularly for chronic total occlusion procedures.
- Infrastructure Expansion in China:The rapid build-out of cardiac care units in China's hospital system creates high-volume, concentrated demand for stents and catheters.
- Shift to Ambulatory Centers:The migration of less invasive procedures to ambulatory surgical centers (ASCs) opens a new, cost-sensitive channel for device manufacturers.
Market Restraints
- Regulatory Friction:The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence requirements, increasing the time and cost to gain market access.
- Biodegradable Material Hurdles:Bioresorbable scaffold development is constrained by the need for extensive, long-term clinical data, which slows the pace of material innovation.
- Reimbursement Headwinds:National health system reimbursement policies often lag behind the premium cost of next-generation drug-eluting technologies, limiting their adoption.
Strategic Opportunities
- Software and Data Integration:Bundling subscription-based software for remote monitoring and procedural analytics with devices creates recurring revenue and enhances value beyond the hardware.
- Southeast Asia Market Entry:Expanding into Southeast Asian markets offers growth as healthcare infrastructure modernizes and access to advanced cardiac care improves.
- Specialized CTO Device Portfolios:Developing dedicated guidewires and microcatheters engineered for chronic total occlusion procedures addresses a significant, complex clinical need.
Industry Challenges
- MDR Recertification Burden:Manufacturers face operational challenges generating the clinical data required to recertify legacy devices under the EU's Medical Device Regulation.
- Specialized Physician Training:A shortage of physicians trained on advanced devices for complex procedures like chronic total occlusion creates an adoption bottleneck.
- Critical Material Sourcing:Securing a consistent supply of high-purity polymers and specialized hydrophilic coatings presents a significant supply chain management challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Cardiology Devices Market |
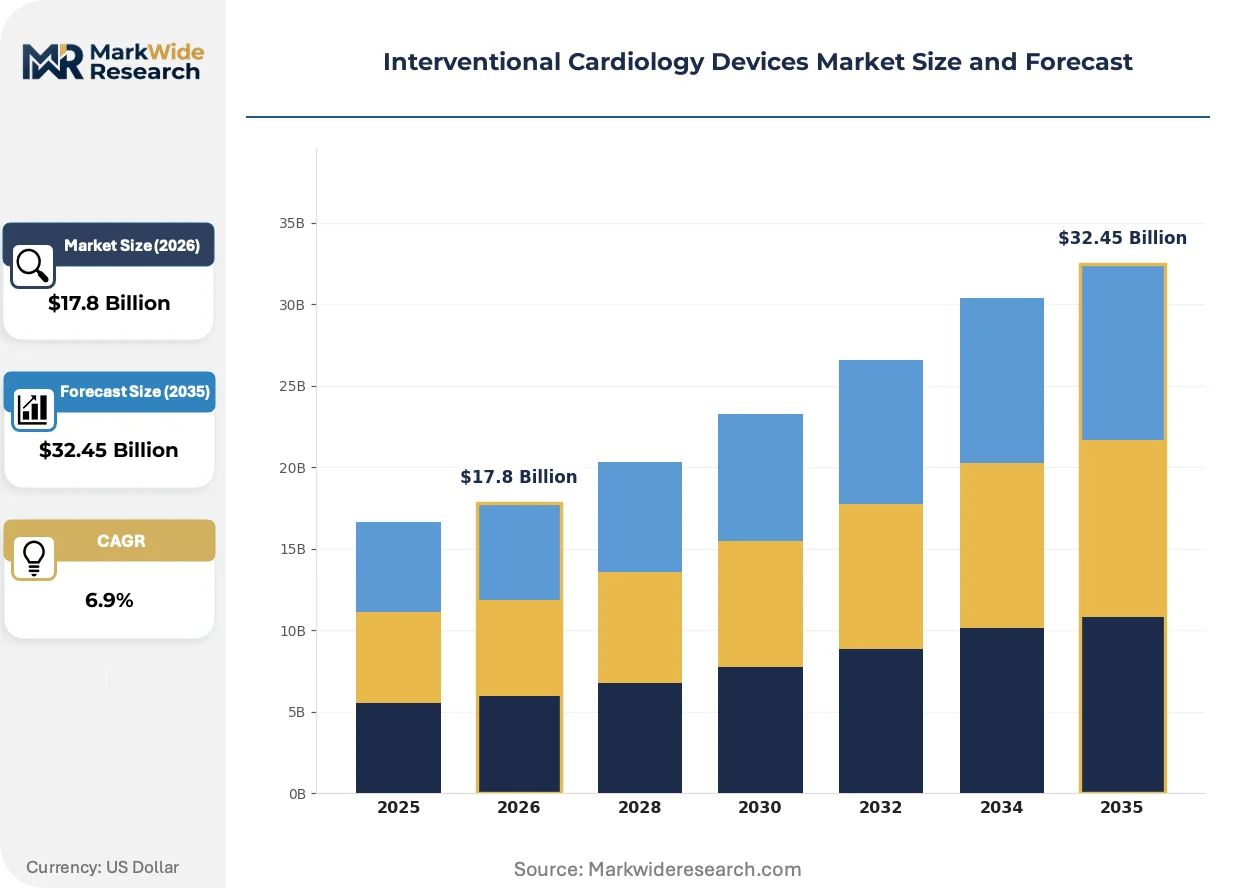
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $32.45 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Balloons, Guidewires, Embolic Protection Devices Technology: Drug-Eluting, Bare-Metal, Biodegradable, Bioresorbable Vascular Scaffold, Cutting Balloon Application: Coronary Artery Disease, Peripheral Artery Disease, Chronic Total Occlusion, Valvular Heart Disease End User: Cardiac Centers, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Clinics |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, Edwards Lifesciences Corporation, Terumo Corporation, Koninklijke Philips N.V., B. Braun SE, Teleflex Incorporated, BIOTRONIK SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Cardiology Devices Market Strategic Shifts & Innovations
The convergence of digital health technologies with physical devices is fundamentally altering the competitive landscape. This integration of data analytics and remote monitoring capabilities moves the value proposition beyond the standalone instrument toward a comprehensive procedural and patient management ecosystem.
Bioresorbable scaffold technology provides temporary vessel support before being fully absorbed by the body, eliminating long-term implants. Interventional cardiologists in specialized centers are the primary adopters, seeking to avoid permanent caging of the vessel. This technology is expanding into treating simpler lesions as long-term safety and efficacy data accumulates.
China's National Medical Products Administration (NMPA) has streamlined its approval pathways for innovative medical devices, including certain high-risk cardiovascular products. This policy change accelerates market entry for novel technologies that can demonstrate significant clinical benefit over existing options. The drug-eluting stent and bioresorbable scaffold segments are most affected, responding with increased R&D investment localized for the Chinese market.
Hospital procurement models are evolving from transactional, per-device purchases to strategic partnerships focused on bundled solutions. This disrupts traditional sales channels that rely on relationships with individual physicians, favoring vendors who can offer integrated device, software, and analytics packages. The shift is most visible in large, integrated hospital networks within the United States and Western Europe.
Interventional Cardiology Devices Market Segmentation
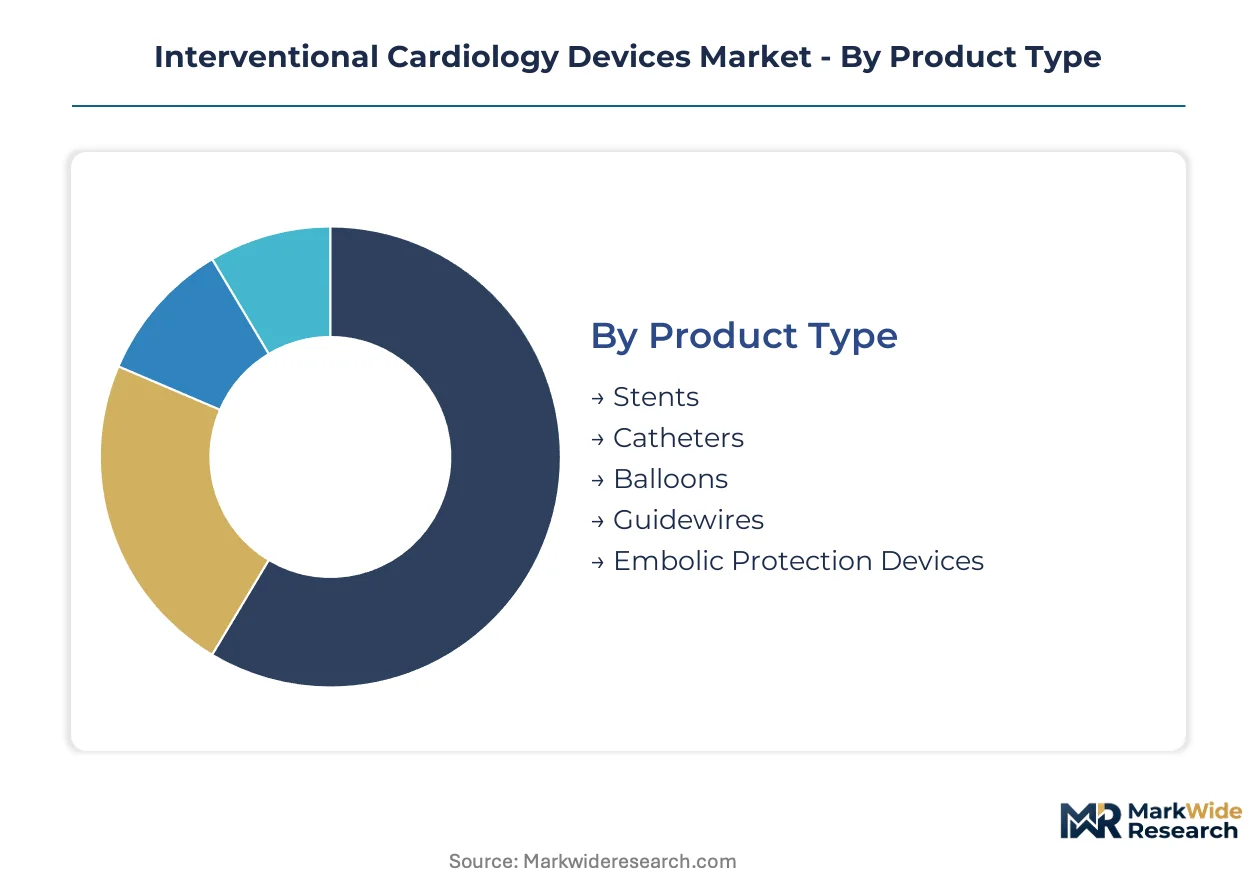
The interventional cardiology devices market is meticulously segmented to reflect the diverse product offerings, technological advancements, clinical applications, and varied end-user environments. Understanding these segments is crucial for device manufacturers to align product development with specific clinical needs and market demands.
Product Type:
The segmentation of product types reveals a clear distinction between high-volume, essential instruments and specialized, high-value devices.
- Stents:These implantable devices, often made of metallic mesh, provide structural support to keep arteries open after angioplasty. Demand for stents is concentrating heavily in China due to expanding hospital infrastructure and increasing prevalence of coronary artery disease.
- Catheters:Flexible tubes with various tip designs and hydrophilic coatings, catheters are essential for navigating vascular anatomy to deliver therapies or diagnostic tools. These devices represent a high-volume, consistent revenue stream particularly for complex interventions.
- Balloons:Used in angioplasty procedures, these inflatable devices expand narrowed arteries to restore blood flow.
- Guidewires:Thin, flexible wires that provide a path for catheters and other devices through the vasculature.
- Embolic Protection Devices:Small filters or occlusion devices designed to capture or divert emboli during interventional procedures, preventing downstream complications.
Mature deployment sits with Stents. Newer deployment is concentrated in Embolic Protection Devices.
Technology:
Technology segmentation highlights the clinical effectiveness and innovation driving product differentiation within the market.
- Drug-Eluting:These stents release medication over time to prevent restenosis, offering superior clinical outcomes in treating coronary artery disease. Demand for drug-eluting stents is strong in markets prioritizing long-term patient outcomes.
- Bioresorbable Vascular Scaffold:Designed to provide temporary vessel support before being fully absorbed by the body, this technology eliminates long-term implants. Specialized centers in Europe are adopting these for treating simpler lesions as long-term safety data accumulates.
- Bare-Metal:Traditional stents made of inert metal, offering mechanical support without drug release.
- Biodegradable:Materials that break down naturally in the body, used in a variety of device components.
- Cutting Balloon:A specialized angioplasty balloon with small blades designed to score plaque and facilitate vessel expansion.
The drug-eluting segment continues to dominate revenue while biodegradable technologies show the steepest expansion trajectory.
Application:
Application areas categorize where interventional cardiology devices deliver targeted therapeutic benefits across various cardiovascular conditions.
- Coronary Artery Disease:Procedures addressing blockages in the arteries supplying the heart muscle, representing the largest segment for interventional cardiology devices. Demand for these procedures is consistently high across North America and Western Europe.
- Chronic Total Occlusion:Complex procedures to recanalize completely blocked coronary arteries, requiring specialized guidewires and microcatheters. A shortage of trained physicians presents an adoption bottleneck for these advanced interventions.
- Peripheral Artery Disease:Interventions targeting blockages in arteries outside the heart, primarily in the legs.
- Valvular Heart Disease:Procedures to treat diseased heart valves, including transcatheter aortic valve replacement (TAVR).
Coronary Artery Disease interventions maintain the largest procedural volume, with chronic total occlusion procedures gaining share fastest.
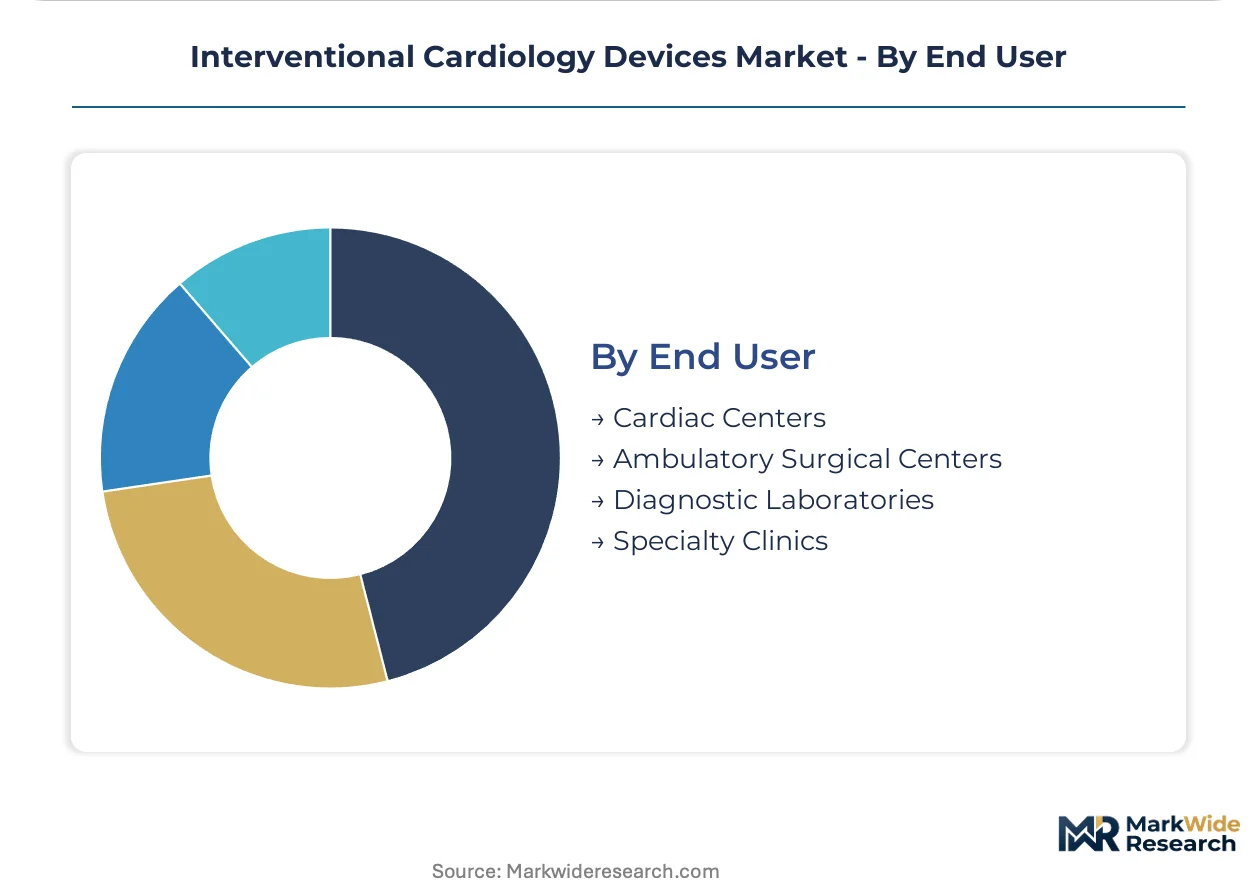
End User:
The end-user landscape reflects evolving healthcare delivery models and patient access points for interventional cardiology procedures.
- Cardiac Centers:Large hospital departments specializing in comprehensive cardiovascular care, performing a wide range of complex interventional procedures. These centers are the primary purchasers of high-end imaging and device systems.
- Ambulatory Surgical Centers:Facilities where less invasive procedures are performed on an outpatient basis, offering a cost-effective alternative to hospital stays. The migration of less invasive procedures to these centers opens a new channel for device manufacturers in the United States.
- Diagnostic Laboratories:Facilities focused on identifying cardiovascular conditions through various tests and imaging.
- Specialty Clinics:Smaller medical practices focusing on specific cardiovascular conditions or patient populations.
Traditional cardiac centers remain the primary users, but ambulatory surgical centers are expanding most quickly as procedural sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The interventional cardiology devices market exhibits a clear division between consumption centers and manufacturing hubs. Expanding healthcare infrastructure and aging populations drive demand in key regions. Regulatory frameworks also significantly influence product availability and market access.
China
Expanding hospital infrastructure and an increasing prevalence of coronary artery disease drive demand for interventional cardiology devices. China's NMPA has streamlined approval pathways for innovative medical devices, accelerating market entry. Major cities like Beijing and Shanghai are seeing concentrated demand for advanced catheter and stent systems within their modernizing cardiac care units.
United States
The shift of less invasive procedures to ambulatory surgical centers (ASCs) and high procedural volumes for coronary artery disease fuel device consumption. The US FDA requires stringent pre-market approvals and post-market surveillance for interventional devices. The Boston-Cambridge cluster remains a hub for medical device innovation and specialized cardiac care development.
Germany
High adoption of advanced drug-eluting stents and a focus on long-term patient outcomes characterize demand in this region. The European Union's Medical Device Regulation (MDR) imposes rigorous clinical evidence requirements on all medical devices. Cities like Munich and Berlin host specialized cardiac centers and advanced device development initiatives.
India
Modernization of healthcare infrastructure and a rising incidence of cardiovascular diseases contribute to growing device demand. The Central Drugs Standard Control Organization (CDSCO) governs medical device approvals and market access. Major metropolitan areas such as Bengaluru and Mumbai are expanding their cardiac care facilities and procedural capabilities.
Japan
An aging population and an emphasis on high-quality medical technology underpin the demand for interventional cardiology devices. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device registration and post-market surveillance. The Tokyo metropolitan area is a center for medical device research and development, alongside specialized cardiology interventions.
Interventional Cardiology Devices Market Key Industry Players
Top-tier vendors anchor the integrated solutions segment, while specialized innovators focus on niche technologies. The market structure exhibits a tiered consolidation, with large players offering comprehensive portfolios. Strategic archetypes include diversified medical technology giants and focused device specialists. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Within the integrated solutions archetype, Medtronic leverages its extensive portfolio to bundle software with its catheter and stent systems, enhancing its value proposition. Boston Scientific Corporation exemplifies specialized innovation, focusing on bioresorbable scaffolds and advanced drug-eluting technologies. Abbott Laboratories competes by integrating its diagnostic and imaging capabilities with its interventional tools, reinforcing its position as a comprehensive cardiovascular solutions provider across diverse clinical needs.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Terumo Corporation |
| Koninklijke Philips N.V. |
| B. Braun SE |
| Teleflex Incorporated |
| BIOTRONIK SE & Co. KG |
| Others |
Cost & Logistics Intelligence
Bioresorbable scaffold technology introduces complex material costs and specialized manufacturing, influencing device pricing and concentrating high-value production. This simultaneously reshapes cost economics and supply concentration for interventional cardiology devices.
Pricing Analysis
Reimbursement headwinds limit adoption for next-generation drug-eluting technologies, intensifying pricing pressure on manufacturers. Value-based pricing models are emerging for integrated device and software solutions, contrasting with traditional per-unit transactional purchases. Price differentiation stems from superior clinical outcomes and stringent regulatory approval tiers like those from the US FDA and EU MDR. Ambulatory Surgical Centers exhibit high price sensitivity for less invasive procedures, while specialized cardiac centers prioritize advanced technology over cost.
Supply Chain Analysis
China's NMPA streamlining approval pathways for innovative devices incentivizes localized production and sourcing within the country. Global supply concentration for interventional cardiology devices centers on manufacturing hubs in the United States and Germany, alongside emerging capabilities in China. High-purity polymers and specialized hydrophilic coatings represent critical raw material dependencies. Critical material sourcing presents a significant supply chain management challenge, creating a structural risk. Distribution runs through direct sales forces targeting hospital systems and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The interventional cardiology devices market operates under supply constraints, particularly for specialized components like high-purity polymers. This critical material sourcing challenge props pricing for advanced guidewires and catheters.
For Market Incumbents: To counter regulatory friction from the EU MDR, incumbents must invest heavily in long-term clinical data generation for legacy and new devices. Medtronic could deepen vertical integration into specialized hydrophilic coating production to secure critical material supply. Expanding software and data integration capabilities enhances value propositions, defending against commoditization of physical devices. Strategic partnerships with hospital networks also reinforce market access.
For New Entrants and Emerging Players: Bioresorbable scaffold technology offers a unique entry point for new entrants targeting specialized cardiac centers, particularly for simpler lesion treatments. Developing dedicated guidewires and microcatheters for chronic total occlusion procedures addresses a significant unmet clinical need. A go-to-market strategy focusing on physician training and education for complex interventions can accelerate adoption. Southeast Asia presents an accessible geography due to modernizing healthcare infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized device innovators with robust intellectual property in biodegradable materials or advanced coating technologies. Investors should seek companies demonstrating strong clinical data for long-term performance, aligning with stringent regulatory requirements. The long-term viability of this market hinges on continuous innovation in less invasive techniques and integration with digital health. A key signal to watch is the accumulation of long-term safety and efficacy data for bioresorbable scaffolds.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Data Investment | Secures market access for legacy devices and accelerates new product approvals in Europe. |
| Software & Data Platform Integration | Expands recurring revenue streams and enhances device value beyond hardware. |
| Specialized CTO Device Development | Addresses complex clinical needs and unlocks high-margin procedural segments. |
| Southeast Asia Market Expansion | Capitalizes on modernizing healthcare infrastructure and increasing cardiac care access. |
| Bioresorbable Scaffold R&D | Positions firms for long-term growth in next-generation, absorbable implant technologies. |
Research Approach
US FDA filings, EU MDR guidance documents, and China NMPA publications formed the secondary backbone for this analysis. This was combined with primary interviews involving interventional cardiologists, hospital procurement managers, and medical device engineers. Bottom-up and top-down triangulation validated market size estimates and segment forecasts.
Historical trendline analysis informed the projection of market growth across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user, alongside regional adoption patterns. CAGRs were derived from a multi-factor regression analysis, incorporating disease prevalence and healthcare infrastructure expansion. Key forecast inputs included regulatory approval timelines and reimbursement policy changes.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid economic shifts. Forecasts reflect assumptions documented regarding technological advancements and healthcare spending. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Magnifiers Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Autosamplers Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Breathing Circuits Market
Medical Devices
Global Biliary Stents Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
Catheter Systems Market