
 North America Surgical Visualization Products Market | 2026-2036
North America Surgical Visualization Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surgical Visualization Products Market Analytics
The capital-intensity divergence between integrated platform vendors and component suppliers is unwinding competitive dynamics across the North America Surgical Visualization Products landscape. Medtronic leverages its end-to-end surgical ecosystem to bundle visualization hardware with navigation and robotics, locking in hospital system procurement contracts. Stryker sustains premium positioning through dedicated arthroscopy and spine visualization workflows that integrate with its powered instrument franchises. Karl Storz anchors its presence in rigid endoscopy through German-engineered optical stacks that dominate North American academic medical center purchasing committees.
Surgical visualization products encompass optical and digital systems engineered to transmit magnified, illuminated imagery from internal anatomical cavities or operative fields to displays for real-time surgeon guidance, typically resolving at 1080p to 4K spatial resolution with color fidelity calibrated to tissue differentiation standards. These systems serve the fundamental industrial purpose of reducing surgical invasiveness while improving procedural precision across minimally invasive and open interventions. Endoscopes and imaging systems command the largest installed base, though augmented reality visualization is expanding fastest as overlay capabilities merge preoperative imaging with live video streams. Hospitals remain the dominant end-user segment by procurement volume, while ambulatory surgical centers represent the most contested growth frontier as case volume shifts away from inpatient settings.
FDA 510(k) premarket notification requirements and Health Canada Medical Device Licensing establish the dual regulatory gateway for commercial entry across the United States and Canada, with ISO 13485 quality management certification serving as the operational baseline for manufacturing compliance. The MDR transition in Europe exerts indirect pressure on North American subsidiaries to elevate clinical evidence standards even for legacy product lines. Stakeholders must monitor how CMS reimbursement coding for outpatient surgical procedures reshapes capital equipment purchasing cycles in ambulatory settings.
Market Dynamics
The migration of surgical procedures from inpatient hospitals to ambulatory surgical centers is compressing capital equipment procurement cycles and forcing visualization vendors to reconfigure service delivery models around lower-acuity settings with constrained infrastructure footprints.
Growth Catalysts
- Outpatient Procedure Volume:CMS reimbursement expansion for same-day surgeries is pulling case volume into ambulatory surgical centers across Texas, Florida, and California corridors.
- FDA 510(k) Streamlining:Predicate device pathways for iterative visualization hardware are compressing regulatory review timelines for manufacturers with established quality management systems.
- 4K-8K Resolution Standards:Surgical societies are embedding ultra-high-definition visualization into training accreditation requirements, mandating infrastructure refresh cycles.
Market Restraints
- Optical Component Concentration:German and Japanese precision lens suppliers control critical supply tiers for rigid endoscope manufacturing, exposing North American assemblers to transatlantic shipping volatility.
- Health Canada Licensing Friction:Dual submission requirements for simultaneous US-Canada launches extend commercialization timelines by eight to fourteen months for mid-tier vendors.
- Capital Equipment Substitution:Leasing and managed service models are displacing outright purchase commitments among independent ambulatory surgical centers with constrained balance sheets.
Strategic Opportunities
- Canadian Market Underpenetration:Ontario and Quebec hospital procurement consolidation has lagged US health system centralization, leaving white space for direct-to-facility visualization vendors.
- Augmented Reality Convergence:Overlay of preoperative CT/MRI with live endoscopic feeds is creating new procedure categories in spine and orthopedic navigation.
- Remote Service Channels:Predictive maintenance via cloud-connected visualization hardware is enabling subscription-based revenue streams independent of capital sales cycles.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialized expertise in surgical camera calibration and fiber-optic repair is concentrating among legacy vendor training programs, constraining third-party service market development.
- Legacy System Integration:Hospital information technology departments face mounting complexity bridging proprietary visualization protocols with enterprise imaging archives and electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surgical Visualization Products Market |
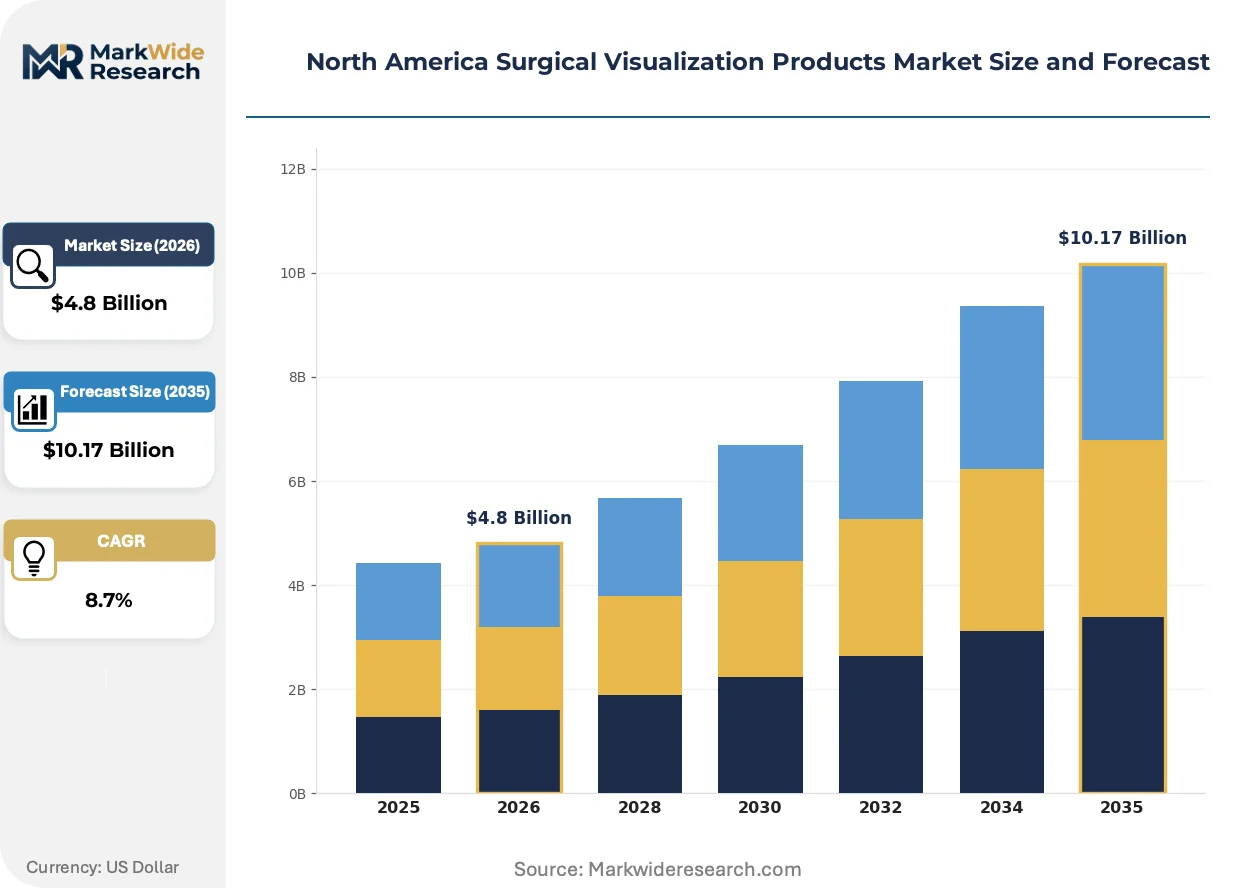
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Surgical Microscopes, Imaging Systems, Video Capture Devices Technology: 3D Visualization, High Definition, Augmented Reality, Digital Imaging End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Orthopedic Surgery, Neurosurgery, General Surgery, Cardiac Surgery |
| Companies Covered | Medtronic, Stryker, Olympus, Karl Storz, Boston Scientific, Smith & Nephew, Conmed, Intuitive Surgical, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surgical Visualization Products Market Evolving Landscape
Sensor miniaturization and wireless transmission protocols are dissolving the physical tether between endoscope and processor, enabling entirely new surgical workflows and challenging decades of established operating room layout conventions.
Chip-on-tip CMOS sensors are miniaturizing distal imaging elements to sub-3mm diameters while maintaining 4K resolution thresholds. Academic medical centers in Boston and Houston are piloting these platforms for pediatric and otolaryngology applications where anatomical access constraints previously mandated fiber-optic bundles. The technology is miniaturizing instrument channel requirements, allowing single-port access devices to carry visualization, suction, and working channels through incisions under 15mm.
Health Canada Medical Device Licensing harmonization discussions with FDA quality system recognition are reducing redundant facility inspections for manufacturers with ISO 13485 certification. Dual-jurisdiction vendors are consolidating submission strategies around FDA 510(k) clearances as predicate foundations for parallel Health Canada applications. Ambulatory surgical center chains with cross-border footprints are the primary beneficiaries, gaining synchronized product availability.
Consolidated procurement through integrated delivery networks is displacing individual hospital purchasing autonomy in visualization capital planning. Multi-hospital systems in the Cleveland Clinic and Mayo Clinic orbits are mandating standardized visualization platforms across affiliated ambulatory surgical centers to compress training costs and service contract complexity. The Upper Midwest and Great Lakes regions exhibit the most advanced centralization, with single-vendor commitments spanning fifty-plus facilities.
North America Surgical Visualization Products Market Segmentation
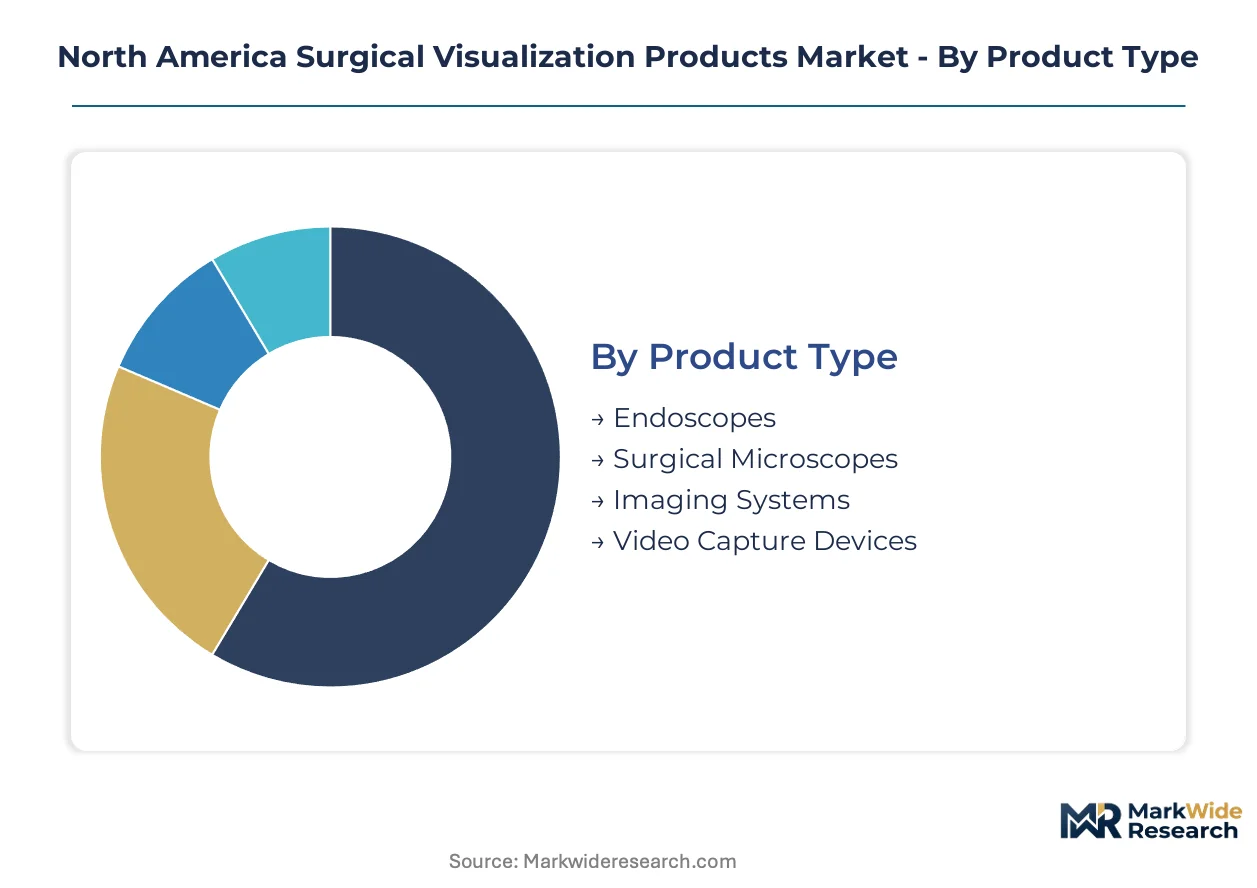
Surgical visualization products fragment across four intersecting dimensions that reshape procurement priorities and regulatory submission strategies. Product type determines capital intensity and service contract structures, while technology tier dictates reimbursement coding and training accreditation requirements.
Product Type:
FDA 510(k) predicate pathways diverge sharply between rigid endoscope line extensions and novel imaging system platforms, compressing timelines for iterative hardware but extending review cycles for breakthrough optical architectures.
- Endoscopes:Rigid and flexible optical systems with distal lens arrays transmit illuminated imagery through fiber-optic bundles or digital sensors. Texas Medical Center procurement clusters concentrate demand for multi-specialty platforms compatible with sterilization protocols across high-volume orthopedic and general surgery workflows.
- Imaging Systems:Camera control units, light sources, and image processors convert optical signals into display-ready video streams at 1080p to 4K resolution. Cleveland Clinic corridor health systems prioritize integrated platforms that bridge proprietary visualization protocols with enterprise PACS archives.
- Surgical Microscopes:Binocular optical trains with motorized positioning enable magnified stereoscopic visualization for microsurgical fields.
- Video Capture Devices:Standalone recording hardware and software modules document procedures for training and quality assurance.
Established volume favors endoscopes; emerging adoption favors imaging systems.
Technology:
Cost tier stratification separates premium visualization platforms from standard-definition legacy installations, with reimbursement differentials widening between academic medical centers and independent ambulatory facilities.
- High Definition:1080p and 4K resolution standards with color calibration to tissue differentiation requirements dominate current installed bases. Surgical societies embed ultra-high-definition thresholds into training accreditation mandates across United States academic programs.
- Augmented Reality:Overlay systems merge preoperative CT and MRI datasets with live endoscopic video streams for navigated intervention. Boston and Houston academic centers pilot these platforms for spine and orthopedic applications where anatomical precision demands real-time image fusion.
- 3D Visualization:Stereoscopic display systems render depth perception for robotic-assisted and laparoscopic procedures.
- Digital Imaging:CMOS and CCD sensor architectures with software-based image enhancement replace analog signal chains.
High definition commands current procurement volume; augmented reality climbs the fastest.
End User:
Customer type determines infrastructure constraints, capital availability, and service delivery model complexity across the North American landscape.
- Hospitals:Inpatient facilities with dedicated biomedical engineering departments manage multi-vendor visualization fleets and long-term service contracts. Integrated delivery networks in the Upper Midwest mandate standardized platforms across fifty-plus affiliated sites to compress training costs.
- Ambulatory Surgical Centers:Outpatient facilities with constrained physical footprints and lean staffing require compact, portable visualization systems with simplified maintenance protocols. CMS reimbursement expansion for same-day surgeries pulls case volume into Texas, Florida, and California corridors.
- Specialty Clinics:Focused practices in otolaryngology, urology, and gastroenterology deploy single-specialty visualization configurations.
- Research Institutions:Academic laboratories and teaching hospitals evaluate pre-commercial visualization technologies for clinical validation.
Hospitals anchor procurement volume; ambulatory surgical centers represent the steepest expansion trajectory.
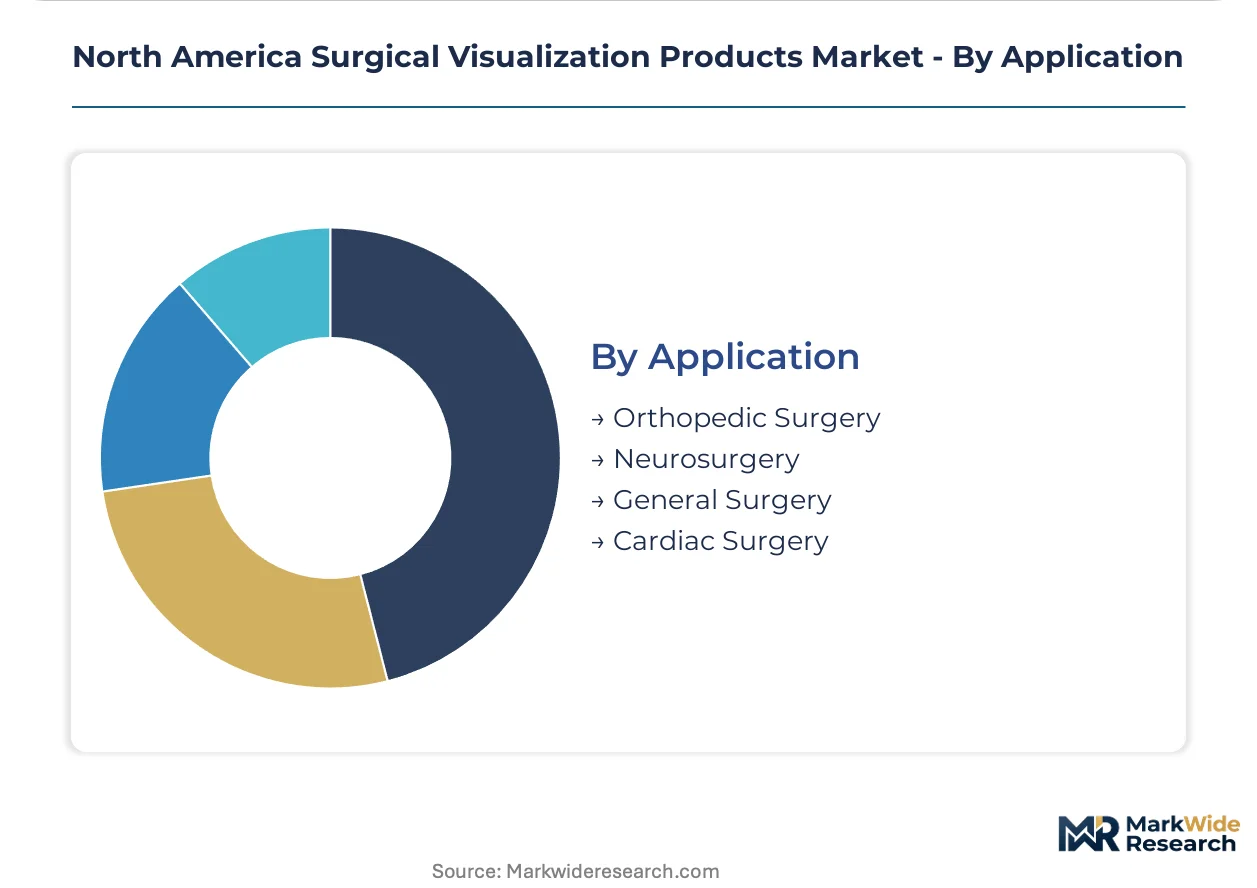
Application:
Procedure-specific visualization requirements drive sensor miniaturization, field-of-view optimization, and integration with navigation and robotics platforms.
- Orthopedic Surgery:Arthroscopy and spine visualization demands wide-angle optics with fluid management integration and powered instrument compatibility. Stryker sustains premium positioning through dedicated arthroscopy workflows that lock in hospital system contracts.
- General Surgery:Laparoscopic and single-port access procedures require flexible endoscopes with instrument channel multiplexing. Chip-on-tip CMOS miniaturization enables sub-3mm distal imaging elements for pediatric and confined-space applications.
- Neurosurgery:Microscope-based visualization with fluorescence guidance supports tumor resection and vascular intervention.
- Cardiac Surgery:Endoscopic and thoracoscopic platforms enable minimally invasive valve and coronary procedures.
Orthopedic surgery concentrates current revenue; general surgery gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States procurement corridors where integrated delivery networks extract volume discounts, while Canadian facilities face extended licensing timelines that compress vendor margins. This asymmetry reshapes cross-border commercialization strategies for visualization hardware manufacturers.
United States
Texas Medical Center in Houston and the Cleveland Clinic corridor drive concentrated demand for multi-specialty visualization platforms compatible with high-volume orthopedic workflows. FDA 510(k) clearance pathways compress regulatory review timelines for established manufacturers with predicate device foundations. Upper Midwest integrated delivery networks now mandate standardized visualization platforms across fifty-plus affiliated ambulatory surgical centers.
Canada
Ontario and Quebec hospital procurement consolidation lags US centralization, leaving white space for direct-to-facility vendors with lean service models. Health Canada Medical Device Licensing requirements extend commercialization timelines by eight to fourteen months compared to parallel US submissions. Toronto and Montreal academic medical centers concentrate demand for rigid endoscopy platforms with German-engineered optical stacks.
Mexico
Border state medical device manufacturing clusters supply optical components to North American assemblers, though domestic visualization procurement remains concentrated in Mexico City private hospital networks. COFEPRIS regulatory alignment with FDA quality system recognition is reducing redundant facility inspections for ISO 13485-certified manufacturers. Guadalajara and Monterrey metropolitan areas exhibit fastest-growing demand for compact visualization systems suited to ambulatory settings.
North America Surgical Visualization Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Surgical Visualization Products landscape. Integrated platform vendors leverage end-to-end surgical ecosystems to bundle visualization hardware with navigation and robotics, locking in multi-year hospital system contracts. Component suppliers and specialized optical manufacturers occupy distinct competitive tiers focused on discrete subsystems. Dominant competitive moves include strategic partnerships bridging hardware and software capabilities, plus portfolio diversification into augmented reality overlay technologies.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson exemplify the integrated-platform archetype that dominates procurement committee decisions at major US academic medical centers. Karl Storz represents the precision-engineering specialist model anchored in German optical manufacturing heritage. Olympus occupies a position bridging component supply and full-system integration for flexible endoscopy applications.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Olympus |
| Karl Storz |
| Boston Scientific |
| Smith & Nephew |
| Conmed |
| Intuitive Surgical |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Japanese precision lens foundries directly shapes component pricing floors for North American surgical visualization assemblers, compressing margins when optical substrate lead times extend and elevating premium tiers when supply tightens. This interdependence forces vendors to calibrate configured-to-order premiums against standard platform pricing while navigating FDA 510(k) predicate pathways that accelerate iterative releases.
Pricing Analysis
Configured-to-order pricing for integrated visualization platforms commands substantial premiums over standard imaging system configurations, with customization depth tied to surgical specialty workflow requirements. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center procurement from ambulatory surgical center leasing arrangements, with ISO 13485 certification tiers further stratifying vendor positioning. Cost compression in mid-tier segments is intensifying because managed service models displace capital purchases among independent facilities. Independent ambulatory surgical centers exhibit highest price sensitivity, while integrated delivery networks leverage volume scale for preferential contract terms.
Supply Chain Analysis
Strategic stockpiling of optical substrates and CMOS sensors dominates inventory strategy among North American assemblers buffering against transatlantic shipping volatility. Manufacturing concentration in Germany, Japan, and South Korea feeds precision lens arrays, chip-on-tip sensors, and fiber-optic bundles into regional assembly operations. Supply chain risk centers on single-source vulnerability for sub-3mm diameter optical substrates critical to pediatric endoscopy platforms. Distribution runs through integrated delivery network procurement committees and GPO contracts that aggregate demand across fifty-plus facility footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical visualization incumbents face substitution pressure from augmented reality overlay platforms merging preoperative imaging with live feeds, requiring defensive positioning around integrated hardware-software ecosystems.
For Market Incumbents: Compound ecosystem lock-in by bundling visualization hardware with navigation and robotics platforms, securing multi-year hospital system contracts against emerging AR-native entrants. Deepen backward integration into CMOS sensor calibration capabilities to reduce dependency on Japanese component suppliers. Prioritize FDA 510(k) predicate accumulation to compress regulatory timelines for iterative releases. For New Entrants and Emerging Players: Lead with lean service models targeting Ontario and Quebec hospital procurement white space, where US-style integrated delivery network centralization remains incomplete. Focus initial commercialization on compact visualization systems purpose-built for ambulatory surgical center infrastructure constraints. Pursue direct-to-facility contracting bypassing GPO intermediaries to capture margin. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-optics specialists with captive German-engineered manufacturing heritage and established academic medical center purchasing committee relationships. Long-term viability hinges on software overlay capabilities and recurring revenue streams from predictive maintenance subscriptions. Watch for Health Canada-FDA quality system recognition harmonization as inflection signal for cross-border commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in multi-year visualization platform standardization across fifty-plus affiliated ambulatory sites. |
| FDA 510(k) Submission Acceleration | Compresses regulatory timelines for iterative chip-on-tip CMOS sensor platforms via predicate stacking. |
| Software Companion Development | Enables augmented reality overlay integration merging preoperative CT/MRI with live endoscopic feeds. |
| Reimbursement Strategy | Aligns visualization capital cycles with CMS outpatient procedure coding expansion for same-day surgeries. |
| CE Marking Pathway | Facilitates European MDR compliance elevation that indirectly strengthens North American clinical evidence standards. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and ambulatory surgical center operations directors anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FDA 510(k) clearance databases, Health Canada Medical Device Licensing records, hospital procurement databases, and CMS reimbursement coding disclosures. Bottom-up installed base modeling and top-down revenue triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across outpatient migration velocity scenarios and regulatory harmonization timelines throughout the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user infrastructure scale, and surgical application workflow complexity. CAGRs derived from procedure volume elasticity to reimbursement expansion and capital equipment replacement cycles tied to 4K-8K resolution accreditation mandates. Forecast inputs incorporated ambulatory surgical center chain expansion patterns and integrated delivery network procurement centralization trajectories.
Underlying assumptions cover FDA 510(k) predicate pathway stability and Health Canada licensing timeline consistency, with deviation risk concentrated in transatlantic optical component supply disruptions and CMS reimbursement coding volatility. Revision becomes warranted when augmented reality overlay adoption crosses threshold penetration in spine and orthopedic navigation procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Spine System Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Chest Drainage System Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Spectacle Lens Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Prescription Lens Market